
 Automotive Driver State Monitoring Systems Market | 2026-2036
Automotive Driver State Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Driver State Monitoring Systems Market Analysis
Software-defined subscription tiers for real-time biometric analytics is rebalancing revenue models away from one-time hardware sales. Robert Bosch GmbH leverages its Tier 1 supplier relationships to embed camera-based monitoring into mainstream vehicle platforms. Seeing Machines anchors the commercial vehicle segment with fleet-focused fatigue detection systems. Smart Eye specializes in multi-camera eye-tracking architectures for luxury OEM programs.
Automotive driver state monitoring systems comprise infrared-enabled cameras, steering angle sensors, and embedded algorithms that classify ocular behavior, head pose, and steering patterns to detect impairment or distraction. Near-infrared illumination permits reliable pupil tracking under variable lighting without driver discomfort. Camera-based technology leads installation volumes due to declining CMOS sensor costs and proven accuracy in drowsiness classification. Sensor-based architectures represent the fastest-growing category as capacitive steering wheel and seat-integrated biometrics gain traction among cost-sensitive OEMs. Electric vehicles constitute a concentrated margin pool because integrated cabin monitoring supports both safety compliance and autonomous driving handover protocols.
The European New Car Assessment Programme mandates driver monitoring for top safety ratings, while NHTSA's proposed FMVSS updates in the United States would require distraction detection in light vehicles. Euro NCAP's timeline accelerates OEM sourcing decisions, and NHTSA rulemaking expands addressable volume for Tier 1 suppliers. Stakeholders must monitor whether China's MIIT incorporates similar monitoring requirements into mandatory GB standards, as this would reshape supplier qualification criteria and testing protocols for export-bound systems.
Market Dynamics
Software-defined revenue architectures are displacing hardware-centric sales models as Tier 1 suppliers bundle real-time biometric analytics into subscription tiers, forcing component manufacturers to restructure pricing frameworks and customer retention strategies around recurring data services rather than one-time camera module transactions.
Growth Catalysts
- Euro NCAP five-star mandate:The European safety rating body's revised protocols now require driver monitoring capability for top scores, compelling OEMs across Germany, France, and Italy to source camera-based attention tracking systems regardless of vehicle price positioning.
- Fleet telematics integration:Commercial vehicle operators in North America are deploying drowsiness detection platforms as standard equipment to reduce liability exposure and insurance premiums across long-haul trucking corridors.
- Capacitive steering wheel sensors:Seat-integrated biometrics and steering angle monitoring are gaining traction among cost-sensitive manufacturers seeking lower bill-of-materials alternatives to multi-camera architectures.
Market Restraints
- CMOS sensor supply concentration:Image sensor fabrication capacity concentrates among Taiwanese and South Korean foundries, exposing Tier 2 module assemblers to allocation risk during semiconductor demand surges.
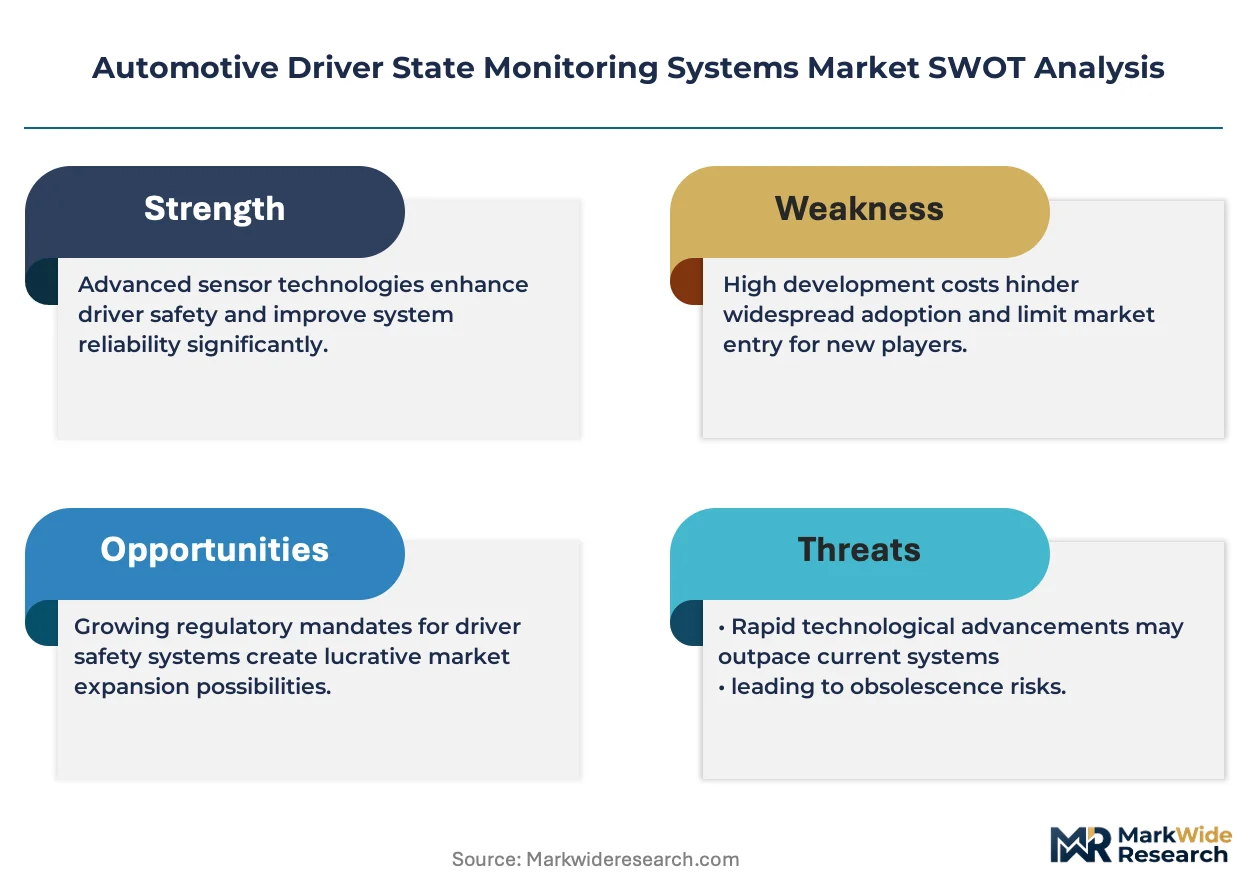
- Infrared illumination thermal constraints:Near-LED arrays face power dissipation limitations in compact cabin installations, restricting continuous monitoring duration in battery-electric vehicles with aggressive energy management protocols.
- Data privacy regulatory friction:GDPR biometric consent requirements in European markets impose deployment complexity that slows fleet-wide rollouts compared to jurisdictions with streamlined driver data frameworks.
Strategic Opportunities
- Autonomous driving handover protocols:Level 3 conditional automation systems require validated driver state assessment before control transitions, creating specification pull from premium OEM programs in Germany and Japan.
- China MIIT standardization pathway:Pending incorporation of driver monitoring into mandatory GB standards would reshape supplier qualification criteria and testing protocols for export-bound systems targeting domestic Chinese production.
- Aftermarket retrofit channels:Independent fleet service providers and commercial vehicle upfitters represent underserved demand for plug-and-play fatigue detection hardware outside factory-installed programs.
Industry Challenges
- Algorithm training data scarcity:Drowsiness classification models require diverse demographic and physiognomic datasets that remain difficult to license across privacy jurisdictions, constraining accuracy validation for Asian and African driver populations.
- Multi-sensor fusion complexity:Integrating camera outputs with steering angle sensors and seat pressure matrices demands specialized embedded software expertise that commands salary premiums and extends development timelines.
- ISO 26262 functional safety certification:Achieving ASIL-B or ASIL-C ratings for safety-critical driver state classifications requires exhaustive failure mode analysis and documentation that stretches qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Driver State Monitoring Systems Market |
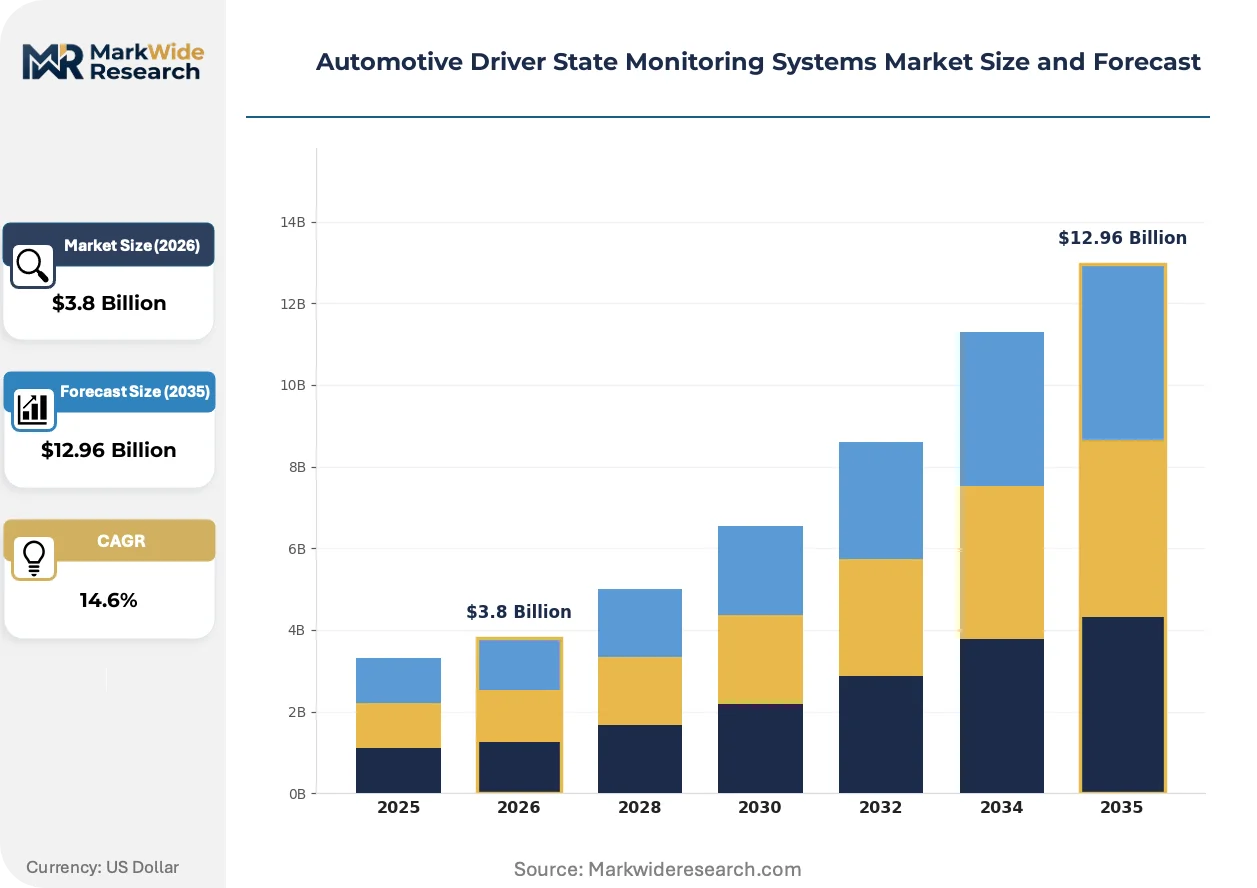
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Sensor-Based, Wearable Devices, Radar End User: OEMs, Aftermarket Providers, Fleet Operators, Insurance Companies Application: Driver Fatigue Detection, Drowsiness Monitoring, Attention Tracking, Safety Alerts Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Cars |
| Companies Covered | Denso Corporation, Aptiv PLC, Valeo SA, Seeing Machines, ZF Friedrichshafen AG, Robert Bosch GmbH, Magna International Inc., Smart Eye, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Driver State Monitoring Systems Market Emerging Trajectories
Near-infrared camera architectures are expanding into mainstream vehicle segments as declining sensor costs and proven drowsiness detection accuracy compress the technology's historical confinement to luxury price tiers, while regulatory mandates accelerate sourcing timelines across multiple geographies.
Multi-camera eye-tracking systems are expanding into mid-range electric vehicle platforms as integrated cabin monitoring supports both Euro NCAP compliance and autonomous driving handover readiness. Chinese OEMs and European mass-market brands are adopting three-camera configurations that track head pose, gaze vector, and eyelid closure simultaneously. This technology expansion is compressing the price premium historically commanded by single-camera solutions and forcing Tier 1 suppliers to defend margin through software differentiation rather than hardware exclusivity.
NHTSA's proposed FMVSS updates in the United States would mandate distraction detection in light vehicles, expanding addressable volume for Tier 1 suppliers beyond voluntary OEM adoption. The rulemaking timeline accelerates sourcing decisions as manufacturers position for compliance rather than competitive differentiation. Commercial vehicle segments face the most immediate impact, as fleet operators pre-position monitoring infrastructure ahead of potential mandate finalization and enforcement phase-in.
Fleet procurement patterns are consolidating around outcome-based safety contracts that tie vendor compensation to measurable incident reduction rather than equipment installation. Long-haul trucking operators in North America and mining vehicle fleets in Australia are leading this shift, replacing capital expenditure models with per-mile or per-operator subscription fees. This behavioral rotation is most visible in Germany, where logistics cooperatives negotiate group purchasing agreements that bundle hardware, software, and insurance premium adjustments into unified service tiers.
Automotive Driver State Monitoring Systems Market Segmentation
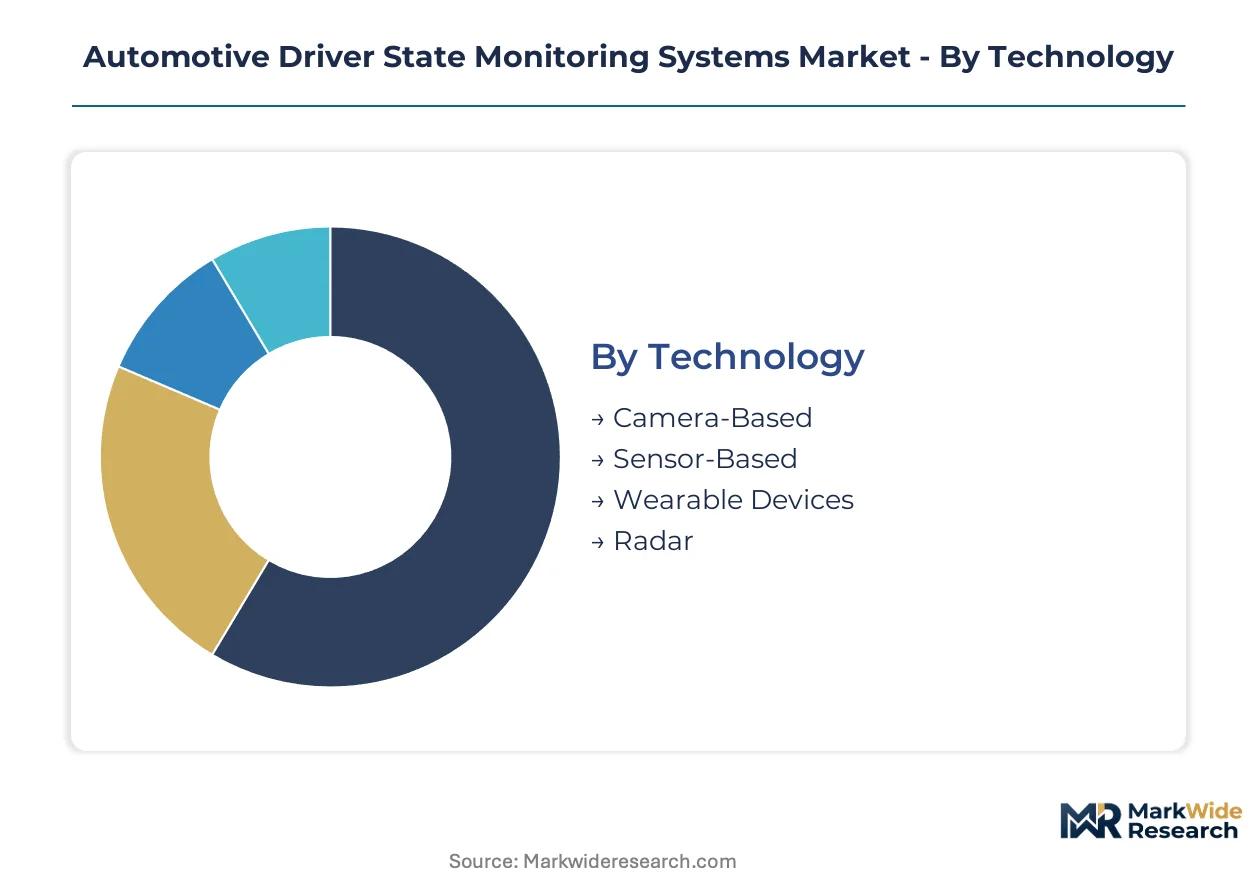
Technology selection in driver state monitoring determines hardware cost, installation complexity, and regulatory compliance pathway. End-user procurement patterns diverge sharply between factory-integrated OEM programs and retrofit fleet deployments. Application focus shapes algorithm training requirements and functional safety certification levels.
Technology:
Cost tier and integration depth separate buyers across technology categories, with premium OEMs prioritizing multi-sensor accuracy while mass-market manufacturers seek streamlined bill-of-materials.
- Camera-Based:Infrared-enabled CMOS architectures with near-LED illumination track pupil dilation, gaze vector, and eyelid closure under variable cabin lighting. Demand concentrates in Germany, where BMW and Mercedes-Benz deploy three-camera configurations as standard equipment to satisfy Euro NCAP five-star mandates.
- Sensor-Based:Capacitive steering wheel sensors and seat-integrated pressure matrices monitor grip patterns and posture shifts without optical components. Fleet operators across long-haul trucking corridors in the United States favor these architectures for lower hardware costs and simplified aftermarket installation.
- Wearable Devices:Smartwatch and headband form factors with photoplethysmography sensors target independent commercial drivers outside factory-installed programs.
- Radar:Millimeter-wave cabin monitoring detects respiration rate and heart rate variability through clothing, emerging in premium electric vehicle programs for contactless vital sign tracking.
Camera-based systems lead volumes today; sensor-based architectures are gaining share fastest among cost-sensitive manufacturers.
End User:
Procurement authority and specification control create distinct commercial dynamics across buyer types.
- OEMs:Vehicle manufacturers integrate driver monitoring into platform architectures during design phase, locking in multi-year supply agreements with Tier 1 suppliers. German luxury brands and Japanese premium OEMs drive specification intensity for Level 3 automation handover readiness.
- Fleet Operators:Commercial vehicle owners deploy drowsiness detection to reduce liability exposure and negotiate insurance premium adjustments. North American long-haul trucking operators and Australian mining vehicle fleets are consolidating procurement around outcome-based safety contracts.
- Aftermarket Providers:Independent service channels retrofit fatigue detection hardware to existing vehicle pools, serving owner-operators and small fleet segments outside factory programs.
- Insurance Companies:Underwriters subsidize monitoring system installation in exchange for telematics data access, creating indirect demand pull through policy incentive structures.
OEMs dominate specification control; fleet operators are expanding procurement most aggressively.
Application:
Functional purpose determines sensor configuration, algorithm complexity, and regulatory alignment requirements.
- Driver Fatigue Detection:Multi-parameter classification models analyze steering micro-corrections, lane deviation patterns, and ocular behavior to identify impairment progression. Euro NCAP protocols mandate this capability for top safety ratings, compelling sourcing across German, French, and Italian vehicle programs.
- Attention Tracking:Gaze vector estimation and head pose monitoring detect distraction from forward road view. NHTSA's proposed FMVSS updates would require this functionality in light vehicles, accelerating manufacturer positioning for compliance.
- Drowsiness Monitoring:PERCLOS algorithms quantify eyelid closure duration as primary fatigue indicator, requiring infrared illumination for reliable nighttime operation.
- Safety Alerts:Haptic steering wheel vibration and dashboard warnings constitute the intervention layer, with escalating alert sequences tied to detected impairment severity.
Fatigue detection leads installed base; attention tracking is climbing the fastest on regulatory mandate timelines.
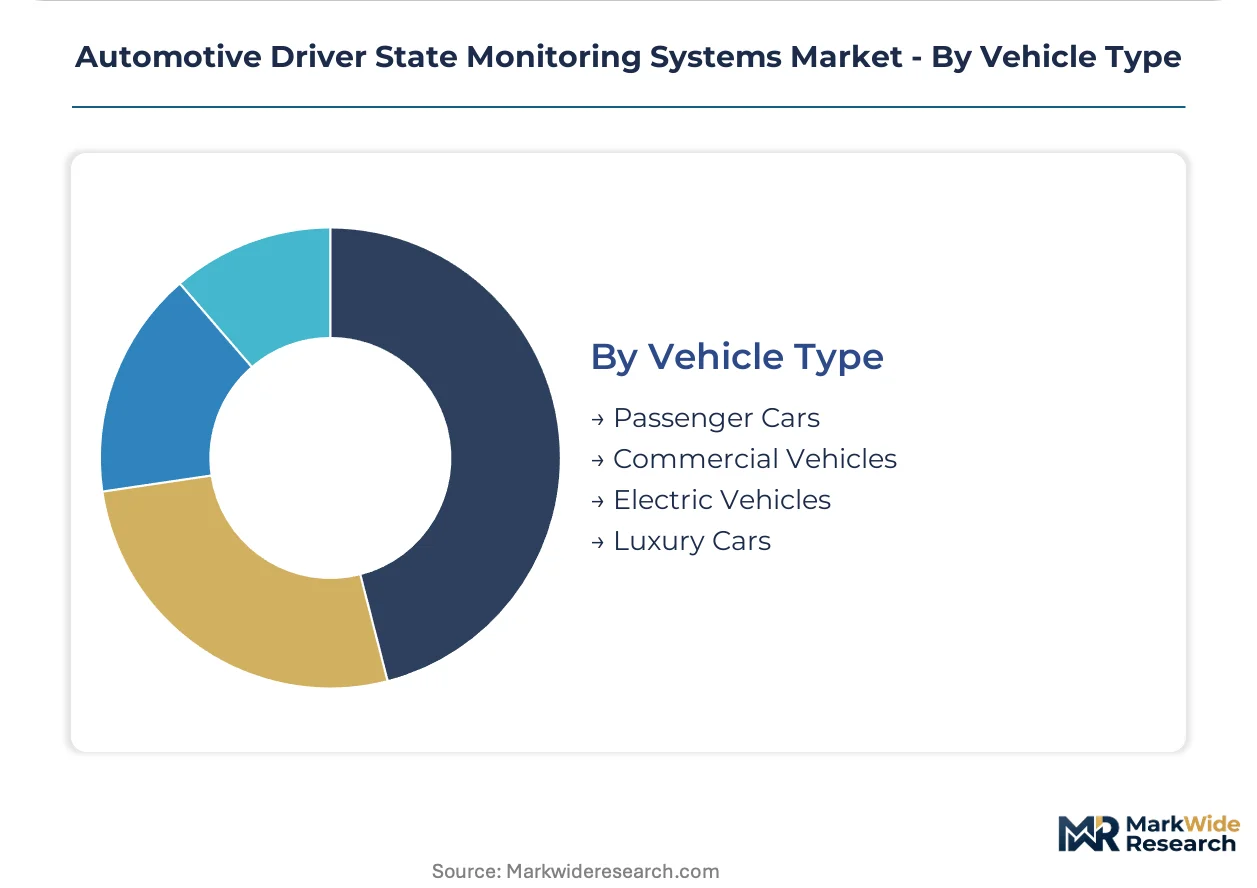
Vehicle Type:
Platform electrification and price positioning segment demand for monitoring system sophistication.
- Electric Vehicles:Integrated cabin monitoring supports both safety compliance and autonomous driving handover protocols, with battery management systems prioritizing energy-efficient sensor operation. Chinese OEMs and European mass-market brands adopt three-camera configurations simultaneously tracking multiple biometric parameters.
- Commercial Vehicles:Heavy-duty trucks and mining equipment deploy robustized camera and sensor architectures for continuous operator monitoring across extended duty cycles. Australian mining fleets and North American trucking corridors lead outcome-based procurement models.
- Passenger Cars:Mass-market vehicle programs balance Euro NCAP compliance against bill-of-materials constraints, favoring streamlined single-camera solutions.
- Luxury Cars:Premium price tiers accommodate multi-sensor fusion with steering angle, seat pressure, and camera inputs for validated driver state assessment.
Electric vehicles anchor margin concentration; commercial vehicles show the steepest expansion trajectory in fleet procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's mandatory Euro NCAP compliance timeline outpaces the United States, where NHTSA rulemaking remains in proposal stage. China sits between these poles, with MIIT standardization pending but domestic OEMs already integrating monitoring hardware.
United States
Long-haul trucking corridors across Texas and California drive fleet procurement of drowsiness detection platforms. NHTSA's proposed FMVSS updates would mandate distraction detection in light vehicles, accelerating Tier 1 supplier positioning. Detroit's automotive engineering cluster anchors OEM integration programs for domestic manufacturers.
Germany
BMW and Mercedes-Benz deploy three-camera attention tracking as standard equipment across all price tiers. Euro NCAP's five-star mandate compels sourcing regardless of vehicle positioning, with KBA type-approval processes validating system compliance. Stuttgart and Munich engineering centers concentrate Tier 1 supplier development activity.
China
Domestic OEMs in the Yangtze River Delta adopt integrated cabin monitoring for both safety compliance and autonomous driving handover protocols. MIIT's pending GB standard incorporation would reshape supplier qualification criteria for export-bound systems. Shanghai and Shenzhen clusters dominate camera module assembly capacity.
Japan
Premium OEMs in the Kanto region specify validated driver state assessment for Level 3 automation readiness. METI's automotive safety guidelines encourage monitoring system deployment ahead of formal mandate timelines. Nagoya's manufacturing corridor concentrates steering sensor production for cost-sensitive architectures.
Australia
Mining vehicle fleets in Western Australia negotiate outcome-based safety contracts tying vendor compensation to incident reduction. TGA medical device frameworks influence biometric sensor validation protocols for commercial deployment. Perth's resources engineering hub anchors fleet-focused fatigue detection implementation.
Automotive Driver State Monitoring Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with Tier 1 automotive suppliers dominating OEM integration while pure-play software vendors capture fleet telematics channels. The structure concentrates around three strategic archetypes: diversified automotive conglomerates with embedded monitoring divisions, specialized computer vision software houses, and steering-system suppliers extending into biometric sensors. Capacity expansion in CMOS sensor fabrication and strategic partnerships between camera module assemblers and algorithm developers constitute the dominant competitive moves reshaping supply relationships.
Within the Tier 1 automotive supplier tier, Robert Bosch GmbH and Continental AG exemplify diversified conglomerates leveraging existing OEM relationships to embed monitoring hardware into mainstream vehicle platforms. Seeing Machines occupies a distinct position among specialized software vendors focused on commercial vehicle fleet applications. These three anchors represent the primary competitive vectors—integrated automotive supply, pure-play software, and fleet-focused specialization—each pursuing different margin structures and customer retention models across factory-installed and aftermarket channels.
| Leading Market Players |
|---|
| Denso Corporation |
| Aptiv PLC |
| Valeo SA |
| Seeing Machines |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Magna International Inc. |
| Smart Eye |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
German luxury OEM procurement concentration anchors subscription-based pricing for real-time biometric analytics, with BMW and Mercedes-Benz multi-year platform agreements compressing hardware margins while elevating software tier revenue. This buyer archetype's specification control forces Tier 1 suppliers to restructure contracts around recurring data services rather than one-time camera module transactions.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for CMOS image sensors, enabling cost-sensitive OEMs to adopt infrared-enabled camera architectures previously confined to premium tiers. Three-tier pricing structure across premium multi-sensor, standard single-camera, and economy sensor-based levels stratifies by Euro NCAP certification grade and autonomous driving handover readiness. Price erosion runs through the economy tier as Chinese module assemblers expand output, while premium tiers defend margins through ISO 26262 ASIL-C validation. Fleet operators exhibit highest price sensitivity, prioritizing per-mile subscription models over capital expenditure.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese OEMs require Tier 1 suppliers to qualify camera module assemblers across Taiwan, South Korea, and China simultaneously. Near-infrared LED arrays, capacitive steering sensors, and embedded AI accelerators constitute critical input dependencies. Single-source vulnerability concentrates in Taiwanese foundry capacity for advanced CMOS fabrication. Distribution runs through direct OEM supply agreements for factory-installed systems, with aftermarket channels serving fleet retrofit demand through independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined revenue architectures enable margin expansion as declining sensor costs shift value capture toward analytics subscriptions and outcome-based fleet contracts.
For Market Incumbents: Extend software differentiation through embedded algorithm IP protection, locking OEM customers into multi-year analytics tiers that resist hardware commoditization. Deepen backward integration into CMOS sensor design to secure allocation priority during semiconductor demand surges. Counter emerging pure-play computer vision vendors by bundling steering sensor fusion capabilities that demand specialized automotive functional safety expertise. For New Entrants and Emerging Players: Fleet telematics platform partnerships offer the most penetrable entry route, bypassing OEM supply qualification barriers that require multi-year validation cycles. Target North American long-haul trucking operators and Australian mining fleets with outcome-based safety contracts that tie vendor compensation to incident reduction metrics. Pursue white-label aftermarket retrofit channels serving owner-operators outside factory-installed programs. For Investors and Strategic Acquirers: Tier 1 automotive conglomerates with embedded monitoring divisions are the most active acquirers in this space, seeking computer vision software capabilities to complement hardware supply relationships. Acquisition target archetypes include specialized PERCLOS algorithm developers and capacitive biometric sensor specialists with ISO 26262 certification progress. Watch NHTSA FMVSS finalization timing as the critical inflection signal for mandate-driven volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | BMW and Mercedes-Benz platform standardization elevates recurring analytics revenue over hardware sales. |
| Multi-Sensor Fusion Partnership | Integration of camera, steering angle, and seat pressure inputs demands specialized embedded software expertise. |
| Geographic Manufacturing Footprint | Shanghai and Shenzhen clusters dominate camera module assembly for Chinese OEM cabin monitoring programs. |
| Charging Infrastructure Partnership | Electric vehicle platform integration links driver state monitoring with battery management energy protocols. |
| Platform Standardization | Euro NCAP five-star mandates compel sourcing across German, French, and Italian vehicle programs regardless of price tier. |
Methodological Framework
Coverage spans Germany, the United States, China, and Japan, with primary inputs from each market cluster. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet telematics operators combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA rulemaking dockets, and Euro NCAP protocol documentation. Bottom-up and top-down triangulation cross-validated segment-level estimates against aggregate market sizing.
Granularity-level modeling deployed technology, end user, application, and vehicle type dimensions at the country level, with propulsion architecture and content per vehicle as automotive-specific refinements. CAGRs derived from logistic adoption curves fitted to regulatory mandate timelines and OEM sourcing decision patterns. Forecast inputs incorporated semiconductor supply allocation scenarios and MIIT standardization pathway probabilities for China.
The model assumes a particular technology adoption path; alternative pathways for capacitive steering wheel sensors displacing camera architectures would alter the outlook. Forecasts reflect assumptions around Euro NCAP enforcement consistency and NHTSA rulemaking finalization. Deviation in China MIIT GB standard incorporation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Airbag Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market