
 North America Very Narrow Aisle Trucks (VNA Truck) Market | 2026-2036
North America Very Narrow Aisle Trucks (VNA Truck) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Very Narrow Aisle Trucks (VNA Truck) Market Outlook
Material handling dealer networks across the United States and Canada are rewriting how VNA trucks reach end users, with independent distributors ceding ground to manufacturer-direct service branches. Hyster-Yale Materials Handling leverages its dual-brand infrastructure to sustain coverage density in the Great Lakes automotive corridor. Crown Equipment Corporation anchors its position through in-house battery and charger production, while Jungheinrich AG competes on European-derived mast technology adapted for North American rack standards.
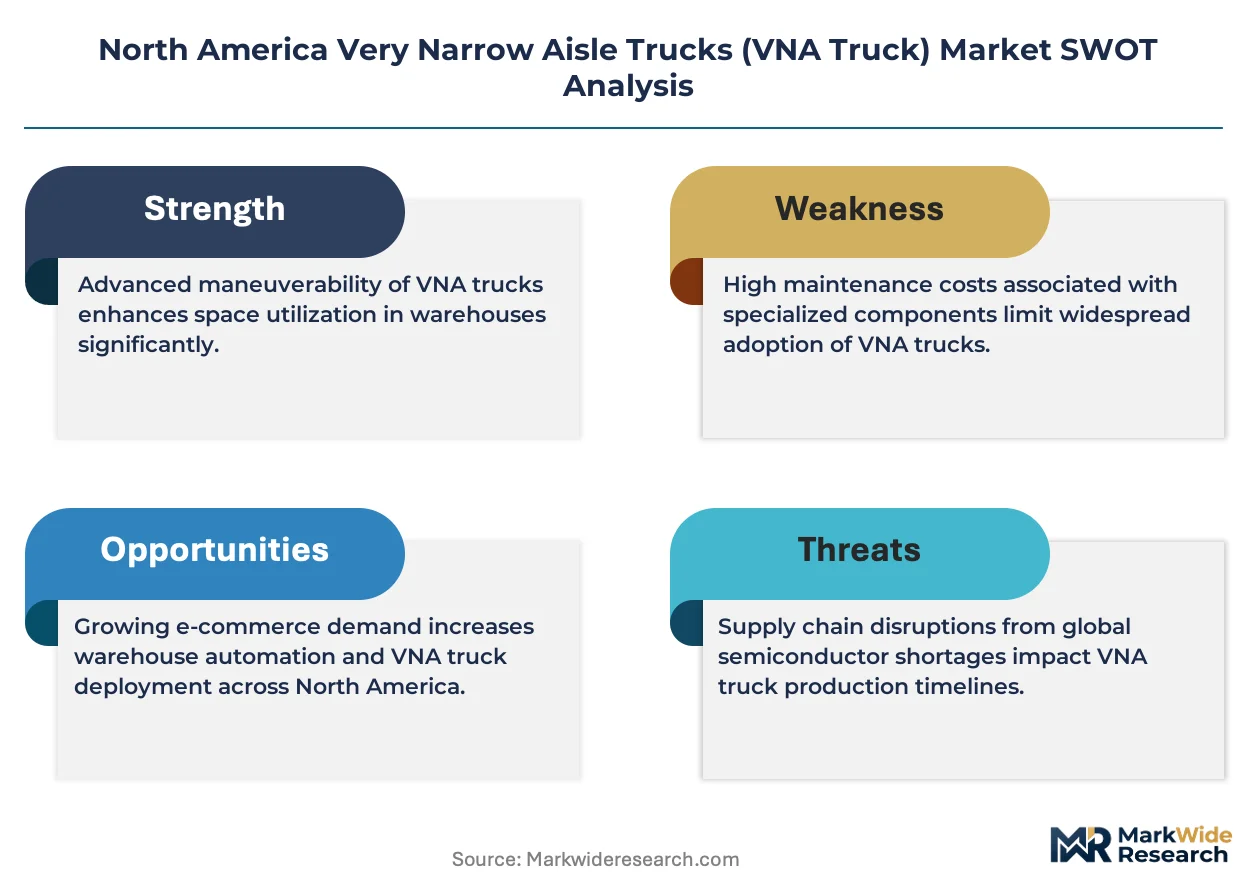
Very Narrow Aisle Trucks are high-lift material handling vehicles engineered to operate in aisles measuring approximately 1.5 to 1.8 meters, utilizing wire or rail guidance systems to achieve pallet storage heights exceeding 12 meters in optimized warehouse configurations. Their primary purpose centers on maximizing cubic storage density while maintaining selectivity in high-turn distribution environments. Man-up VNA configurations dominate margin pools due to their operator elevation capability and throughput advantages in full-case picking operations, while automated technology variants represent the fastest-expanding segment as labor availability tightens across Midwest and Southeast logistics hubs. Electric powertrains sustain the broadest installed base, though hybrid systems are gaining traction in multi-shift cold storage applications where battery swap infrastructure remains limited.
OSHA workplace safety standards and ANSI B56.1 industrial truck requirements govern operator training, stability testing, and load handling protocols for VNA equipment deployed across United States facilities. EPA emissions regulations and California Air Resources Board zero-emission mandates accelerate electric fleet transitions, particularly in Los Basin and Central Valley distribution clusters. Canadian Centre for Occupational Health and Safety guidelines parallel OSHA frameworks while introducing province-specific inspection intervals that shape aftermarket service contract structures. Stakeholders must monitor how emerging autonomous navigation standards intersect with existing operator-certification frameworks to determine technology roadmaps and capital allocation priorities.
Market Dynamics
OSHA operator certification requirements and ANSI B56.1 stability testing protocols are compressing equipment replacement cycles across United States distribution networks, while Canadian provincial inspection intervals reshape aftermarket service economics.
Growth Catalysts
- EPA zero-emission mandates:California Air Resources Board regulations accelerate electric VNA fleet conversions in Los Angeles Basin fulfillment clusters, eliminating internal combustion options from procurement shortlists.
- E-commerce fulfillment densification:Third-party logistics operators in Chicago and Toronto corridors deploy man-up configurations to achieve storage heights exceeding 12 meters in existing footprint constraints.
- Automated guidance systems:Wire and rail guidance technology reduces aisle width requirements to 1.5 meters, enabling cubic density gains in Midwest automotive parts distribution hubs.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing capacity concentrates in Asian supply chains, exposing North American fleet operators to input cost volatility and extended lead times.
- Operator training infrastructure gaps:OSHA-mandated certification programs face instructor scarcity in secondary logistics markets, delaying equipment commissioning timelines.
- High-voltage system complexity:Electric VNA maintenance requires specialized technician competencies that concentrate in manufacturer-direct service branches, limiting independent dealer participation.
Strategic Opportunities
- Canadian cold storage expansion:Province-specific CCOHS inspection protocols create captive aftermarket revenue streams for service providers establishing presence in Alberta and British Columbia protein export corridors.
- Autonomous navigation convergence:Integration of LiDAR-based obstacle detection with existing wire guidance infrastructure enables semi-automated operation in labor-constrained Southeast distribution hubs.
- IRA clean energy incentives:Federal tax credits for zero-emission material handling equipment reduce total cost of ownership calculations for electric VNA procurement in multi-shift operations.
Industry Challenges
- Certification timeline compression:OSHA operator re-certification intervals and emerging autonomous navigation standards create overlapping compliance burdens for training departments.
- Legacy warehouse management system integration:Automated VNA variants require API connectivity with existing WMS platforms, generating implementation friction in brownfield facilities.
- Multi-shift battery swap infrastructure:Cold storage applications in limited grid capacity locations face charging station deployment constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Very Narrow Aisle Trucks (VNA Truck) Market |
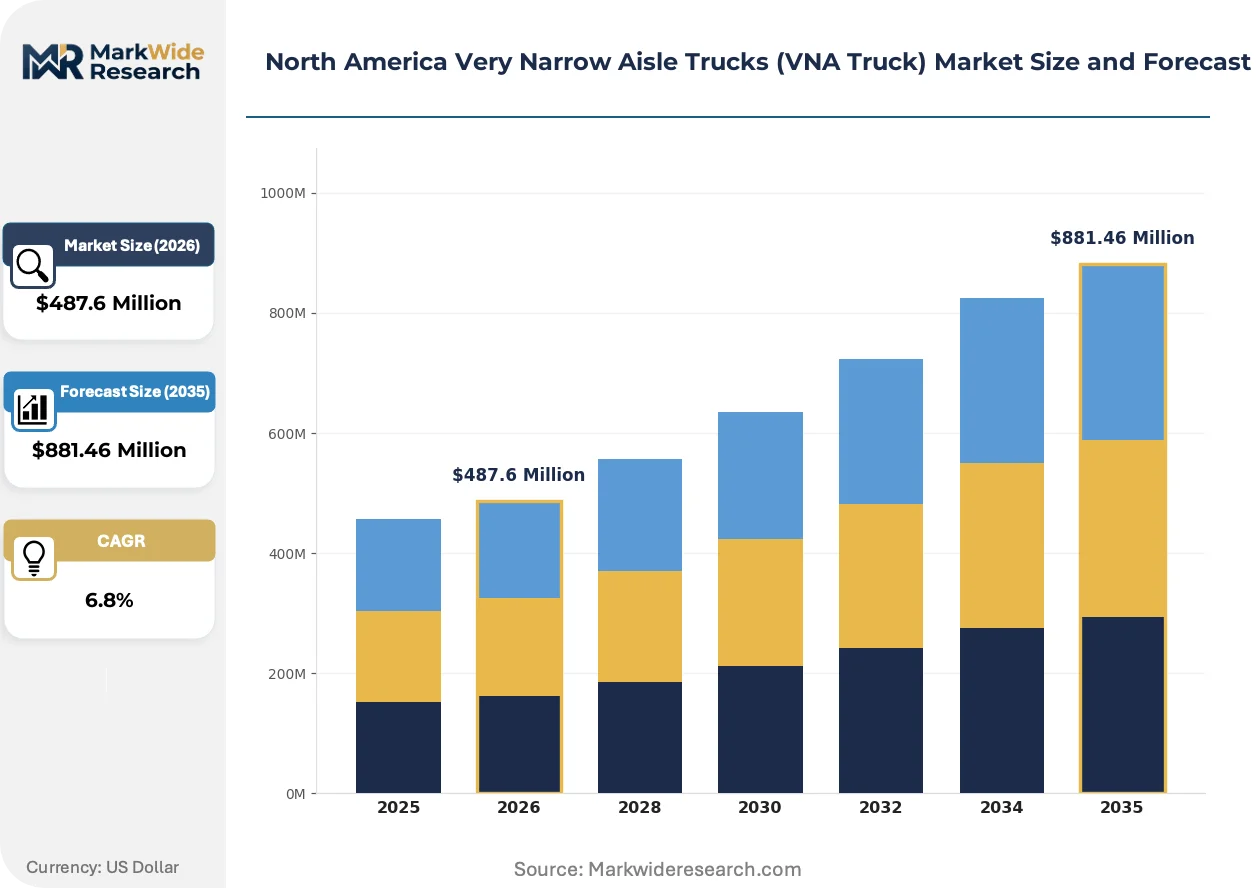
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided VNA, Man-up VNA, Stackers, Reach Trucks End User: Warehousing, Retail, Manufacturing, Logistics Technology: Electric, Diesel, Hybrid, Automated Capacity: 1000 kg, 1200 kg, 1500 kg, 1800 kg |
| Companies Covered | Hyster-Yale Materials Handling, Inc., Jungheinrich AG, Crown Equipment Corporation, Linde Material Handling, Mitsubishi Logisnext Co., Ltd., Raymond Corporation, Yale Materials Handling Corporation, STILL GmbH, Toyota Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Very Narrow Aisle Trucks (VNA Truck) Market Strategic Shifts
Electrification architectures and autonomous navigation capabilities are restructuring competitive advantage in VNA equipment procurement, while regulatory compliance automation reshapes operator training economics.
Lithium-ion battery chemistry is migrating from lead-acid dominance in high-duty-cycle applications. Cold storage operators in Central Valley distribution clusters adopt fast-charging configurations to eliminate battery swap downtime. This transition is compressing total cost of ownership calculations and shifting procurement criteria toward energy density specifications.
OSHA is revising powered industrial truck operator training standards to address semi-automated control interfaces. The proposed framework mandates simulator-based certification for man-up configurations exceeding 9-meter lift heights. Midwest automotive parts distributors are pre-emptively upgrading training infrastructure to avoid commissioning delays.
Fleet procurement is consolidating around lifecycle service contracts that bundle equipment, maintenance, and operator training. Third-party logistics operators in the Great Lakes corridor are displacing transactional purchase models with subscription-based arrangements. This restructuring concentrates vendor relationships and reduces independent dealer participation in aftermarket revenue pools.
North America Very Narrow Aisle Trucks (VNA Truck) Market Segmentation
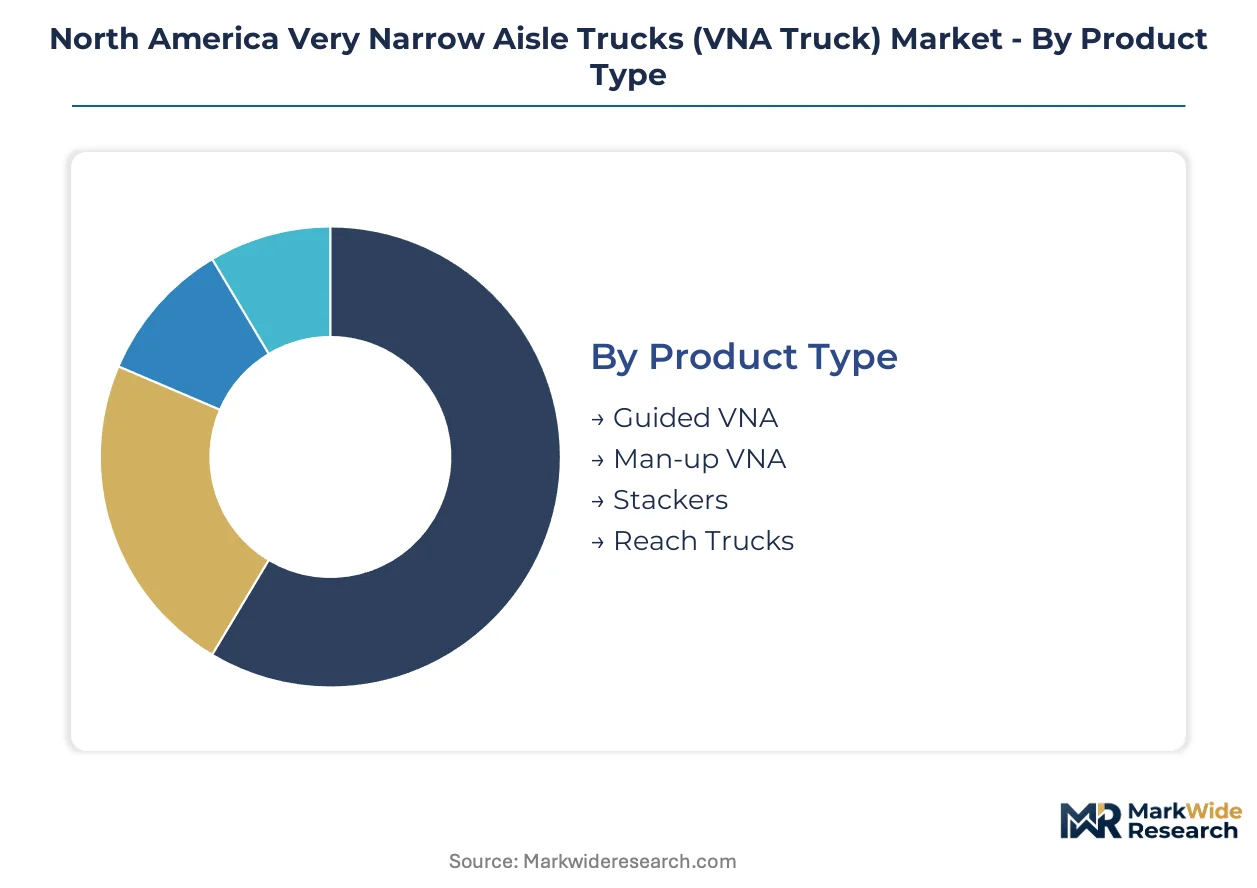
Segmentation in North American VNA truck procurement reflects divergent operational economics across warehouse configurations, powertrain technologies, and load specifications. Procurement committees weight aisle dimensions, vertical reach requirements, and shift intensity differently based on facility vintage and SKU velocity profiles.
Product Type:
Cost tier differentiation separates premium man-up configurations from entry-level guided systems, with margin concentration tracking operator elevation capabilities and throughput velocity.
- Man-up VNA:Operator elevation platforms enable full-case picking at heights exceeding 12 meters. Chicago and Toronto third-party logistics corridors deploy these for e-commerce fulfillment densification where SKU selectivity drives labor efficiency.
- Guided VNA:Wire or rail guidance systems constrain aisle widths to 1.5 meters for cubic density maximization. Midwest automotive parts distributors favor these for existing footprint constraints where rack retrofit costs dominate capital planning.
- Stackers:Pedestrian-operated units serve low-velocity SKUs in secondary markets with limited vertical reach requirements. Independent dealers in secondary logistics corridors maintain inventory for transactional replacement cycles.
- Reach Trucks:Counterbalanced mast designs bridge conventional forklift and true VNA applications. Cold storage operators in Central Valley distribution clusters specify these for intermediate lift heights in limited aisle retrofit scenarios.
Man-up VNA commands the established base. The steepest expansion runs through Guided VNA as existing facilities pursue densification without greenfield construction.
End User:
Application intensity varies sharply across facility types, with throughput velocity and SKU granularity dictating equipment specification and fleet sizing.
- Warehousing:High-velocity distribution centers in Los Angeles Basin and Great Lakes corridors drive fleet standardization around electric man-up configurations. EPA zero-emission mandates accelerate procurement timelines in California fulfillment clusters.
- Logistics:Third-party operators consolidate vendor relationships through lifecycle service contracts bundling equipment, maintenance, and OSHA-mandated operator training. Subscription-based arrangements displace transactional purchase models.
- Manufacturing:Automotive parts distribution in the Midwest manufacturing belt sustains replacement cycles tied to production schedules. ANSI B56.1 stability testing protocols compress equipment refresh intervals.
- Retail:Back-of-store operations in urban locations prioritize compact footprints over vertical reach. Limited grid capacity constrains charging infrastructure deployment in older facilities.
Warehousing anchors procurement volume. Logistics represents the fastest-expanding trajectory as third-party operators consolidate multi-site fleet standardization.
Technology:
Powertrain selection tracks duty cycle intensity, shift structure, and regional emissions compliance, with infrastructure availability constraining transition timelines.
- Electric:Lithium-ion chemistry migrates from lead-acid dominance in high-duty-cycle applications. Fast-charging configurations eliminate battery swap downtime for Central Valley cold storage operators.
- Automated:LiDAR-based obstacle detection converges with existing wire guidance infrastructure for semi-automated operation. Labor-constrained Southeast distribution hubs pilot these configurations.
- Hybrid:Dual-power systems gain traction in multi-shift cold storage where battery swap infrastructure remains limited. Alberta and British Columbia protein export corridors evaluate these for extended runtime requirements.
- Diesel:Internal combustion options retreat to remote facilities beyond grid capacity. CARB regulations eliminate these from California procurement shortlists entirely.
Electric sustains the broadest installed base. Automated variants gain share fastest as OSHA revises training standards for semi-automated control interfaces.
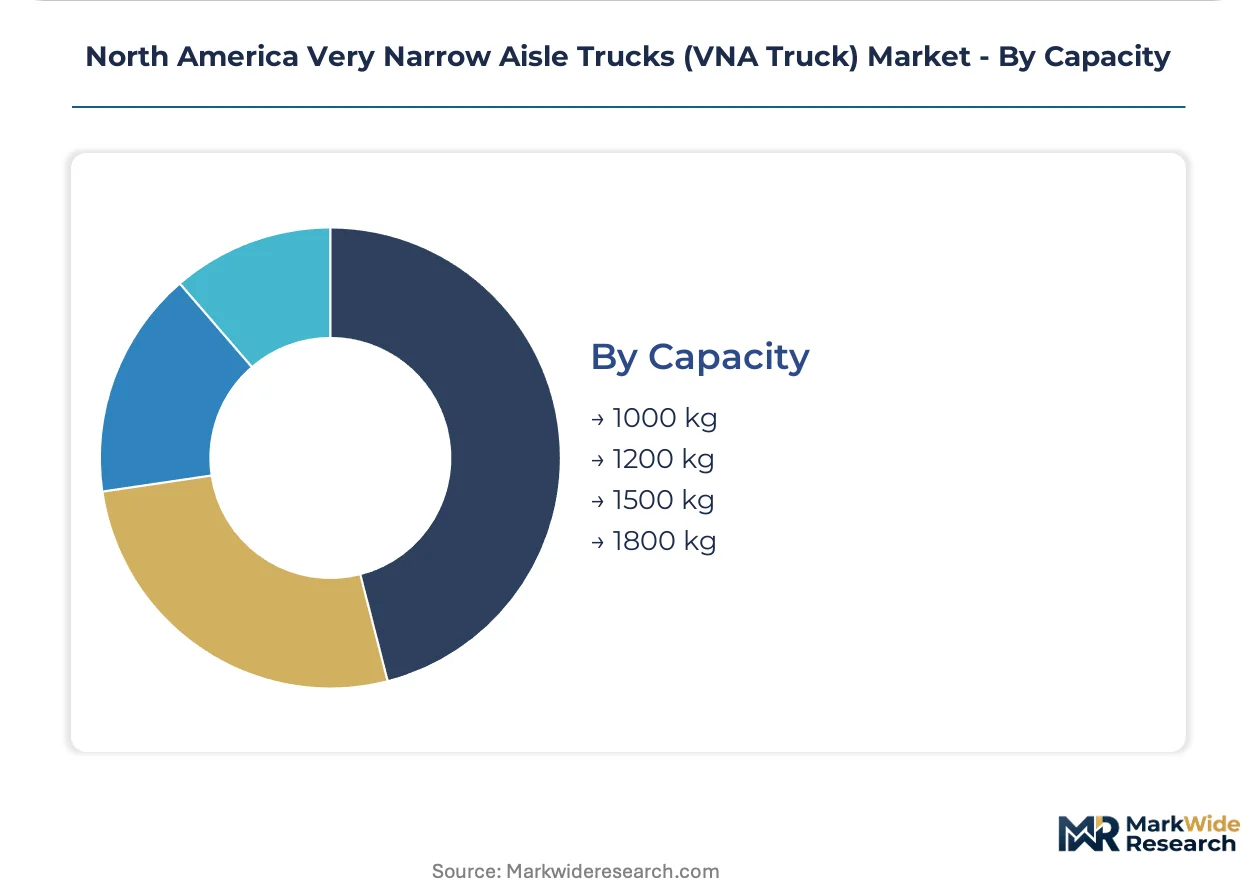
Capacity:
Load specification concentrates around standardized pallet weights, with incremental capacity tiers commanding premium pricing for specialized applications.
- 1500 kg:Standard pallet configurations dominate general merchandise distribution. Great Lakes automotive parts hubs specify these for component handling across mixed-SKU operations.
- 1200 kg:European-derived specifications serve import-dependent facilities with ISO pallet standards. Toronto corridor distribution centers standardize here for cross-border operational consistency.
- 1800 kg:Heavy-duty variants address beverage and dense consumer goods applications. Limited production runs concentrate manufacturer-direct service relationships.
- 1000 kg:Lightweight configurations serve electronics and pharmaceutical verticals with fragile handling requirements. Cleanroom specifications add certification complexity.
1500 kg anchors fleet standardization. 1800 kg climbs fastest as beverage distributors densify storage configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA clean energy incentives and EPA zero-emission mandates are accelerating electric VNA fleet conversions across North American distribution corridors. Provincial inspection protocols in Canada and OSHA certification requirements in the United States reshape service contract economics. Sub-regional demand concentrates in automotive manufacturing belts and e-commerce fulfillment clusters.
United States
Midwest automotive parts distributors in Michigan and Ohio sustain replacement cycles tied to production schedules. OSHA operator certification requirements compress equipment refresh intervals as ANSI B56.1 stability testing protocols tighten. Chicago corridor third-party logistics operators deploy man-up configurations to achieve storage heights exceeding 12 meters in existing footprint constraints.
Canada
Alberta and British Columbia protein export corridors drive cold storage expansion with extended runtime requirements. CCOHS guidelines parallel OSHA frameworks while introducing province-specific inspection intervals that shape aftermarket service contract structures. Toronto distribution centers standardize on European-derived specifications for cross-border operational consistency.
Mexico
Nuevo León and Baja California manufacturing hubs attract automotive supplier investment requiring dense storage configurations. Mexican labor regulations influence operator training infrastructure development near maquiladora zones. Mexico City metro distribution networks evaluate guided VNA systems for footprint-constrained facilities.
North America Very Narrow Aisle Trucks (VNA Truck) Market Competitive Environment
On the supply side, the industry is consolidating around manufacturer-direct service branches that displace independent distributor networks. Equipment producers compete through lifecycle service contracts bundling maintenance, training, and energy infrastructure. Three archetypes dominate: integrated battery-charger producers, European-derived mast technology specialists, and dual-brand infrastructure operators. Competitive moves concentrate on geographic coverage density in the Great Lakes corridor and captive aftermarket revenue capture through inspection-protocol compliance services.
Among North American infrastructure operators, Hyster-Yale Materials Handling, Inc. and Crown Equipment Corporation exemplify the dual-brand and vertical-integration archetypes respectively. Jungheinrich AG occupies a position representing European-derived technology adaptation for regional rack standards. These three anchors demonstrate how service branch density and in-house component production reshape procurement relationships across Midwest automotive and Southeast logistics hubs.
| Leading Market Players |
|---|
| Hyster-Yale Materials Handling, Inc. |
| Jungheinrich AG |
| Crown Equipment Corporation |
| Linde Material Handling |
| Mitsubishi Logisnext Co., Ltd. |
| Raymond Corporation |
| Yale Materials Handling Corporation |
| STILL GmbH |
| Toyota Industries Corporation |
| Others |
Value Chain & Pricing Dynamics
Great Lakes freight corridors transmit lithium-ion battery cost volatility from Asian cathode processing hubs into North American VNA truck pricing tiers, compressing margins for independent distributors while amplifying manufacturer-direct pricing power through captive service contracts.
Pricing Analysis
Certification level creates the primary spread across VNA procurement tiers, with OSHA-compliant man-up configurations commanding substantial premiums over basic guided systems. Subscription-based lifecycle contracts now dominate in third-party logistics corridors, displacing per-unit transactional models. Price differentiation rests on energy density specifications and fast-charging capability in multi-shift operations. Cold storage operators in Central Valley distribution clusters exhibit highest price sensitivity due to grid capacity constraints, while automotive parts distributors in the Midwest manufacturing belt prioritize throughput velocity over unit cost.
Supply Chain Analysis
Contract manufacturing for VNA battery systems concentrates in South Korea and Japan, with cathode material processing anchored in Chinese supply chains. Lithium carbonate and nickel sulfate feedstock dependencies expose North American fleet operators to commodity price swings. Single-source vulnerability in semiconductor components for automated guidance systems generates procurement risk. Distribution runs through manufacturer-direct service branches that displace independent dealer networks across the Great Lakes and Los Angeles Basin corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician competencies for high-voltage electric VNA maintenance remain scarce across secondary logistics markets, creating structural bottlenecks that concentrate vendor relationships and reshape competitive entry economics.
For Market Incumbents: Insulate aftermarket revenue pools by deepening in-house battery and charger production capabilities, while accelerating service branch density in Alberta and British Columbia protein export corridors where CCOHS inspection protocols generate captive contract opportunities. Counter emerging autonomous navigation entrants through pre-emptive simulator-based training infrastructure investments that align with OSHA's revised certification frameworks. For New Entrants and Emerging Players: Build out presence in Canadian cold storage expansion corridors where province-specific inspection intervals create service contract white space underserved by incumbent branch networks. Target secondary logistics markets in the Southeast where operator training infrastructure gaps delay equipment commissioning and open procurement windows for agile service providers. Lead with fast-charging lithium-ion configurations that eliminate battery swap downtime in multi-shift operations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized material handling divisions lacking vertical integration into energy storage systems. Long-term viability favors manufacturers with captive battery chemistry capabilities and dense service branch footprints across Midwest automotive belts. Monitor OSHA autonomous navigation standard finalization as inflection signal for technology roadmap consolidation and capital allocation shifts toward semi-automated platform development.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Crown Equipment's in-house battery manufacturing insulates margin pools from Asian cathode cost volatility. |
| Service Branch Density Expansion | Hyster-Yale's dual-brand infrastructure captures captive aftermarket revenue across Great Lakes automotive corridors. |
| Simulator-Based Training Infrastructure Deployment | Midwest automotive distributors pre-empt OSHA certification delays through advanced operator simulation platforms. |
| LiDAR-Based Autonomous Navigation Development | Wire guidance convergence enables semi-automated operation in labor-constrained Southeast distribution hubs. |
| Lifecycle Service Contract Standardization | Third-party logistics operators displace transactional purchases with subscription arrangements bundling equipment and maintenance. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with warehouse operations directors, fleet procurement managers, OSHA training coordinators, aftermarket service heads, and lithium-ion battery supply specialists informed demand-side dynamics. Secondary sources include EPA enforcement databases, CARB zero-emission mandate documentation, CCOHS provincial inspection protocols, ANSI B56.1 stability testing standards, and SEC 10-K disclosures from publicly traded material handling equipment manufacturers. Bottom-up equipment shipment data triangulates against top-down warehouse construction permits and e-commerce fulfillment center expansion announcements.
Calibration against historical replacement cycle patterns and regulatory compliance timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (man-up, guided, stacker, reach truck), powertrain technology (electric, automated, hybrid, diesel), end-use application (warehousing, logistics, manufacturing, retail), and load capacity tier. CAGRs derive from installed base turnover rates, densification investment cycles, and emissions mandate phase-in schedules. Forecast inputs incorporate lithium-ion battery cost curves, grid capacity expansion timelines in Central Valley distribution clusters, and OSHA autonomous navigation standard development progress.
Stress conditions across cathode material supply disruptions, lithium price volatility, and operator training infrastructure bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption curves. Quarterly review of OSHA rulemaking dockets, CARB enforcement actions, and battery chemistry patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Brake Pad Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Spring Market
Automotive Parts
North America Automotive AHSS Market