
 Europe Industrial Roller Chain Drive Market | 2026-2036
Europe Industrial Roller Chain Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Roller Chain Drive Market Analytics
The EU Green Deal is realigning industrial procurement priorities across European manufacturing, pushing buyers toward energy-efficient mechanical power transmission. IWIS Antriebssysteme GmbH & Company KG leverages its R&D intensity in precision-engineered roller chains for high-torque applications. Renold plc anchors its position through backward integration into heat treatment and specialized steel processing. Wippermann Jr. GmbH differentiates via advanced corrosion-resistant coatings that extend service intervals in harsh environments.
Industrial roller chain drives transmit mechanical power between rotating shafts through interlinked metal plates, pins, bushings, and rollers, typically constructed from hardened carbon steel or stainless steel with pitch tolerances measured in millimeters. These systems serve as critical power transmission components in conveyor systems, lifting equipment, and precision manufacturing lines where synchronous motion transfer withstands heavy loads and contamination. Heavy-duty chains capture substantial margin pools in mining and construction applications where failure costs exceed premium pricing. Stainless steel chains represent the fastest-growing product category, driven by food processing and pharmaceutical hygiene mandates. Material handling applications sustain the largest volume base, though automotive OEM demand shows the steepest trajectory as electric vehicle assembly lines require customized pitch configurations.
REACH and the EU F-Gas Regulation shape material composition and lubricant chemistry requirements, while CE marking governs mechanical safety conformity for power transmission equipment sold across member states. ECHA restrictions on hexavalent chromium and certain PFAS compounds are forcing reformulation of surface treatments and chain lubricants. The EU AI Act introduces emerging compliance dimensions for smart monitoring systems integrated into predictive maintenance chains. Stakeholders must monitor evolving substance restrictions and energy efficiency labeling proposals that could reshape competitive positioning in European industrial supply chains.
Market Dynamics
EU Green Deal mandates are compressing replacement cycles and redirecting capital toward lower-friction drive architectures, forcing manufacturers to requalify materials and lubricant chemistries ahead of ECHA substance restrictions.
Growth Catalysts
- REACH substance restrictions:ECHA limitations on hexavalent chromium and PFAS compounds are accelerating R&D investment in alternative surface treatments and bio-based lubricants that extend chain service intervals.
- Automotive OEM conveyor modernization:Electric vehicle assembly lines in Germany and Poland require customized pitch configurations and synchronous motion systems for battery module handling.
- Food processing hygiene mandates:Stainless steel chains with corrosion-resistant coatings are displacing carbon steel in pharmaceutical and dairy processing equipment across Italy and the Netherlands.
Market Restraints
- Specialized steel supply concentration:Premium-grade alloy steel for heat treatment remains concentrated among a narrow supplier base in Central Europe, creating input cost volatility and qualification delays.
- CE marking conformity costs:Mechanical safety certification requirements for power transmission equipment impose fixed compliance burdens that disproportionately affect smaller replacement-part distributors.
- Belt and direct-drive substitution:Poly-V belt systems and integrated direct-drive motors are capturing light-duty material handling applications where load precision requirements permit.
Strategic Opportunities
- Polish industrial corridor expansion:Manufacturing investment in Lower Silesia and the Warsaw region is generating greenfield demand for heavy-duty mining and construction chain systems.
- EU AI Act predictive maintenance integration:Smart monitoring systems embedded in roller chains enable condition-based replacement contracts that shift revenue from product sales to service subscriptions.
- Energy efficiency labeling tailwinds:Proposed EU-wide mechanical power transmission efficiency standards would favor premium low-friction chain designs in public procurement.
Industry Challenges
- Heat treatment skill scarcity:Specialized metallurgical expertise for case hardening and induction heating faces generational attrition across German and Italian manufacturing clusters.
- Legacy system integration friction:Retrofitting predictive maintenance sensors onto existing conveyor architectures requires custom engineering that extends project timelines and erodes margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Roller Chain Drive Market |
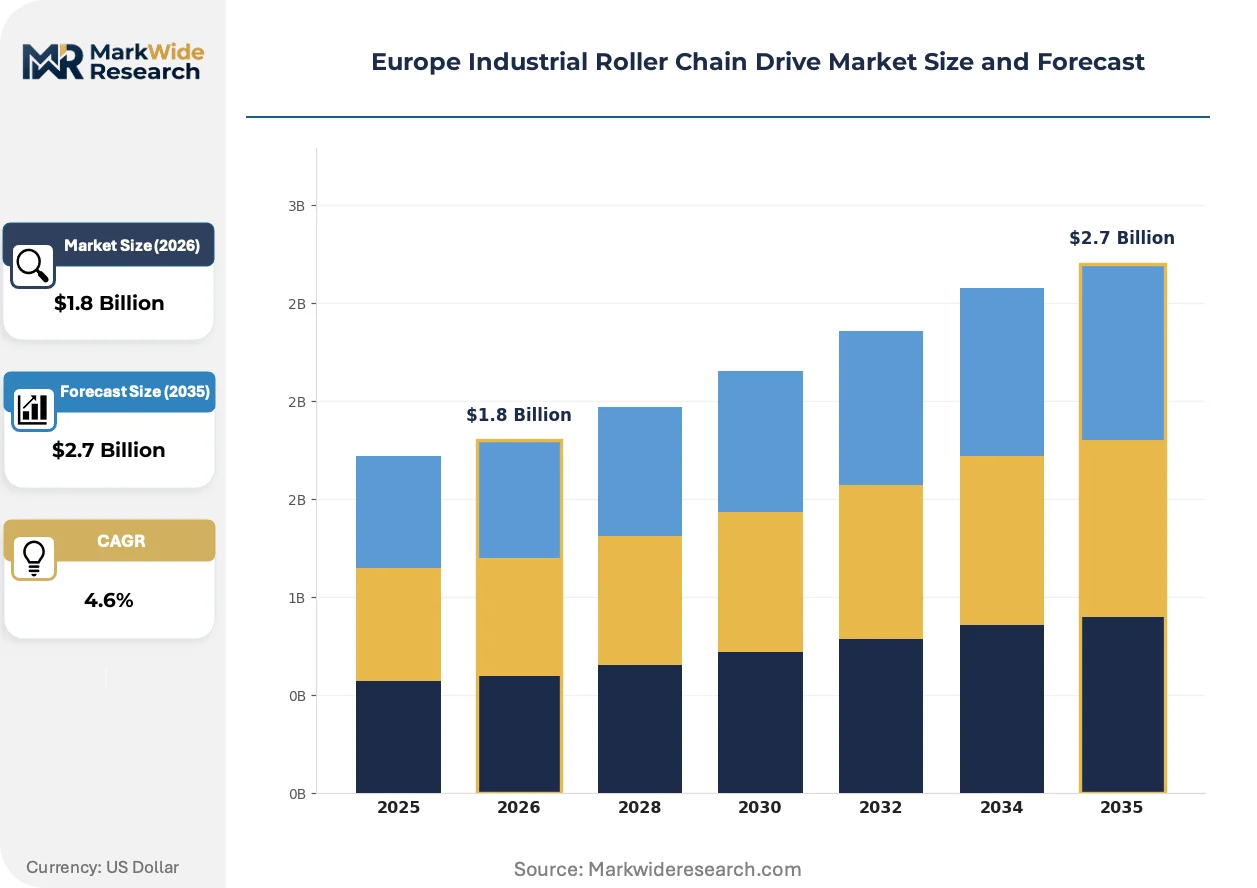
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Roller Chains, Heavy-Duty Chains, Stainless Steel Chains, Coated Chains Application: Manufacturing, Material Handling, Construction, Food Processing End User: Automotive OEMs, Aerospace Manufacturers, Mining Operations, Packaging Industry Size: Small Size, Medium Size, Large Size, Custom Size |
| Companies Covered | Fordertechnik Kenizler GmbH, Wippermann Jr. GmbH, IWIS Antriebssysteme GmbH & Company KG, Z.M.C. Italia, Ditton Driving Chain Factory, Renold plc, Kettentechnik Roeder GmbH, Topbas Group, Regal Rexnord Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Roller Chain Drive Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to redefine surface treatment protocols and lubricant formulations across European industrial supply chains.
Self-lubricating polymer-impregnated bushings are expanding into food processing and pharmaceutical cleanroom environments where external lubricant contamination poses compliance risk. Dutch and Danish dairy equipment OEMs are specifying these chains for washdown-intensive bottling lines. The technology is expanding into applications previously reserved for stainless steel, compressing the premium pricing spread between corrosion-resistant and standard carbon steel product tiers.
EU F-Gas Regulation phase-down schedules are forcing reformulation of fluorinated lubricants used in high-temperature oven and kiln conveyor systems. Industrial bakeries and ceramic manufacturers in Germany and Italy face accelerated transition timelines to PFAS-free synthetic alternatives. Heat-resistant chain segments serving these end-uses are responding with expanded bio-based and polyalphaolefin lubricant compatibility testing.
Consolidated automotive OEMs are unbundling after-sales service contracts from original equipment purchases, creating direct procurement relationships with tier-two chain suppliers. Tier-one conveyor integrators in Stuttgart and Turin are losing exclusivity on replacement parts for lines they installed. This pattern is most visible in battery assembly operations where OEMs seek to standardize chain specifications across multiple equipment vendors.
Europe Industrial Roller Chain Drive Market Segmentation
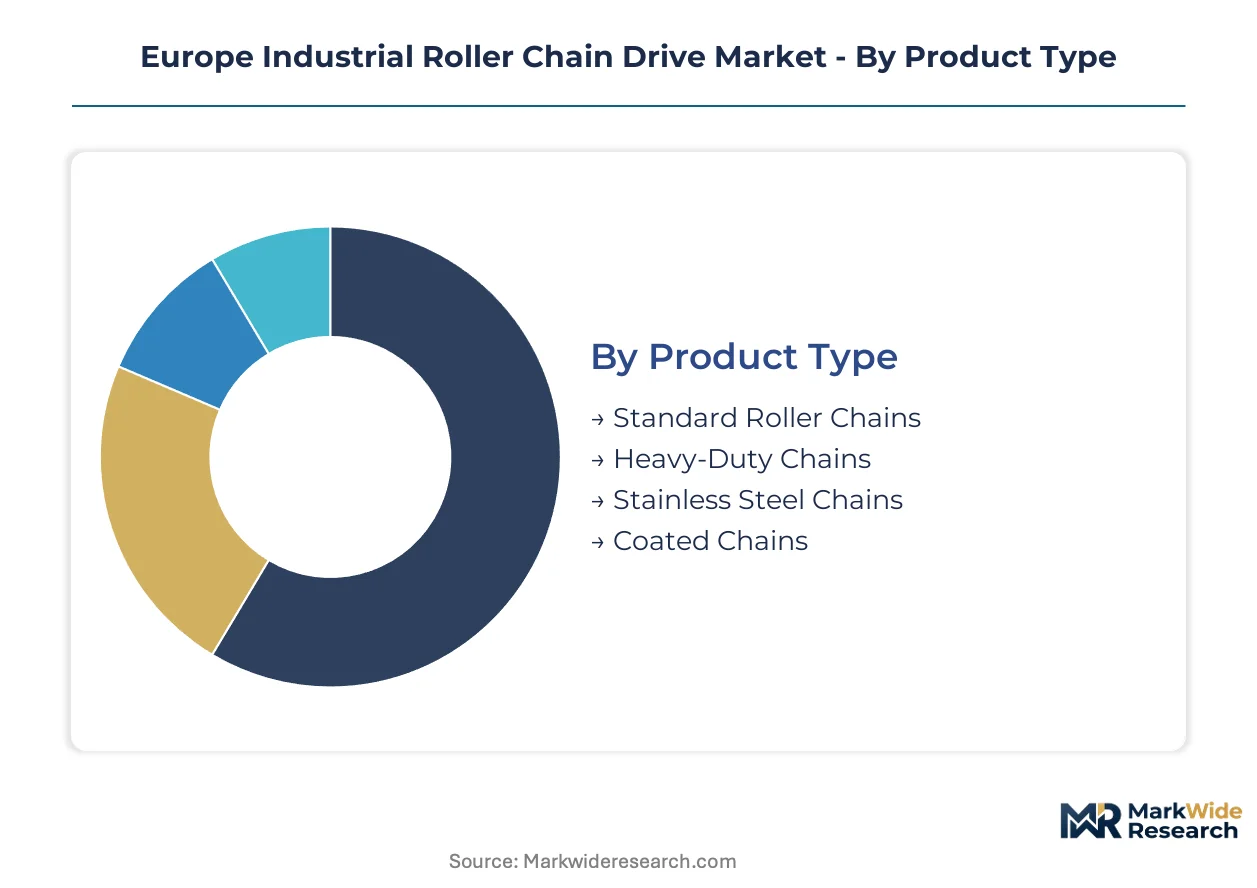
Segmentation in the Europe Industrial Roller Chain Drive Market reveals how procurement priorities diverge across load requirements, environmental exposure, and regulatory compliance. Buyers select chain architectures based on torque demands, corrosion risk, and integration complexity rather than unit cost alone.
Product Type:
Buyers weight total cost of ownership against failure risk, with premium alloys commanding position where downtime costs dwarf initial spend.
- Heavy-Duty Chains:Constructed from case-hardened alloy steel with reinforced link plates and oversized rollers for shock load absorption. Mining operations in Poland and construction equipment OEMs in Germany concentrate procurement here, driven by failure-cost economics that justify 40-60% price premiums over standard equivalents.
- Stainless Steel Chains:Manufactured from AISI 304 or 316-grade steel with passivated surfaces eliminating external corrosion protection needs. Food processing lines across Italy and the Netherlands specify these for washdown-intensive dairy and pharmaceutical environments where EFSA hygiene mandates prohibit lubricant contamination.
- Standard Roller Chains:Carbon steel construction with through-hardened pins serves general manufacturing and light conveyor applications where moderate loads and controlled environments limit corrosion exposure.
- Coated Chains:Zinc-flake or polymer surface treatments extend carbon steel service life in humid or chemically aggressive settings without full stainless steel cost.
Volume sits with Standard Roller Chains; growth tilts toward Stainless Steel Chains.
Application:
Application selection tracks facility automation intensity and regulatory exposure, with hygiene-critical processes commanding specialized architectures.
- Material Handling:Warehouse automation and distribution centers across Germany and the Netherlands drive demand for precision-pitch chains in automated storage and retrieval systems. E-commerce fulfillment expansion in the Dutch Randstad corridor accelerates replacement cycles.
- Manufacturing:Assembly line synchronization and machine tool power transmission dominate volume, with automotive OEMs in Stuttgart and Turin specifying customized pitch configurations for battery module handling equipment.
- Food Processing:Stainless steel and self-lubricating variants serve dairy, meat, and beverage processing where REACH-compliant lubricants and washdown resistance are non-negotiable.
- Construction:Mobile cranes, concrete pumps, and earthmoving equipment in Poland and Romania require heavy-duty chains with extended pin bearings for abrasive environments.
Manufacturing commands current volume; Material Handling shows the steepest expansion trajectory.
End User:
End-user procurement patterns reflect unbundling of after-sales service contracts and direct sourcing standardization across multi-vendor equipment fleets.
- Automotive OEMs:Electric vehicle assembly lines in Germany and Poland require synchronous motion systems with customized pitch for battery module transport. OEMs increasingly bypass tier-one integrators to standardize specifications across equipment vendors.
- Mining Operations:Underground and surface extraction equipment in Lower Silesia and the Polish industrial corridor demands heavy-duty chains with 50,000+ hour service life ratings under abrasive load conditions.
- Aerospace Manufacturers:Precision heat treatment and tight pitch tolerance chains serve airframe assembly jigs and component handling systems in Toulouse and Hamburg manufacturing clusters.
- Packaging Industry:High-speed bottling and carton forming lines in Italy and France specify corrosion-resistant chains for washdown environments with minimal maintenance access.
Automotive OEMs anchor premium pricing; Mining Operations generate replacement volume at extended intervals.
Size:
Size selection correlates with power transmission requirements and retrofit compatibility constraints in legacy equipment.
- Medium Size:ANSI 40-60 and ISO 08B-12B pitch ranges serve the broadest cross-section of industrial machinery, from machine tools to packaging equipment, capturing volume concentration in general manufacturing.
- Custom Size:Non-standard pitch and width configurations address OEM-specific integration requirements, particularly in battery assembly lines where space constraints and motion precision demands defy catalog standards.
- Small Size:Compact pitch chains for light conveyors, instrumentation, and precision positioning equipment in electronics and pharmaceutical cleanroom applications.
- Large Size:Heavy pitch constructions for mining draglines, cement kilns, and steel mill continuous casters where single-chain failure halts entire production trains.
Medium Size dominates installed base; Custom Size expands fastest as OEMs unbundle specification control from integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Turin automotive corridor drives the steepest demand trajectory for precision roller chain systems across European manufacturing.
Germany
Electric vehicle assembly lines in Stuttgart and Wolfsburg require customized pitch configurations for battery module transport systems. ECHA restrictions on hexavalent chromium are accelerating R&D investment in alternative surface treatments among Bavarian heat treatment specialists. The Ruhr industrial cluster sustains heavy replacement demand from steel mill continuous casters and cement kiln operations.
Poland
Lower Silesia mining operations and Warsaw-region manufacturing investment generate greenfield demand for heavy-duty chains with extended service life ratings. EU Green Deal procurement mandates are redirecting capital toward energy-efficient drive architectures in Polish industrial corridors. The Katowice mining basin concentrates abrasive-environment chain consumption at 50,000+ hour replacement intervals.
Italy
Food processing hygiene mandates from EFSA are displacing carbon steel with stainless steel chains across Emilia-Romagna dairy equipment lines. Turin-based automotive OEMs increasingly bypass tier-one integrators to standardize chain specifications across battery assembly vendors. The Veneto packaging machinery cluster drives corrosion-resistant chain demand for washdown-intensive bottling operations.
Netherlands
Randstad distribution center automation accelerates replacement cycles for precision-pitch chains in automated storage systems. REACH-compliant lubricant requirements are reshaping procurement specifications for Rotterdam port material handling equipment. Dutch dairy OEMs specify self-lubricating polymer-impregnated bushings for contamination-sensitive cleanroom environments.
France
Aerospace manufacturers in Toulouse demand tight pitch tolerance chains for airframe assembly jigs and component handling systems. CE marking conformity costs for mechanical safety certification disproportionately affect smaller replacement-part distributors in Lyon industrial zones. The Hauts-de-France automotive supplier base is modernizing conveyor architectures to align with EU F-Gas Regulation phase-down schedules.
Europe Industrial Roller Chain Drive Market Competitive Landscape
Premium-margin players sit above commodity-margin players across heat treatment sophistication and metallurgical qualification depth. The vendor base stratifies into three tiers: precision-engineered specialists with captive R&D, integrated heat-treatment operators with backward control over steel processing, and regional fabricators serving replacement-part distribution. Dominant competitive moves include geographic expansion into Polish industrial corridors and portfolio diversification toward stainless steel variants for food processing mandates.
Within the precision-engineered tier, IWIS Antriebssysteme GmbH & Company KG and Wippermann Jr. GmbH exemplify German GmbH-structured specialists with R&D intensity in high-torque applications. Renold plc anchors the integrated-operator archetype through its plc structure and UK-based positioning. Among regional fabricators, Fordertechnik Kenizler GmbH and Kettentechnik Roeder GmbH represent German GmbH-structured entities serving replacement demand. Z.M.C. Italia occupies a position within Italian-based specialists, while Ditton Driving Chain Factory exemplifies Eastern European fabrication capacity. Regal Rexnord Corporation represents US-based multinational presence, and Topbas Group anchors Turkish-origin supply into European distribution channels.
| Leading Market Players |
|---|
| Fordertechnik Kenizler GmbH |
| Wippermann Jr. GmbH |
| IWIS Antriebssysteme GmbH & Company KG |
| Z.M.C. Italia |
| Ditton Driving Chain Factory |
| Renold plc |
| Kettentechnik Roeder GmbH |
| Topbas Group |
| Regal Rexnord Corporation |
| Others |
Value Network & Pricing Analysis
Backward integration into specialized heat treatment anchors supply position and pricing power for European roller chain manufacturers facing ECHA substance restrictions and alloy steel qualification delays. Captive metallurgical capabilities insulate integrated operators from input cost volatility while justifying 40-60% premiums over regional fabricators serving replacement-part distribution.
Pricing Analysis
Failure-cost economics anchor value-based pricing for heavy-duty chains serving Polish mining operations and German construction equipment OEMs. Three-tier pricing structure across premium, standard, and economy levels separates precision-engineered specialists with captive R&D from integrated heat-treatment operators and regional fabricators. Cost compression in standard carbon steel tiers is intensifying because belt and direct-drive substitution captures light-duty material handling applications. Automotive OEMs show lowest price sensitivity as downtime costs in battery assembly lines dwarf premium chain spend, while smaller replacement-part distributors face disproportionate CE marking conformity burdens.
Supply Chain Analysis
EU Green Deal local-content mandates and procurement realignment toward energy-efficient drive architectures are reshaping sourcing patterns across member states. Premium-grade alloy steel for case hardening draws from concentrated supplier bases in Germany, Italy, and Poland, creating qualification bottlenecks for alternative surface treatments. Supply chain risk centers on single-source vulnerability for specialized induction heating equipment and heat-resistant lubricant formulations facing F-Gas Regulation phase-down. Distribution runs through tier-one conveyor integrators in Stuttgart and Turin, though automotive OEM unbundling of after-sales contracts is shifting volume toward direct tier-two relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgical expertise scarcity props pricing across German and Italian manufacturing clusters, constraining capacity expansion and reinforcing incumbent positioning. Heat treatment skill attrition limits supply elasticity even as EU Green Deal mandates accelerate replacement cycle compression.
For Market Incumbents: Deploy predictive maintenance sensor integration to shift revenue from transactional product sales toward condition-based service subscriptions. Deepen captive R&D in bio-based lubricant compatibility and low-friction chain architectures ahead of ECHA PFAS restrictions. Defend against belt and direct-drive substitution by emphasizing synchronous motion precision in battery assembly applications where load tolerance defies alternative technologies. For New Entrants and Emerging Players: Digital aftermarket platforms for replacement-part distribution offer the lowest barrier to established relationships in fragmented regional fabricator networks. Target Polish industrial corridor greenfield demand in Lower Silesia mining and Warsaw-region manufacturing investment where incumbent presence remains thinner. Lead with stainless steel variants for food processing hygiene mandates in Italy and the Netherlands, bypassing heavy-duty qualification requirements that demand metallurgical heritage. For Investors and Strategic Acquirers: Exit pathways concentrate in precision-engineered specialists with captive heat treatment and established automotive OEM direct relationships. Long-term viability favors operators with backward integration into specialized steel processing and qualification depth for REACH-compliant surface treatments. Watch for EU-wide mechanical power transmission efficiency labeling proposals as inflection signal favoring premium low-friction designs in public procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive metallurgical capabilities insulate margins from alloy steel supply volatility and ECHA-driven reformulation costs. |
| Predictive Maintenance Sensor Integration | Embedded smart monitoring enables condition-based replacement contracts shifting revenue to recurring service streams. |
| Stainless Steel Portfolio Expansion | Food processing hygiene mandates from EFSA displace carbon steel in Italian dairy and Dutch pharmaceutical equipment lines. |
| Polish Industrial Corridor Expansion | Greenfield manufacturing investment in Lower Silesia and Warsaw region generates demand for heavy-duty mining chains. |
| Bio-Based Lubricant Compatibility R&D | F-Gas Regulation phase-down forces reformulation of fluorinated lubricants for German industrial bakery and ceramic kiln conveyors. |
Research Methodology
Document review covered EU regulatory filings from ECHA and EFSA, complemented by interviews with maintenance directors at German automotive OEMs, plant engineers in Polish mining operations, procurement leads at Italian food processing equipment manufacturers, and aftermarket service heads at Netherlands distribution center operators. Secondary validation drew from REACH substance restriction databases, CE marking conformity assessment records, customs data on alloy steel imports, and SEC filings from listed power transmission equipment suppliers. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, and end-user segmentation.
Historical shipment data cross-referenced against expert panel input on replacement cycle compression and EU Green Deal procurement mandate adoption shaped the analytical framework across the analysis window. Segmentation dimensions modeled include chain construction material, load duty tier, environmental exposure rating, and integration complexity level. CAGRs derived from regression analysis of disclosed capital expenditure patterns in conveyor modernization and electric vehicle assembly line investment. Industry-specific forecast inputs incorporated ECHA substance restriction timelines and proposed EU mechanical power transmission efficiency labeling trajectories.
The model holds under stable regulatory enforcement of REACH and F-Gas provisions; deviation in ECHA restriction acceleration or EU AI Act predictive maintenance compliance mandates would shift replacement cycle assumptions. Forecasts reflect documented assumptions on automotive OEM unbundling patterns and heat treatment skill availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Grease Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
North America Ceramic Ball Bearings Market