
 Passenger Car Motor Oil Market | 2026-2036
Passenger Car Motor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Car Motor Oil Market Intelligence
Synthetic base oil technology is narrowing the performance gap between mineral-derived and laboratory-engineered formulations, forcing reformulation across the entire product pyramid. Shell plc leverages its integrated gas-to-liquids platform to sustain supply security for high-purity Group III+ bases. ExxonMobil anchors its position through proprietary metallocene polyalphaolefin capacity in Asia and North America. BP plc competes by extending its Castrol brand into OEM co-development agreements for electric vehicle thermal management fluids.
Passenger car motor oil comprises refined petroleum or synthetic base stocks blended with detergent, dispersant, anti-wear, and viscosity modifier additives, formulated to lubricate internal combustion engines operating across temperature extremes from cold-start cranking to sustained highway thermal loads. The product type dimension shows synthetic grades capturing margin pools as OEM drain intervals extend past fifteen thousand kilometers, while conventional segments retain volume dominance in emerging aftermarket channels where price sensitivity governs purchase decisions. Viscosity grade stratification reveals 0W-20 and 5W-30 specifications displacing 10W-40 in new vehicle parc alignment, concentrating formulation R&D investment in low-high-temperature shear stability.
The US EPA governs fuel economy credits tied to SAE J300-compliant low-viscosity oils, while California's Air Resources Board imposes additional volatility limits that shape regional product portfolios. Europe's REACH framework and ACEA sequences restrict certain additive chemistries, redirecting formulation investment toward boron-free and sulfur-reduced packages. Stakeholders must monitor OEM electrification roadmaps and thermal fluid specifications, as battery electric vehicle penetration redefines whether passenger car motor oil demand tracks powertrain population or fragments into niche classic-vehicle and hybrid internal-combustion residual segments.
Market Dynamics
OEM drain interval extensions past fifteen thousand kilometers are compressing aftermarket volume elasticity, forcing reformulation investment toward low-viscosity synthetic grades that command premium positioning while unit sales stagnate.
Growth Catalysts
- Fleet scheduled maintenance programs:Commercial operators in Germany and the United States are expanding predictive service intervals to control total cost of ownership, creating contracted volume pipelines for synthetic formulations.
- REACH compliance frameworks:Europe's additive chemistry restrictions are redirecting R&D expenditure toward boron-free and sulfur-reduced packages, accelerating next-generation lubricant development.
- SAE J300 low-viscosity specifications:The US EPA's fuel economy credit mechanism tied to compliant oils is pulling OEM fill requirements toward 0W-20 and 5W-30 grades.
Market Restraints
- Group II/III base oil supply concentration:Asian refiners dominate high-purity base stock output, creating geographic vulnerability for blenders lacking captive supply.
- Electric vehicle powertrain substitution:Battery electric vehicle penetration in passenger segments threatens to fragment motor oil demand into residual internal-combustion niches.
- California Air Resources Board volatility limits:State-level NOx precursor restrictions impose formulation constraints that fragment regional product portfolios and inflate compliance costs.
Strategic Opportunities
- India's aftermarket channel expansion:Price-sensitive emerging market segments retain conventional oil dominance, offering volume scale for economy-tier positioning.
- OEM co-development agreements:Thermal management fluid specifications for hybrid powertrains create white space for lubricant-coolant convergence products.
- EU F-Gas Regulation tailwinds:Lower-emission lubricant chemistry mandates reward early movers with preferred supplier status in European automotive manufacturing corridors.
Industry Challenges
- ACEA sequence certification timelines:Extended testing protocols for European OEM approvals delay product launches and compress commercialization windows.
- Additive package integration complexity:Reformulation for reduced sulfur and boron content requires recalibration of detergent-dispersant balance without sacrificing wear protection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Car Motor Oil Market |
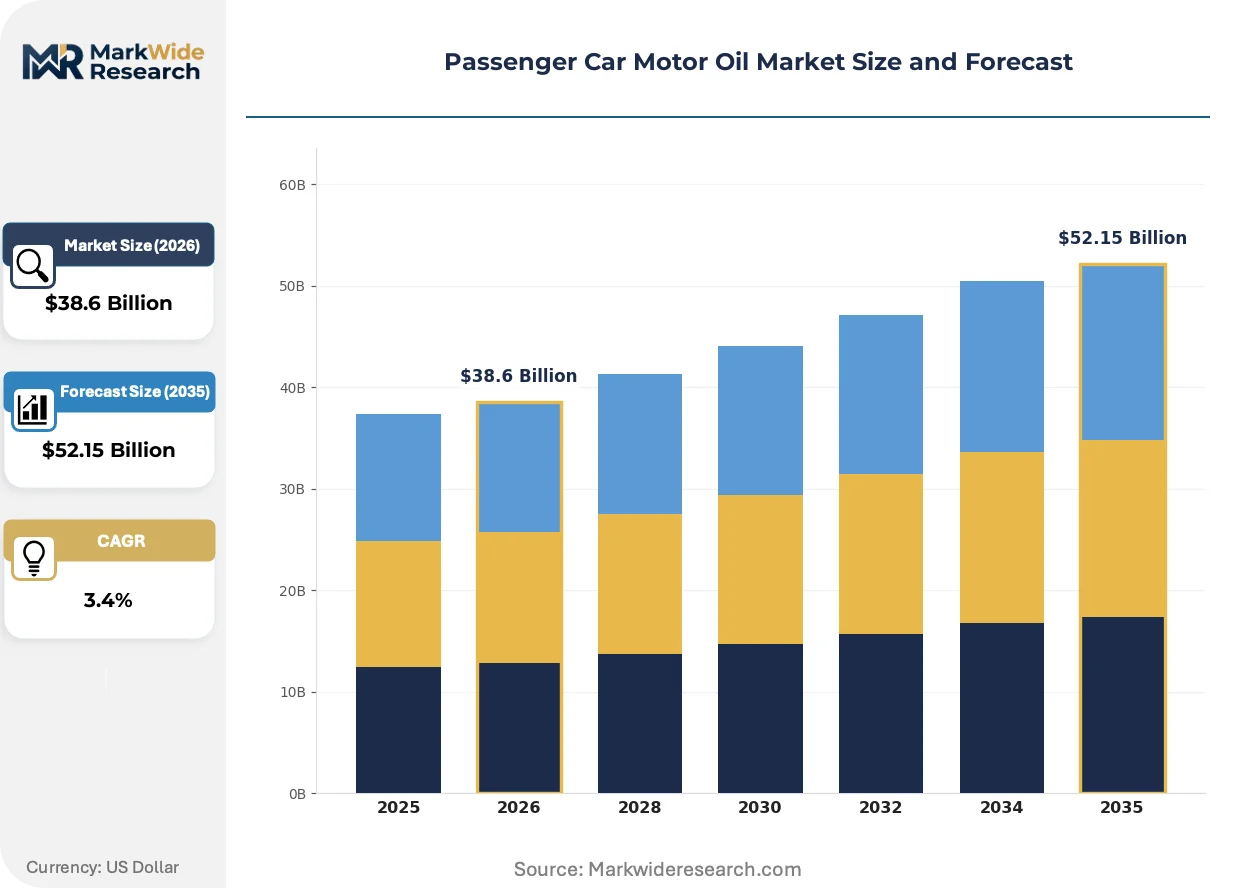
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $52.15 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Synthetic, Synthetic Blend, High Mileage Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 End User: Individual Consumers, Automotive Service Centers, Fleet Operators, Oil Change Shops Packaging Type: Bottles, Drums, Bulk, Sachets |
| Companies Covered | Shell plc, ExxonMobil, BP plc, TotalEnergies, Chevron Corporation, Valvoline Inc., Sinopec Lubricant, PetroChina, FUCHS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Car Motor Oil Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward molecular precision as base oil technology narrows performance differentials, while regulatory chemistry restrictions and electrification timelines compress traditional product lifecycle assumptions.
Polyalphaolefin synthetic base stocks are migrating from niche high-performance applications into mainstream OEM fill specifications as metallocene catalyst technology improves low-temperature fluidity and oxidative stability. German and Japanese automakers now specify Group III+ or PAO blends for extended drain intervals, compressing mineral oil share in new vehicle parc alignment and forcing mid-tier blenders to reformulate or exit premium segments.
Europe's F-Gas Regulation and REACH additive restrictions are tightening permissible chemistry thresholds for sulfur, boron, and phosphorus content. Blenders must redirect formulation investment toward ash-reduced and sulfur-free packages, with ACEA C sequences capturing the compliance pathway. German OEMs are responding by tightening co-development specifications and requiring third-party chemistry certification before supplier qualification.
Service bay consolidation and fleet direct-procurement models are compressing traditional distributor margins and fragmenting aftermarket channel power. Independent repair shops in the United States are losing volume to national quick-lube chains and telematics-enabled fleet maintenance programs, while price transparency platforms accelerate switching behavior and compress brand loyalty cycles in consumer segments.
Passenger Car Motor Oil Market Segmentation
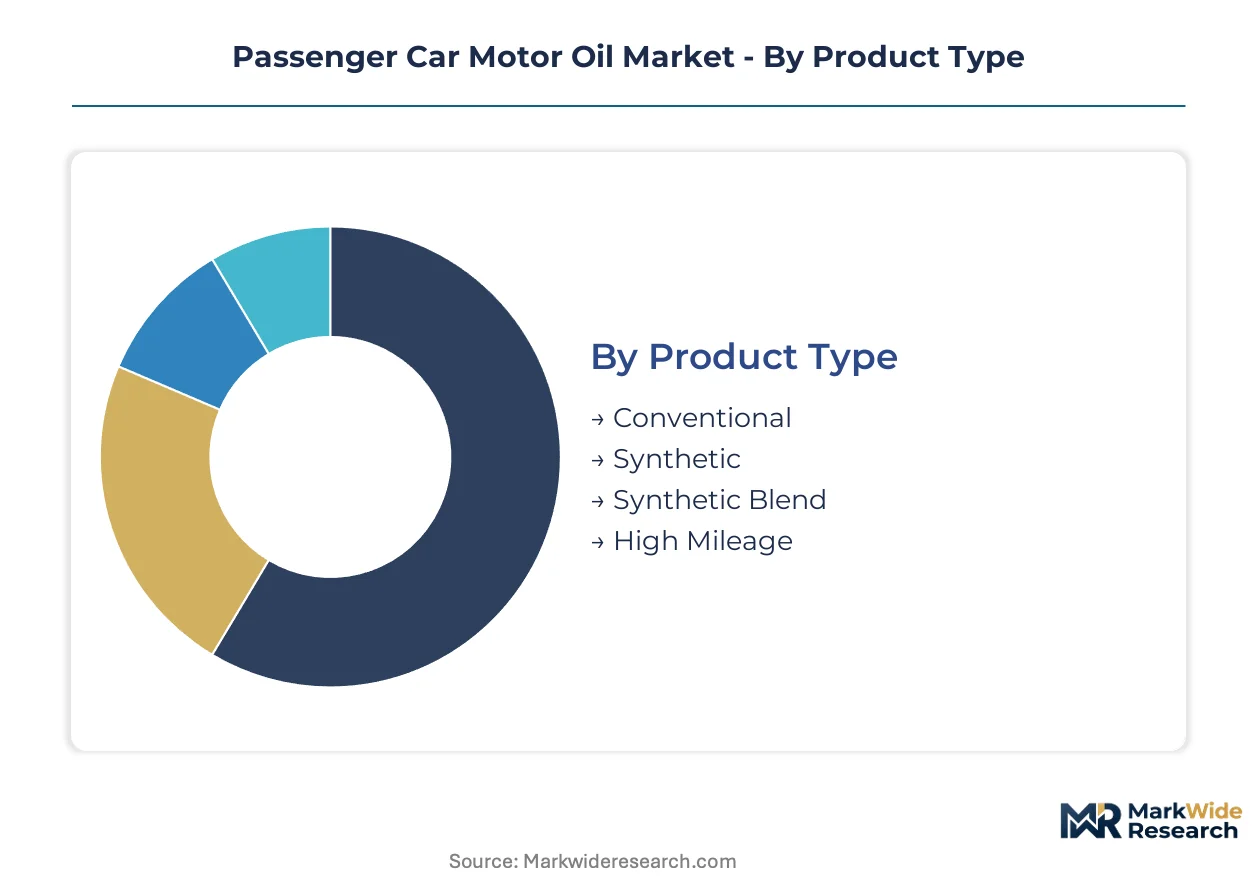
Passenger car motor oil segmentation reveals how formulation technology, viscosity engineering, and channel economics fragment demand across distinct customer workflows. Each dimension carries divergent margin structures and regulatory exposure that reshape competitive positioning.
Product Type:
Cost tier differentiation separates mineral-derived formulations from laboratory-engineered synthetic chemistries, with blending complexity and additive packages determining price positioning.
- Conventional:Refined petroleum base stocks with standard detergent-dispersant packages serve price-sensitive aftermarket channels. Demand concentrates in India's emerging service bays and independent repair shops where per-liter cost governs purchase decisions.
- Synthetic:Group III+ or PAO base stocks deliver extended drain intervals and thermal stability for OEM fill specifications. German automakers now mandate synthetic grades for factory fill, compressing mineral oil share in new vehicle parc alignment.
- Synthetic Blend:Hybrid formulations balance performance uplift against cost premiums for mid-tier positioning.
- High Mileage:Seal conditioners and anti-wear boosters target vehicles exceeding 120,000 kilometers.
Conventional commands the established base. The steepest expansion runs through Synthetic.
Viscosity Grade:
Application temperature range and engine architecture specifications fragment demand across SAE J300 classifications, with OEM fuel economy credits pulling formulation investment toward low-viscosity chemistries.
- 0W-20:Ultra-low viscosity PAO or Group III+ formulations minimize cold-start friction and maximize EPA fuel economy credit eligibility. Japanese and US automakers specify this grade for hybrid and downsized turbocharged engines.
- 5W-30:The mainstream workhorse balances cold-crank protection with high-temperature shear stability. European OEMs favor this grade for ACEA C-sequence compliance and extended drain intervals.
- 10W-40:Higher viscosity mineral or semi-synthetic blends retain share in aging vehicle parc and high-temperature climates.
- 15W-50:Heavy-duty viscosity for performance engines and severe operating conditions.
10W-40 retains the legacy installed base. The steepest climb in specification share is occurring through 0W-20.
End User:
Customer type determines procurement scale, brand loyalty cycles, and technical specification authority, with fleet direct-procurement models compressing traditional distributor economics.
- Individual Consumers:DIY purchasers buying through retail auto parts chains or e-commerce platforms. Price transparency engines accelerate switching behavior and erode brand stickiness in this segment.
- Fleet Operators:Commercial vehicle managers in Germany and the United States negotiate contracted volume pipelines with predictive maintenance programs. Telematics-enabled service intervals create locked-in synthetic formulation demand.
- Automotive Service Centers:Multi-bay independent and franchised repair facilities sourcing through distributor networks.
- Oil Change Shops:Quick-lube chains with high-throughput models and bulk procurement leverage.
Individual Consumers anchor volume scale. The fastest share gains are materializing through Fleet Operators.
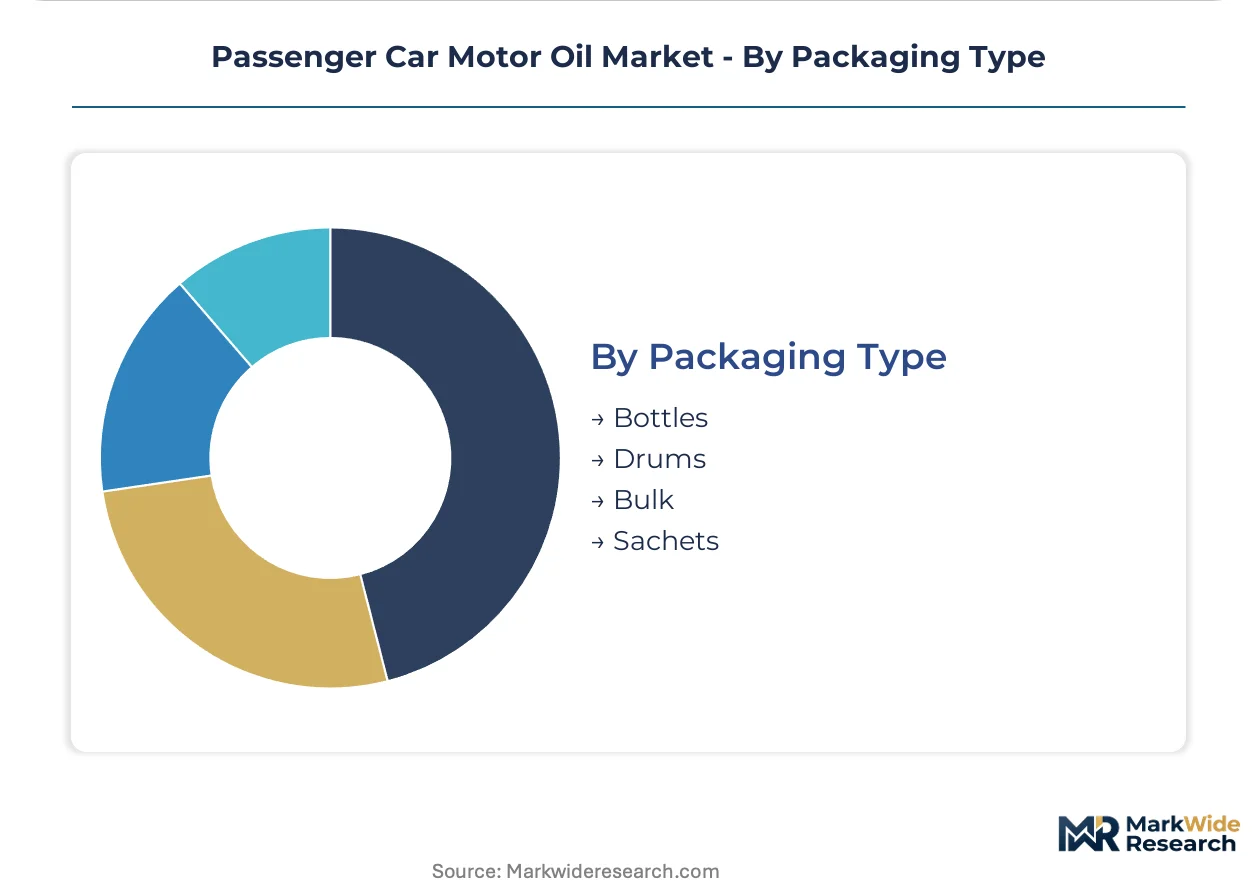
Packaging Type:
Volume and handling economics segment distribution infrastructure, with bulk and drum formats capturing commercial scale while bottles retain consumer accessibility.
- Bulk:Tanker or tote deliveries for high-throughput service centers and fleet maintenance depots. US quick-lube chains and German commercial operators favor this format for per-liter cost minimization.
- Drums:200-liter containers for mid-scale workshops and regional distributors. India's aftermarket expansion relies heavily on drum-format supply to independent service bays.
- Bottles:Retail-ready 1-liter to 5-liter containers for consumer DIY and small workshop procurement.
- Sachets:Single-use pouches for emergency top-up and rural distribution in emerging markets.
Bottles hold the consumer-facing standard. The most rapid format shift is advancing through Bulk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German blenders export high-specification synthetic formulations to automotive manufacturing corridors across Central Europe and North America, establishing a trade-flow corridor that channels REACH-compliant chemistries into OEM fill programs.
United States
EPA fuel economy credits tied to SAE J300-compliant low-viscosity oils pull formulation investment toward 0W-20 and 5W-30 grades. California's Air Resources Board imposes additional volatility limits that fragment regional product portfolios. Detroit's automotive engineering cluster concentrates OEM specification authority, with domestic automakers mandating synthetic grades for factory fill.
Germany
German automakers specify Group III+ or PAO blends for extended drain intervals, compressing mineral oil share in new vehicle parc alignment. The F-Gas Regulation and REACH framework restrict sulfur, boron, and phosphorus content in additive packages. Stuttgart's manufacturing corridor sets regional benchmarks for OEM co-development specifications and third-party chemistry certification.
China
Domestic vehicle parc expansion sustains volume demand for conventional and semi-synthetic grades in price-sensitive aftermarket channels. The Ministry of Ecology and Environment enforces dual carbon goals that redirect refinery investment toward higher-purity base stock output. Shanghai's Yangtze River Delta cluster hosts blending capacity serving both domestic OEM fill and export markets.
India
Aftermarket channel expansion in emerging service bays retains conventional oil dominance where per-liter cost governs purchase decisions. Bureau of Indian Standards certification requirements shape product registration timelines for imported formulations. Maharashtra's automotive component belt concentrates independent repair shop density and drum-format distribution infrastructure.
Japan
Japanese automakers specify ultra-low viscosity 0W-20 grades for hybrid and downsized turbocharged engines to maximize thermal efficiency. METI energy conservation standards accelerate OEM drain interval extensions past fifteen thousand kilometers. Toyota City's engineering ecosystem anchors co-development relationships between domestic automakers and lubricant formulators.
Passenger Car Motor Oil Market Key Industry Players
On the supply side, the industry is consolidating around integrated energy majors with captive base oil production and specialized lubricant blenders with regional formulation expertise. Three archetypes dominate: integrated oil majors controlling gas-to-liquids and refining assets, mid-tier blenders competing on service bay relationships, and national oil companies leveraging domestic feedstock access. Competitive moves center on backward integration into base oil production and strategic partnerships for OEM co-development agreements.
Within the integrated major tier, Shell plc and ExxonMobil occupy positions defined by proprietary synthetic base stock technology and geographic production scale. BP plc exemplifies brand-architecture competition through aftermarket channel presence and OEM thermal fluid specifications. These entities anchor the premium formulation segment where extended drain intervals and regulatory compliance create entry barriers for smaller blenders.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil |
| BP plc |
| TotalEnergies |
| Chevron Corporation |
| Valvoline Inc. |
| Sinopec Lubricant |
| PetroChina |
| FUCHS |
| Others |
Cost & Logistics Intelligence
REACH additive chemistry restrictions function as a regulatory chokepoint that simultaneously widens price spreads between premium synthetic and economy mineral formulations while compressing mid-tier blenders into backward integration or exit decisions. This chemistry constraint reshapes both tiered pricing architecture and sourcing strategies across European and export-oriented supply networks.
Pricing Analysis
The technology-generation pricing gap separates next-generation boron-free synthetic packages from incumbent sulfur-rich formulations and legacy mineral base stocks. Three-tier pricing structure across premium, standard, and economy levels reflects ACEA C-sequence certification costs, captive Group III+ base oil access, and volume scale in fleet procurement contracts. Cost compression in mid-tier synthetic blends is intensifying because Asian refiners dominate high-purity base stock output. Fleet operators in Germany exhibit the lowest price sensitivity due to telematics-locked service contracts, while India's independent repair shops remain most responsive to per-liter differentials.
Supply Chain Analysis
Tariff exposure between Asian base oil exporters and European blenders dominates supply chain risk calculations for REACH-compliant formulation networks. Production gravity centers on South Korea, Singapore, and Germany for Group III+ and PAO base stocks, while additive package blending draws from the United States, Germany, and Japan. The supply chain hinges on single-source vulnerability in metallocene catalyst technology for ultra-low viscosity grades. Distribution runs through bulk tanker networks for fleet and quick-lube channels, with drum and bottle formats serving fragmented aftermarket service bays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH and ACEA sequence certification timelines create switching costs that protect incumbent positions while raising barriers for unqualified entrants.
For Market Incumbents: Harden supply security through captive Group III+ base oil production or long-term offtake agreements with Asian refiners. Deepen OEM co-development relationships for hybrid thermal management fluids before electrification roadmaps fragment addressable demand. Defensive consolidation should prioritize additive package suppliers with proven boron-free chemistry portfolios.
For New Entrants and Emerging Players: Build out regional blending capacity in India's Maharashtra automotive belt to capture conventional oil volume in price-sensitive aftermarket channels. White-space exists in thermal fluid specifications for hybrid powertrains where lubricant-coolant convergence products lack established suppliers. A fleet-direct procurement model with telematics-enabled predictive maintenance contracts offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated majors with captive base oil assets and specialized blenders with OEM qualification depth. Long-term viability rests on exposure to extended drain interval specifications and regulatory-compliant chemistry capabilities. The signal to watch is battery electric vehicle penetration rates in passenger segments as the inflection indicator for residual internal-combustion demand sizing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group III+ supply secures formulation flexibility against Asian refiner concentration. |
| OEM Co-Development Agreement | Thermal management fluid specifications for hybrid powertrains create preferred supplier status. |
| REACH-Compliant Additive Package Investment | Boron-free and sulfur-reduced chemistry certification unlocks European automotive manufacturing corridors. |
| Fleet Direct Procurement Contract | Telematics-enabled predictive maintenance creates locked-in synthetic formulation volume pipelines. |
| India Aftermarket Channel Expansion | Drum-format distribution to independent service bays captures price-sensitive conventional oil demand. |
Research Approach
Desk research of trade flow databases, refinery capacity disclosures, and regulatory filing repositories preceded structured interviews with lubricant formulators, OEM procurement leads, fleet maintenance managers, and additive package suppliers. Primary fieldwork captured specification evolution timelines and co-development relationship dynamics. Secondary validation drew from customs records, ACEA sequence documentation, and SEC filings of integrated energy majors. Bottom-up volume modeling triangulated against top-down market sizing across synthetic, blend, and conventional product tiers.
Fixed assumptions across the analysis window held battery electric vehicle penetration, REACH enforcement timelines, and OEM drain interval extension rates at central-case values while stress-testing high-low bands. Segmentation dimensions modeled included product type, viscosity grade, end-user archetype, and packaging format, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from parc alignment trends and specification shift velocities. Forecast inputs incorporated base oil capacity expansion announcements and F-Gas Regulation implementation schedules.
Stress conditions across electrification adoption curves, additive chemistry substitution costs, and refinery output disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM specification authority and fleet procurement consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Motor Bearings Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Oil Filter Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Coolant Aftermarket Market