
 Electric Forklifts Market | 2026-2036
Electric Forklifts Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Forklifts Market Foresight
ISO 3691-1 safety certification is reorganizing competitive access in electric forklifts, forcing OEMs to redesign mast stability systems and control architectures. Toyota Industries Corporation leverages its captive battery supply chain to anchor premium positioning in counterbalance units. Jungheinrich AG specializes in narrow-aisle reach trucks for European warehouse operators. BYD Company Ltd competes on lithium-iron-phosphate cell integration, bypassing conventional lead-acid infrastructure entirely.
An electric forklift is a battery-powered industrial truck equipped with an electric motor, controller unit, and rechargeable energy storage system designed to lift and transport palletized loads across warehouse and manufacturing environments. Lithium-ion battery configurations now displace lead-acid systems in high-throughput operations where opportunity charging and zero maintenance offset upfront capital premiums. Counterbalance units dominate unit shipments across manufacturing end users, while reach trucks command margin concentration in automated warehouse verticals. Pallet jack electrification is accelerating fastest among retail distribution networks replacing manual pump trucks.
The EPA enforces Tier 4 Final emissions standards that effectively bar new diesel forklift sales in indoor applications, redirecting procurement budgets toward electric alternatives. OSHA powered industrial truck standards mandate operator training and equipment inspection protocols that shape fleet replacement cycles. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in cooling systems, indirectly pressuring remaining internal combustion forklift segments. Stakeholders must monitor battery raw material supply agreements and charging infrastructure interoperability standards as fleet electrification scales.
Market Dynamics
Battery chemistry migration from lead-acid to lithium-ion is compressing fleet total cost of ownership and forcing charging infrastructure retrofits across warehouse operations worldwide.
Growth Catalysts
- EPA Tier 4 Final standards:Indoor diesel forklift sales face de facto prohibition in United States manufacturing facilities, redirecting capital expenditure toward electric alternatives.
- E-commerce fulfillment density:Automated storage and retrieval system deployments in Germany and China demand electric fleets compatible with narrow-aisle robotics.
- Lithium-iron-phosphate cells:Opportunity charging protocols eliminate battery changeout labor, cutting operational downtime in high-throughput distribution centers.
Market Restraints
- Cobalt and lithium price volatility:Raw material cost swings compress OEM margins and destabilize long-term fleet leasing contracts.
- Charging infrastructure capital intensity:Grid upgrade requirements and high-voltage installation timelines extend facility electrification payback periods beyond procurement cycles.
- Lead-acid incumbent base:Existing battery watering systems and maintenance workflows create organizational friction against chemistry transitions.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for manufacturing and logistics infrastructure create first-mover positioning for lithium-ion forklift penetration.
- Battery-as-a-service models:Unbundled energy storage subscriptions convert capital expenditure to operating expenditure for mid-size fleet operators.
- ISO 3691-1 compliance services:Mast stability recertification and operator retraining packages capture margin from safety mandate enforcement.
Industry Challenges
- High-voltage technician scarcity:Lithium-ion system diagnostics and thermal runaway response protocols outpace vocational training program output.
- Legacy fleet integration:Mixed-voltage charging networks and warehouse management system compatibility extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Forklifts Market |
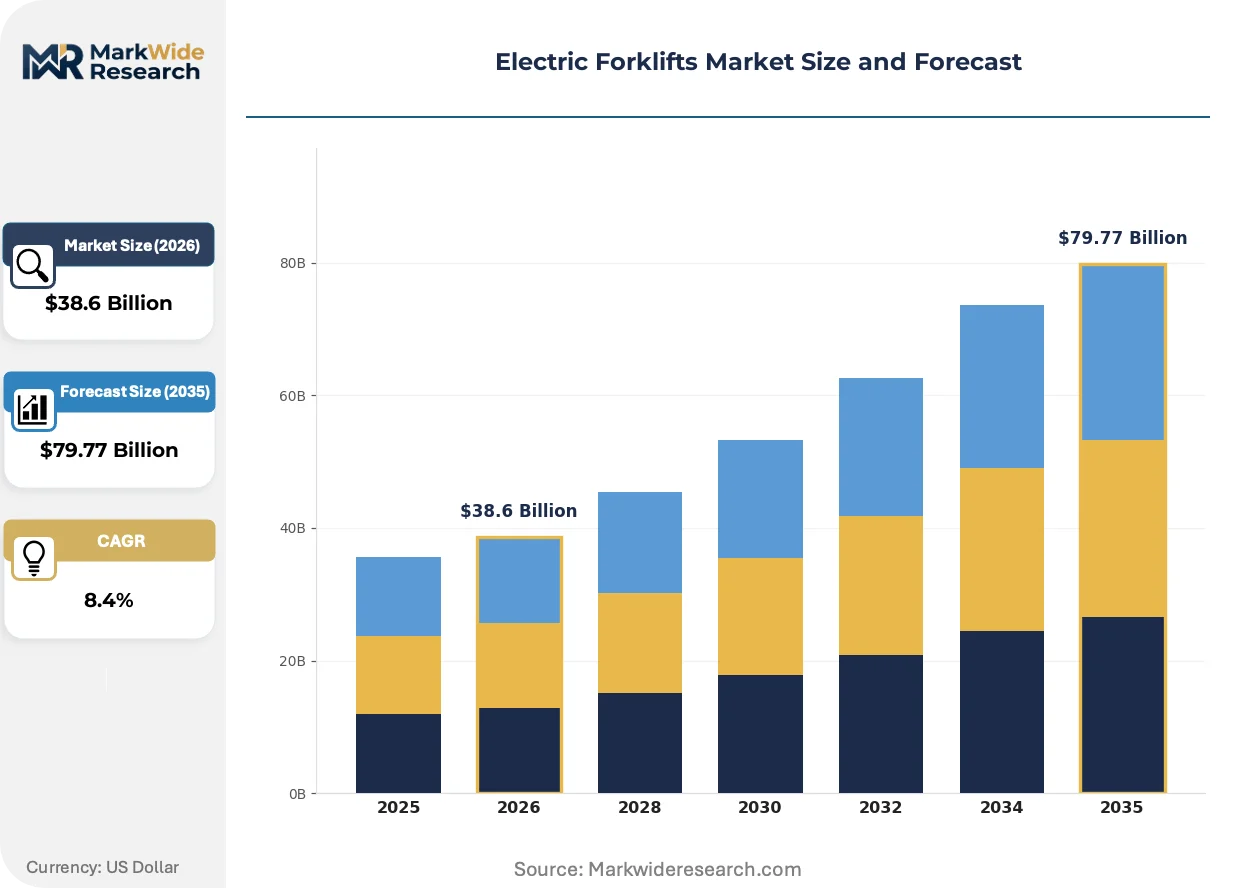
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counterbalance, Reach Truck, Pallet Jack, Order Picker End User: Warehouse, Manufacturing, Retail, Construction Battery Type: Lead-Acid, Lithium-Ion, NiMH, Others Load Capacity: Below 3 Ton, 3-5 Ton, 5-10 Ton, Above 10 Ton |
| Companies Covered | Crown Equipment Corporation, Komatsu Ltd., Toyota Industries Corporation, Anhui Heli Co Ltd., BYD Company Ltd, KION Group AG, Hyster-Yale Materials Handling Inc., Hangcha Group Co Ltd, Jungheinrich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Forklifts Market Shifts & Advancements
Electrification is converging with automation and data analytics to redefine fleet economics and operator interaction models across material handling operations.
Lithium-iron-phosphate battery packs is supplanting lead-acid configurations in three-shift operations. Cold storage distributors and automotive parts suppliers are adopting opportunity charging protocols that eliminate battery swap infrastructure. The technology is compressing facility footprint requirements and reducing lifetime energy costs by half.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are accelerating phase-out of internal combustion engine forklifts with hydrofluorocarbon-based cooling. Equipment lessors in European Union member states face stranded asset risk on diesel fleet residuals. Counterbalance forklift procurement in Germany and Netherlands is shifting decisively toward fully electric alternatives.
Telematics-enabled usage-based contracting is displacing traditional equipment ownership in retail distribution networks. Third-party logistics providers are unbundling forklift assets from labor contracts, transferring utilization risk to OEM finance arms. United States grocery and consumer packaged goods verticals are piloting per-pallet-move pricing structures.
Electric Forklifts Market Segmentation
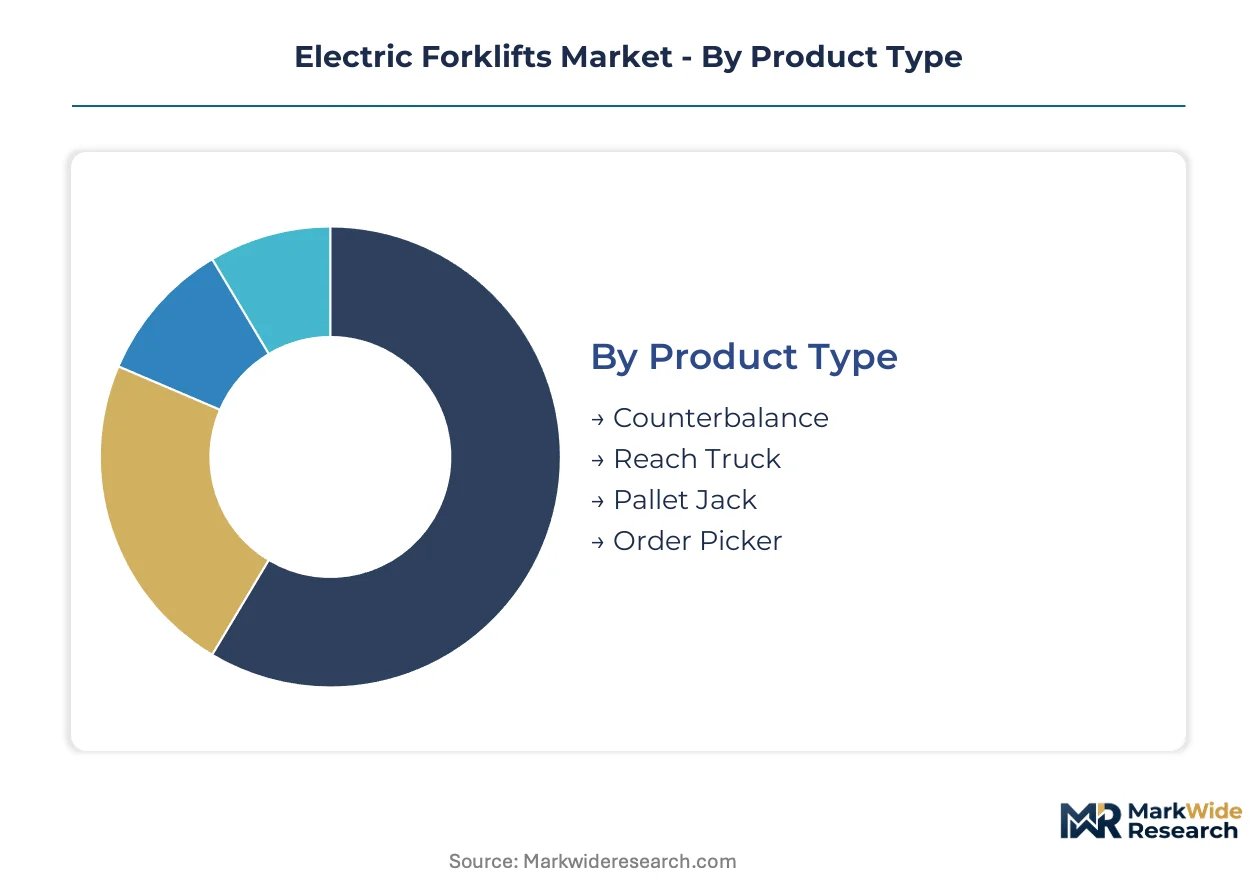
Segmentation in electric forklifts reveals how battery chemistry, load specifications, and facility type dictate procurement channels. Equipment lessors and OEM direct sales target different segments based on operational intensity and fleet scale.
Product Type:
Counterbalance units and reach trucks flow through industrial distributors and OEM direct channels, while pallet jacks concentrate in retail procurement and e-commerce fulfillment networks.
- Counterbalance:The most versatile configuration features a weighted rear chassis to offset front-loaded pallets without outrigger arms. Manufacturing plants in Germany and the United States specify these for dock-to-stock operations where aisle width permits. Lead-acid variants still dominate existing fleet bases, though lithium-ion retrofits are accelerating replacement cycles.
- Reach Truck:Designed with telescoping masts and outrigger legs that extend into racking aisles as narrow as 2.5 meters. Automated warehouses in China and the Netherlands deploy these for high-density storage compatible with autonomous mobile robot coordination. Opportunity charging protocols eliminate battery swap labor in three-shift operations.
- Pallet Jack:Compact walk-behind or ride-on units for horizontal transport over short distances. Retail distribution centers are electrifying fastest here, replacing manual pump trucks with lithium-ion variants that support continuous picking workflows.
- Order Picker:Elevating operator platforms enable manual case-level selection from elevated racking. Cold storage distributors favor these for temperature-controlled fulfillment where diesel emissions are prohibited.
By volume, Counterbalance leads. By growth pace, Pallet Jack electrification is climbing the fastest.
End User:
Cost tier separation is pronounced: manufacturing and warehouse operations absorb premium lithium-ion configurations, while retail and construction segments remain price-sensitive with longer lead-acid replacement horizons.
- Warehouse:Multi-shift distribution facilities with automated storage and retrieval systems. E-commerce fulfillment centers in the United States and Germany are driving fleet electrification fastest here, with charging infrastructure integrated into facility design.
- Manufacturing:Just-in-time production environments where forklifts feed assembly lines. Tier 1 automotive suppliers specify electric fleets to comply with EPA indoor air quality mandates and OSHA powered industrial truck standards.
- Retail:Back-of-store and regional distribution operations with intermittent usage patterns. Grocery and consumer packaged goods chains are piloting telematics-enabled usage-based contracting to convert capital expenditure to operating expenditure.
- Construction:Outdoor and rough-terrain applications with heavier load demands. This segment lags in electrification due to battery range limitations and charging infrastructure gaps on temporary job sites.
Manufacturing commands the highest average selling prices. Warehouse applications are gaining share fastest.
Battery Type:
Margin concentration follows chemistry: lithium-ion systems capture premium positioning, while lead-acid maintains volume through installed base inertia and lower upfront capital requirements.
- Lead-Acid:Flooded or sealed lead-acid cells requiring regular watering and equalization charging. Existing fleet bases in North America and legacy European warehouses retain these due to sunk infrastructure costs in battery changeout stations and maintenance workflows.
- Lithium-Ion:Lithium-iron-phosphate and lithium-manganese-oxide chemistries enabling opportunity charging and zero maintenance. BYD Company Ltd and Toyota Industries Corporation are vertically integrating cell production to secure supply for high-throughput operations.
- NiMH:Nickel-metal hydride configurations offering intermediate energy density with reduced thermal runaway risk compared to lithium-ion. Niche adoption in cold storage applications where operating temperatures stress conventional chemistries.
- Others:Emerging solid-state and sodium-ion prototypes in pilot deployment. These remain pre-commercial for material handling applications pending scale manufacturing cost reduction.
Lead-Acid still ships the most units annually. Lithium-Ion is expanding most quickly in new fleet procurement.
Load Capacity:
Application maturity varies by tonnage: below 3 ton segments are fully electrified with commodity pricing, while above 10 ton remains contested terrain between electric and internal combustion alternatives.
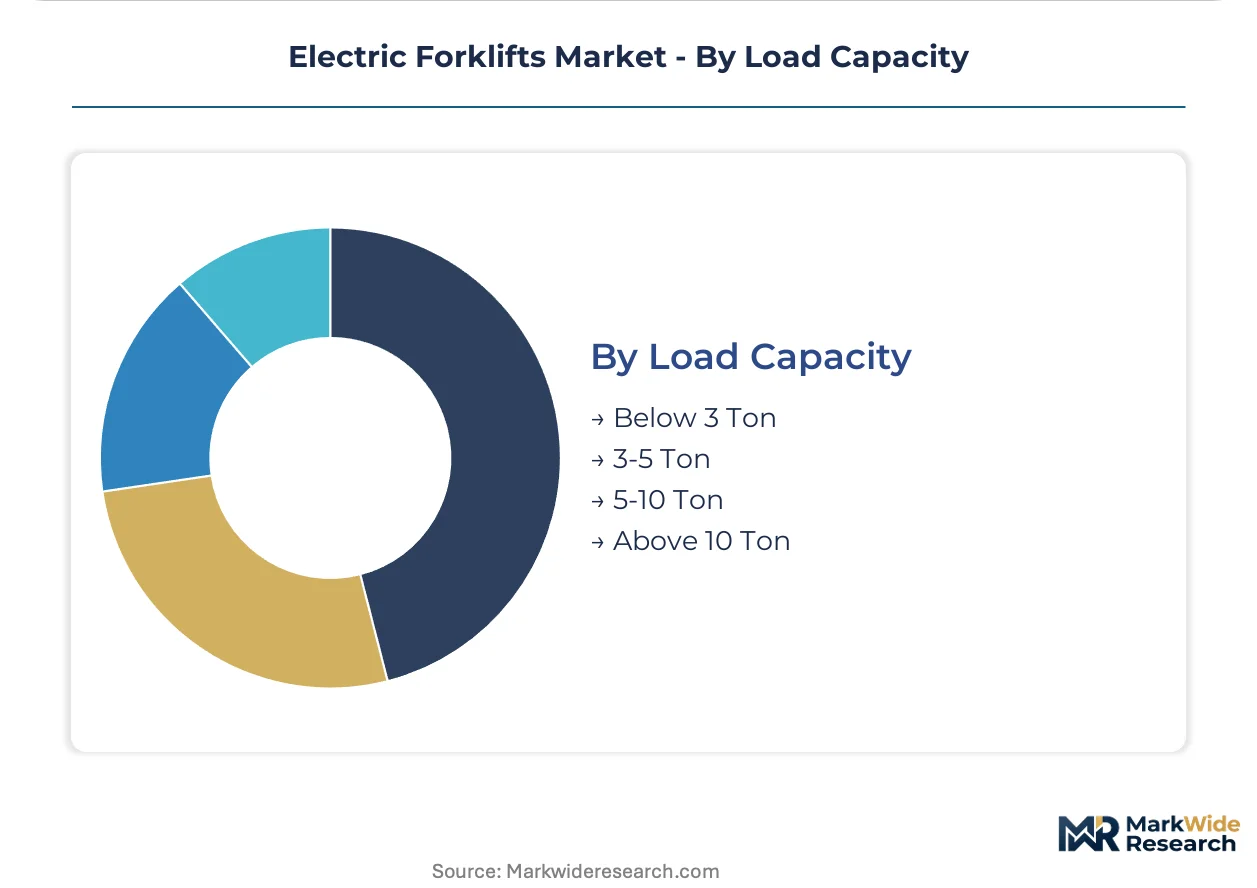
- Below 3 Ton:Standard pallet weights for retail and light manufacturing. Pallet jacks and three-wheel counterbalance units dominate here, with lithium-ion penetration highest due to manageable battery mass and charging infrastructure requirements.
- 3-5 Ton:Four-wheel counterbalance configurations for general warehousing and automotive parts distribution. This band captures the bulk of replacement demand as EPA Tier 4 Final standards phase out diesel equivalents.
- 5-10 Ton:Heavy-duty counterbalance units for steel, paper, and beverage handling. Battery weight and charging duration create operational constraints that hybrid and hydrogen fuel cell alternatives are targeting.
- Above 10 Ton:Specialty container handlers and heavy manufacturing applications. Electric penetration remains limited due to energy density requirements, though port electrification mandates in California and Rotterdam are stimulating development.
The 3-5 Ton band anchors current revenue. Below 3 Ton is gaining share fastest as retail electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity clusters in Germany, China, and the United States where warehouse automation investments are deepest and emissions regulations are most stringent. Buyer archetypes span automotive tier-1 suppliers, e-commerce fulfillment operators, and third-party logistics providers with distinct fleet scale requirements.
United States
EPA Tier 4 Final standards bar new diesel forklift sales in indoor manufacturing facilities, redirecting capital expenditure toward electric alternatives. OSHA powered industrial truck standards mandate operator training protocols that shape fleet replacement cycles. The Midwest automotive corridor spanning Michigan and Ohio anchors counterbalance unit demand from just-in-time assembly line feeding operations.
Germany
EU F-Gas Regulation restrictions on fluorinated greenhouse gases accelerate phase-out of internal combustion engine forklifts with hydrofluorocarbon-based cooling systems. The country's national industrial safety regulator enforces ISO 3691-1 mast stability certifications that force OEM redesigns. The Rhine-Ruhr logistics cluster and Bavarian automotive supply chain drive narrow-aisle reach truck procurement for automated storage integration.
China
Dual carbon goals under MEE supervision compress timelines for industrial fleet electrification across manufacturing and logistics sectors. GB standards for industrial vehicle safety reshape certification requirements for domestic and imported equipment. The Yangtze River Delta warehouse automation corridor around Shanghai and Suzhou concentrates lithium-ion forklift deployment for e-commerce fulfillment networks.
Japan
METI industrial decarbonization roadmaps pressure manufacturing facilities to eliminate propane and diesel forklifts from indoor environments. JIS standards for battery-powered industrial trucks establish interoperability benchmarks for charging infrastructure. The Chubu region around Nagoya anchors demand from automotive and electronics manufacturing clusters with high-throughput material handling requirements.
India
PLI scheme incentives for manufacturing and logistics infrastructure create first-mover positioning for lithium-ion forklift penetration in emerging warehouse automation. The central electricity authority regulates grid upgrade standards that shape charging infrastructure deployment timelines. The Delhi-NCR logistics corridor and Maharashtra industrial belt around Pune concentrate early fleet electrification pilots among third-party logistics providers.
Electric Forklifts Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive battery supply chains and specialized material handling equipment manufacturers. Market structure shows moderate consolidation around integrated OEMs with vertical control over critical components. Three strategic archetypes dominate: Japanese and German industrial groups with automotive heritage, Chinese battery-integrated challengers, and European narrow-aisle specialists. Competitive moves concentrate on backward integration into cell production and strategic partnerships for charging infrastructure deployment.
Within the diversified industrial tier, Toyota Industries Corporation and Komatsu Ltd represent integrated manufacturers with captive supply chain advantages. BYD Company Ltd exemplifies the battery-native challenger archetype leveraging in-house lithium-iron-phosphate cell production. Jungheinrich AG occupies the specialist position in European warehouse automation. KION Group AG anchors the premium-tier reach truck segment. Crown Equipment Corporation and Hyster-Yale Materials Handling Inc sit within the North American distribution-focused tier. Anhui Heli Co Ltd and Hangcha Group Co Ltd represent scale-driven Chinese fabricators expanding internationally.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Komatsu Ltd. |
| Toyota Industries Corporation |
| Anhui Heli Co Ltd. |
| BYD Company Ltd |
| KION Group AG |
| Hyster-Yale Materials Handling Inc. |
| Hangcha Group Co Ltd |
| Jungheinrich AG |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for lithium-iron-phosphate cell packs concentrate pricing power with integrated OEMs possessing captive battery supply chains, while spot-market buyers absorb volatility in cobalt and lithium carbonate indices. This inventory compression dynamic rewards backward integration and punishes pure-play assemblers without upstream cell offtake agreements.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange lithium carbonate and cobalt sulfate benchmarks dominate long-term fleet procurement agreements between OEMs and large warehouse operators. Price differentiation rests on ISO 3691-1 certification tier and charging infrastructure bundling, with certified premium units commanding substantial premiums over uncertified standard configurations. Cost compression in the lead-acid replacement segment is intensifying because Chinese cell producers are expanding lithium-iron-phosphate capacity faster than European charging infrastructure deployment. Retail distribution networks exhibit the highest price sensitivity due to intermittent utilization patterns, while automated warehouse operators demonstrate the lowest sensitivity given operational downtime costs from battery failures.
Supply Chain Analysis
Strait of Malacca transit underwrites critical raw material flows for electric forklift battery production, with concentrated exposure to disruption from regional shipping congestion. Cell manufacturing concentrates in China, South Korea, and Japan, while forklift final assembly localizes in Germany, the United States, and China to satisfy regional regulatory certification requirements. The supply chain draws from lithium carbonate, cobalt sulfate, and copper busbar inputs, with single-source vulnerability concentrated in cathode active material precursor processing. Tariff exposure runs through battery cell trade flows between China and Western markets. Distribution runs through industrial equipment distributors for manufacturing segments and OEM direct sales for large automated warehouse deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric forklifts market functions as a defensive-moat industry where regulatory entrenchment around EPA Tier 4 Final and EU F-Gas standards creates substantial switching costs for fleet operators committed to electrification infrastructure investments.
For Market Incumbents: Shield installed base relationships by embedding telematics-enabled usage-based contracting that raises switching costs for warehouse operators. Deepen captive battery supply through in-house lithium-iron-phosphate cell production or exclusive offtake agreements with Chinese producers. Expand ISO 3691-1 compliance service offerings to capture recurring revenue from mandatory recertification cycles.
For New Entrants and Emerging Players: Differentiate on battery-as-a-service subscription models that convert capital expenditure to operating expenditure for mid-size fleet operators in India and Southeast Asia. Target India's PLI-subsidized warehouse automation corridor where incumbent presence remains shallow. Pursue white-label partnerships with established industrial distributors rather than building captive sales networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core material handling divisions amid portfolio restructuring. Long-term viability hinges on securing lithium-iron-phosphate cell supply agreements that outlast the current capacity expansion cycle. Monitor charging infrastructure interoperability standardization as the inflection signal for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | Toyota Industries and BYD secure lithium-iron-phosphate supply for high-throughput warehouse fleets. |
| Charging Infrastructure Partnership | OEM alliances with grid operators accelerate facility electrification payback periods in Germany. |
| Battery-as-a-Service Launch | Unbundled energy subscriptions convert capital expenditure to operating expenditure for mid-size operators. |
| ISO 3691-1 Compliance Service Expansion | Mast stability recertification packages capture margin from mandatory safety enforcement in EU markets. |
| Telematics Platform Integration | Usage-based contracting raises switching costs and displaces traditional equipment ownership in retail verticals. |
Research Methodology
A spread of perspectives from warehouse operations directors, OEM product managers, battery procurement leads, and industrial equipment distributors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with fleet operators across automotive, e-commerce, and third-party logistics verticals with secondary validation against SEC filings, EU F-Gas regulatory databases, EPA enforcement records, and customs trade data. Bottom-up unit shipment estimates by product type and battery chemistry triangulated against top-down market size calculations derived from OEM revenue disclosures.
Segmentation dimensions modeled include product type, battery chemistry, load capacity tier, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles, fleet electrification penetration curves, and regulatory phase-out timelines. Key forecast inputs incorporated lithium-iron-phosphate cell cost decline trajectories and charging infrastructure deployment rates in priority logistics corridors.
Decision-makers should treat outputs as directional under assumptions of continued EPA Tier 4 Final enforcement and EU F-Gas Regulation stringency; material deviation in regulatory timelines or battery raw material cost trajectories would warrant model refresh. Practitioners should keep alternative scenarios live as cobalt supply concentration and charging technician training pipeline constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Car Diffuser Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Vehicle Cargo Box Market