
 Asia-Pacific Electric Power Steering Market | 2026-2036
Asia-Pacific Electric Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Power Steering Market Outlook
Steer-by-wire architecture is reshaping how electric power steering systems are engineered for precision and weight reduction in Asia-Pacific vehicle platforms. JTEKT Corporation leverages its integrated column-assist production footprint across Japan and China to sustain regional supply leadership. NSK Ltd. anchors high-volume rack-and-pinion contracts with Japanese automotive OEMs. ZF Friedrichshafen AG competes through modular integrated systems that span passenger and commercial vehicle applications.
Electric power steering replaces hydraulic assist with an electric motor mounted on the steering column or rack, drawing 12-48V input to vary torque assistance based on vehicle speed and driver input via torque sensors and control modules. The technology eliminates engine-belt-driven hydraulic pumps, cutting fuel consumption by three to five percent in internal combustion platforms while enabling advanced driver-assistance integration. Rack and pinion configurations dominate volume across Asia-Pacific due to their compatibility with front-wheel-drive passenger cars, while brushless DC motor technology leads growth because of superior thermal efficiency and regenerative braking compatibility in hybrid platforms. Integrated systems that combine motor, controller, and sensor arrays into single housings command premium positioning as OEMs pursue packaging density and assembly simplification.
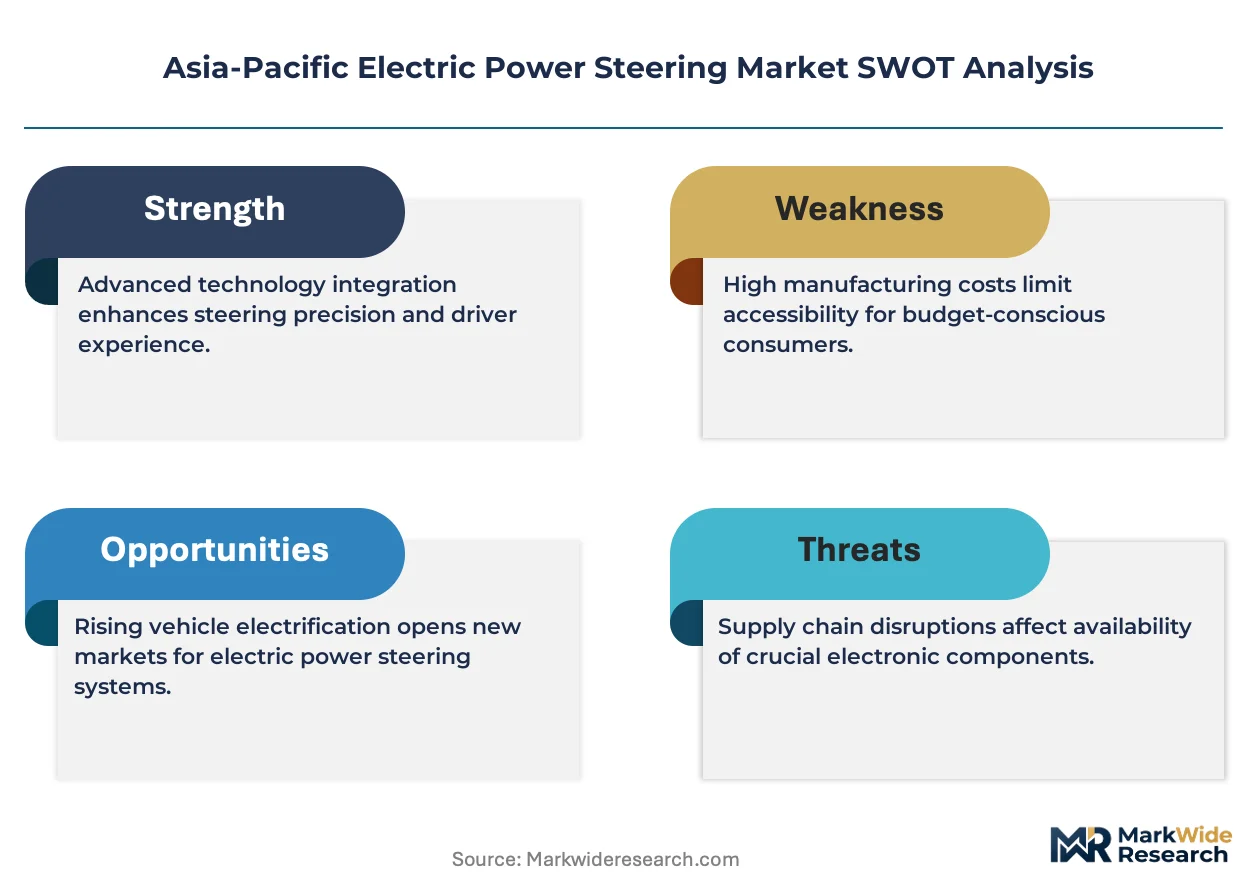
China's MIIT enforces dual carbon goals that push NEV steering suppliers toward higher-efficiency motor designs, while Japan's METI coordinates JIS standards for steer-by-wire fail-safe protocols. India's BIS mandates electromagnetic compatibility testing for imported steering electronics, shaping market access requirements for component vendors. Stakeholders must monitor how China's GB standards evolution and India's PLI scheme for automotive components will redistribute manufacturing investment across the region's supplier base.
Market Dynamics
Steer-by-wire architecture is compressing mechanical linkages across Asia-Pacific vehicle platforms as China's MIIT dual carbon goals and Japan's METI JIS fail-safe mandates simultaneously tighten efficiency and safety requirements.
Growth Catalysts
- Brushless DC motor adoption:Passenger car OEMs in China and Japan are converting steering columns to eliminate hydraulic pumps entirely. The technology captures regenerative braking energy in hybrid platforms.
- India's PLI scheme for automotive components:Domestic suppliers receive production-linked incentives for localizing EPS controller manufacturing. This draws assembly investment away from import-dependent configurations.
- China's eastern manufacturing corridor:Shanghai-Jiangsu-Zhejiang cluster concentrates tier-one steering system production within 200 kilometers of major OEM assembly plants.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings disrupt brushless DC motor cost structures. Suppliers face margin compression when contract pricing locks ahead of material spikes.
- Steer-by-wire fail-safe complexity:Redundant torque sensors and backup power systems add component count. Japan's METI JIS protocols extend validation timelines for new platform introductions.
- Hydraulic steering residual demand:Commercial vehicle segments in Southeast Asia retain belt-driven pumps for extreme load conditions. Electric alternatives carry payload and thermal management penalties.
Strategic Opportunities
- India's BIS electromagnetic compatibility mandates:Imported steering electronics must undergo domestic testing certification. Local assembly partners capture margin from compliance services.
- Integrated column-rack systems:Motor-controller-sensor consolidation into single housings reduces OEM assembly steps. Tier-one suppliers in China are tooling dedicated lines for this architecture.
- 48V mild-hybrid steering integration:Higher voltage architectures enable heavier assist torque without copper weight penalties. Korean and Japanese OEMs are specifying 48V EPS for next-generation C-segment platforms.
Industry Challenges
- Embedded software validation timelines:Functional safety certification under ISO 26262 stretches 18-24 months for new EPS control modules. OEMs delay platform launches when supplier code fails audit cycles.
- Torque sensor calibration precision:Sub-one-percent accuracy requirements demand cleanroom assembly environments. Southeast Asian suppliers struggle to replicate Japanese metrology standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Power Steering Market |
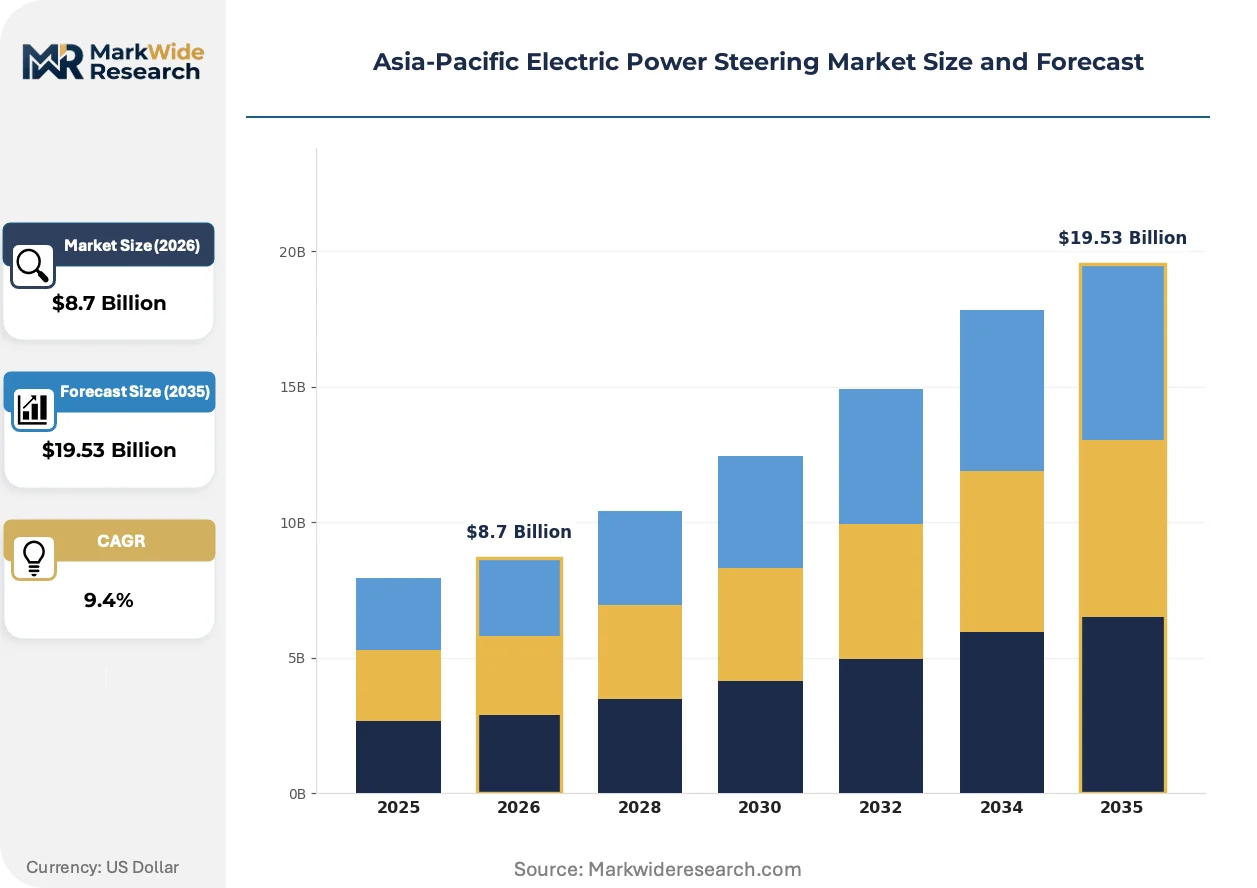
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column, Rack and Pinion, Electric Motor, Power Control Module Technology: Brushless DC, Steer-by-Wire, Servo Motor, Integrated Systems End User: Aerospace, Automotive OEMs, Aftermarket Providers, Commercial Vehicles Application: Passenger Cars, Light Trucks, Heavy-Duty Trucks, Specialty Vehicles |
| Companies Covered | JTEKT Corporation, NSK Ltd., Nexteer Automotive, ZF Friedrichshafen AG, Robert Bosch GmbH, Denso Corporation, HL Mando Corporation, Hyundai Mobis, Zhejiang Shibao Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Power Steering Market Strategic Shifts
Digital control architectures are displacing analog feedback loops across Asia-Pacific steering systems as software-defined functionality becomes the primary differentiation vector.
Steer-by-wire technology is digitizing the mechanical pathway between driver input and road-wheel response. Japanese and Chinese OEMs are specifying redundant electronic pathways for premium electric vehicle platforms. The architecture eliminates steering column intrusion into passenger compartments while enabling variable steering ratios through software calibration.
China's MIIT is enforcing GB standards for new energy vehicle steering efficiency that exceed prior internal combustion benchmarks. Suppliers must demonstrate three to five percent fuel-equivalent savings in certification testing. Rack-and-pinion configurations with brushless DC motors dominate compliant submissions.
Aftermarket service unbundling is fragmenting traditional dealer-channel dependency for EPS repairs. Independent workshops in India and Southeast Asia are acquiring diagnostic tools for torque sensor recalibration. Tier-one suppliers respond with encrypted software locks that route warranty claims through authorized channels.
Asia-Pacific Electric Power Steering Market Segmentation
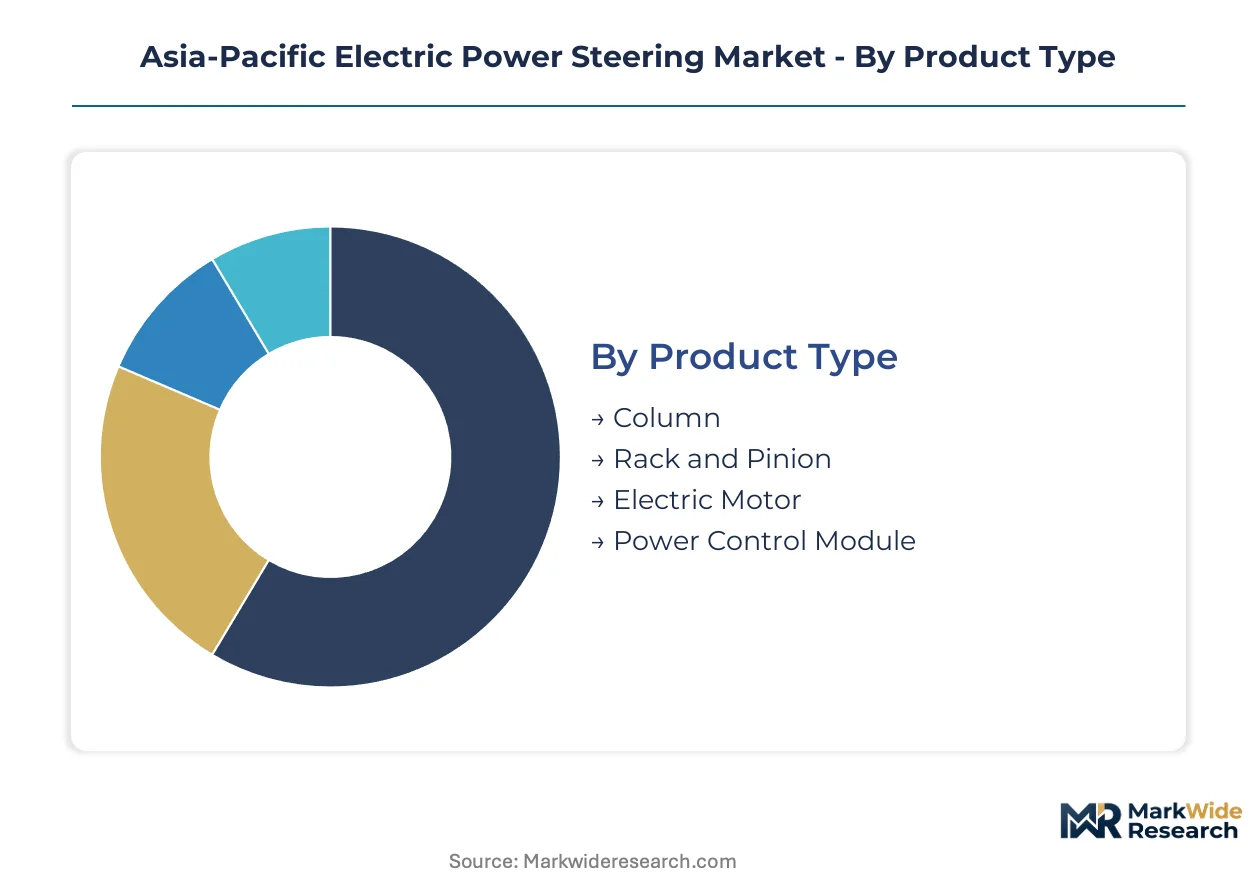
Segmentation in the Asia-Pacific Electric Power Steering Market reveals how component architecture, voltage protocols, and vehicle duty cycles reshape supplier priorities. Understanding these divisions exposes where brushless DC motor investments concentrate and which platform types drive steer-by-wire adoption.
Product Type:
The use-case spectrum spans from compact column-mounted assist units for urban passenger cars to fully integrated rack systems for premium electric vehicle platforms.
- Rack and Pinion:This configuration mounts the electric motor directly onto the steering rack, delivering precise torque vectoring for front-wheel-drive architectures. China's eastern manufacturing corridor—spanning Shanghai, Jiangsu, and Zhejiang—hosts dedicated production lines serving Japanese and Korean OEM assembly plants. MIIT efficiency mandates push suppliers toward higher gear-ratio precision to capture regenerative braking energy in hybrid applications.
- Column:Column-assist systems position the motor atop the steering shaft, offering packaging flexibility for subcompact vehicles where engine bay space is constrained. Indian suppliers localize these units under PLI scheme incentives to avoid BIS electromagnetic compatibility testing delays on imported controllers. The architecture dominates entry-level passenger car segments across Southeast Asia.
- Electric Motor:Standalone motor units serve retrofit applications and modular platform strategies where OEMs source controllers separately.
- Power Control Module:These embedded electronics govern torque assistance algorithms and interface with vehicle CAN networks for ADAS integration.
Established volume favors Rack and Pinion; emerging adoption favors Integrated column-rack consolidation per OEM packaging density requirements.
Technology:
Cost tier differentiation separates commodity motor suppliers from premium system integrators commanding higher margins through software-defined functionality.
- Brushless DC:Permanent-magnet synchronous motors eliminate brush friction losses while enabling precise torque control through field-oriented commutation. Japanese tier-one suppliers anchor high-volume contracts with domestic OEMs using neodymium-iron-boron magnet configurations optimized for thermal efficiency. Rare earth price volatility from Chinese export quotas compresses margins when contract pricing locks ahead of material spikes.
- Steer-by-Wire:Fully electronic steering pathways replace mechanical linkages with redundant torque sensors and backup power architectures. Japan's METI JIS fail-safe protocols extend validation timelines, favoring incumbent suppliers with existing certification infrastructure. The technology enables variable steering ratios and cabin packaging freedom for premium electric vehicle platforms.
- Servo Motor:Brushed DC alternatives persist in commercial vehicle applications where cost sensitivity outweighs efficiency premiums.
- Integrated Systems:Motor-controller-sensor consolidation into single housings reduces OEM assembly steps and wiring complexity.
Brushless DC captures the steepest expansion trajectory as China's MIIT dual carbon goals accelerate NEV platform rollouts; Steer-by-Wire climbs fastest in premium segments where software differentiation commands pricing power.
End User:
Application maturity varies sharply across customer types, with regulatory intensity shaping procurement patterns for aerospace versus automotive volumes.
- Automotive OEMs:Original equipment manufacturers specify EPS architectures during platform development, locking suppliers into multi-year contracts with embedded software validation cycles. Chinese OEMs in the Shanghai-Jiangsu-Zhejiang cluster demand 48V mild-hybrid compatibility for next-generation C-segment vehicles. ISO 26262 functional safety certification stretches 18-24 months for new control modules.
- Commercial Vehicles:Heavy-duty truck operators in Southeast Asia retain hydraulic steering for extreme load conditions where electric alternatives face thermal management penalties. Payload requirements and duty cycle severity limit EPS penetration below passenger car adoption rates.
- Aftermarket Providers:Independent workshops in India and Southeast Asia acquire diagnostic tools for torque sensor recalibration, fragmenting traditional dealer-channel dependency.
- Aerospace:Aircraft steering systems demand redundant fail-safe architectures with MIL-STD-810 environmental qualification, serving niche volumes with extreme reliability requirements.
Automotive OEMs concentrate procurement scale; Aftermarket Providers gain share fastest as encrypted software locks route warranty claims through authorized channels.
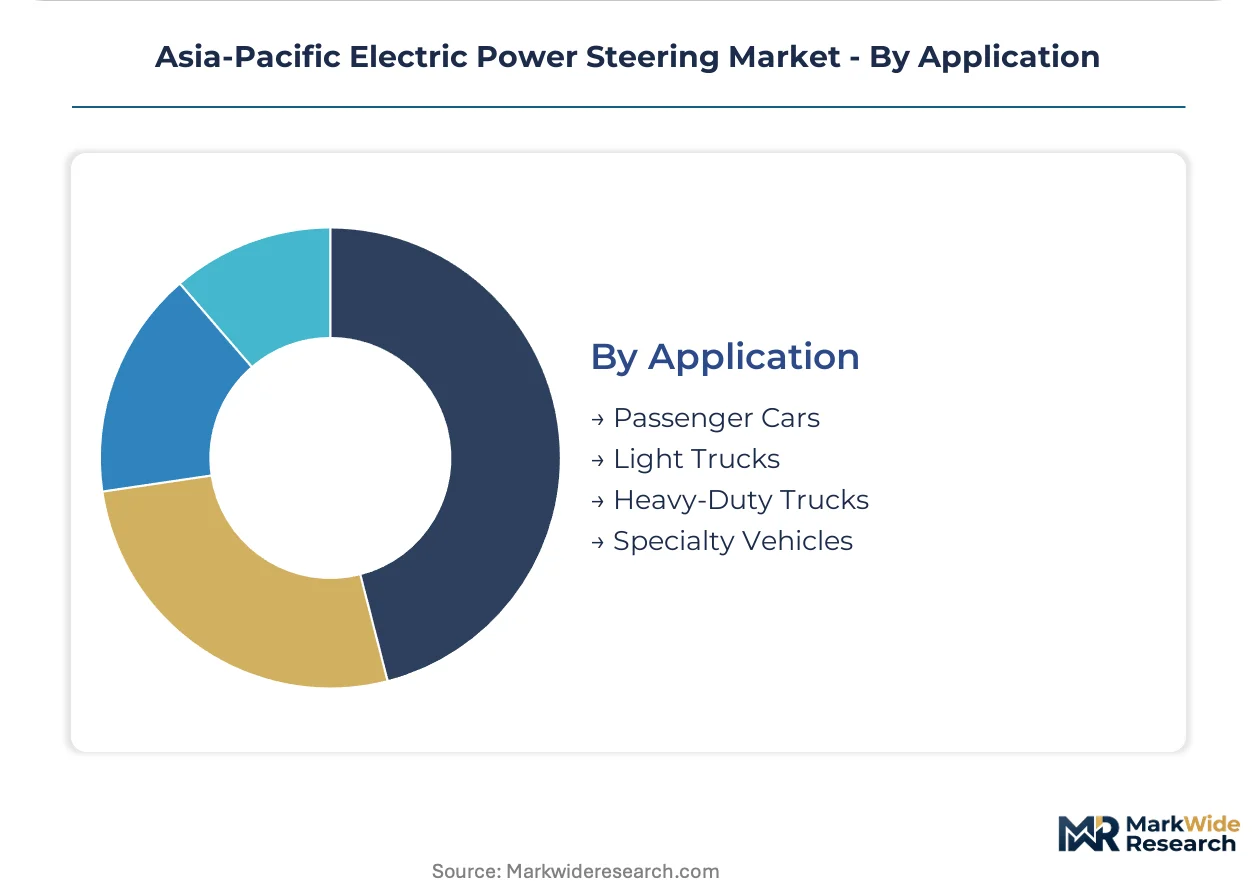
Application:
Customer type and duty cycle severity segment demand between urban mobility platforms and load-bearing commercial architectures.
- Passenger Cars:Front-wheel-drive architectures dominate Asia-Pacific volumes, with rack-and-pinion configurations standard across Japanese, Korean, and Chinese OEM lineups. India's BIS mandates electromagnetic compatibility testing for imported steering electronics, shaping local assembly decisions. Three to five percent fuel consumption reduction versus hydraulic systems drives MIIT compliance submissions.
- Heavy-Duty Trucks:Extreme steering loads and continuous duty cycles favor hydraulic assist in Southeast Asian mining and logistics fleets. Electric alternatives carry copper weight penalties and battery thermal management complexity that erode payload capacity.
- Light Trucks:Mid-duty commercial applications in urban delivery segments adopt column-assist EPS for maneuverability in dense traffic corridors.
- Specialty Vehicles:Agricultural and construction equipment requires sealed enclosures against dust and moisture ingress, with custom torque profiles for low-speed precision.
Passenger Cars anchor volume concentration; Light Trucks expand most quickly as urban logistics electrification accelerates across Chinese and Indian metro corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision steering components to assembly plants across Southeast Asia, while China manufactures complete rack-and-pinion systems for domestic OEMs and Korean vehicle platforms. This trade-flow corridor shapes procurement patterns as tier-one suppliers position production within 200 kilometers of major vehicle assembly hubs.
China
MIIT dual carbon goals accelerate NEV platform rollouts requiring higher-efficiency motor designs. GB standards for new energy vehicle steering efficiency exceed prior internal combustion benchmarks. The Shanghai-Jiangsu-Zhejiang manufacturing corridor concentrates tier-one steering system production serving Japanese and Korean OEM assembly plants.
Japan
METI coordinates JIS standards for steer-by-wire fail-safe protocols extending validation timelines. Domestic OEMs anchor high-volume rack-and-pinion contracts with precision torque sensor requirements. The Kanto region around Tokyo hosts integrated column-assist production facilities supplying regional export markets.
India
BIS mandates electromagnetic compatibility testing for imported steering electronics, reshaping local assembly decisions. The PLI scheme for automotive components draws controller manufacturing investment away from import-dependent configurations. Maharashtra and Tamil Nadu automotive clusters localize column-assist EPS production for entry-level passenger segments.
South Korea
OEMs specify 48V mild-hybrid compatibility for next-generation C-segment vehicle platforms. Higher voltage architectures enable heavier assist torque without copper weight penalties. The Seoul Capital Area anchors system integration facilities serving domestic brands and export markets.
Thailand
Commercial vehicle segments retain hydraulic steering for extreme load conditions in mining and logistics fleets. Electric alternatives face thermal management penalties that erode payload capacity. The Eastern Economic Corridor concentrates Japanese OEM assembly plants sourcing steering systems from regional suppliers.
Asia-Pacific Electric Power Steering Market Competitive Environment
On the supply side, the industry is consolidating around integrated system architectures that combine motor, controller, and sensor arrays into single housings. Tier-one suppliers with existing certification infrastructure capture premium positioning as OEMs pursue packaging density. Three strategic archetypes dominate: Japanese precision manufacturers with JIS validation capabilities, German modular system integrators, and Korean scale-driven suppliers. Competitive moves center on capacity expansion in China's eastern manufacturing corridor and strategic partnerships for 48V mild-hybrid platform access.
Within the precision-manufacturing tier, JTEKT Corporation and NSK Ltd. represent integrated production capabilities across Japan and China. ZF Friedrichshafen AG exemplifies modular system architecture spanning passenger and commercial applications. These three anchors sit within distinct competitive vectors—JTEKT leverages regional supply chain integration, NSK occupies high-volume domestic OEM relationships, and ZF commands cross-segment technology transfer.
| Leading Market Players |
|---|
| JTEKT Corporation |
| NSK Ltd. |
| Nexteer Automotive |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Denso Corporation |
| HL Mando Corporation |
| Hyundai Mobis |
| Zhejiang Shibao Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo maritime corridor carries rare earth magnets and precision-machined steering components across the East China Sea, with freight cost volatility amplifying both supplier concentration in China's eastern manufacturing belt and the three-tier pricing spread between integrated steer-by-wire systems, brushless DC rack-and-pinion units, and commodity column-assist configurations.
Pricing Analysis
Next-generation steer-by-wire architectures command substantial premiums over incumbent brushless DC rack-and-pinion systems, while brushed DC servo motors in commercial vehicle applications occupy the economy tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under Japan's METI JIS protocols and ISO 26262 functional safety tiers. Cost compression in the standard tier is intensifying because Chinese OEMs are consolidating procurement volumes around 48V mild-hybrid compatible platforms. Southeast Asian commercial vehicle operators exhibit highest price sensitivity, while Japanese and Korean OEMs purchasing for premium electric vehicle platforms demonstrate lowest sensitivity to unit pricing.
Supply Chain Analysis
Tariff exposure between China and Japan dominates supply chain risk calculations for neodymium-iron-boron magnet sourcing. Manufacturing concentrates in China, Japan, and South Korea, with the Shanghai-Jiangsu-Zhejiang cluster feeding Japanese and Korean OEM assembly plants. Raw material flows draw from Chinese rare earth processing facilities, Japanese precision torque sensor foundries, and Korean copper winding operations. Single-source vulnerability persists for high-grade permanent magnets subject to Chinese export quota administration. Distribution runs through tier-one supplier direct-to-OEM contracts, with limited aftermarket penetration outside authorized dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are expanding as India's PLI scheme and China's MIIT efficiency mandates create divergent compliance requirements that favor specialized suppliers over universal system integrators.
For Market Incumbents: Pre-empt margin erosion in standard rack-and-pinion segments by securing backward integration into rare earth magnet supply through offtake agreements with Chinese processors. Defend positioning in Japan's steer-by-wire validation pipeline by accelerating METI JIS certification investments ahead of competitor submissions. Channel control through encrypted software locks on torque sensor recalibration tools protects aftermarket revenue streams against independent workshop encroachment. For New Entrants and Emerging Players: Establish a beachhead in India's column-assist EPS segment by partnering with Maharashtra and Tamil Nadu automotive clusters for PLI-compliant local assembly. Target electromagnetic compatibility testing services as a compliance-margin capture opportunity under BIS mandates for imported steering electronics. Pursue white-label controller manufacturing for Chinese tier-two suppliers seeking to avoid MIIT efficiency certification delays on foreign-sourced power control modules. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive steering component divisions lacking standalone scale to justify continued R&D investment. Long-term viability favors suppliers with demonstrated ISO 26262 certification infrastructure and existing relationships with Japanese OEM platform engineering teams. Watch for inflection when China's GB standards evolution mandates steer-by-wire fail-safe architectures across mass-market NEV platforms, compressing validation timelines for uncertified entrants.| Strategic Initiative | Industry Significance |
|---|---|
| 48V Mild-Hybrid Platform Integration | Korean and Japanese OEM specifications for C-segment vehicles drive higher-voltage motor controller demand. |
| Backward Integration into Rare Earth Processing | Neodymium-iron-boron magnet supply security insulates margins from Chinese export quota volatility. |
| Steer-by-Wire Fail-Safe Certification | METI JIS protocol compliance opens premium electric vehicle platform procurement at Japanese OEMs. |
| PLI-Compliant Local Assembly in India | Maharashtra and Tamil Nadu cluster investment captures BIS electromagnetic compatibility testing margin. |
| Software-Defined Steering Calibration | Encrypted torque sensor recalibration tools route warranty claims through authorized channels against aftermarket fragmentation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs and trade flow records, and regulatory filings with China's MIIT and Japan's METI. Primary interviews engaged Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers across the Asia-Pacific region. Secondary validation drew from SEC filings of listed automotive component manufacturers, production capacity disclosures, and patent filings related to brushless DC motor and steer-by-wire architectures. Bottom-up unit volume estimates triangulate against top-down market value reconstructions.
Forecast inputs span vehicle class segmentation, propulsion architecture differentiation, content per vehicle trajectories, OEM tier stratification, and regional production cluster concentration across the projection horizon. The analytical framework models rack-and-pinion, column-assist, and integrated system architectures separately, with voltage protocol splits between 12V conventional, 12V enhanced, and 48V mild-hybrid configurations. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory mandate acceleration effects. Industry-specific inputs include MIIT dual carbon goal implementation timelines and BIS electromagnetic compatibility enforcement phases.
Stress conditions across rare earth magnet price volatility, steer-by-wire validation timeline extensions, and PLI scheme incentive modifications were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM platform rollout schedules and supplier certification progressions. Macroeconomic contraction, regulatory enforcement delays, or breakthrough solid-state steering actuator technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Traffic Control Products Market
Automotive Parts
Automotive Propeller Shaft Couplings Market