
 Mexico Automotive Air Filters Market | 2026-2036
Mexico Automotive Air Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Air Filters Market Insights
Asset-light leasing models for filter manufacturing equipment are reshaping competitive entry in Mexico's automotive supply base. Mann+Hummel Group leverages its captive pleated paper capacity to anchor OEM contracts with major assemblers in Querétaro. Donaldson Company specializes in heavy-duty engine air filtration for commercial vehicle producers operating near Saltillo. Robert Bosch GmbH extends its channel control through direct distribution to independent aftermarket workshops across Mexico City and Monterrey.
Mexico automotive air filters are replaceable porous media components engineered to remove particulate contaminants from intake air streams, with pleated paper and synthetic fiber constructions rated for ISO 5011 filtration efficiency and dust-holding capacity. These components protect internal combustion engines and cabin environments from abrasive wear and respiratory hazards. Engine air filters lead volume demand due to mandatory replacement intervals tied to OEM service schedules, while HEPA and activated carbon cabin filters capture the fastest expansion as consumer awareness of in-cabin air quality rises. Aftermarket providers occupy the deepest margin pools through branded premium positioning and direct-to-workshop distribution networks.
NOM-042-SEMARNAT-2003 emission standards and NOM-163-SEMARNAT-2012 particulate limits enforce minimum filtration efficiency for vehicles operating in Mexican metropolitan zones. The Secretariat of Environment and Natural Resources coordinates with PROFECO consumer protection standards to regulate aftermarket filter labeling and performance claims. Stakeholders must monitor alignment between incoming EPA Tier 3-equivalent protocols and Mexico's domestic rulemaking timeline to anticipate product recertification obligations.
Market Dynamics
Light commercial vehicle fleet expansion across Guanajuato and Puebla is compressing filter replacement cycles while NOM environmental standards tighten filtration performance thresholds, forcing suppliers to recalibrate product portfolios for OEM compliance.
Growth Catalysts
- NOM-163-SEMARNAT-2012 particulate limits:Metropolitan emission zones mandate higher-efficiency media, pulling premium pleated paper and synthetic fiber upgrades into the replacement cycle.
- HEPA cabin filtration:Consumer awareness of in-cabin respiratory hazards accelerates specification of activated carbon composites in aftermarket channels serving Mexico City and Monterrey workshops.
- Bajío automotive corridor concentration:Assembly plant clustering in Querétaro creates captive demand pull for localized filter supply contracts with compressed logistics lead times.
Market Restraints
- Pulp and synthetic fiber input volatility:Raw material cost swings compress margin buffers for filter media converters operating without captive paper production.
- Single-source pleated paper dependence:Guanajuato-based OEM suppliers face concentration risk when primary media sources experience capacity constraints or quality deviations.
- Extended service interval engineering:Engine air filter durability improvements in newer powertrains reduce per-vehicle replacement frequency, compressing aftermarket volume potential.
Strategic Opportunities
- Saltillo heavy-duty commercial hub:Underpenetrated heavy-duty engine filtration demand among regional truck assemblers offers white space for specialized high-dust-capacity product lines.
- Direct-to-workshop digital platforms:Independent aftermarket distributors in Monterrey bypass traditional wholesale tiers through mobile-enabled inventory replenishment systems.
- EPA Tier 3-equivalent protocol alignment:Anticipatory recertification investments position suppliers for accelerated OEM approval when domestic rulemaking converges with US emission benchmarks.
Industry Challenges
- ISO 5011 testing infrastructure scarcity:Limited accredited laboratories in Mexico delay product validation timelines for new media formulations seeking OEM qualification.
- PROFECO labeling compliance complexity:Evolving consumer protection standards for aftermarket performance claims require dedicated regulatory affairs capacity that smaller converters lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Air Filters Market |
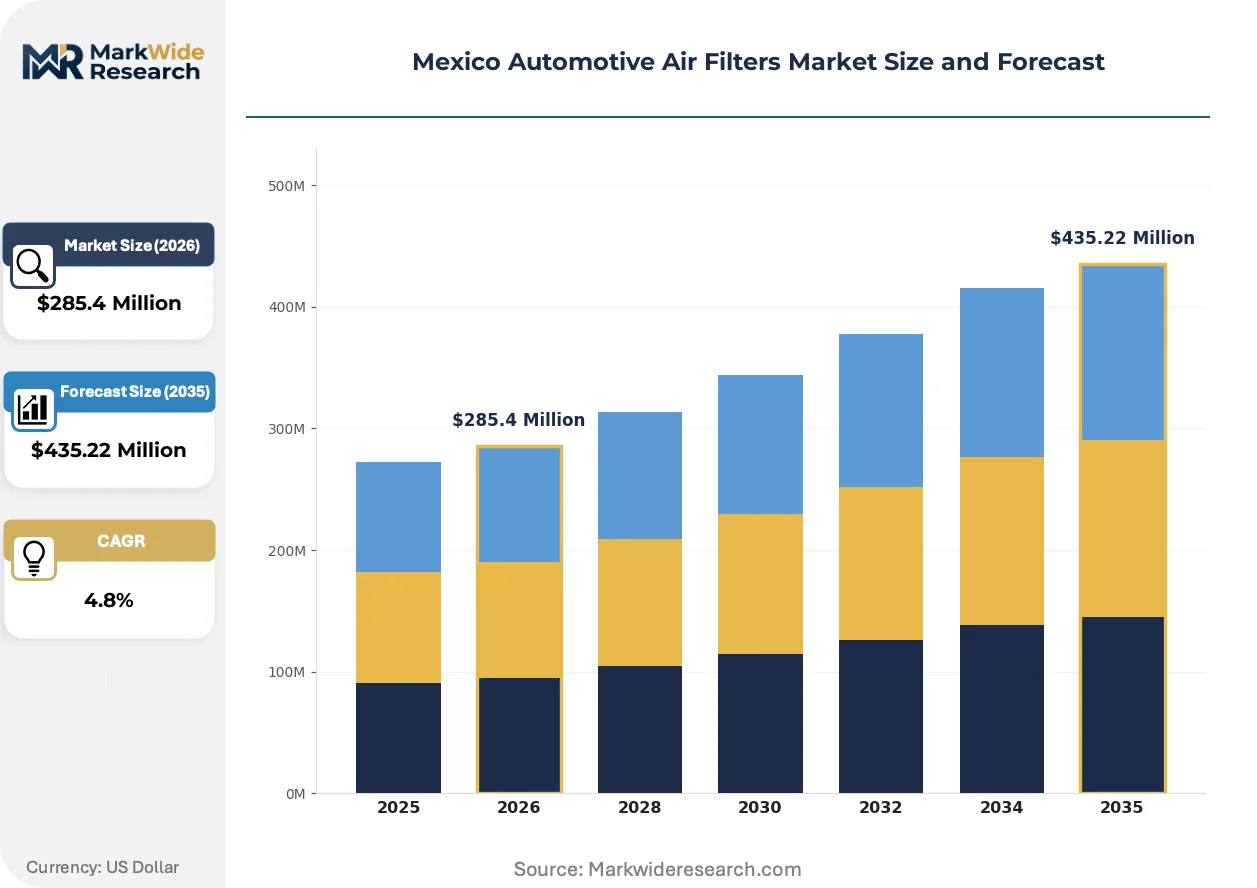
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabin Air Filters, Engine Air Filters, Fuel Filters, Oil Filters End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: HEPA, Activated Carbon, Electrostatic, Foam Material: Pleated Paper, Synthetic Fiber, Metal Mesh, Others |
| Companies Covered | Denso Corporation, K&N Engineering, Inc., Mann+Hummel Group, Purolator Filters LLC, Valeo S.A., Donaldson Company, Inc., Robert Bosch GmbH, Cummins Inc., MAHLE GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Air Filters Market Trends and Innovations
Sensor-integrated filtration systems and predictive maintenance platforms are rewiring how filter life is monitored and monetized, shifting value capture from physical replacement toward data-enabled service models.
Pleated nanofiber media engineered for sub-micron particle capture is digitizing how OEMs manage warranty exposure and service scheduling. Major assemblers in the Bajío corridor embed pressure-differential sensors that stream clogging data to fleet management dashboards. This connectivity compresses unplanned downtime risk while creating recurring software revenue streams that offset commodity filter margin erosion.
NOM-042-SEMARNAT-2003 emission standards are tightening enforcement protocols for vehicle inspection programs in Mexican metropolitan zones. The Secretariat of Environment and Natural Resources coordinates with state-level verification centers to mandate documented filtration efficiency for registration renewal. Heavy-duty commercial operators in Puebla face the steepest compliance burden, accelerating adoption of high-capacity primary and safety-stage filter configurations.
Fleet procurement teams are consolidating supplier relationships around integrated air and cabin filtration contracts with performance guarantees. Direct distribution networks serving independent workshops in Mexico City displace traditional three-tier wholesale structures. This channel compression is most visible among light commercial vehicle operators seeking single-source accountability for both engine protection and cabin air quality outcomes.
Mexico Automotive Air Filters Market Segmentation
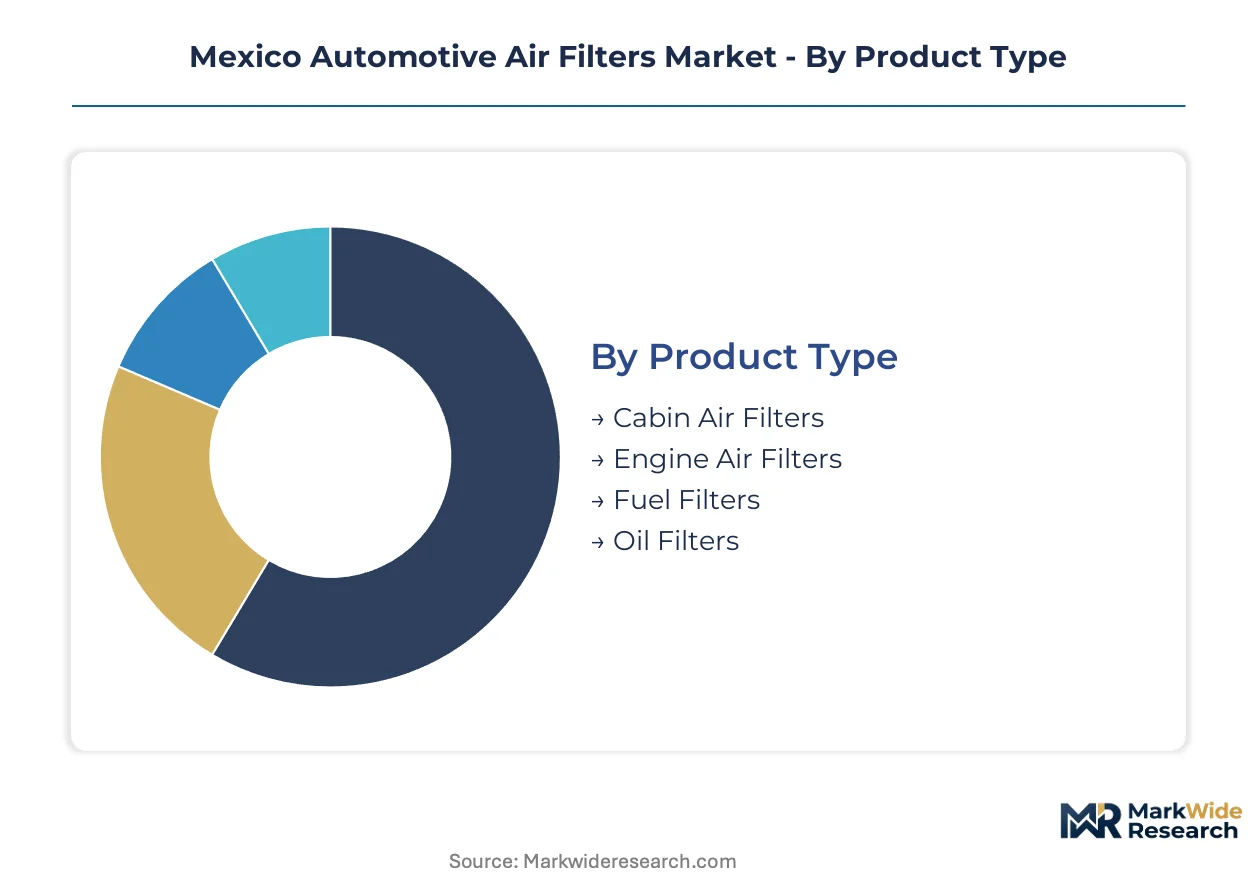
Segmentation in Mexico's automotive air filters market reveals divergent replacement economics across product categories, with cycle times ranging from annual cabin filter swaps to extended-interval engine filtration. Understanding these temporal patterns shapes inventory positioning and margin capture strategies for suppliers serving the Bajío corridor.
Product Type:
Engine air filters turn over fastest at standard OEM service intervals, while cabin filtration cycles compress further in high-dust metropolitan environments.
- Engine Air Filters:Pleated paper and synthetic fiber media engineered for ISO 5011 dust-holding capacity protect intake systems from abrasive wear. Demand concentrates among OEM supply contracts serving assembly plants in Querétaro and Guanajuato, where mandatory replacement schedules drive predictable volume. NOM-163-SEMARNAT-2012 particulate limits force media upgrades that shorten effective service life in metropolitan verification zones.
- Cabin Air Filters:HEPA and activated carbon composites capture particulate and gaseous contaminants for occupant respiratory protection. Replacement cycles compress in Mexico City and Monterrey workshops as consumer awareness of in-cabin air quality rises, pulling premium media specifications into the aftermarket.
- Fuel Filters:Multi-stage filtration systems protect precision fuel injection components from water and particulate contamination.
- Oil Filters:Full-flow and bypass configurations extend powertrain longevity through contaminant removal from lubrication circuits.
Engine air filters anchor the volume base while cabin air filters gain share at the steepest rate.
End User:
Cost tier differentiation separates captive OEM supply relationships from margin-rich aftermarket distribution channels.
- OEMs:Original equipment manufacturers specify filtration systems during vehicle platform development, locking in multi-year supply agreements with validated media converters. Querétaro-based assemblers demand localized production to satisfy just-in-sequence delivery requirements.
- Aftermarket Providers:Independent distributors and workshop networks capture the deepest margin pools through branded premium positioning and direct-to-workshop replenishment systems. Monterrey-based digital platforms are bypassing traditional wholesale tiers.
- Vehicle Assemblers:Bajío corridor production facilities consolidate procurement around integrated air and cabin filtration contracts with performance guarantees.
- Tier-1 Suppliers:System integrators manage sub-assembly filtration modules for powertrain and HVAC integration.
Aftermarket providers command the highest margin tier while OEM relationships deliver volume stability.
Technology:
Application requirements dictate technology selection, with respiratory protection applications demanding superior particle capture efficiency.
- HEPA:High-efficiency particulate air media rated for sub-micron capture addresses NOM environmental compliance and consumer health concerns. Specification accelerates in cabin filtration for light commercial fleets operating across Puebla and Mexico City metropolitan zones.
- Activated Carbon:Adsorptive media layers neutralize volatile organic compounds and NOx ingress. Demand climbs fastest among premium vehicle segments and urban fleet operators prioritizing occupant comfort.
- Electrostatic:Charge-enhanced fiber matrices improve particle capture without flow restriction penalties.
- Foam:Reticulated polyurethane structures serve pre-filtration and coarse dust applications in heavy-duty commercial environments.
HEPA technology dominates cabin air specifications while activated carbon composites expand most quickly in premium applications.
Material:
Supply concentration around captive paper production creates cost tier stratification between integrated and non-integrated converters.
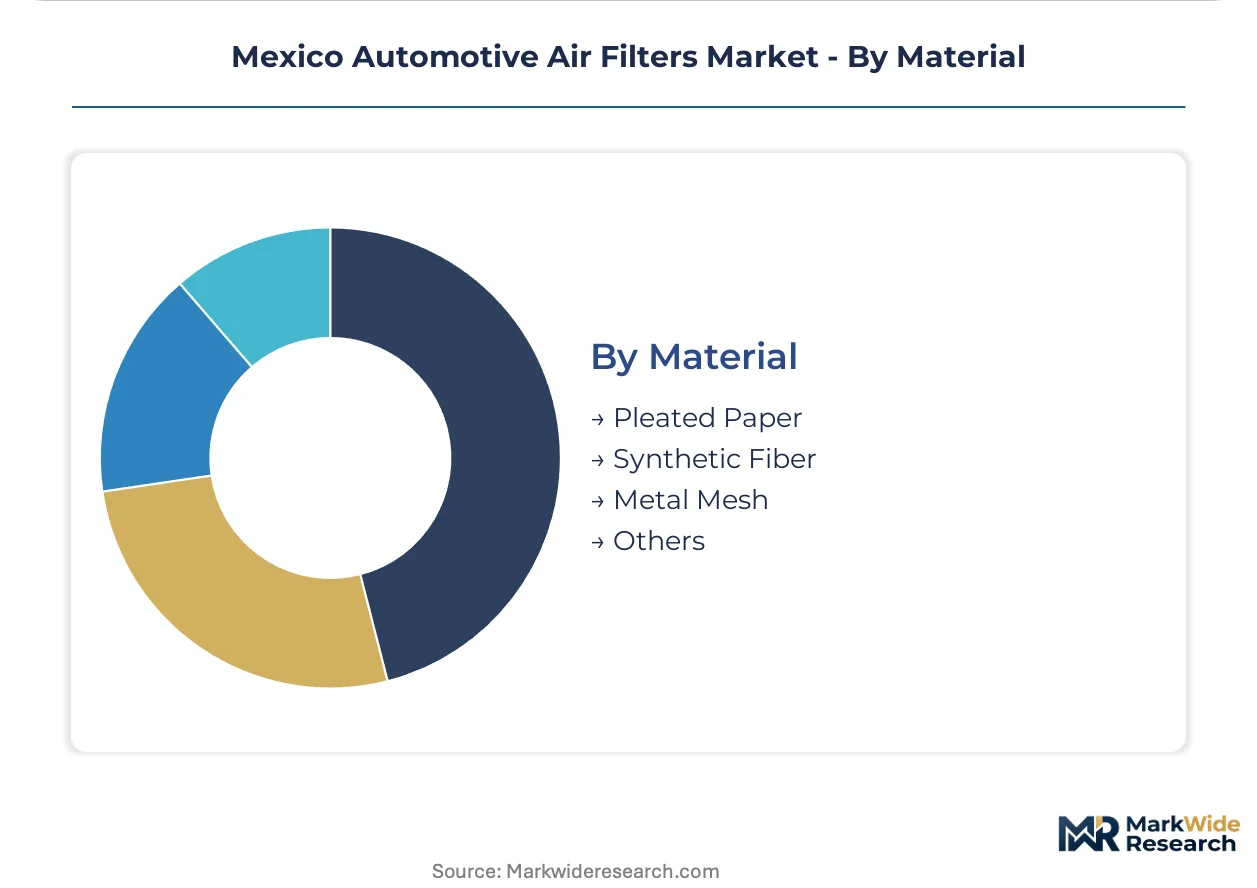
- Pleated Paper:Cellulose and synthetic-blend media formed into multi-layer configurations deliver calibrated filtration efficiency and dust-holding capacity. Mann+Hummel Group's captive capacity anchors OEM contract competitiveness in Querétaro supply relationships.
- Synthetic Fiber:Melt-blown and spun-bond polymer matrices engineered for extended service intervals and moisture resistance. Saltillo heavy-duty commercial producers specify synthetic media for high-dust operating environments.
- Metal Mesh:Stainless steel and aluminum screens provide cleanable, reusable pre-filtration for industrial and off-highway applications.
- Others:Composite and nanofiber formulations emerging from ISO 5011 validation pipelines.
Pleated paper holds the volume foundation while synthetic fiber media climbs fastest in heavy-duty and extended-service applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NOM-163-SEMARNAT-2012 particulate limits and EPA Tier 3-equivalent protocol alignment are reshaping demand geography across Mexican sub-regions, with assembly plant clustering and fleet density determining filter procurement intensity.
Bajío Region
Querétaro and Guanajuato assembly corridors concentrate OEM supply contracts for engine air filtration, with just-in-sequence delivery requirements pulling localized production capacity. NOM environmental verification centers in León enforce documented filtration efficiency for commercial fleet registration. Mann+Hummel Group anchors pleated paper supply relationships with major assemblers operating across this corridor.
Nuevo León
Saltillo heavy-duty commercial vehicle producers generate specialized demand for high-dust-capacity engine filtration systems. The state's proximity to Texas border logistics amplifies cross-border fleet procurement patterns. Donaldson Company occupies position among fabricators serving regional truck assemblers with extended-service-interval media specifications.
Mexico City Metro
Metropolitan emission verification programs compress cabin filter replacement cycles as consumer awareness of respiratory protection climbs. PROFECO labeling enforcement creates compliance complexity for aftermarket distributors serving independent workshops. Direct-to-workshop digital platforms bypass traditional wholesale tiers in this high-density service market.
Jalisco
Guadalajara automotive supplier parks feed components to Bajío assembly plants, with filter media converters locating near OEM logistics nodes. State-level environmental agencies coordinate with federal SEMARNAT protocols on vehicle inspection standardization. Synthetic fiber media demand accelerates among converters seeking moisture-resistant formulations for regional climate conditions.
Northern Border States
Chihuahua and Coahuila maquiladora operations export filtration subassemblies under USMCA trade provisions, linking Mexican production to US EPA certification requirements. Cross-border supply chains integrate ISO 5011 testing validation from accredited US laboratories. Cummins Inc. and MAHLE GmbH exemplify multinational fabricators leveraging this binational production architecture.
Mexico Automotive Air Filters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Mexico's automotive air filters market, creating a tiered structure where captive OEM relationships coexist with margin-rich aftermarket distribution. German and Japanese multinational suppliers anchor premium-tier supply contracts through validated media technology and localized production presence. US-based heavy-duty specialists occupy differentiated positions in commercial vehicle filtration. Strategic moves concentrate on backward integration into pleated paper production, direct-to-workshop digital platform deployment, and anticipatory recertification investments for emission protocol convergence.
Among Germany-based fabricators, Mann+Hummel Group and Robert Bosch GmbH exemplify channel-controlling archetypes through OEM supply relationships and aftermarket distribution networks. Denso Corporation represents Japanese multinational positioning with integrated powertrain component supply. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across Mexico's Bajío corridor and metropolitan service markets.
| Leading Market Players |
|---|
| Denso Corporation |
| K&N Engineering, Inc. |
| Mann+Hummel Group |
| Purolator Filters LLC |
| Valeo S.A. |
| Donaldson Company, Inc. |
| Robert Bosch GmbH |
| Cummins Inc. |
| MAHLE GmbH |
| Others |
Pricing and Supply Chain Analysis
The Bajío automotive corridor's just-in-sequence logistics networks transmit pulp and synthetic fiber cost volatility directly into OEM contract pricing, concentrating margin pressure on non-integrated converters while rewarding captive paper producers with pricing power over aftermarket distributors.
Pricing Analysis
ISO 5011 certification grade creates the primary spread between premium OEM supply contracts and economy aftermarket tiers. Pricing stratifies across validated media specifications, standard pleated paper replacements, and unbranded economy alternatives. Cost compression in the economy tier is intensifying because Guanajuato-based converters face single-source pulp dependencies. Fleet procurement teams demonstrate lowest price sensitivity, while independent Mexico City workshops exhibit highest elasticity to branded premiums.
Supply Chain Analysis
Pulp feedstock from US Southeast timber operations and synthetic fiber from Gulf Coast petrochemical complexes anchor Mexico's media conversion base. The supply chain draws from cellulose suppliers in Canada, melt-blown polymer producers in the United States, and specialty nanofiber developers in Germany. Single-source pleated paper vulnerability concentrates risk among OEM suppliers lacking backward integration. Distribution runs through direct-to-workshop digital platforms that bypass traditional wholesale tiers in Monterrey and Mexico City metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
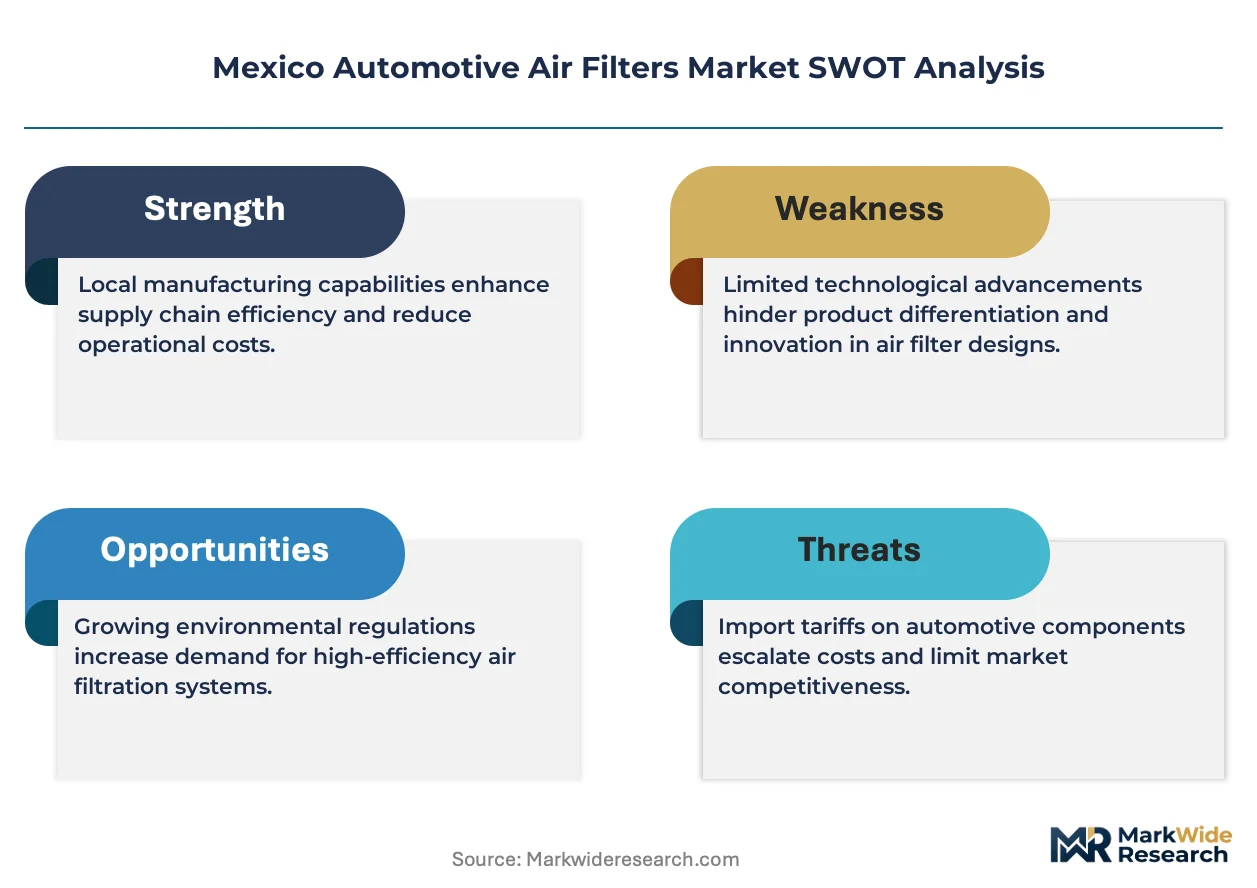
This market functions as a defensive-moat structure where NOM regulatory entrenchment and ISO 5011 validation requirements create switching costs that protect incumbent positions from commodity substitution.
For Market Incumbents: Entrench position through captive pleated paper capacity expansion in Querétaro to secure just-in-sequence OEM contracts against emerging synthetic fiber substitutes. Deepen regulatory affairs capabilities to navigate PROFECO labeling complexity and anticipate EPA Tier 3-equivalent recertification timelines.
For New Entrants and Emerging Players: Saltillo heavy-duty commercial vehicle filtration presents the most penetrable white space, with regional truck assemblers seeking specialized high-dust-capacity configurations underserved by incumbent portfolios. Target digital platform partnerships with independent Monterrey workshops to establish direct distribution footholds without wholesale tier investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational automotive component parents seeking to divest non-core filtration divisions lacking vertical integration. Long-term viability hinges on regulatory alignment capabilities rather than commodity scale. Watch for NOM-163 enforcement acceleration in Puebla and Mexico City as the inflection signal for premium media demand step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pleated Paper Production | Mann+Hummel Group's captive capacity anchors OEM competitiveness in Querétaro supply relationships. |
| Direct-to-Workshop Digital Platform Deployment | Monterrey-based distributors bypass wholesale tiers through mobile-enabled inventory replenishment systems. |
| ISO 5011 Recertification Investment | Anticipatory validation positions suppliers for accelerated OEM approval when NOM standards converge with EPA benchmarks. |
| Saltillo Heavy-Duty Capacity Expansion | Regional truck assemblers generate specialized demand for high-dust-capacity engine filtration configurations. |
| Sensor-Integrated Filtration System Development | Bajío corridor assemblers embed pressure-differential sensors that stream clogging data to fleet management dashboards. |
Research Methodology
A standing panel of OEM platform engineers, aftermarket distributor operations heads, and SEMARNAT regulatory affairs specialists provided ongoing calibration across primary interview rounds, with secondary validation drawing from vehicle production databases, NOM filing records, and customs trade documentation. Bottom-up volume triangulation from assembly plant procurement data converged with top-down market sizing from filter media consumption metrics.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning engine versus cabin filtration, OEM versus aftermarket channel economics, and pleated paper versus synthetic fiber material trajectories. CAGRs derived from replacement cycle compression rates and fleet expansion patterns in Guanajuato and Puebla, cross-referenced against NOM enforcement intensity gradients across metropolitan verification zones.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by synthetic fiber specialists or accelerated EPA Tier 3-equivalent rulemaking would shift outcomes beyond modeled ranges. Cross-checking against IHS Markit vehicle registration data and SEMARNAT verification center throughput statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Drum Brake Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Car Rack Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
Air Suspension Systems Market