
 Bus Transmission System Market | 2026-2036
Bus Transmission System Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Transmission System Market Analytics
Euro VI and EPA 2010-compliant transmission specifications is unwinding legacy mechanical dominance across the bus transmission system landscape. ZF Friedrichshafen AG leverages its integrated torque converter manufacturing to anchor premium automatic supply contracts with European OEMs. Allison Transmission Holdings Inc. sustains its position through hydraulic hybrid technology leadership in North American transit applications. Voith GmbH dominates German-speaking markets with its DIWA automated transmission platform engineered for stop-and-go urban duty cycles.
A bus transmission system is an integrated powertrain assembly comprising a torque converter, multi-speed gearbox, and electronic control unit that modulates engine output to drive wheels across variable load conditions. The assembly typically manages torque ranges from 1,000 to 3,000 Nm and operates at thermal loads exceeding 120°C during peak urban cycles. Automatic transmission configurations command the largest installed base among public transport buses where driver fatigue reduction and fuel efficiency targets converge. Electro-mechanical technology represents the fastest-expanding category as fleet operators pursue predictive maintenance capabilities and real-time shift optimization. Manual transmission retains residual share in emerging-market school bus segments where first-cost sensitivity overrides operational efficiency priorities.
The EPA and NHTSA jointly enforce greenhouse gas standards that compel transmission efficiency improvements in US heavy-duty bus platforms. The EU Green Deal and ECHA REACH framework restrict hazardous substances in transmission fluids while mandating lifecycle recyclability for clutch assemblies. China's MIIT issues GB standards that specify durability testing protocols for automated mechanical transmissions in municipal fleets. Stakeholders must monitor how divergent regional compliance timelines reshape component sourcing strategies and technology roadmaps across their manufacturing footprints.
Market Dynamics
Electrification mandates from the EU Green Deal and China's MIIT GB standards are compressing demand for legacy mechanical transmissions while expanding procurement of automated and electro-mechanical alternatives across municipal fleet operators.
Growth Catalysts
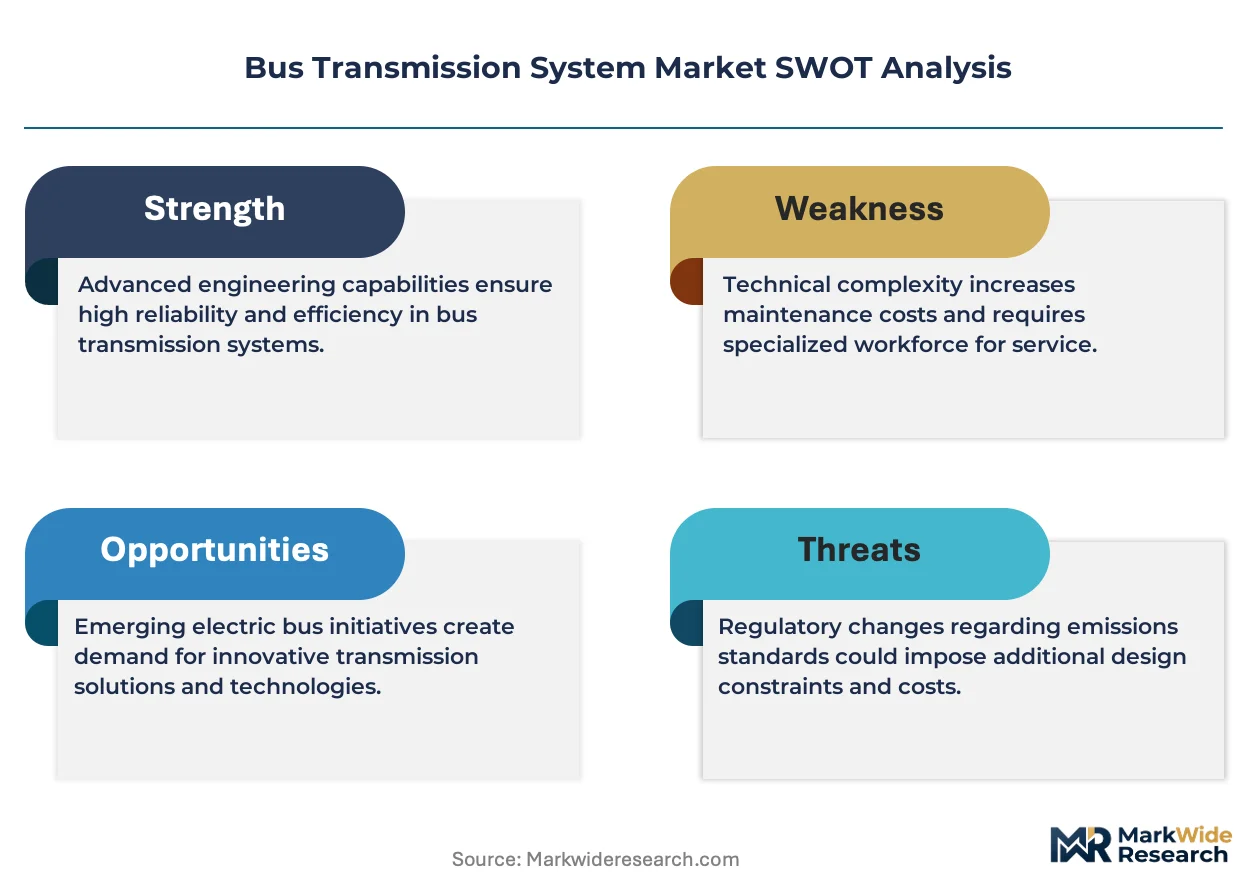
- EU Green Deal electrification timelines:Municipal transit authorities in Germany, France, and the Netherlands must phase out pure diesel buses by 2030, accelerating hybrid-compatible transmission procurement.
- China's state-backed fleet modernization:MIIT durability protocols for automated mechanical transmissions are driving replacement of aging mechanical systems in tier-one city bus networks.
- Urban duty cycle optimization:Stop-and-go municipal routes favor torque converter automation that reduces driver fatigue and improves fuel efficiency versus manual alternatives.
Market Restraints
- Rare earth magnet cost volatility:Electro-mechanical transmission production depends on neodymium and dysprosium supply concentrated in Chinese processing facilities, creating input price uncertainty.
- Technical integration barriers:Legacy bus chassis architectures require substantial redesign to accommodate the thermal management and packaging demands of automated electro-mechanical systems.
- First-cost sensitivity in emerging markets:School bus operators in India and Southeast Asia prioritize mechanical transmission procurement due to lower upfront capital requirements.
Strategic Opportunities
- India's FAME-II subsidy extension:The country's electric mobility incentive scheme creates procurement pull for hybrid transmission systems in state transport corporation tenders.
- Predictive maintenance convergence:Integration of IoT sensors with transmission control units enables real-time health monitoring and shift optimization for fleet operators.
- Aftermarket service unbundling:Independent service networks are emerging as a new channel for transmission refurbishment and remanufacturing outside OEM captive distribution.
Industry Challenges
- Electro-mechanical engineering talent scarcity:The specialized skill set combining mechanical gearbox design with power electronics control is concentrated among a limited pool of experienced engineers.
- EPA and NHTSA compliance timeline compression:Greenhouse gas standard phase-ins require transmission efficiency improvements faster than typical product development cycles can accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Transmission System Market |
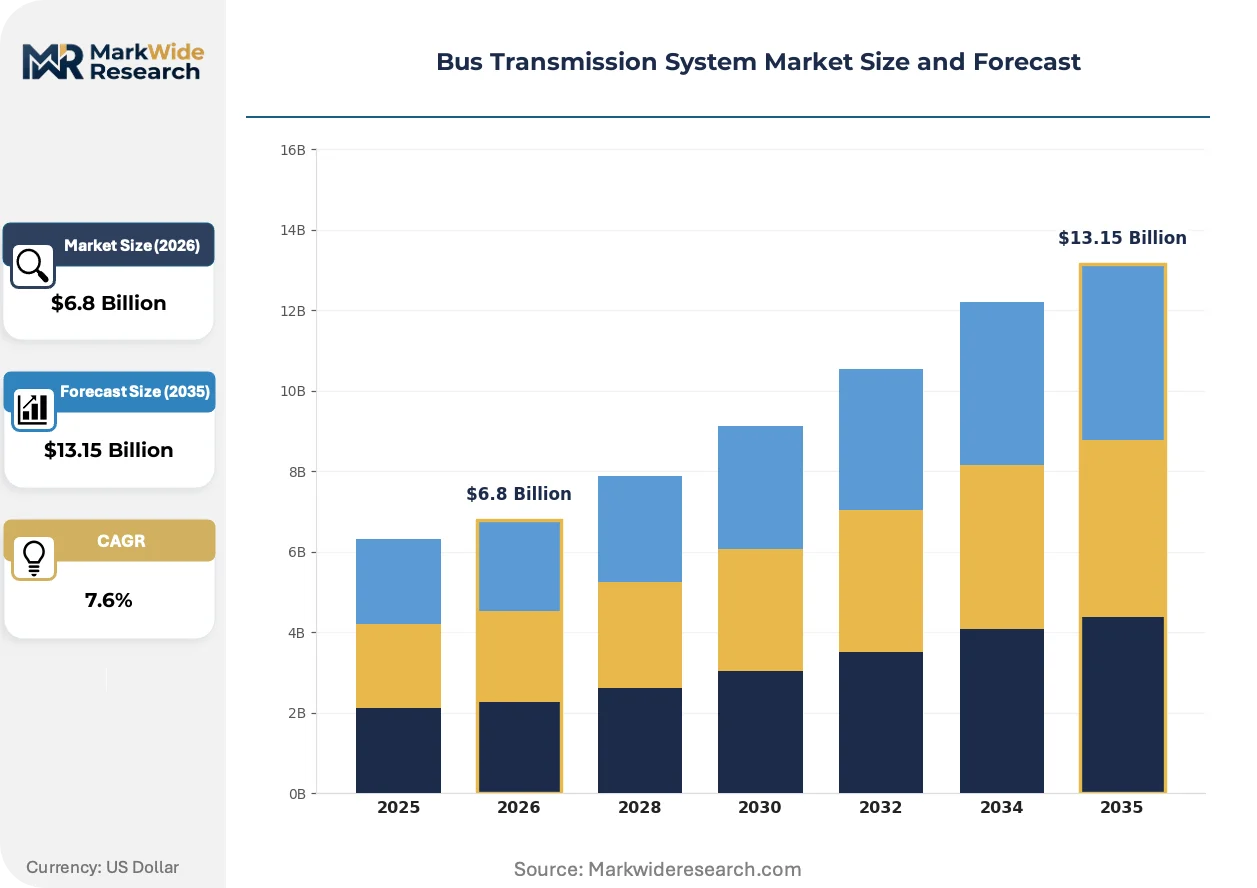
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transmission, Manual Transmission, Dual-Clutch Transmission, Continuously Variable Transmission Vehicle Type: Public Transport Buses, School Buses, Shuttle Buses, Luxury Coaches Component: Torque Converter, Gearbox, Clutch Assembly, Transmission Fluid Technology: Hydraulic, Pneumatic, Electro-Mechanical, Smart Transmission |
| Companies Covered | ZF Friedrichshafen AG, Allison Transmission Holdings Inc., Eaton Corporation, Voith GmbH, BorgWarner Inc., Aisin Corporation, Daimler Truck AG, MAN Truck & Bus, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Transmission System Market Evolving Landscape
Powertrain architecture is fragmenting across competing electrification pathways, with transmission suppliers forced to engineer modular platforms serving parallel hybrid, series hybrid, and full-electric drivetrain configurations simultaneously.
Electro-mechanical automated transmission technology is decomposing the traditional separation between gearbox mechanical design and electronic control systems. Tier-one suppliers are integrating silicon carbide inverters directly into transmission housings. European OEMs are adopting these integrated packages at accelerated pace for Euro VI-compliant urban bus platforms. The technology is decomposing established supplier boundaries between power electronics and mechanical drivetrain specialists.
The EU ECHA REACH framework is restricting hazardous substance content in transmission fluids and mandating lifecycle recyclability for clutch friction materials. Component suppliers must reformulate fluid chemistry and redesign clutch pack architectures to eliminate restricted substances. German and Austrian bus operators face the most immediate compliance deadlines, driving accelerated qualification of alternative material formulations.
Fleet procurement departments are consolidating transmission supplier relationships and demanding total cost of ownership guarantees spanning ten-year operational lifecycles. Large municipal authorities in Spain, Italy, and Poland are replacing transactional component purchasing with performance-based supply agreements. This contractual evolution is most visible in Southern European markets where public budget constraints intensify scrutiny of maintenance cost predictability.
Bus Transmission System Market Segmentation
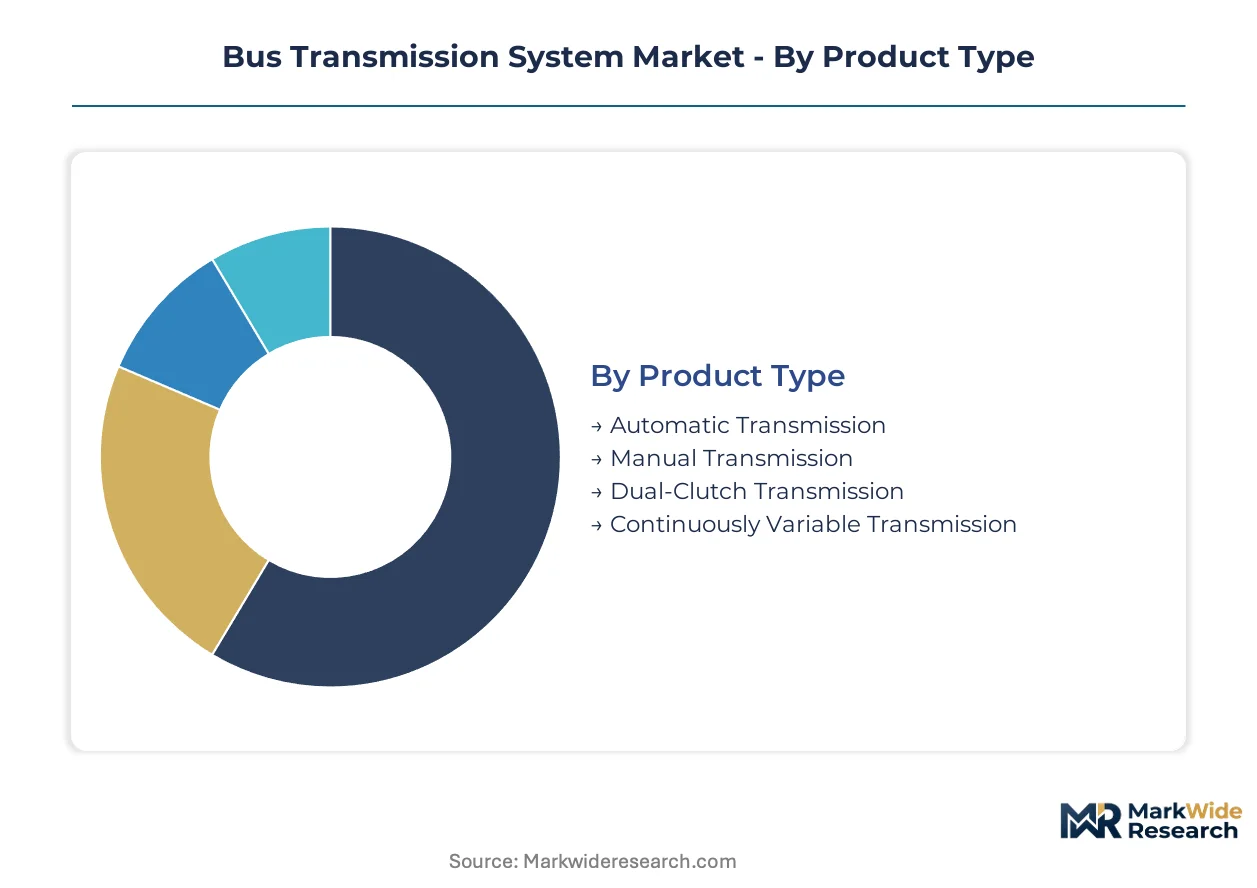
Bus transmission system procurement varies sharply across duty cycles and regulatory environments. Fleet operators select configurations based on stop-and-go intensity, driver skill availability, and electrification roadmaps. Component sourcing strategies diverge between municipal authorities prioritizing lifecycle cost and private operators minimizing upfront capital.
Product Type:
Automatic transmission dominates domestic procurement in Germany, France, and the Netherlands where EU Green Deal timelines mandate hybrid-compatible platforms. Manual transmission retains strong export demand from Indian and Southeast Asian school bus operators.
- Automatic Transmission:Torque converter-based systems manage 1,000 to 3,000 Nm across variable urban loads. German municipal fleets in Berlin and Munich specify these for driver fatigue reduction and fuel efficiency compliance with Euro VI standards.
- Manual Transmission:Mechanical clutch and synchromesh gearbox configurations persist where first-cost sensitivity overrides operational efficiency. Indian state transport corporations in Maharashtra and Karnataka favor these for intercity school bus deployment.
- Dual-Clutch Transmission:Twin-shaft architecture delivers rapid shift sequences for luxury coach applications.
- Continuously Variable Transmission:Pulley-based ratio modulation serves niche low-speed shuttle configurations.
Automatic transmission holds the largest share; momentum sits with dual-clutch systems as hybrid integration demands intensify.
Vehicle Type:
Cost tiers separate premium long-distance configurations from economy municipal specifications. Public transport buses command the highest component durability requirements.
- Public Transport Buses:High-cycle urban duty demands automated systems with predictive maintenance capability. Transit authorities in Madrid, Rome, and Warsaw specify electro-mechanical platforms for ten-year operational lifecycles.
- Luxury Coaches:Premium overland configurations prioritize shift comfort and noise suppression. French and Austrian operators on Alpine routes specify automated manual transmissions for gradient performance.
- School Buses:Safety-regulated stop-and-go routes in North America favor hydraulic automatics for driver focus.
- Shuttle Buses:Low-speed airport and campus circuits accommodate simpler mechanical architectures.
Public transport buses generate the highest volume; luxury coaches yield the steepest margin expansion trajectory.
Component:
Supply concentration varies by subsystem, with torque converter casting and electronic control unit sourcing showing divergent geographic patterns.
- Torque Converter:Fluid coupling assembly modulates engine torque across stall and coupling phases. ZF Friedrichshafen AG and Allison Transmission Holdings Inc. dominate supply to European and North American OEMs respectively.
- Gearbox:Multi-speed planetary or countershaft housing manages ratio selection under thermal loads exceeding 120°C. Voith GmbH's DIWA platform anchors German-speaking municipal markets.
- Clutch Assembly:Friction plate and pressure plate stack requires REACH-compliant material reformulation for EU ECHA compliance.
- Transmission Fluid:Lubricant chemistry faces hazardous substance restrictions under EU Green Deal lifecycle mandates.
Gearbox assemblies represent the highest value capture; torque converter refurbishment is expanding most quickly in aftermarket channels.
Technology:
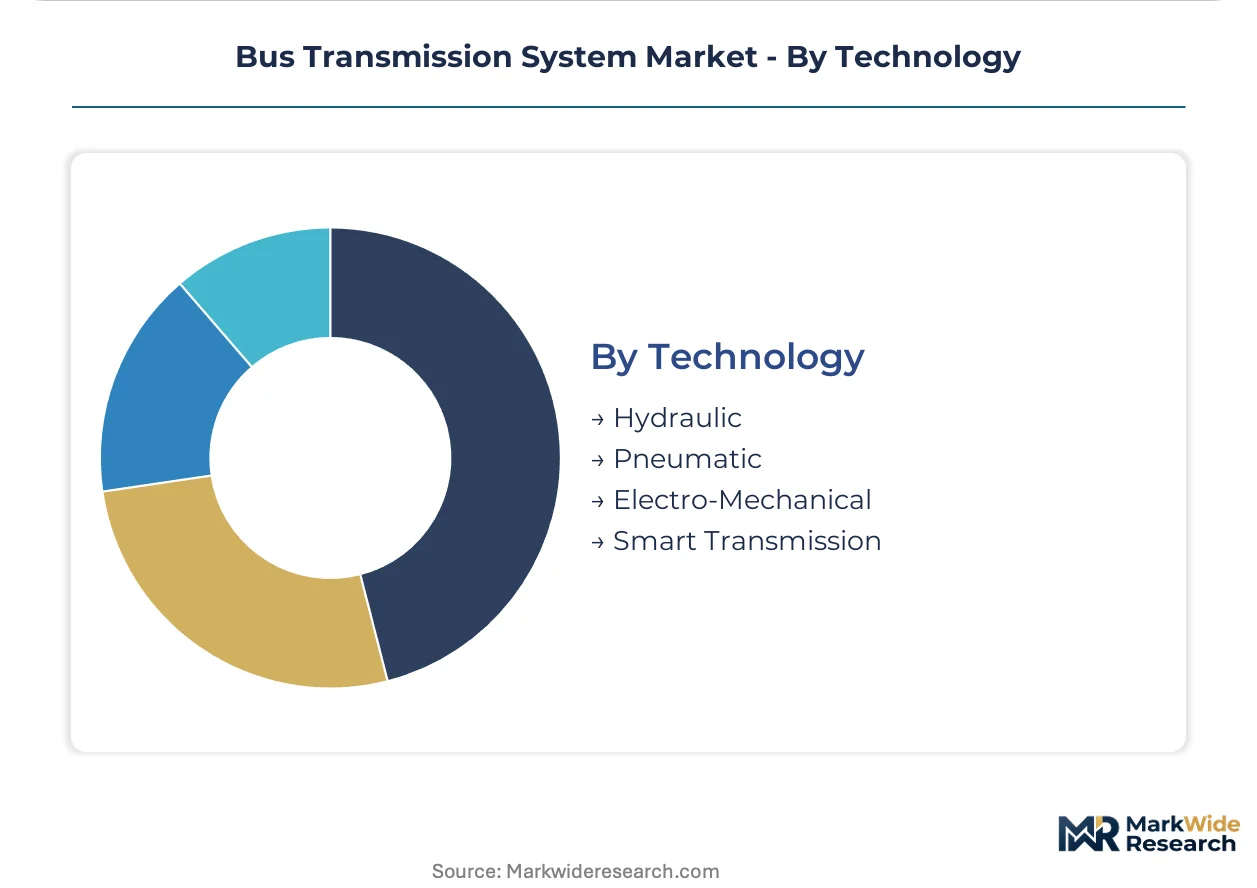
Technology maturity separates legacy hydraulic dominance from emerging electro-mechanical penetration rates across fleet replacement cycles.
- Electro-Mechanical:Integrated motor-generator and power electronics enable real-time shift optimization and predictive maintenance. Silicon carbide inverter integration into transmission housings is accelerating among European OEMs for Euro VI platforms.
- Smart Transmission:IoT sensor fusion with cloud-connected control units enables fleet-wide health monitoring. Municipal operators in Barcelona and Milan pilot these for total cost of ownership contracting.
- Hydraulic:Torque converter and planetary gearset automation serves established North American transit specifications.
- Pneumatic:Compressed air actuation retains niche application in specific legacy platform retrofits.
Hydraulic systems retain installed base dominance; electro-mechanical configurations are gaining share fastest as electrification mandates compress procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in bus transmission systems tilt toward net exporters with integrated automotive clusters, while import-dependent markets concentrate procurement around state fleet tenders and electrification subsidy windows.
China
State-backed bus operators in Beijing and Shanghai drive automated mechanical transmission replacement under MIIT GB durability protocols. The country's dual carbon goals compress procurement timelines for legacy mechanical systems. Yangtze River Delta manufacturing clusters supply torque converter assemblies to domestic OEMs and Southeast Asian export markets.
Germany
Municipal transit authorities in Berlin, Munich, and Hamburg specify hybrid-compatible automatic platforms to meet EU Green Deal phase-out deadlines for pure diesel buses. KBA enforcement of Euro VI compliance tightens component qualification requirements. Baden-Württemberg and Bavaria host integrated torque converter manufacturing anchored by long-term OEM supply contracts.
United States
EPA and NHTSA joint greenhouse gas standards compel transmission efficiency improvements across heavy-duty bus platforms operated by municipal transit agencies. School bus fleets in Texas and Florida favor hydraulic automatics for driver safety compliance. Midwest manufacturing corridors supply North American transit specifications with established planetary gearset automation.
India
FAME-II subsidy extensions create procurement pull for hybrid transmission systems in state transport corporation tenders across Maharashtra and Karnataka. First-cost sensitivity in school bus segments sustains mechanical transmission demand. Tamil Nadu and Gujarat industrial corridors concentrate gearbox assembly for domestic intercity operators and regional export markets.
Japan
METI energy efficiency standards shape transmission specification for urban bus fleets in Tokyo and Osaka metropolitan areas. Precision manufacturing clusters in Aichi and Kanagawa prefectures supply electro-mechanical control systems for premium coach applications. Domestic OEMs integrate silicon carbide power electronics into automated platforms for hybrid drivetrain export programs.
Bus Transmission System Market Competitive Landscape
Concentration sits with integrated powertrain specialists possessing captive torque converter casting and electronic control unit development capabilities. The competitive terrain separates three tiers: full-system integrators with OEM captive relationships, component specialists supplying gearbox subassemblies, and emerging electro-mechanical technology entrants. Strategic moves center on silicon carbide inverter integration partnerships and ten-year total cost of ownership contracting with municipal fleet operators.
Among German-speaking system integrators, ZF Friedrichshafen AG and Voith GmbH occupy positions anchored by automated transmission platforms engineered for European urban duty cycles. Allison Transmission Holdings Inc. represents the hydraulic hybrid technology archetype in North American transit applications. These three entities exemplify how geographic regulatory alignment—EU Green Deal timelines, EPA greenhouse gas standards, MIIT durability protocols—shapes competitive boundary definition across regional markets.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Allison Transmission Holdings Inc. |
| Eaton Corporation |
| Voith GmbH |
| BorgWarner Inc. |
| Aisin Corporation |
| Daimler Truck AG |
| MAN Truck & Bus |
| Cummins Inc. |
| Others |
Value Network & Pricing Analysis
Long-term performance-based supply agreements anchor municipal procurement across European transit authorities, locking in ten-year total cost of ownership visibility while constraining supplier pricing power through contractual efficiency guarantees. These structures tie transmission unit pricing to uptime metrics and predictive maintenance outcomes, compressing margin buffers for component manufacturers serving Berlin, Madrid, and Warsaw fleet operators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the bus transmission system market. Price differentiation separates silicon carbide-integrated electro-mechanical platforms from conventional hydraulic torque converter assemblies, with certification tier under Euro VI and EPA standards commanding measurable premiums. Cost compression in the economy tier is intensifying because Indian and Southeast Asian school bus operators prioritize first-cost minimization over lifecycle efficiency. State transport corporations in Maharashtra and Karnataka exhibit the highest price sensitivity, while German municipal authorities in Munich and Hamburg accept premium positioning for hybrid-compatible automated systems.
Supply Chain Analysis
Rare earth magnet processing concentration in Chinese facilities underwrites electro-mechanical transmission cost structures across global supply networks. Manufacturing gravity centers on Germany for precision gearbox assemblies, China for torque converter castings and electronic control units, and the United States for hydraulic planetary gearset production. Raw material dependencies include neodymium-dysprosium magnet alloys, high-grade steel forgings, and silicon carbide semiconductor substrates. Single-source vulnerability in Chinese rare earth processing creates exposure to export restriction risks. Distribution runs through OEM captive channels for new equipment, with independent aftermarket networks expanding for refurbishment and remanufacturing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bus transmission system market sits in early-cycle expansion as electrification mandates across the EU Green Deal and China's MIIT protocols accelerate hybrid-compatible platform procurement ahead of legacy mechanical phase-out deadlines.
For Market Incumbents: Consolidate torque converter casting capabilities and electronic control unit development through selective acquisition of specialized electro-mechanical engineering teams. Secure ten-year performance-based contracts with municipal fleet operators in Southern Europe to lock out emerging competitors. The priority defensive lever rests on backward integration into silicon carbide inverter manufacturing to preserve margin structure against power electronics specialists encroaching on transmission housings. For New Entrants and Emerging Players: Differentiate on predictive maintenance software integration for aftermarket service channels unbundled from OEM captive distribution. Target India's FAME-II subsidy window for hybrid transmission tenders in state transport corporation procurement cycles. Penetrate the remanufacturing segment serving aging hydraulic automatic fleets in North American school bus applications through IoT-enabled health monitoring as the primary go-to-market angle. For Investors and Strategic Acquirers: Electro-mechanical technology specialists with silicon carbide integration capabilities and municipal fleet software contracts represent the most defensible acquisition archetype across a five-to-ten-year electrification transition. Monitor EPA and NHTSA greenhouse gas standard phase-in acceleration as the critical inflection signal indicating compression of legacy hydraulic transmission replacement cycles and corresponding valuation pressure on pure-play hydraulic specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Power electronics consolidation into transmission housings enables Euro VI compliance for German OEM urban bus platforms. |
| Predictive Maintenance Platform Development | IoT sensor fusion with cloud-connected control units creates ten-year total cost of ownership contracting leverage with Barcelona and Milan municipal operators. |
| Aftermarket Service Network Expansion | Independent refurbishment channels capture margin from aging hydraulic automatic installed base in North American transit fleets. |
| Rare Earth Magnet Supply Diversification | Alternative sourcing for neodymium-dysprosium alloys reduces exposure to Chinese processing concentration and price volatility. |
| REACH-Compliant Material Reformulation | ECHA-mandated clutch friction material redesign qualifies component suppliers for German and Austrian bus operator procurement cycles. |
Research Methodology
A standing panel of municipal fleet procurement directors, Tier 1 supplier platform engineers, aftermarket service network managers, and power electronics control specialists provided ongoing calibration across the research process. Primary interview data combined with secondary validation from EPA regulatory filings, EU ECHA substance restriction databases, MIIT GB standard documentation, and vehicle production registration databases. Bottom-up unit shipment modeling triangulated against top-down value chain analysis across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including OEM captive supply disclosures and independent aftermarket channel shipment estimates. The analytical framework segmented by propulsion architecture, vehicle duty cycle intensity, electronic integration tier, and regional regulatory compliance cluster. CAGRs were derived from fitted growth curves applied to replacement cycle dynamics and electrification mandate penetration schedules. Forecast inputs incorporated rare earth magnet price indices and municipal fleet electrification subsidy allocation patterns.
Material uncertainties — rare earth supply disruption, EPA timeline acceleration, and electro-mechanical engineering talent scarcity — sit outside the modeled envelope and could compress or extend adoption trajectories. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fleet operator capital allocation priorities. Practitioners should keep alternative scenarios live as EU Green Deal phase-out deadlines and China's dual carbon goal implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Intercity Bus Travel Market
Buses
Luxury Bus Market
Buses
North America Bus Market
Buses
Canada School Bus Market
Buses
Bus Charter Services Market
Buses
Bus Bellows Market
Buses
Airport Bus Market
Buses
Bus Chassis Market
Buses
Europe Trolley Bus Market
Buses
Europe Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Canada Transit Buses Market
Buses
Africa Electric Bus Market
Buses
Electric Intercity Bus Market
Buses
Airport Shuttle Bus Market
Buses
Bus Rental Market