
 India Electric Hydraulic Power Steering Market | 2026-2036
India Electric Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Hydraulic Power Steering Market Insights
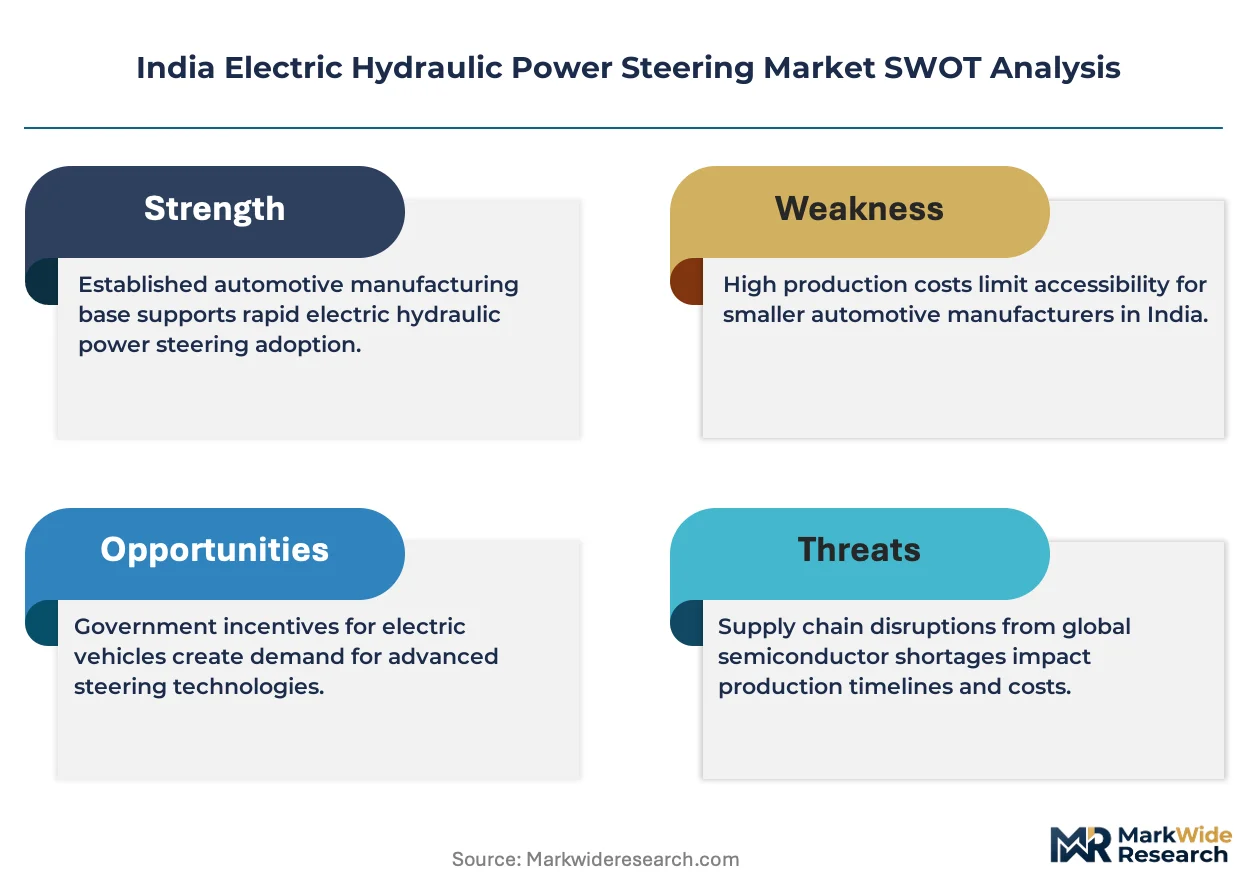
AIS-153 certification compliance for steering systems is collapsing the supplier base to qualified manufacturers. ZF Steering Gear (India) Limited leverages its domestic manufacturing footprint to anchor supply contracts with major OEMs. JTEKT Corporation competes through deep R&D intensity in electro-hydraulic valve design. Mando Automotive India specializes in adaptive control modules tailored to Indian road conditions.
Electric hydraulic power steering combines an electric motor-driven hydraulic pump with conventional rack-and-pinion or column-type steering gear, delivering variable assist force based on vehicle speed and steering angle through sensor feedback. The system serves commercial vehicles requiring high steering torque at low speeds without the parasitic losses of engine-driven pumps. Rack and pinion configurations dominate OEM installations due to compact packaging and direct road feel. Sensor-based technology commands premium positioning as fleet operators demand predictive maintenance integration. Aftermarket retrofitting lags OEM fitment but accelerates among aging commercial vehicle parc operators seeking fuel efficiency gains.
BIS mandates AIS-153 testing protocols while CEA guidelines shape electric motor efficiency benchmarks for auxiliary automotive systems. CDSCO oversight extends to sensor components qualifying as automotive safety-critical devices. PLI scheme disbursements for advanced automotive technology are redirecting capital toward in-house EHPS module production. Stakeholders must monitor how AIS-153 amendment timelines interact with state-level commercial vehicle scrappage incentives to anticipate replacement cycle acceleration.
Market Dynamics
AIS-153 certification mandates are compressing the supplier base to qualified manufacturers while PLI scheme disbursements redirect capital toward in-house EHPS module production. This regulatory-capital convergence is restructuring competitive positioning across Maharashtra and Gujarat commercial vehicle corridors.
Growth Catalysts
- CEA efficiency benchmarks:Electric motor efficiency standards for auxiliary automotive systems are accelerating OEM migration from engine-driven hydraulic pumps to motor-driven EHPS architectures.
- Sensor-based predictive maintenance:Fleet operators in Chennai and Pune manufacturing corridors are demanding integrated sensor feedback systems for real-time steering diagnostics and downtime reduction.
- State-level scrappage incentives:Commercial vehicle replacement programs in Maharashtra and Gujarat are compressing fleet refresh cycles toward EHPS-equipped platforms.
Market Restraints
- Input cost volatility:Rare earth magnet prices for high-efficiency electric motors create margin pressure for pump assembly manufacturers.
- Supply concentration risk:Electro-hydraulic valve precision machining capacity clusters in select Tamil Nadu and Karnataka supplier parks.
- Full-electric steering substitution:Battery-electric commercial vehicle platforms are skipping EHPS entirely for steer-by-wire architectures in long-haul segments.
Strategic Opportunities
- Aftermarket retrofitting acceleration:Aging commercial vehicle parc operators in Uttar Pradesh and Rajasthan are seeking fuel efficiency gains through EHPS conversions.
- Adaptive control module localization:PLI scheme benefits for advanced automotive technology are enabling domestic production of road-condition-tuned control algorithms.
- CDSCO safety-critical sensor pathway:Automotive safety device certification is creating first-mover advantage for integrated sensor-electronics suppliers.
Industry Challenges
- AIS-153 testing timeline compression:Certification protocol amendments are forcing simultaneous engineering validation across multiple OEM programs.
- Electro-mechanical integration complexity:Legacy rack-and-pinion architectures require extensive redesign to accommodate motor-driven pump packaging constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Hydraulic Power Steering Market |
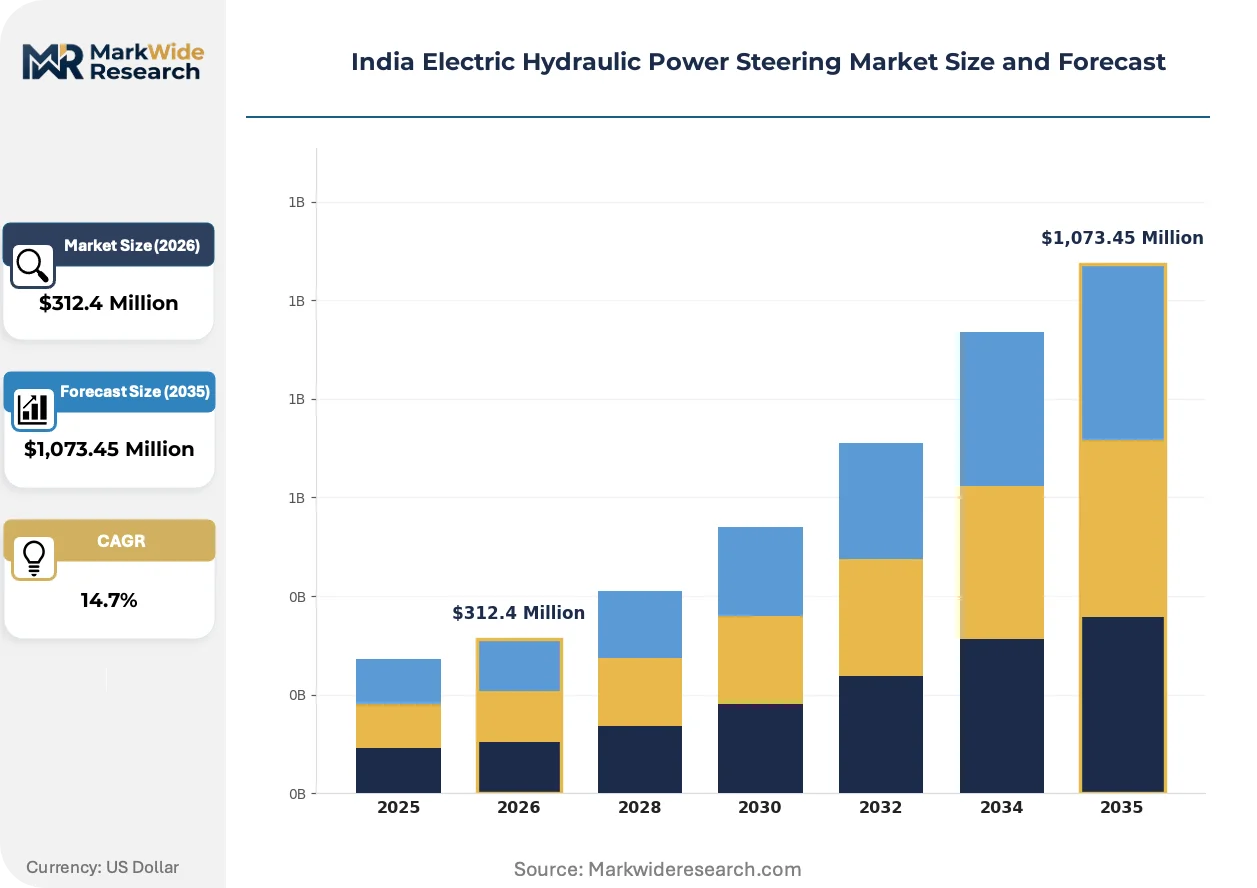
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Type, Rack And Pinion, Electro-Hydraulic, Integrated End User: Passenger Vehicles, Commercial Vehicles, Light Trucks, Heavy Trucks Technology: Adaptive Control, Sensor-Based, Variable Gear Ratio, Active Control Installation: OEM, Aftermarket, Retrofitting, Custom |
| Companies Covered | JTEKT Corporation, Denso Corporation, ZF TRW Automotive Holdings Corp, Danfoss, NSK Ltd, Hitachi Automotive Systems Ltd, Nexteer Automotive, ZF Steering Gear (India) Limited, Mando Automotive India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Hydraulic Power Steering Market Trends and Innovations
EHPS architecture is undergoing fundamental redesign as sensor integration and electric motor efficiency improvements reshape system boundaries. Three concurrent developments are redefining competitive differentiation in steering system supply.
Variable displacement pump technology is bifurcating the product landscape between fixed-output units for cost-sensitive applications and intelligent flow-matched systems for premium commercial platforms. Fleet operators in Gujarat are specifying the latter for long-haul tractors despite unit cost premiums. The technology is bifurcating supplier R&D allocation toward software-defined flow control versus mechanical efficiency optimization.
BIS amendment timelines for AIS-153 steering system protocols are forcing premature redesign cycles among component suppliers. The industrial consequence is accelerated obsolescence of pre-2023 validation data and retesting investments. Tier-1 suppliers in Pune are responding by consolidating multiple OEM validation programs into shared test cell infrastructure.
Service unbundling is separating EHPS hardware procurement from predictive analytics subscriptions among large fleet operators. Traditional component distributors are losing attach rates to telematics-integrated service providers. This pattern is most visible in Maharashtra where state transport corporation tenders now specify minimum sensor data retention periods.
India Electric Hydraulic Power Steering Market Segmentation
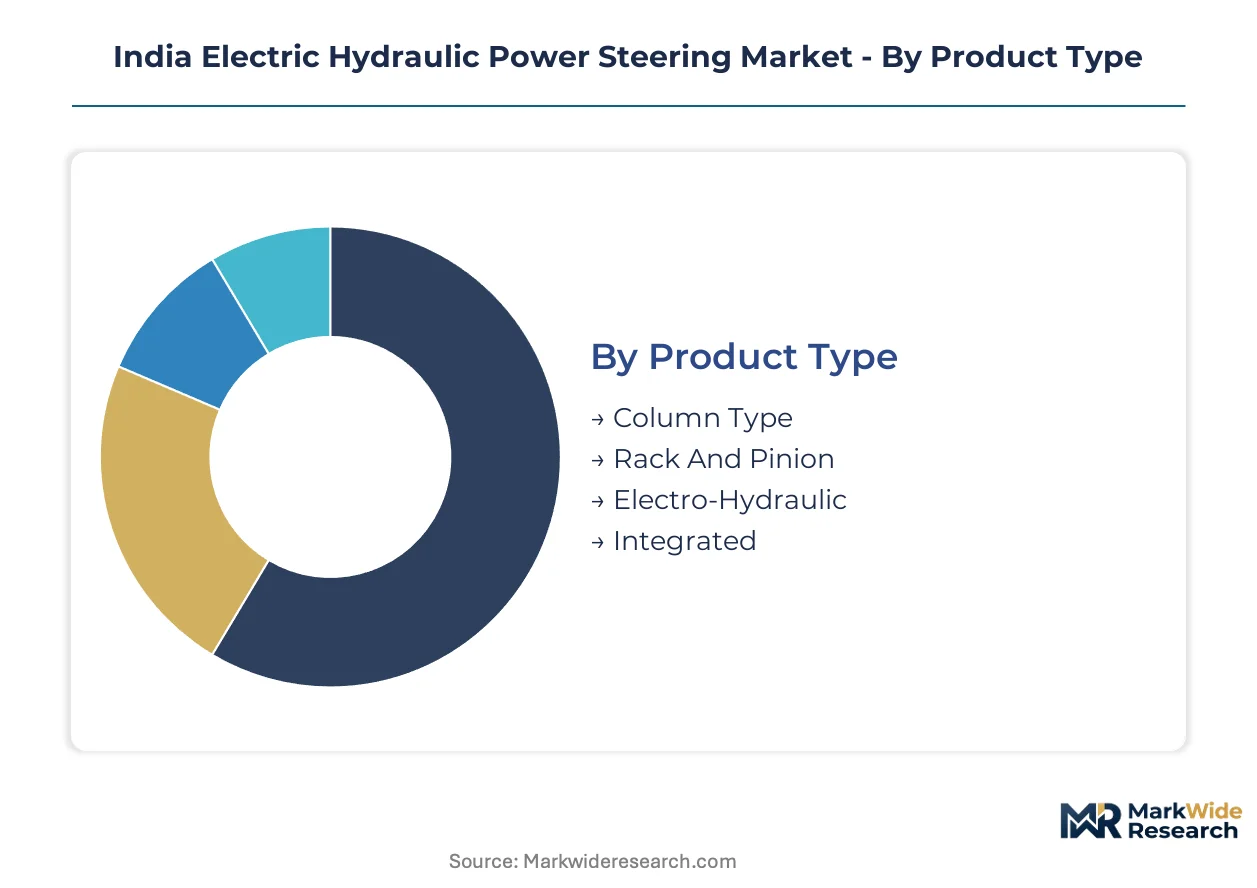
Segmentation in the India EHPS market reveals how regulatory mandates and fleet operator procurement patterns concentrate value across distinct technical configurations. Understanding these divisions exposes where BIS certification requirements and PLI scheme incentives are redirecting capital investment.
Product Type:
Premium margin pools sit with integrated systems that combine pump, motor, and control electronics in sealed modules, while rack and pinion architectures dominate volume throughput.
- Column Type:Compact packaging suits light commercial vehicles with restricted engine bay space. Demand concentrates among Uttar Pradesh and Rajasthan fleet operators retrofitting aging parc vehicles for fuel efficiency compliance.
- Rack And Pinion:Direct mechanical linkage delivers precise road feedback through integrated pinion gear engagement with the steering rack. Maharashtra and Gujarat OEM installations favor this configuration for heavy commercial platforms requiring sustained high-torque assist.
- Electro-Hydraulic:Modular retrofit architecture enables aftermarket conversion of engine-driven hydraulic systems.
- Integrated:Sealed motor-pump-control units command price premiums through reduced assembly complexity.
The dominant share belongs to Rack And Pinion, while Integrated is closing the gap fastest.
End User:
Commercial vehicle procurement volumes exceed passenger vehicle fitment, with heavy trucks generating the highest per-unit system value.
- Passenger Vehicles:Limited EHPS penetration as electric power steering dominates light vehicle architectures.
- Commercial Vehicles:Fleet operators in Chennai and Pune manufacturing corridors specify sensor-integrated EHPS for predictive maintenance capabilities and downtime reduction.
- Light Trucks:Municipal and last-mile delivery operators in Tier-2 cities drive retrofit demand.
- Heavy Trucks:Long-haul tractor configurations require sustained hydraulic assist under loaded conditions.
Commercial Vehicles capture the largest installed base, though Heavy Trucks show the steepest expansion trajectory.
Technology:
Sensor-based architectures concentrate R&D investment as CDSCO safety-critical device certification creates competitive moats.
- Adaptive Control:Real-time road condition algorithms adjust assist force through steering angle and vehicle speed feedback. Tamil Nadu and Karnataka control module suppliers are localizing software tuned to Indian pavement irregularities.
- Sensor-Based:Integrated torque, position, and temperature sensors enable fleet telematics integration. Maharashtra state transport tenders now mandate minimum sensor data retention periods, accelerating specification.
- Variable Gear Ratio:Mechanical rack designs modify steering sensitivity by vehicle speed.
- Active Control:Predictive algorithms anticipate driver input through machine learning models.
Sensor-Based systems hold the leading position, with Adaptive Control gaining share fastest.
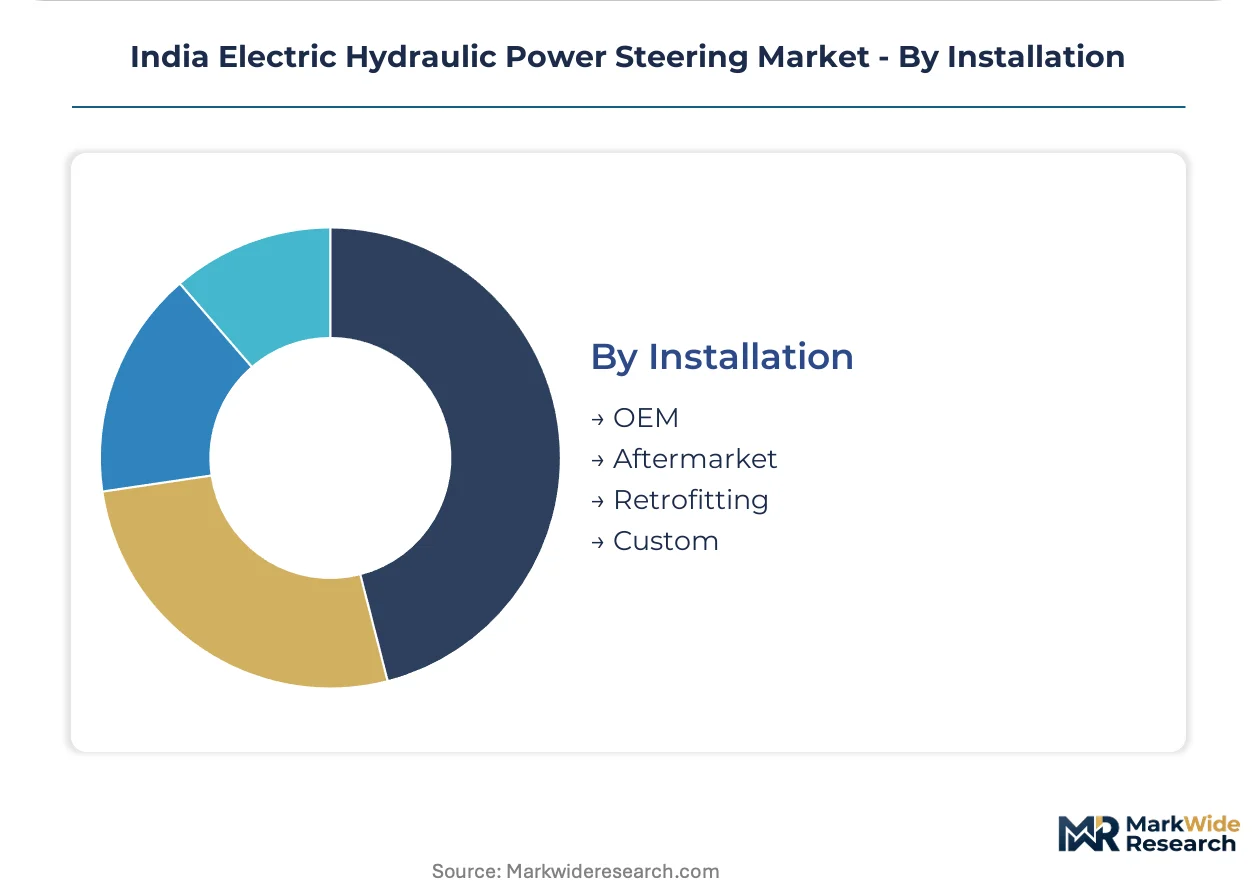
Installation:
OEM fitment generates volume scale, while aftermarket retrofitting delivers margin expansion as aging parc operators seek compliance.
- OEM:Factory-installed EHPS dominates new commercial vehicle platforms as BIS AIS-153 certification compresses supplier qualification to tier-1 manufacturers.
- Aftermarket:Distributor networks in Delhi and Mumbai supply replacement units for warranty repairs.
- Retrofitting:Conversion of engine-driven hydraulic systems to motor-driven architectures accelerates among Rajasthan and Uttar Pradesh operators facing fuel cost pressure.
- Custom:Specialized vehicle builders specify non-standard pump configurations.
OEM installation maintains the dominant share, while Retrofitting is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level commercial vehicle scrappage incentives and BIS certification mandates are redirecting EHPS procurement toward manufacturing corridors in Maharashtra, Gujarat, Tamil Nadu, and Karnataka. Fleet operators in these states face compressed replacement cycles as older vehicles phase out under environmental compliance programs.
Maharashtra
Heavy commercial vehicle production clusters in Pune and Mumbai anchor OEM demand for rack-and-pinion EHPS configurations. The state's transport corporation tenders now mandate minimum sensor data retention periods under revised fleet specifications. Tier-1 suppliers concentrate validation infrastructure in shared test cells across the Chakan automotive belt to manage AIS-153 compliance timelines.
Gujarat
Long-haul tractor fleet operators in Ahmedabad and Vadodara corridors specify variable displacement pump systems despite unit cost premiums. The state's commercial vehicle replacement program accelerates EHPS-equipped platform procurement through direct scrappage subsidies. Manufacturing parks in Sanand house electro-hydraulic valve precision machining capacity serving western India demand.
Tamil Nadu
Chennai manufacturing corridors concentrate sensor-integrated EHPS demand from commercial vehicle exporters targeting ASEAN markets. Control module suppliers in Sriperumbudur localize adaptive algorithms tuned to Indian pavement irregularities. CEA electric motor efficiency benchmarks drive OEM migration from engine-driven pumps to motor-driven architectures in regional assembly plants.
Karnataka
Bangalore-Tumkur industrial zones host electro-hydraulic valve machining capacity that creates supply concentration risk for national OEM programs. The state's PLI scheme disbursements for advanced automotive technology redirect capital toward in-house EHPS module production. Aftermarket retrofitting accelerates among aging commercial vehicle operators in Hubli-Dharwad facing fuel cost pressure.
Uttar Pradesh
Light commercial vehicle retrofit demand concentrates in Kanpur and Lucknow as aging parc operators seek fuel efficiency compliance without full platform replacement. State transport utility procurement lags western corridors but accelerates through central government fleet modernization mandates. Distributor networks in Noida supply replacement units for warranty repairs across the northern belt.
India Electric Hydraulic Power Steering Market Competitive Landscape
Player mix skews toward diversified automotive component conglomerates with steering system heritage, supplemented by specialized electro-hydraulic control module developers. Market structure consolidates around tier-1 manufacturers holding AIS-153 certification, compressing qualified supplier ranks. Two strategic archetypes dominate: integrated system suppliers combining pump-motor-control in sealed modules, and adaptive control specialists tuning algorithms to local road conditions. Competitive moves center on shared validation infrastructure investments and PLI scheme capital capture for domestic module production.
Within the integrated system tier, ZF Steering Gear (India) Limited and JTEKT Corporation occupy positions exemplifying scale-driven supply contract anchoring with major OEMs. Mando Automotive India represents the adaptive control specialization archetype, with its India-domiciled structure reflecting PLI scheme beneficiary positioning. These three entities collectively illustrate how regulatory certification requirements and incentive program access determine competitive tier placement.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Denso Corporation |
| ZF TRW Automotive Holdings Corp |
| Danfoss |
| NSK Ltd |
| Hitachi Automotive Systems Ltd |
| Nexteer Automotive |
| ZF Steering Gear (India) Limited |
| Mando Automotive India |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Maharashtra OEMs and tier-1 EHPS suppliers lock in rare earth magnet supply access while fixing pump assembly unit costs against neodymium price volatility. This contract structure compresses margin exposure for qualified manufacturers holding AIS-153 certification while freezing out spot-market dependent competitors from fleet procurement tenders.
Pricing Analysis
Certification level creates the primary spread between qualified tier-1 suppliers and unvalidated component vendors. Three-tier pricing structure separates integrated motor-pump-control modules from rack-and-pinion assemblies and basic electro-hydraulic retrofit kits. Cost compression in economy-tier retrofit segments is intensifying because Uttar Pradesh fleet operators prioritize fuel savings over predictive maintenance features. Light commercial vehicle retrofit buyers exhibit highest price sensitivity, while Gujarat long-haul tractor fleets accept premiums for variable displacement pump intelligence.
Supply Chain Analysis
Inventory buffers for electro-hydraulic valve precision components stretch 8-12 weeks due to concentrated machining capacity in Tamil Nadu and Karnataka supplier parks. Rare earth magnet procurement draws from China and domestic Indian rare earth processing facilities, with neodymium-iron-boron alloy representing the critical cost anchor. Single-source vulnerability in high-torque electric motor winding equipment creates chokepoint exposure for pump assembly manufacturers. Distribution runs through OEM direct supply contracts for factory fitment, with aftermarket channels served by Mumbai and Delhi distributor networks stocking replacement sealed modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified AIS-153 certification slots represent the binding constraint compressing competitive participation, with electro-hydraulic valve machining expertise and sensor-integration firmware development constituting the scarcest deployable capabilities. Manufacturers lacking shared test cell infrastructure face disqualification from multi-OEM validation programs regardless of component quality.
For Market Incumbents: Compound defensive positioning through backward integration into rare earth magnet procurement and captive electro-hydraulic valve machining capacity in Tamil Nadu supplier parks. Lock in shared AIS-153 validation infrastructure access with Chakan automotive belt test cell consortiums to neutralize certification timeline compression threats from BIS amendment cycles. Prioritize sensor firmware R&D investment to maintain CDSCO safety-critical device pathway advantages against full-electric steering substitution pressure. For New Entrants and Emerging Players: Anchor in aftermarket retrofitting acceleration across Uttar Pradesh and Rajasthan aging commercial vehicle parc operators seeking fuel efficiency compliance without platform replacement. Target light truck municipal fleet segments in Tier-2 cities where specification flexibility exceeds Maharashtra state transport tender rigidity. Pursue adaptive control module localization partnerships with Karnataka PLI scheme beneficiaries to bypass integrated system manufacturing capital barriers. For Investors and Strategic Acquirers: Capital is best deployed toward electro-hydraulic control module specialists possessing India-tuned road condition algorithms and CDSCO safety-critical sensor certification progress. Long-term viability hinges on positioning upstream of steer-by-wire displacement in heavy commercial segments where hydraulic assist torque requirements persist. Watch battery-electric commercial vehicle platform ramp rates as the critical inflection signal for EHPS demand trajectory compression.| Strategic Initiative | Industry Significance |
|---|---|
| Shared AIS-153 Validation Infrastructure Investment | Chakan belt test cell consortiums compress multi-OEM certification timelines for tier-1 suppliers. |
| Adaptive Control Module Localization | Karnataka PLI scheme disbursements enable domestic software tuning to Indian pavement irregularities. |
| Rare Earth Magnet Backward Integration | Captive neodymium procurement insulates pump assembly margins against commodity volatility. |
| Sensor-Electronics CDSCO Certification Pathway | Safety-critical device status creates competitive moats for integrated telematics suppliers. |
| Aftermarket Retrofit Channel Expansion | Uttar Pradesh distributor networks capture fuel efficiency demand from aging parc operators. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement heads, aftermarket distributors in Delhi and Mumbai, and fleet maintenance directors at Maharashtra state transport utilities anchored the qualitative base. Primary interview insights triangulated against BIS certification documentation, CEA electric motor efficiency benchmark filings, PLI scheme disbursement records, and commercial vehicle production databases from regional automotive clusters. Secondary validation incorporated customs data on rare earth magnet imports, CDSCO medical device safety filings for sensor components, and state-level scrappage incentive program implementation reports. Bottom-up EHPS unit demand estimates from fleet operator procurement patterns converged with top-down market sizing derived from OEM platform engineering specifications across the analysis window.
Sensitivity analysis tested forecast robustness against battery-electric commercial vehicle penetration scenarios, rare earth magnet price volatility bands, and AIS-153 certification timeline compression variants. Segmentation modeling spanned product architecture, vehicle class, technology integration level, and regional manufacturing corridor concentration. CAGRs emerged from fitted growth curves applied to validated base-year unit volumes, with projections incorporating OEM platform lifecycle transitions and fleet replacement cycle dynamics. Industry-specific inputs included electro-hydraulic valve machining capacity utilization rates and sensor-integrated system attach rates in state transport corporation tenders.
Material uncertainties — regulatory amendment timing, rare earth supply disruption events, and steer-by-wire technology cost curves — sit outside the modeled envelope. Forecasts reflect assumptions regarding PLI scheme continuation and BIS certification protocol stability. Revision becomes warranted when battery-electric heavy commercial vehicle share crosses thresholds triggering EHPS demand displacement in long-haul tractor segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Timing Gear Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Indonesia Automotive Lubricants Market