
 Turkey Passenger Vehicles Lubricants Market | 2026-2036
Turkey Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Passenger Vehicles Lubricants Market Analytics
Turkish base oil refiners and blenders is repositioning toward API SP and ILSAC GF-6 compliant stocks to serve the domestic passenger car parc. Petrol Ofisi leverages its integrated refinery-to-retail network across the Marmara corridor. BP PLC (Castrol) anchors premium synthetic positioning through authorized service center partnerships in metropolitan areas. Royal Dutch Shell PLC competes on logistics density, sustaining nationwide distribution through its terminal and depot infrastructure.
Turkey passenger vehicles lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and prevent wear in internal combustion engines and driveline components, with viscosity grades typically spanning SAE 0W-16 through 20W-50 depending on regional climate and OEM specifications. Their primary commercial purpose is to extend engine operational life while maintaining fuel economy compliance under variable Turkish driving conditions spanning hot Anatolian summers and cold eastern winters. Engine oil dominates value generation due to higher change frequency and formulation complexity, while synthetic formulations capture expanding margin pools as OEM service intervals lengthen and turbocharged direct-injection engines proliferate in the Turkish parc. Distribution through service stations retains volume leadership, though online sales channels are gaining traction among younger vehicle owners in urban centers.
Turkey's Ministry of Industry and Technology, the Turkish Standards Institution (TSE), and EU-aligned REACH frameworks collectively shape product compliance, emissions-linked formulation mandates, and import quality gates for lubricant marketers. TSE's mandatory labeling and performance certification requirements create barriers for unbranded imports while rewarding domestic blenders with accredited laboratory infrastructure. Stakeholders must monitor evolving OEM warranty conditions and the pace of electrification in Turkey's domestic assembly sector to calibrate portfolio transitions between combustion-optimized and hybrid-compatible lubricant technologies.
Market Dynamics
Turkey's passenger vehicle lubricant market faces structural pressure from the Ministry of Industry and Technology's accelerated emissions compliance timelines, which force workshops to abandon conventional mineral formulations in favor of higher-grade synthetic stocks. This regulatory compression cascades through the supply chain, repositioning domestic blenders and reshaping procurement patterns across Istanbul's dense service network.
Growth Catalysts
- EU-Aligned REACH Frameworks:Chemical registration and hazard communication standards mandate cleaner base oil streams, pushing Turkish blenders toward Group III and Group IV stocks that command premium positioning in authorized service channels.
- Turbocharged Direct-Injection Engine Proliferation:OEM service interval extension requirements create pull for low-viscosity synthetics, with SAE 0W-20 and 0W-16 grades capturing disproportionate margin pools in newer vehicle cohorts.
- Marmara Corridor Fleet Density:Urban commercial operators in Istanbul and Ankara consolidate lubricant procurement through integrated service contracts, concentrating volume in synthetic formulations with documented fuel economy benefits.
Market Restraints
- Base Oil Import Dependence:Turkey's domestic refining capacity for high-quality Group III stocks remains limited, exposing blenders to volatility in Middle Eastern and Mediterranean feedstock supply chains.
- TSE Certification Timelines:Mandatory Turkish Standards Institution laboratory testing creates 8-12 week approval windows for new formulations, slowing product refresh cycles against faster-moving regional competitors.
- Electric Powertrain Substitution:Battery electric vehicle assembly growth within Turkey's domestic automotive sector threatens long-term demand compression for combustion-optimized lubricant categories.
Strategic Opportunities
- Central Anatolia Service Infrastructure:Aftermarket penetration in Konya, Kayseri, and Sivas lags Marmara density, creating whitespace for branded synthetic distribution through independent workshop networks.
- Hybrid-Compatible Formulation Development:Dual-clutch and mild-hybrid systems require specialized thermal stability profiles, opening portfolio expansion beyond conventional ICE-optimized products.
- E-Commerce Channel Integration:Younger vehicle owners in Izmir and Bursa demonstrate receptivity to direct-to-consumer lubricant sales, bypassing traditional service station intermediaries for routine maintenance purchases.
Industry Challenges
- API SP and ILSAC GF-6 Technical Competency:Formulation chemistry for latest-generation passenger car motor oils requires specialized additive package knowledge scarce among mid-tier Turkish blenders.
- Warranty Compliance Documentation:OEM-authorized service centers demand extensive oil analysis records and batch traceability, imposing data infrastructure investments on smaller independent workshops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Passenger Vehicles Lubricants Market |
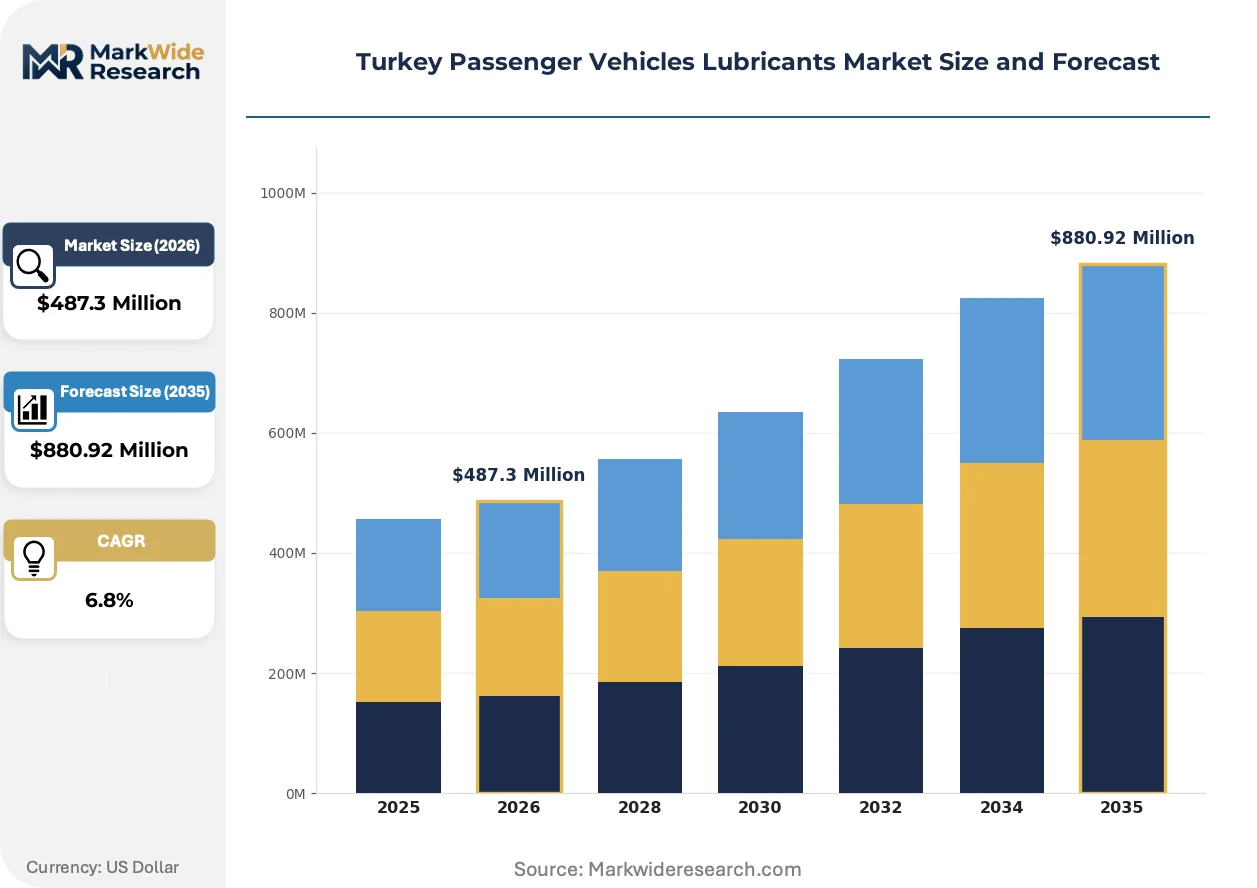
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil Application: Passenger Cars, SUVs, Light Trucks, Commercial Vans Formulation: Synthetic, Semi-Synthetic, Mineral, Bio-Based Distribution Channel: Retail Stores, Online Sales, Service Stations, Wholesalers |
| Companies Covered | Petrol Ofisi, BP PLC (Castrol), Royal Dutch Shell PLC, TotalEnergies, FUCHS, Altinbas Holdings, BELGIN Oil, ExxonMobil Corporation, LUKOIL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Passenger Vehicles Lubricants Market Evolving Landscape
Digital diagnostic integration and predictive maintenance platforms are restructuring how Turkish workshops specify and procure lubricant products, compressing traditional supplier relationships and opening entry points for data-enabled service models.
Condition-based oil monitoring systems using particle count sensors and viscosity real-time measurement are automating change interval determination for commercial fleet operators in Istanbul. Transport logistics companies with 50-plus vehicle parcs are piloting these installations to extend drain intervals beyond fixed schedules. This capability is automating procurement timing and reducing bulk inventory holdings at depot locations.
TSE's alignment with EU REACH hazard classification standards is mandating reformulation of corrosion inhibitor packages across passenger car motor oil portfolios. Domestic blenders face 18-month transition windows to re-register products with updated safety data sheets. Istanbul-based authorized service centers are responding by consolidating supplier relationships with accredited laboratories capable of accelerated certification turnaround.
Fleet procurement consolidation is compressing the independent workshop channel's lubricant autonomy. Large commercial operators in Ankara negotiate direct supply agreements with blenders, bypassing traditional distributor markups for volume commitments above 10,000 liters annually. This behavior concentrates margin capture with integrated refinery-to-retail networks while marginalizing smaller service stations dependent on spot purchasing.
Turkey Passenger Vehicles Lubricants Market Segmentation
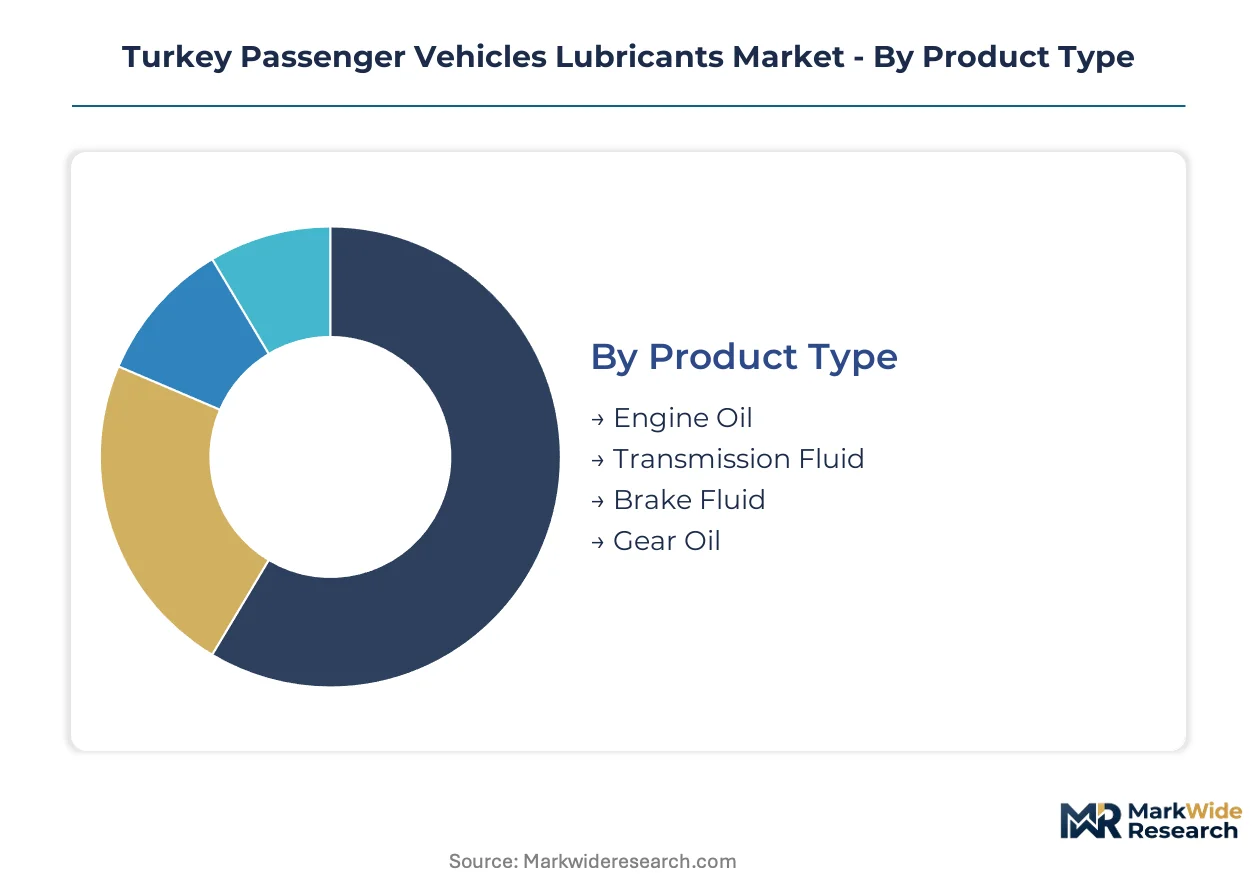
Segmentation in Turkey's passenger vehicle lubricants market reveals how regulatory pressure and fleet modernization reshape procurement patterns across product categories and channel structures. Understanding these divides exposes where margin pools concentrate and which formulations face substitution risk from electrification trends.
Product Type:
Engine oil functions as a standalone consumable with direct customer visibility, while transmission and brake fluids operate as embedded systems requiring specialist intervention.
- Engine Oil:Formulated hydrocarbon-based fluids spanning SAE 0W-16 through 20W-50 viscosity grades, engineered to reduce friction and dissipate heat in internal combustion engines. Istanbul's urban fleet operators concentrate procurement here due to higher change frequency and documented fuel economy compliance requirements under Turkish emissions timelines. API SP and ILSAC GF-6 specifications now dominate premium positioning.
- Transmission Fluid:Specialized lubricants for automatic and dual-clutch systems requiring precise friction coefficient maintenance. Ankara's commercial van operators generate concentrated demand as extended service intervals and thermal stability requirements push toward synthetic formulations with OEM warranty documentation.
- Brake Fluid:Hygroscopic glycol-ether or silicone-based hydraulic fluids meeting DOT 3, DOT 4, and DOT 5.1 specifications. Marmara region workshops stock for routine maintenance cycles tied to safety inspection schedules.
- Gear Oil:High-viscosity extreme-pressure lubricants for differential and manual transmission applications. Central Anatolia's independent service networks maintain inventory for older vehicle parcs.
Engine oil leads volumes today; transmission fluid is gaining share fastest.
Application:
Cost tier stratification separates premium OEM-compliant service from economy aftermarket alternatives across vehicle categories.
- Passenger Cars:Turkey's largest vehicle cohort driving synthetic formulation demand through turbocharged direct-injection engine proliferation. Istanbul and Izmir's younger vehicle owners prioritize low-viscosity grades for fuel economy compliance.
- SUVs:Heavier-duty operating profiles requiring enhanced thermal stability and load-bearing additive packages. Ankara's fleet operators specify these for mixed urban-highway duty cycles.
- Light Trucks:Commercial utility applications with extended drain interval requirements. Central Anatolia's logistics consolidators negotiate volume contracts for synthetic stocks.
- Commercial Vans:High-utilization urban delivery vehicles with intensive maintenance schedules. Marmara corridor last-mile operators drive bulk procurement through integrated service agreements.
Passenger cars anchor current revenue; commercial vans show steepest expansion trajectory.
Formulation:
Margin concentration follows technology maturity, with premium synthetics capturing expanding pools as mineral formulations face regulatory compression.
- Synthetic:Group III and Group IV base oil formulations engineered for extreme temperature stability and extended drain intervals. Turkey's Ministry of Industry and Technology emissions mandates accelerate workshop conversion in metropolitan service centers.
- Semi-Synthetic:Blended formulations balancing performance enhancement with cost sensitivity. Bursa's independent workshops favor these for mid-age vehicle maintenance.
- Mineral:Conventional Group I and Group II base stocks facing structural decline as TSE certification requirements tighten. Eastern Anatolia's price-sensitive segments sustain residual demand.
- Bio-Based:Renewable-source formulations with limited current penetration but emerging positioning for sustainability-linked fleet procurement. Izmir's municipal pilot programs test viability.
Synthetic formulations command dominant share; bio-based alternatives are climbing the fastest from minimal base.
Distribution Channel:
Customer type fragmentation separates institutional fleet procurement from individual owner behavior, with channel choice correlating to vehicle age and technical confidence.
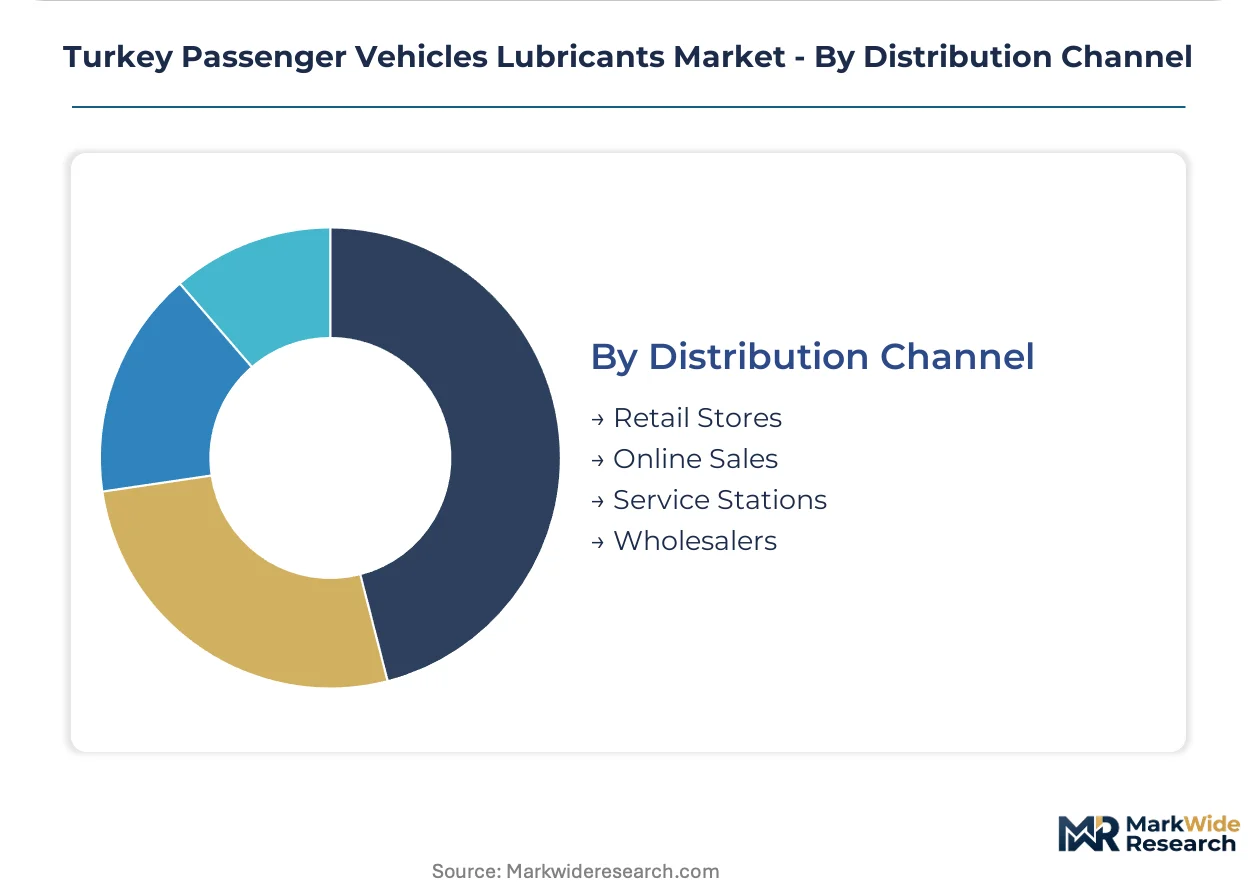
- Service Stations:Integrated refinery-to-retail networks retaining volume leadership through convenience and brand trust. Petrol Ofisi's Marmara corridor presence exemplifies this channel's density advantage.
- Retail Stores:Automotive parts specialists and hypermarkets serving DIY maintenance segments. Younger vehicle owners in urban centers increasingly bypass these for digital alternatives.
- Online Sales:Direct-to-consumer platforms gaining traction among Istanbul and Izmir's digitally native vehicle owners seeking price transparency and specification verification.
- Wholesalers:Bulk supply intermediaries serving independent workshop networks across Central and Eastern Anatolia's fragmented service infrastructure.
Service stations maintain volume leadership; online sales are expanding most quickly among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic blenders are migrating toward higher-grade formulations as compliance costs widen between Turkey's regulatory environment and neighboring markets. Production arbitrage favors integrated refinery networks capable of absorbing certification investments that marginalize smaller competitors.
Marmara Region
Istanbul's dense vehicle parc drives synthetic lubricant procurement through turbocharged engine proliferation and extended service intervals. Turkey's Ministry of Industry and Technology emissions mandates compress workshop conversion timelines in metropolitan service centers. The Izmit-Kocaeli industrial corridor hosts Petrol Ofisi's integrated refining and blending infrastructure serving authorized OEM channels.
Central Anatolia
Ankara's commercial fleet operators negotiate direct supply agreements for bulk synthetic procurement above ten thousand liters annually. Turkish Standards Institution certification requirements create eight-to-twelve week approval windows that favor established blenders with accredited laboratory partnerships. Konya's independent workshop networks represent whitespace for branded synthetic distribution penetration.
Aegean Region
Izmir's younger vehicle owners demonstrate receptivity to e-commerce lubricant channels bypassing traditional service station intermediaries. EU-aligned REACH frameworks mandate reformulation of corrosion inhibitor packages with eighteen-month transition windows. The city's municipal pilot programs test bio-based formulations for sustainability-linked fleet procurement.
Mediterranean Region
Antalya's tourism-dependent commercial vehicle operators maintain intensive maintenance schedules for airport and hospitality logistics. TSE mandatory labeling and performance certification requirements create import quality gates favoring domestic blenders. The Alanya-Manavgat corridor sustains residual mineral oil demand among price-sensitive independent operators.
Black Sea Region
Samsun's port logistics infrastructure positions the city as a distribution node for feedstock imports from Middle Eastern and Mediterranean supply chains. Base oil import dependence exposes regional blenders to volatility in Group III stock availability. Trabzon's mountainous terrain drives seasonal viscosity grade variation in workshop inventory management.
Turkey Passenger Vehicles Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid-compatible formulation development and digital channel integration. The vendor base stratifies across integrated refinery-to-retail networks, international brand licensors, and mid-tier domestic blenders. Three archetypes dominate: scale-driven integrated operators, premium synthetic specialists, and price-competitive regional formulators. Competitive moves concentrate on strategic partnerships with OEM-authorized service centers and backward integration into base oil supply.
Among Turkey-based integrated operators, Petrol Ofisi anchors the domestic refinery-to-retail archetype through Marmara corridor density. BP PLC (Castrol) and Royal Dutch Shell PLC represent international brand licensors competing on formulation technology and logistics infrastructure. These three exemplify how scale and certification capability separate viable competitors from margin-compressed alternatives.
| Leading Market Players |
|---|
| Petrol Ofisi |
| BP PLC (Castrol) |
| Royal Dutch Shell PLC |
| TotalEnergies |
| FUCHS |
| Altinbas Holdings |
| BELGIN Oil |
| ExxonMobil Corporation |
| LUKOIL |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap blenders across Turkey's Marmara corridor anchor supply discipline through generational capital structures that resist short-term margin compression. Their patient ownership timelines align with multi-year TSE certification investments, insulating pricing power against spot-market competitors while passing compliance costs downstream to Istanbul's authorized service networks.
Pricing Analysis
Distributor margin layers in Turkey's lubricant market stratify across three tiers: integrated refinery-to-retail networks capture 18-22 point spreads through captive base oil supply, independent distributors absorb 12-15 point markups serving Central Anatolia workshops, and direct-to-fleet contracts compress intermediaries to 6-8 points for volumes above ten thousand liters annually. Price differentiation hinges on API SP certification grade and documented fuel economy performance under Turkish Standards Institution protocols. Cost compression in mineral formulations is intensifying because TSE's eighteen-month REACH alignment windows force reformulation investments that smaller blenders cannot amortize. Fleet procurement managers show lowest price sensitivity, prioritizing warranty compliance documentation over per-liter savings.
Supply Chain Analysis
Dual-sourcing requirements from Turkey's largest fleet operators mandate qualified supply from at least two Group III base oil origins, typically drawing from Middle Eastern refineries in Saudi Arabia and UAE alongside Mediterranean sources in Spain and Italy. Domestic formulation depends on polyalphaolefin imports from South Korea and corrosion inhibitor packages from German specialty chemical producers. Single-source vulnerability concentrates in high-viscosity index base stocks, where regional geopolitics intermittently disrupt Red Sea transit corridors. Distribution runs through Petrol Ofisi's terminal infrastructure for Istanbul metropolitan coverage, while independent wholesalers maintain inventory buffers in Konya and Sivas for Central Anatolia penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's lubricant market functions as a geographic-arbitrage play where EU-aligned REACH compliance costs exceed those in neighboring Middle Eastern markets, creating export-competent capacity that can serve both regulatory zones. This cost differential rewards blenders with accredited laboratory infrastructure capable of dual-certification production.
For Market Incumbents: Cement API SP and ILSAC GF-6 formulation competency through additive package partnerships with Lubrizol or Infineum, insulating against emerging entrants lacking technical chemistry depth. Lock in backward integration into Group III base oil supply through long-term offtake agreements with Middle Eastern refiners, neutralizing feedstock volatility that threatens margin stability. Prioritize channel control in Ankara's fleet procurement segment where direct supply agreements are displacing traditional distributor relationships. For New Entrants and Emerging Players: Authorized service center partnerships in Izmir and Bursa offer the most penetrable entry vector, as these cities' younger vehicle owners demonstrate receptivity to digital procurement platforms bypassing established service station networks. Target Central Anatolia's independent workshop whitespace where synthetic penetration lags Marmara density by approximately forty points. Deploy e-commerce integration with specification verification tools as the primary go-to-market angle, capturing urban DIY maintenance segments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier domestic blenders with TSE-accredited laboratories but sub-scale distribution reach, as these assets trade below integrated network multiples yet carry embedded regulatory moats. Long-term viability over a five-to-ten year horizon hinges on hybrid-compatible formulation portfolios that extend relevance beyond pure ICE applications. Monitor battery electric vehicle assembly growth within Turkey's domestic automotive sector as the critical inflection signal for combustion-optimized lubricant demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| API SP Certification Investment | TSE laboratory partnerships accelerate product registration timelines against regional competitors. |
| Backward Integration into Group III Supply | Long-term Middle Eastern offtake agreements neutralize feedstock cost volatility exposure. |
| Hybrid-Compatible Formulation Development | Dual-clutch thermal stability profiles capture OEM warranty channels beyond conventional ICE products. |
| E-Commerce Channel Integration | Direct-to-consumer platforms penetrate Istanbul's digitally native vehicle owner segments. |
| Fleet Procurement Consolidation | Direct supply agreements above ten thousand liters annually bypass distributor markups. |
Research Methodology
Multiple input streams — primary interviews with lubricant blenders and fleet procurement managers, secondary validation through TSE certification databases and customs trade records, and technical specification analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned refinery operations directors at Petrol Ofisi, aftermarket distributors in Konya and Sivas, OEM-authorized service center operators in Istanbul, and commercial fleet managers at Ankara-based logistics consolidators. Secondary sources included Turkish Standards Institution product registries, REACH compliance documentation, and vehicle production data from Turkey's automotive assembly sector.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning formulation type, viscosity grade tier, distribution channel structure, and regional vehicle density clusters. CAGRs were derived from trend extrapolation of synthetic adoption rates, turbocharged engine penetration in the Turkish parc, and regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated TSE certification approval windows and OEM service interval extension requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery electric vehicle substitution rates and Middle Eastern base oil supply disruptions. Forecasts reflect documented assumptions regarding regulatory alignment pace and fleet modernization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Forging Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Hydraulic Lash Adjuster Market