
 Lug Wrench Market | 2026-2036
Lug Wrench Market Size, Share, and Industry Trends Forecast 2026-2036
Lug Wrench Market Analytics
Skilled tool-and-die labor scarcity in North American manufacturing is rotating procurement strategies toward higher-durability lug wrench platforms. Stanley Black & Decker leverages its vertical integration into forged steel production to sustain margin control across retail and industrial channels. GearWrench competes through ratcheting mechanism specialization that anchors its position in professional repair shop segments.
A lug wrench is a mechanical torque application device, typically forged from chrome-vanadium or alloy steel with heat-treated socket heads rated for specific foot-pound tolerances, designed to tighten or loosen wheel lug nuts on vehicles and industrial equipment. Manual lug wrenches retain volume leadership in emergency roadside and consumer DIY segments where portability and zero power dependency outweigh speed requirements. Impact wrenches command premium positioning in commercial fleet and OEM settings where pneumatic or battery-driven systems compress tire change cycles. Carbon fiber and composite variants are gaining traction among motorsport and aerospace ground crews where mass reduction justifies elevated unit economics.
The US NHTSA maintains wheel retention standards that indirectly govern lug wrench torque specification compliance across OEM assembly protocols. REACH and RoHS frameworks in Europe restrict hexavalent chromium coatings on tool surfaces, pushing suppliers toward nickel-tungsten or ceramic conversion finishes. China's SAMR enforces GB standards on tool steel certification that filter import eligibility. Stakeholders must monitor evolving torque precision requirements from electric vehicle manufacturers whose heavier battery architectures demand revised fastening protocols.
Market Dynamics
The electric vehicle transition is rewriting fastening specifications, as battery pack weights of 500-800 kilograms demand torque protocols that legacy lug wrench platforms cannot reliably deliver. OEM assembly lines now require recalibrated tool fleets.
Growth Catalysts
- GB Standard Certification:China's SAMR enforcement of upgraded tool steel standards is filtering supplier pools and elevating procurement thresholds for qualified manufacturers.
- EV Assembly Automation:Automotive OEMs are deploying impact wrench arrays on electric vehicle production lines, compressing tire mounting cycles.
- Stuttgart-Wolfsburg Corridor:Germany's automotive supplier concentration is anchoring premium tool demand for just-in-time manufacturing ecosystems.
Market Restraints
- Alloy Steel Volatility:Chrome-vanadium input costs fluctuate with nickel and molybdenum spot markets, squeezing margin predictability for forged tool producers.
- REACH Coating Restrictions:ECHA limitations on hexavalent chromium surface treatments force costly conversion to nickel-tungsten or ceramic finishes.
- Pneumatic Infrastructure Dependency:Commercial impact wrench adoption requires compressed air systems that smaller fleet operators lack capital to install.
Strategic Opportunities
- Battery-Electric Commercial Fleets:Heavy-duty EV trucks entering service in California and the EU create demand for high-torque fastening platforms rated for commercial wheel loads.
- Carbon Fiber Composite Tools:Motorsport ground crews are adopting mass-reduced lug wrenches where gram savings justify 3-4x unit cost premiums.
- IRA Domestic Content Incentives:US tool manufacturers capturing forged steel production within North American supply chains qualify for clean vehicle tax credit pass-through benefits.
Industry Challenges
- Tool-and-Die Labor Scarcity:North American forging operations face 15-20% vacancy rates in heat-treatment and CNC programming roles, constraining output scaling.
- ISO 6789 Calibration Timelines:Torque wrench recertification cycles for professional repair shops create administrative burden and temporary tool retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lug Wrench Market |
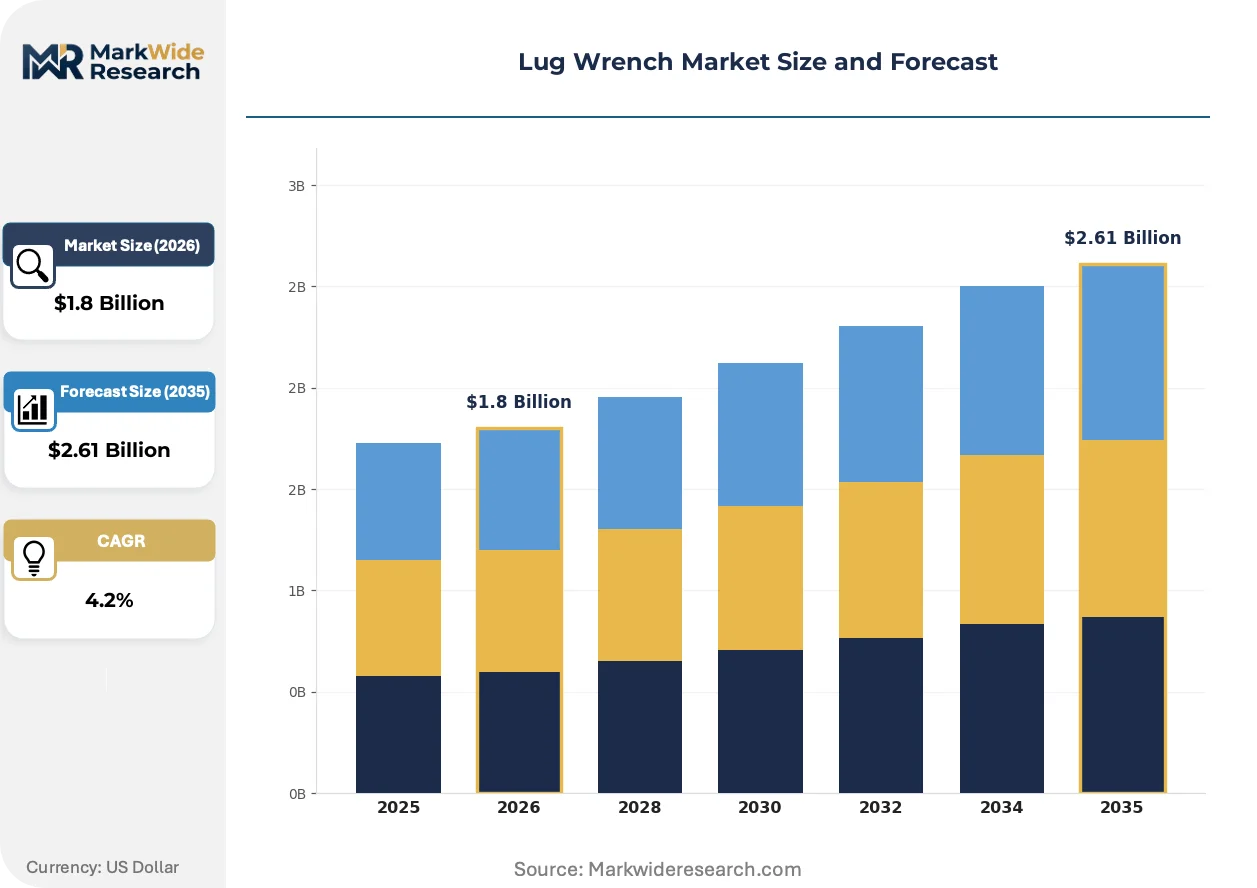
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Lug Wrench, Impact Wrench, Electric Lug Wrench, Pneumatic Wrench End User: Automobile OEMs, Repair Shops, DIY Enthusiasts, Fleet Operators Material: Steel, Aluminum, Carbon Fiber, Composite Usage Type: Personal, Commercial, Industrial, Emergency |
| Companies Covered | Stanley Black & Decker, Ken-Tool, SATA, Performance Tool, GearWrench, TEKTON, Hazet, Proto, Williams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lug Wrench Market Evolving Landscape
Tool intelligence and material science are converging to redefine performance benchmarks. Connected torque systems and advanced alloys are displacing legacy mechanical platforms across professional segments.
Battery-powered impact platforms with integrated torque feedback are decomposing pneumatic tool dominance in commercial fleet maintenance. Mid-size logistics operators in the US Midwest are adopting 20-volt cordless systems that eliminate compressor infrastructure. This shift is compressing the addressable market for traditional air-driven assemblies and rewiring distributor inventory priorities toward battery ecosystem compatibility.
REACH and RoHS frameworks are mandating elimination of hexavalent chromium conversion coatings on tool surfaces. European suppliers are migrating to nickel-tungsten electrodeposits and ceramic-based alternatives that maintain corrosion resistance. Professional repair chains in Germany and France are now specifying RoHS-compliant finishes as mandatory procurement criteria, filtering non-compliant Asian imports from qualified vendor lists.
Direct-to-fleet procurement models are bypassing traditional automotive aftermarket distributors. Large commercial operators with 500-plus vehicle fleets are negotiating volume contracts with tool manufacturers for standardized platforms. This pattern is most pronounced in California's Central Valley agricultural trucking sector, where consolidated procurement is compressing channel margins and forcing distributor consolidation.
Lug Wrench Market Segmentation
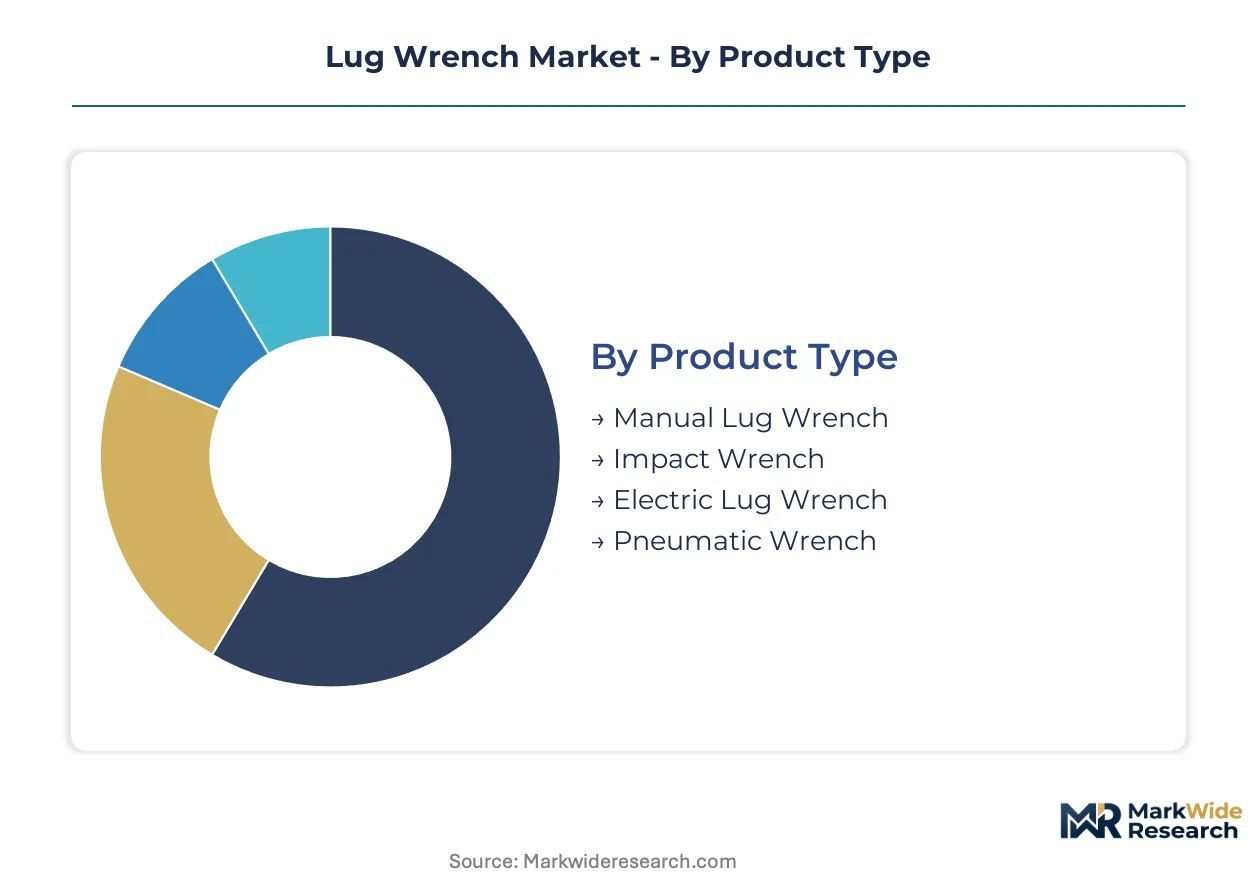
Lug wrench segmentation reveals divergent margin architectures across mechanical, powered, and advanced material platforms. Procurement patterns split sharply between price-sensitive consumer channels and specification-driven industrial contracts.
Product Type:
Premium margins concentrate in powered fastening systems where torque precision and automation compatibility command price multiples over mechanical alternatives.
- Manual Lug Wrench:Forged chrome-vanadium or alloy steel construction with heat-treated socket heads delivers specified foot-pound tolerances without power dependency. Demand clusters in emergency roadside kits and consumer DIY segments across the US and Germany, where portability requirements override speed considerations.
- Impact Wrench:Pneumatic or battery-driven systems compress tire change cycles through high-torque impulse delivery. OEM assembly lines in Stuttgart and Wolfsburg anchor commercial demand, with battery-electric platforms displacing compressed air infrastructure in mid-size US fleet operations.
- Electric Lug Wrench:Corded and cordless motor platforms serve hybrid applications requiring sustained torque without pneumatic infrastructure. European repair chains specify these for workshop environments where noise restrictions apply.
- Pneumatic Wrench:Compressed air systems dominate high-volume commercial tire service bays. Capital requirements for compressor installation limit adoption among smaller fleet operators in North America.
The dominant share belongs to Manual Lug Wrench, while Impact Wrench is closing the gap fastest.
End User:
Volume scale tilts toward consolidated procurement by large fleet operators and OEMs, fragmenting across dispersed consumer and small-shop channels.
- Automobile OEMs:Assembly line procurement demands calibrated tool fleets with ISO 6789 traceability and EV-compatible torque protocols. China's SAMR GB standard enforcement filters qualified suppliers for electric vehicle production.
- Repair Shops:Professional maintenance facilities require ratcheting mechanisms and torque feedback systems. Labor scarcity in North American tool-and-die operations rotates procurement toward durability-rated platforms.
- DIY Enthusiasts:Price-sensitive consumers prioritize portability and storage efficiency over precision specifications. Retail distribution concentrates through mass-market channels.
- Fleet Operators:Commercial vehicle pools with standardized maintenance protocols negotiate direct manufacturer contracts. California agricultural trucking consolidators exemplify this procurement pattern.
Automobile OEMs capture the largest revenue pool, though Fleet Operators are expanding most quickly through direct contracting models.
Material:
Input cost volatility in alloy metals creates margin pressure points distinct from stable-price aluminum and premium-priced composites.
- Steel:Chrome-vanadium and alloy grades dominate forged tool production. Nickel and molybdenum spot market fluctuations compress margin predictability for heat-treated socket manufacturers.
- Aluminum:Lightweight corrosion-resistant variants serve consumer and marine applications where mass reduction carries secondary priority.
- Carbon Fiber:Mass-reduced construction justifies unit cost premiums in motorsport ground crews. Gram savings in pit stop operations drive adoption despite 3-4x pricing multiples.
- Composite:Engineered polymer matrices with fiber reinforcement target aerospace ground handling and specialized industrial mobility.
Steel maintains volume leadership, while Carbon Fiber climbs the fastest on motorsport and aerospace specification expansion.
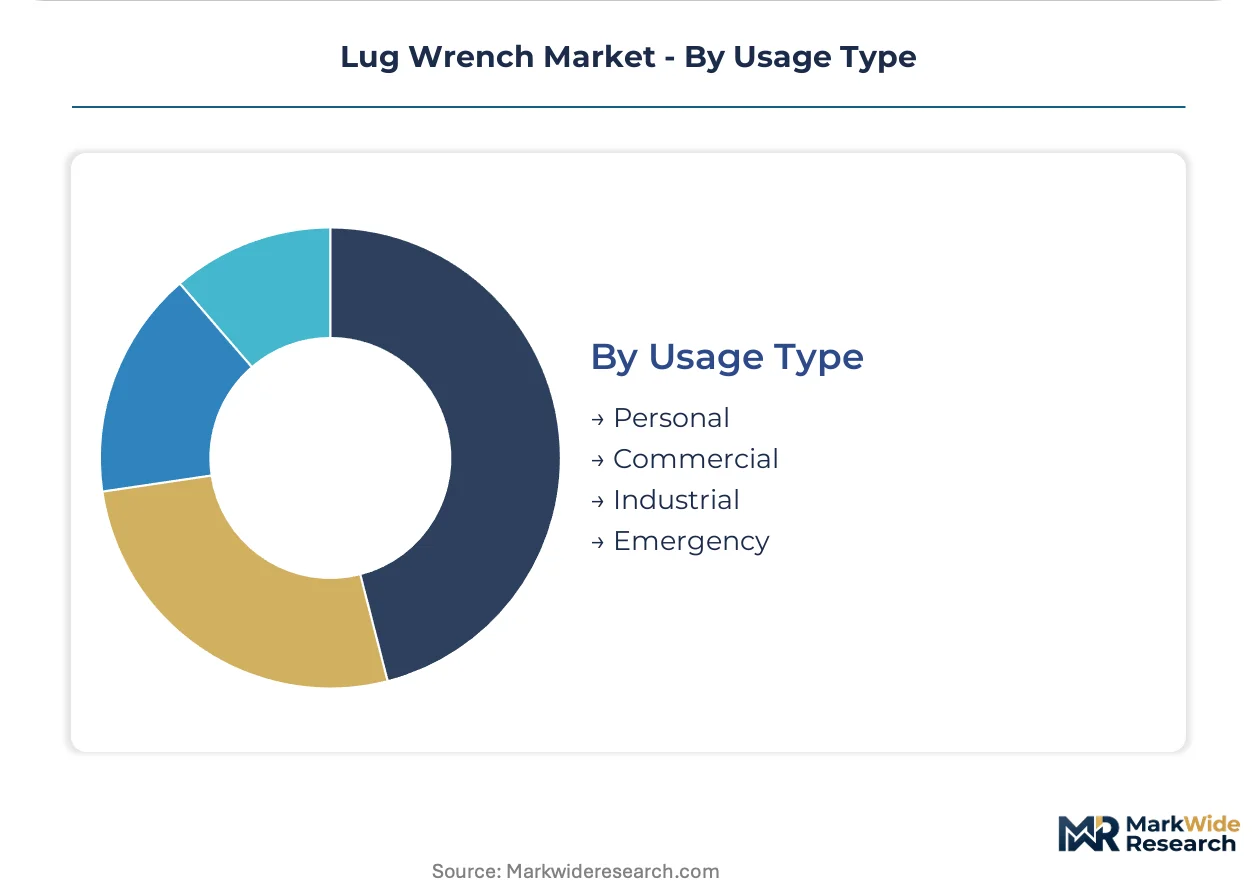
Usage Type:
Regulatory compliance burdens and calibration requirements concentrate in commercial and industrial categories, elevating barriers against personal and emergency segments.
- Personal:Consumer-owned tools for occasional vehicle maintenance prioritize cost minimization and storage convenience.
- Commercial:Fleet and rental operations require documented torque compliance and periodic recertification cycles. ECHA REACH coating restrictions mandate nickel-tungsten or ceramic finishes for European-qualified vendor lists.
- Industrial:Heavy-equipment and manufacturing applications demand sustained duty-cycle performance under load. OSHA workplace safety protocols govern tool selection in US manufacturing environments.
- Emergency:Roadside assistance and first-responder kits emphasize reliability under uncontrolled conditions. Zero power dependency shapes specification requirements.
Commercial usage anchors revenue concentration, with Industrial applications gaining share fastest on manufacturing automation and EV assembly line expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor consumes impact wrenches at triple the per-capita rate of DIY-heavy US retail channels, while China's GB-certified production lines drive specification divergence between export and domestic tooling standards.
United States
Mid-size logistics operators across the Midwest are adopting 20-volt cordless impact systems that eliminate compressor infrastructure entirely. OSHA workplace safety protocols govern tool selection in manufacturing environments. California's Central Valley agricultural trucking consolidators negotiate direct manufacturer contracts for standardized fleet maintenance platforms.
Germany
Professional repair chains specify RoHS-compliant nickel-tungsten finishes as mandatory procurement criteria, filtering non-compliant imports from qualified vendor lists. ECHA REACH coating restrictions mandate surface treatment conversions. Stuttgart and Wolfsburg anchor premium tool demand for just-in-time automotive manufacturing ecosystems.
China
Automotive OEM procurement of impact wrenches for electric vehicle assembly lines is strengthening order volumes from qualified suppliers. SAMR enforcement of upgraded GB tool steel standards filters import eligibility and elevates procurement thresholds. Yangtze River Delta manufacturing clusters are retooling heat-treatment capacity to meet certification requirements.
Japan
Precise torque protocols for battery-electric vehicle assembly drive demand for calibrated tool fleets with ISO 6789 traceability. METI industrial standards govern professional-grade tool specifications. Kanto region automotive suppliers are integrating impact wrench arrays into automated tire mounting cells.
Lug Wrench Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on mechanism design and material differentiation. The upper tier controls captive forging capacity and heat-treatment operations, insulating margin structures from alloy steel spot volatility. Mid-cap specialists anchor positions through ratcheting mechanism patents and torque feedback integration. Dominant competitive moves include backward integration into forged steel production and direct-to-fleet contracting that bypasses traditional aftermarket distributors.
Among North American diversified tool manufacturers, Stanley Black & Decker exemplifies the integrated archetype through upstream control over metal forming operations. GearWrench occupies a specialist position emphasizing ratcheting platform refinement for professional repair environments. SATA represents the Asia-based fabrication tier serving both domestic certification requirements and export quality tiers.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Ken-Tool |
| SATA |
| Performance Tool |
| GearWrench |
| TEKTON |
| Hazet |
| Proto |
| Williams |
| Others |
Value Network & Pricing Analysis
Heat-treatment capacity utilization above 85% in Yangtze River Delta forging clusters compresses margin flexibility for mid-tier producers while anchoring price floors for GB-certified tool steel. This scale concentration simultaneously elevates procurement thresholds for automotive OEMs and squeezes non-compliant suppliers from qualified vendor pools.
Pricing Analysis
Long-term offtake contracts dominate procurement between German automotive OEMs and forged steel suppliers, insulating premium tier pricing from nickel-molybdenum spot volatility. Price differentiation rests on GB certification tier and ISO 6789 calibration traceability, with EV-compatible torque protocols commanding substantial premiums. Cost compression in standard-grade mechanical wrenches intensifies as Chinese exports saturate DIY retail channels. Fleet operators exhibit lowest price sensitivity due to standardized maintenance protocols and direct manufacturer contracting.
Supply Chain Analysis
Inbound logistics costs from Shanghai-Ningbo port congestion periodically disrupt alloy steel delivery schedules to North American distributors. Supply concentrates in China, Germany, and Taiwan, with chrome-vanadium billet and heat-treatment furnace capacity as critical input dependencies. Single-source vulnerability in Yangtze River Delta forging clusters exposes downstream buyers to GB standard enforcement disruptions. Distribution runs through automotive aftermarket distributors, though direct-to-fleet contracting is compressing channel margins in California and EU commercial vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle transition constitutes a high-growth disruption, with battery pack weight specifications forcing complete tool fleet recalibration across OEM assembly lines. This technological inflection compresses replacement cycles and elevates certification barriers simultaneously.
For Market Incumbents: Fortify captive heat-treatment capacity in Stuttgart-Wolfsburg corridor operations to defend margin structures against alloy steel spot volatility. Accelerate backward integration into forged steel production to qualify for IRA domestic content incentives. Prioritize GB standard pre-certification for Yangtze River Delta facilities before SAMR enforcement tightens supplier pools further.
For New Entrants and Emerging Players: GB standard fast-track certification unlocks entry into Chinese EV assembly line procurement, the most penetrable premium segment. Target carbon fiber composite platforms for motorsport ground crews where gram savings justify elevated unit economics. Pursue direct-to-fleet contracting models in California agricultural trucking to bypass entrenched aftermarket distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated forging operations with captive heat-treatment capacity and established OEM qualification. Long-term viability hinges on EV torque protocol adaptation and regulatory certification moats. Monitor SAMR GB enforcement intensity as inflection indicator for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Pre-Certification | SAMR enforcement filters qualified suppliers for Chinese EV production lines. |
| Backward Integration into Forged Steel | Captive production secures IRA domestic content incentives for US manufacturers. |
| Carbon Fiber Composite Platform Launch | Motorsport ground crews adopt mass-reduced tools despite 3-4x cost premiums. |
| Direct-to-Fleet Contracting Model | California agricultural trucking consolidators bypass traditional aftermarket distributors. |
| ISO 6789 Calibration Service Expansion | Professional repair chains require documented torque compliance and periodic recertification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with automotive OEM procurement officers, Tier 1 supplier quality directors, aftermarket distributor category managers, and professional repair shop owners; and secondary validation against SAMR GB standard filings, NHTSA wheel retention documentation, ECHA REACH restriction updates, and customs trade data for chrome-vanadium billet flows. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Across the analysis window, projections incorporated product type segmentation by power source and torque delivery mechanism, end-user concentration by fleet scale and OEM tier, and material grade stratification. CAGRs derived from regression analysis of historical procurement volumes against EV production ramp schedules and regulatory compliance timelines. Forecast inputs weighted battery-electric commercial fleet penetration and heat-treatment capacity expansion in Yangtze River Delta clusters.
Underlying assumptions cover sustained EV assembly line automation, GB standard enforcement continuity, and alloy steel spot price band stability, with deviation risk concentrated in SAMR certification timeline acceleration or nickel-molybdenum supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Car Rack Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market