
 Automotive Steel Market | 2026-2036
Automotive Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steel Market Analysis
European integrated mills is repositioning capacity toward automotive-certified coated products as legacy blast furnace routes face carbon cost pressure. ArcelorMittal leverages its Gent and Bremen sites to supply OEM-certified advanced high-strength grades across premium platform programs. China BaoWu Steel Group Corporation Limited anchors its expansion through captive supply of dual phase and martensitic grades to domestic EV assemblers. POSCO competes on tight thickness tolerance for exposed body panels, sustaining technical leadership in South Korea's automotive export chain.
Automotive steel encompasses flat and long carbon steel products engineered to precise tensile strength, formability, and surface quality specifications for vehicle manufacturing, typically produced through continuous casting followed by hot rolling, cold rolling, and annealing sequences to achieve microstructures suited to crash-energy management. Cold rolled steel commands margin pools in exposed body applications where surface finish requirements exclude cheaper hot rolled alternatives, while advanced high strength grades within the grade taxonomy represent the fastest-growing category as OEMs pursue mass reduction without sacrificing structural integrity. Body structure applications dominate volume offtake, though engine components demand specialized alloy formulations that resist thermal fatigue under turbocharged combustion cycles.
The EPA enforces Corporate Average Fuel Economy standards that implicitly penalize vehicle mass, pushing Detroit automakers toward high-strength low alloy substitutions in body-in-white assemblies. ECHA administers REACH restrictions on hexavalent chromium conversion coatings, forcing mills to certify alternative passivation chemistries for corrosion-resistant automotive sheet. China's MIIT mandates new energy vehicle production quotas that reshape grade demand toward lighter, stronger substrates. Stakeholders must monitor how carbon border adjustment mechanisms in Europe and North America reroute trade flows for semi-finished automotive steel inputs.
Market Dynamics
Platform electrification is compressing traditional grade hierarchies as EV chassis architectures demand novel strength-to-weight ratios that legacy mild steel formulations cannot satisfy. This structural force is redrawing procurement criteria across OEM engineering departments and tier-one stamping operations worldwide.
Growth Catalysts
- EPA CAFE standards:Implicit mass penalties in US fuel economy regulations force Detroit automakers toward advanced high-strength substitutions in body-in-white assemblies.
- China MIIT NEV quotas:Domestic production mandates for new energy vehicles redirect substrate demand toward lighter, stronger steel grades for battery enclosure structures.
- Third-generation advanced high-strength steels:Twinning-induced plasticity grades enable 20-30% mass reduction in crash-critical pillars without sacrificing formability.
Market Restraints
- Iron ore and scrap volatility:Input cost swings compress margin predictability for flat-rolled automotive products, particularly at integrated mills dependent on seaborne raw materials.
- European supply concentration:Blast furnace capacity retirement in Germany and the Netherlands is tightening certified automotive sheet availability ahead of EV ramp schedules.
- Aluminum substitution in closures:Hood and door applications above 1.2m² surface area increasingly specify 5000-series aluminum extrusions for mass-critical premium platforms.
Strategic Opportunities
- India automotive corridor expansion:Tamil Nadu and Gujarat manufacturing clusters lack localized supply of press-hardened ultra-high-strength grades for emerging SUV platforms.
- EU Green Deal carbon border adjustments:Embodied-carbon thresholds for imported flat steel create first-mover advantage for mills with electric arc furnace or hydrogen-reduction certification.
- Digital twin integration with metallurgical modeling:Convergence of finite element crash simulation and microstructure prediction tools accelerates grade qualification timelines from 18 to 8 months.
Industry Challenges
- Automotive metallurgy expertise scarcity:Retirement waves among senior annealing process engineers constrain quality assurance at mills expanding into third-generation grades.
- OEM certification timeline compression:Dual-phase and complex-phase grade approvals now require 40% more physical crash-test validation cycles despite compressed platform development schedules.
- Legacy ERP integration with carbon accounting systems:Mill-level traceability requirements for Scope 3 disclosure create data architecture friction with 1990s-era production planning software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steel Market |
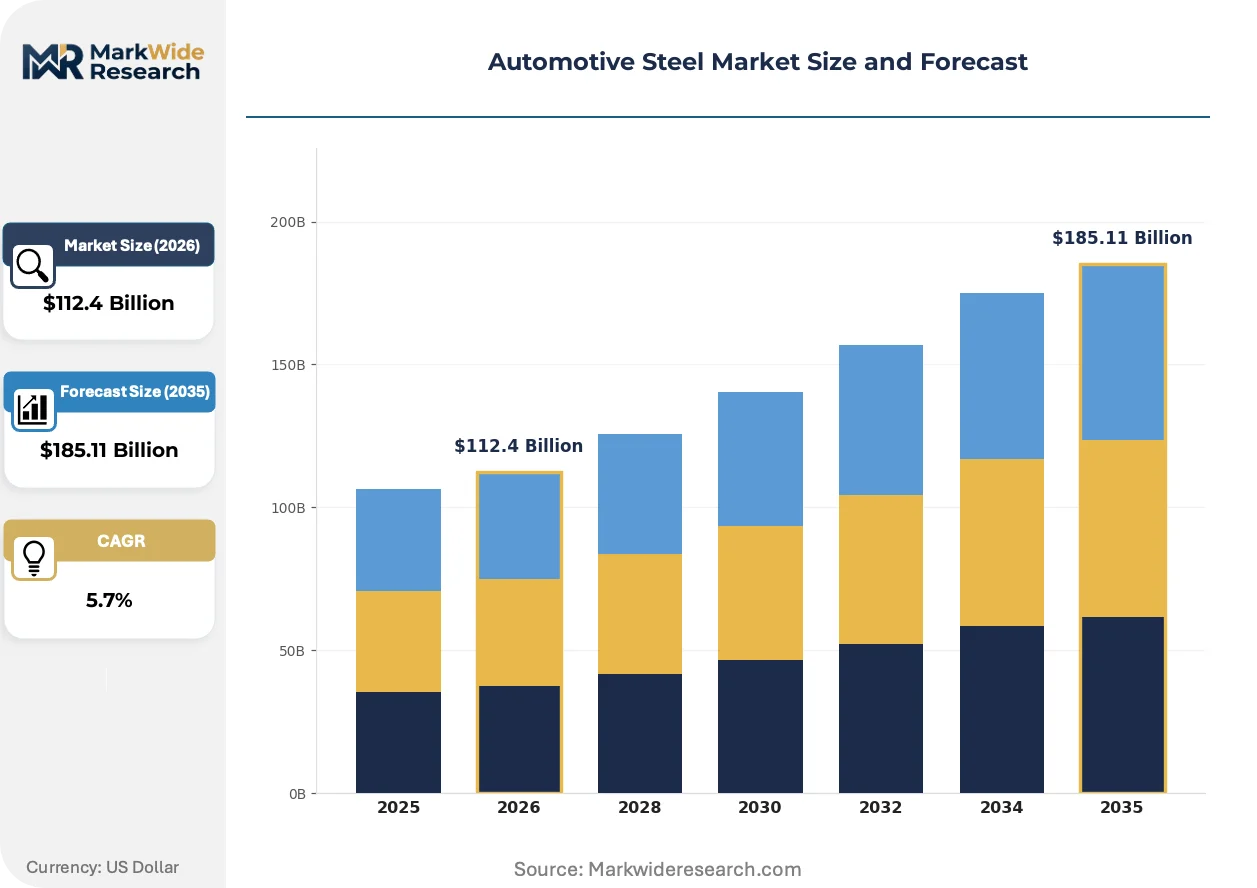
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $185.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled Steel, Cold Rolled Steel, Stainless Steel, Alloy Steel Application: Body Structure, Chassis, Engine Components, Suspension Parts Grade: High Strength Low Alloy, Dual Phase, Martensitic, Advanced High Strength End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | ArcelorMittal, China BaoWu Steel Group Corporation Limited, Nippon Steel Corporation, POSCO, JFE Steel Corporation, Nucor, Hyundai Steel, Thyssenkrupp, United States Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steel Market Emerging Trajectories
Active transformation in automotive steel centers on microstructural engineering breakthroughs, regulatory carbon accounting mandates, and procurement centralization around platform-scale supply agreements rather than spot purchasing.
Press-hardened boron-manganese steels with tailored tempering properties enable single-piece hot-stamped B-pillar designs that replace multi-part welded assemblies. European and Chinese EV assemblers are adopting these grades at twice the rate of North American incumbents. The technology is expanding into battery tray structures and cross-car beams where torsional rigidity requirements exceed 25,000 Nm/degree.
REACH restrictions on hexavalent chromium conversion coatings administered by ECHA have eliminated traditional passivation chemistries from Q4 2024 qualification programs. Mills must now certify trivalent chromium or zirconium-based alternatives through extended corrosion-cycle testing. Exposed body panel applications in Germany and Sweden face the steepest compliance timelines, with some OEMs accepting 15% surface-finish variation during transition periods.
Consolidated platform sourcing agreements now cover 60-70% of OEM steel offtake, displacing fragmented mill-direct purchasing that dominated prior decades. Tier-one stamping suppliers in South Korea and Mexico are absorbing inventory risk through consignment structures that shift working capital burden downstream. This concentration is most visible in battery electric vehicle programs where single-source qualification for advanced high-strength grades reduces supplier count from twelve to four per platform.
Automotive Steel Market Segmentation
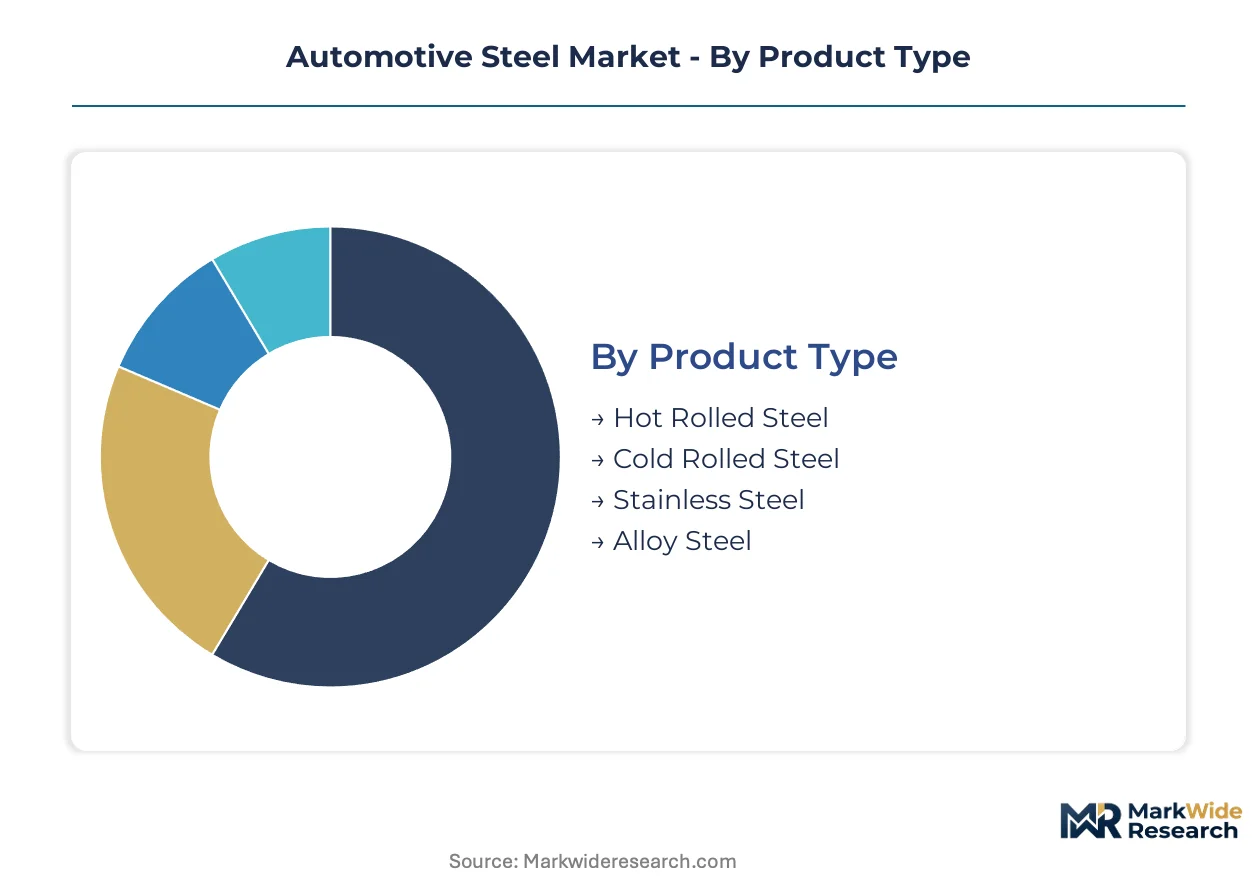
Automotive steel procurement decisions cascade through four distinct taxonomies: product form determines processing cost, application dictates performance specification, grade governs structural capability, and end-user category shapes contract structure and inventory liability.
Product Type:
Volume concentrates in commodity flat-rolled formats, while premium margin pools accrue to precision-finished grades with certified surface quality.
- Cold Rolled Steel:Produced through cold reduction below recrystallization temperature to achieve tight dimensional tolerances and superior surface finish. Exposed body panel programs in Germany's automotive manufacturing corridor specify cold rolled substrates exclusively, driven by OEM aesthetic standards that reject orange peel or roll mark defects visible through paint layers.
- Hot Rolled Steel:Manufactured via continuous casting and hot rolling above recrystallization temperature, yielding lower-cost substrates with acceptable dimensional variance for concealed structural applications. Chassis rail and crossmember production in China's EV assemblers consumes hot rolled tonnage at scale, constrained by battery platform cost targets that prioritize mass over cosmetic perfection.
- Stainless Steel:Chromium-alloyed grades resisting corrosion in exhaust system manifolds and decorative trim applications.
- Alloy Steel:Engineered with precise carbon and microalloy additions for thermal fatigue resistance in powertrain components.
Today's leader: Cold Rolled Steel. Tomorrow's challenger: Hot Rolled Steel.
Application:
Structural mass reduction priorities are compressing traditional application hierarchies as platform electrification rewrites load path engineering.
- Body Structure:Body-in-white assemblies including pillars, rails, and floor pans that manage crash energy absorption and occupant compartment integrity. Battery electric vehicle architectures in South Korea demand redesigned body structure substrates with 30% higher strength-to-weight ratios than internal combustion platforms, driven by battery mass penalties that cascade through chassis load calculations.
- Chassis:Frame rails, subframes, and suspension attachment points transmitting road loads while isolating powertrain vibration. European OEMs are consolidating chassis steel specifications across modular electric platforms, constrained by REACH-compliant coating chemistries that extend qualification timelines for new grade introductions.
- Engine Components:Cylinder blocks, crankshafts, and connecting rods requiring fatigue resistance under thermal cycling.
- Suspension Parts:Control arms, springs, and stabilizer bars subject to cyclic loading and corrosion exposure.
Body Structure commands current volume primacy. Chassis applications are climbing the fastest as EV platform architectures proliferate.
Grade:
Material selection criteria are migrating from formability-centric specifications toward strength-dominated performance envelopes.
- Advanced High Strength:Multi-phase microstructures including dual phase, complex phase, and transformation-induced plasticity grades achieving tensile strengths above 980 MPa with retained formability. Battery enclosure structures in China's MIIT-regulated NEV programs specify advanced high strength grades exclusively, driven by crashworthiness mandates for battery pack protection under pole and side-impact protocols.
- Dual Phase:Ferrite-martensite microstructures combining high initial work hardening with excellent stretch flangeability for draw-formed components. North American pickup truck bed manufacturing consumes dual phase tonnage at volume, constrained by EPA CAFE implicit mass penalties that discourage reverting to mild steel alternatives.
- High Strength Low Alloy:Microalloyed carbon steels offering moderate strength elevation through precipitation hardening.
- Martensitic:Fully hardened microstructures delivering ultimate tensile strength above 1200 MPa for anti-intrusion applications.
Advanced High Strength anchors current procurement focus. Dual Phase grades are gaining share fastest as stamping process windows expand.
End User:
Contractual risk allocation diverges sharply between direct OEM relationships and tiered supply chain intermediation.
- OEMs:Vehicle manufacturers specifying steel grades directly and managing mill qualification programs. Germany's premium OEMs maintain dedicated technical teams at ArcelorMittal Gent and Bremen sites, driven by platform-scale sourcing agreements that consolidate 60-70% of steel offtake under single-source structures.
- Tier-1 Suppliers:Stamping and component manufacturers absorbing inventory risk through consignment arrangements. Mexican automotive corridor tier-1 operations are accepting extended payment terms and consignment liability, constrained by OEM pressure to shift working capital burden downstream.
- Vehicle Assemblers:Contract manufacturing operations with limited grade specification authority.
- Aftermarket Providers:Collision repair and restoration suppliers sourcing certified equivalent grades for replacement panels.
OEMs dominate specification control today. Tier-1 Suppliers represent the steepest expansion trajectory as platform sourcing consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-mandated NEV quotas are compressing grade demand timelines faster than Germany's REACH-compliant coating transitions, creating divergent procurement pressures across the two largest automotive steel markets.
China
Battery enclosure structures for domestic EV assemblers are driving dual-phase and martensitic grade consumption at scale. MIIT production mandates for new energy vehicles redirect substrate specifications toward lighter, stronger steel grades. The Yangtze River Delta manufacturing corridor anchors captive supply relationships between BaoWu mills and platform-scale battery electric vehicle programs.
Germany
Premium OEM body-in-white programs specify cold-rolled advanced high-strength grades exclusively for exposed panel applications. ECHA REACH restrictions on hexavalent chromium conversion coatings force mills to certify trivalent chromium alternatives through extended corrosion-cycle testing. The automotive manufacturing corridor spanning Bavaria and Baden-Württemberg concentrates ArcelorMittal Gent and Bremen supply relationships.
United States
Detroit automakers face implicit mass penalties under EPA CAFE standards that push body-structure specifications toward high-strength low-alloy substitutions. NHTSA crashworthiness protocols maintain qualification barriers for third-generation advanced high-strength grade adoption. The Midwest manufacturing belt spanning Michigan and Ohio retains concentrated stamping capacity for pickup truck and SUV platforms.
South Korea
Battery electric vehicle architectures demand redesigned body-structure substrates with elevated strength-to-weight ratios compared to internal combustion platforms. MFDS-administered industrial standards govern surface quality certification for exposed panel applications. The Busan-Ulsan industrial corridor sustains POSCO's technical leadership in tight thickness tolerance for automotive export chains.
India
Tamil Nadu and Gujarat manufacturing clusters lack localized supply of press-hardened ultra-high-strength grades for emerging SUV platform ramp schedules. BIS automotive steel standards are tightening certification requirements for crash-critical structural applications. The Delhi-Mumbai Industrial Corridor is attracting mill investment in coated flat-rolled capacity to serve Maruti Suzuki and Hyundai Motor India expansion plans.
Automotive Steel Market Vendor Landscape
European integrated mills anchor one tier through OEM-certified coated products; East Asian specialists hold technical leadership in tight-tolerance exposed panel grades. Market structure consolidates around platform-scale sourcing agreements that displace fragmented mill-direct purchasing. Three archetypes dominate: blast-furnace integrated producers repositioning toward automotive-certified output, electric-arc furnace operators pursuing carbon-accounting advantages, and state-backed national champions serving captive domestic demand. Competitive moves center on hydrogen-reduction certification for EU Green Deal compliance and digital twin integration to compress grade qualification timelines.
Within the integrated-mill tier, ArcelorMittal represents European capacity repositioning toward automotive-certified coated products. China BaoWu Steel Group Corporation Limited exemplifies state-backed vertical integration into captive EV-grade supply. POSCO occupies a position of technical specialization in surface-critical exposed body panel applications. These three entities collectively illustrate the geographic and technological fault lines reshaping procurement relationships across major automotive manufacturing corridors.
| Leading Market Players |
|---|
| ArcelorMittal |
| China BaoWu Steel Group Corporation Limited |
| Nippon Steel Corporation |
| POSCO |
| JFE Steel Corporation |
| Nucor |
| Hyundai Steel |
| Thyssenkrupp |
| United States Steel Corporation |
| Others |
Supply Flow & Price Mechanics
Iron ore futures volatility cascades through automotive steel pricing tiers, compressing margins at integrated mills while rewarding electric arc furnace operators with scrap-cost stability. The spread between seaborne raw material exposure and circular feedstock sourcing now separates premium-certified coated products from commodity-grade alternatives.
Pricing Analysis
Direct-to-OEM contract discounts dominate volume transactions, with tier-one stamping suppliers absorbing inventory risk through consignment structures. Price differentiation rests on REACH-compliant coating certification and tight thickness tolerance for exposed body panels. Cost compression in hot-rolled chassis grades is intensifying because battery platform cost targets prioritize mass over surface finish. Tier-one suppliers in Mexico's automotive corridor exhibit highest price sensitivity, while Germany's premium OEMs accept premium positioning for mill-direct relationships.
Supply Chain Analysis
Single-source vulnerability sits with blast furnace capacity concentrated in Germany and the Netherlands, where certified automotive sheet availability tightens ahead of EV ramp schedules. Geographic supply concentration centers on China, South Korea, and Germany for advanced high-strength grades. Raw material dependencies draw from Australian iron ore, Brazilian pellets, and Turkish scrap. Tariff exposure on semi-finished inputs creates rerouting pressure under carbon border adjustment mechanisms. Distribution runs through platform-scale sourcing agreements that consolidate sixty to seventy percent of OEM offtake under single-source structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive steel functions as a stable compounder, with platform electrification driving steady grade migration toward advanced high-strength specifications.
For Market Incumbents: Lock in captive supply relationships with domestic EV assemblers before hydrogen-reduction certification becomes mandatory under EU Green Deal thresholds. ArcelorMittal's Gent and Bremen positioning illustrates how OEM-certified coated products defend against aluminum substitution in closures. Prioritize electric arc furnace or hydrogen-based direct reduction investments to secure carbon-accounting advantages. For New Entrants and Emerging Players: The price-point gap between premium cold-rolled exposed grades and economy hot-rolled chassis substrates offers entry traction. India's Tamil Nadu and Gujarat manufacturing clusters lack localized press-hardened ultra-high-strength supply, creating white-space for qualified entrants. Target battery enclosure structures with MIIT-compliant dual-phase grades, leveraging digital twin integration to compress qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with electric arc furnace operators possessing hydrogen-reduction certification pathways. Long-term viability favors mills with Scope 3 traceability infrastructure and platform-scale OEM relationships. Watch for carbon border adjustment mechanism implementation as inflection indicator for trade flow rerouting.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Based Direct Reduction Certification | EU Green Deal compliance secures premium positioning for German and Dutch mill output. |
| Platform-Scale Supply Agreement | Single-source consolidation reduces supplier count from twelve to four per battery electric vehicle program. |
| Digital Twin Integration | Finite element crash simulation convergence accelerates grade qualification from eighteen to eight months. |
| Scrap-Based Circular Feedstock Sourcing | Turkish and domestic scrap supply anchors cost stability against seaborne iron ore volatility. |
| REACH-Compliant Coating Transition | Trivalent chromium alternatives replace hexavalent passivation for ECHA-administered corrosion certification. |
Methodological Framework
Direct dialogue with OEM platform engineers, tier-one supplier procurement leads, mill technical directors, and aftermarket distributors grounded qualitative assessment in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from listed steel producers, and ECHA REACH substance restriction updates. Bottom-up grade demand modeling and top-down capacity triangulation converged on volume estimates.
Segmentation outputs reflect disaggregation across propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating MIIT NEV quota trajectories and EPA CAFE implicit mass penalties. Third-generation advanced high-strength steel adoption curves and press-hardened boron-manganese penetration rates informed grade-specific growth differentials.
Caveats apply where iron ore and scrap volatility, blast furnace retirement acceleration, or aluminum substitution thresholds could materially shift the outlook. Forecasts embed assumptions about regulatory timeline adherence and platform development schedule integrity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Air Brake Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Automotive Bellows Market