
 Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market | 2026-2036
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market Outlook
Aftermarket service revenue for HPDC component repair and remanufacturing is rewriting traditional profit pools in automotive supply chains. Nemak leverages its vertical casting-to-assembly model to capture value from EV platform contracts across multiple continents. Rheinmetall AG sustains defense-to-automotive technology transfer that strengthens its position in structural aluminum castings. Georg Fischer Limited anchors premium supply relationships with European OEMs through precision cold-chamber capabilities.
Automotive aluminum parts high pressure die casting is a metal-forming process where molten aluminum alloy is injected into a hardened steel die at pressures exceeding 1,000 bar to produce complex, thin-walled components with tight dimensional tolerances. The process yields parts with excellent strength-to-weight ratios, enabling vehicle mass reduction critical to fuel efficiency and electric range targets. Transmission housings represent the most mature product category, while chassis components for electric vehicles command the fastest growth trajectory as skateboard platforms multiply. Among applications, electric vehicles absorb the highest growth rate of HPDC capacity, though passenger vehicles still dominate absolute volume demand from Tier-1 suppliers.
The US EPA Corporate Average Fuel Economy standards and the EU Green Deal's CO2 fleet targets compel OEMs to substitute aluminum castings for heavier steel assemblies in body structures and powertrains. China's MIIT new-energy vehicle mandates and GB standards for lightweight materials further tighten material specifications that HPDC foundries must meet for market access. Stakeholders must monitor how solid-state battery pack architectures reshape load-bearing requirements for chassis castings and whether semi-solid casting technologies displace conventional HPDC in next-generation electric platforms.
Market Dynamics
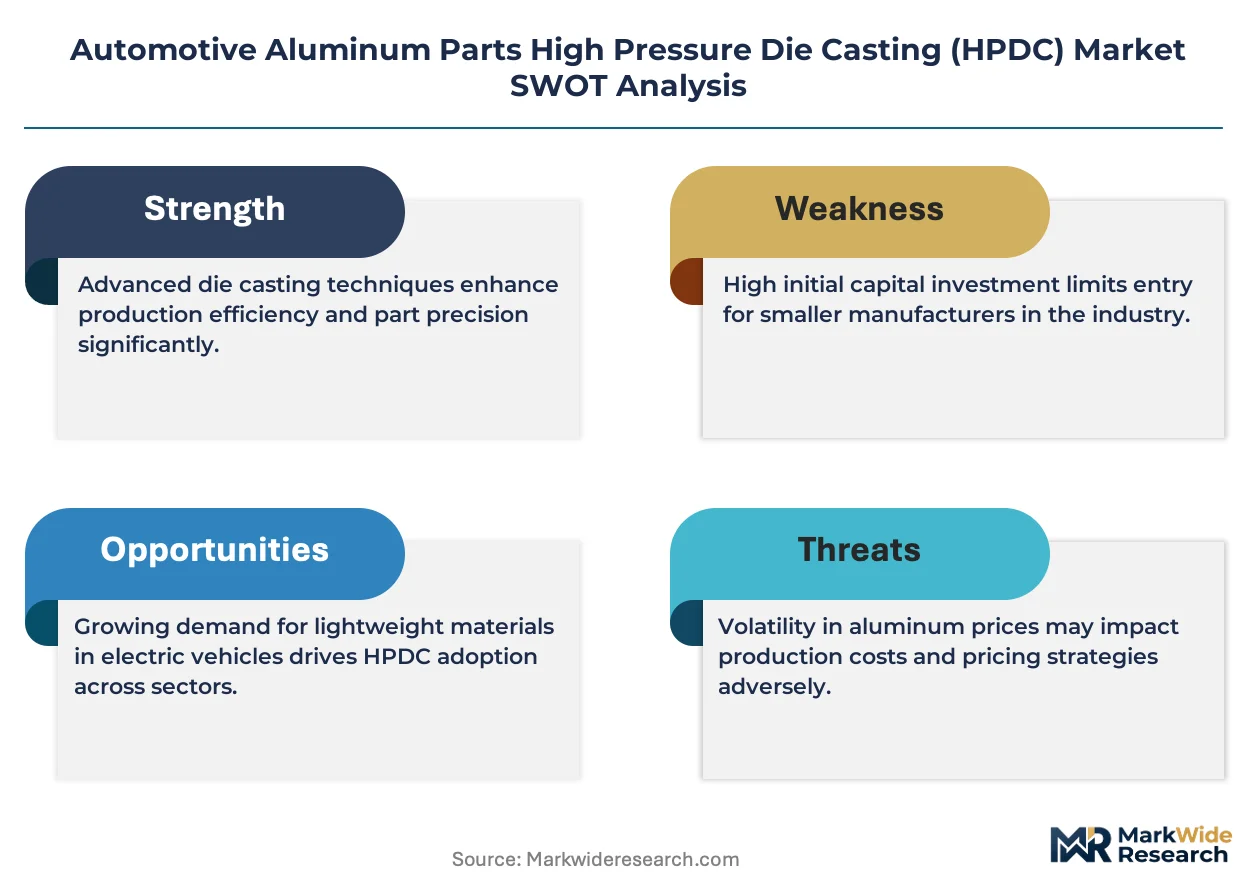
Electric vehicle platform architectures are compressing multi-part steel assemblies into single aluminum castings, forcing foundries to retool for larger die sizes and higher locking forces.
Growth Catalysts
- EU Green Deal CO2 fleet targets:OEMs must achieve 55% emissions reduction by 2030, accelerating aluminum substitution in body structures and powertrains.
- Skateboard platform proliferation:Tesla, Rivian, and legacy OEMs are consolidating battery housings, cross-members, and subframes into mega-castings exceeding 100 kilograms.
- China MIIT new-energy vehicle mandates:Domestic EV production quotas and GB standards for lightweight materials create captive demand for high-specification HPDC capacity.
Market Restraints
- Primary aluminum price volatility:LME aluminum spikes and energy cost surges in European smelting regions compress foundry margins on fixed-price OEM contracts.
- Die manufacturing concentration:Hardened steel die production clusters in specialized tooling corridors of Germany and Japan, creating 12-18 month lead time bottlenecks.
- Semi-solid casting substitution threat:Rheocasting and thixocasting processes offer superior mechanical properties for safety-critical chassis nodes, threatening conventional HPDC in premium segments.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced manufacturing attract HPDC investment to serve domestic EV programs and export platforms.
- Solid-state battery pack architectures:Elimination of liquid cooling channels enables thinner-walled, structurally optimized castings with reduced thermal management complexity.
- Direct OEM-foundry contracting:BYD and Tesla are bypassing Tier-1 suppliers to secure dedicated casting capacity, rewriting traditional supply chain hierarchies.
Industry Challenges
- Large-die machining specialist scarcity:Five-axis CNC capacity for dies exceeding 4,000 tons locking force is concentrated among fewer than 20 qualified suppliers globally.
- IATF 16949 certification timelines:New entrant foundries face 18-24 month qualification periods before receiving production approval from European and Japanese OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market |
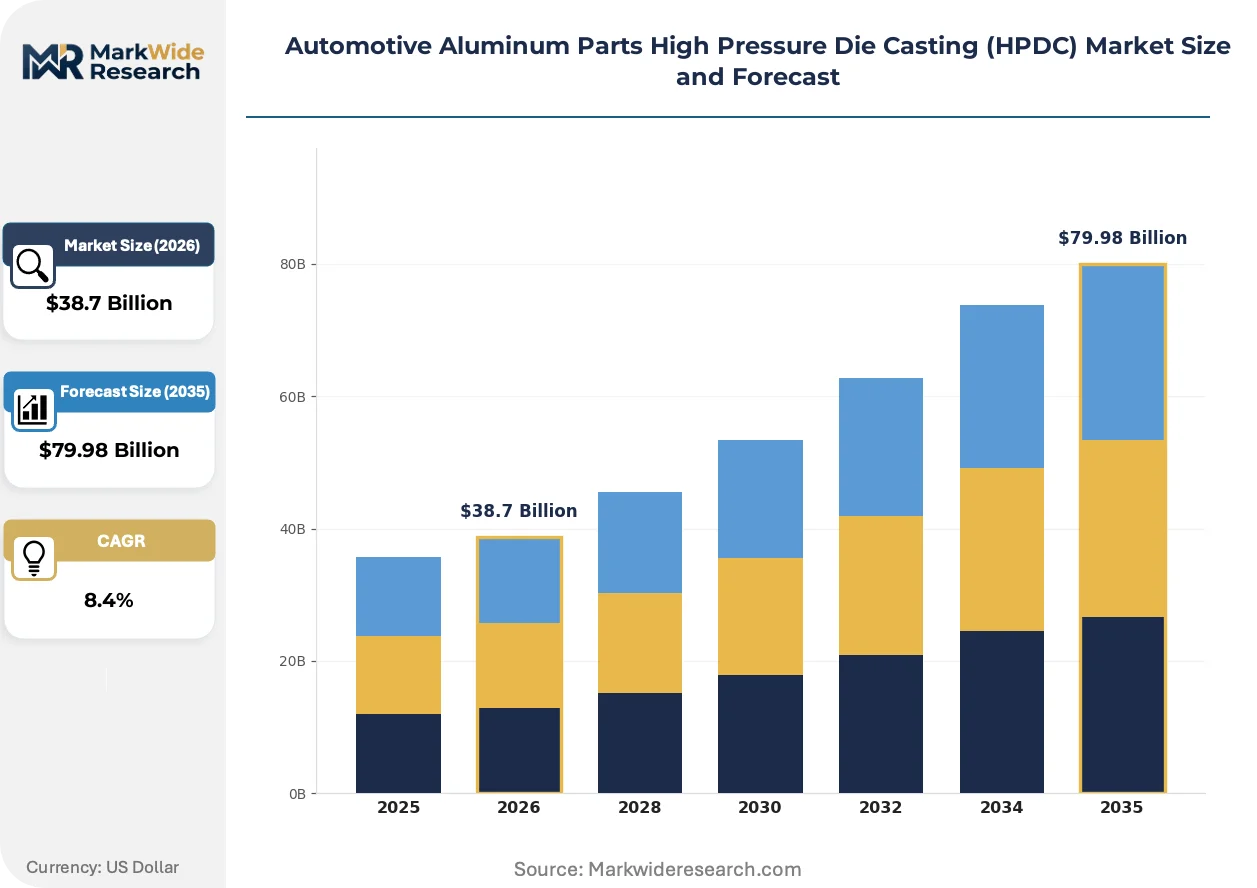
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Suspension Parts, Chassis Components Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Technology: Conventional Die Casting, Semi-Solid Casting, Gravity Die Casting, Cold Chamber Die Casting End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Endurance Technologies Limited, Koch Enterprises (Gibbs Die Casting Corporation), Nemak, Shiloh Industries, Bocar Group, Form Technologies Inc. (Dynacast), Georg Fischer Limited, Ryobi Die Casting Ltd, Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market Strategic Shifts
Process intensification and materials science breakthroughs are collapsing traditional boundaries between casting, machining, and assembly operations in automotive supply chains.
Integrated die-casting-to-paint systems are rendering obsolete the multi-station pre-treatment lines that previously handled aluminum body components separately from steel assemblies. Tesla's Giga Press installations in Texas and Berlin consolidate structural bonding, thermal management, and corrosion protection into single-cycle operations. This convergence eliminates 30-40 separate process steps, compressing factory footprints and redefining capital allocation for greenfield EV plants.
REACH authorization requirements for hexavalent chromium surface treatments are forcing foundries to migrate toward trivalent chrome and zirconium-based conversion coatings. The ECHA sunset date for Cr(VI) in automotive applications triggers reformulation of pretreatment chemicals across European supply chains. Suppliers serving BMW and Mercedes-Benz programs are accelerating qualification of silane-based thin-film technologies to maintain coating adhesion on high-pressure die cast surfaces.
Consolidated chassis sourcing is concentrating procurement decisions at OEM platform engineering centers rather than dispersed commodity buyers. Volkswagen's unified cell format and Rivian's skateboard architecture both specify single-source mega-casting suppliers for entire vehicle families. This buyer concentration shifts negotiation leverage toward foundries with proven 6,000-ton-plus press capacity and integrated CT-scan quality verification.
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market Segmentation
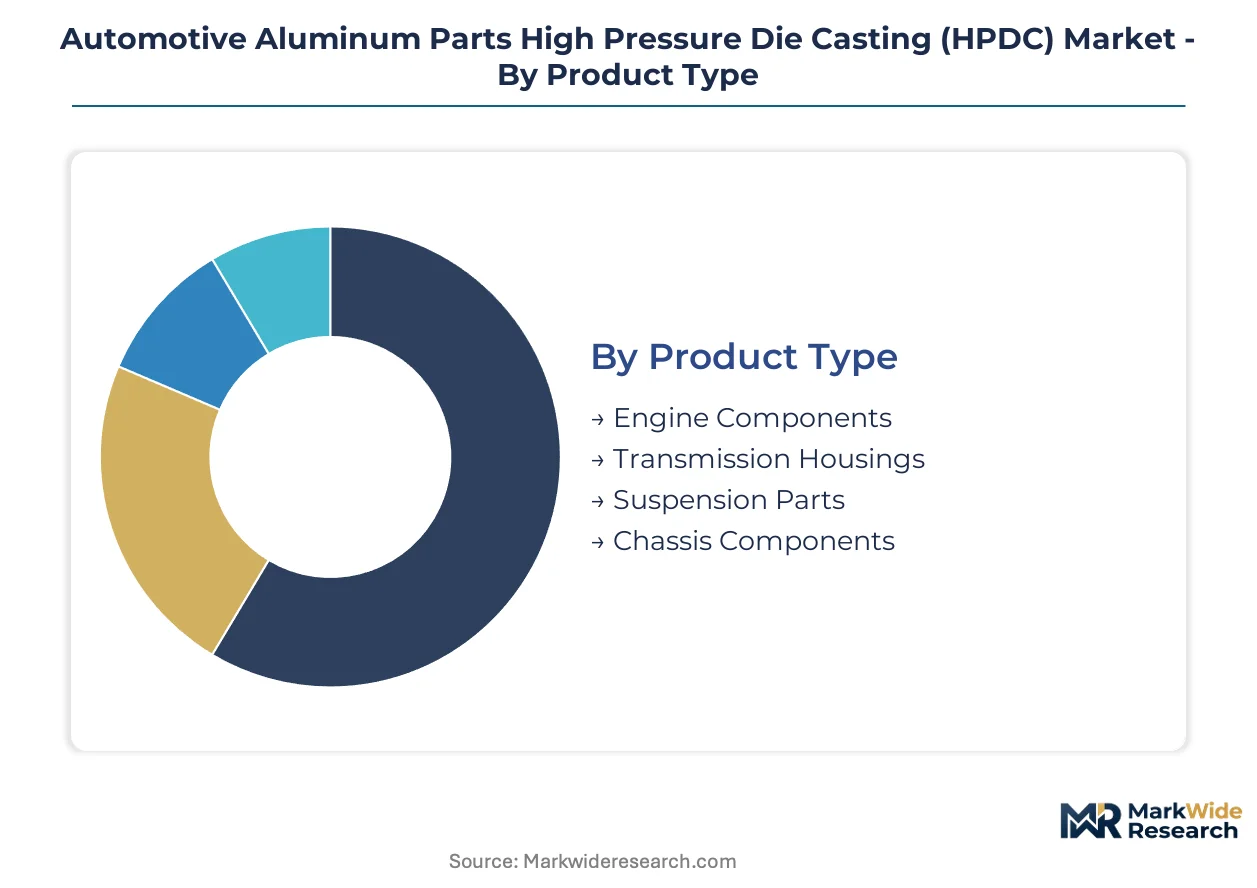
HPDC market segmentation reveals how casting specifications diverge across powertrain architectures and supply chain tiers. Product complexity, thermal loading requirements, and OEM platform standardization decisions determine which segments absorb capital investment and technical talent.
Product Type:
Cost tier stratification separates mature high-volume categories from emerging structural applications commanding premium die sizes.
- Transmission Housings:These multi-cavity aluminum enclosures integrate gear channels, bearing seats, and fluid galleries under tight leak-rate specifications. Demand concentrates in Germany's automotive corridor, where BMW, Mercedes-Benz, and Volkswagen suppliers cluster around foundries in Baden-Württemberg and Bavaria, driven by dual-clutch and e-axle transmission proliferation.
- Chassis Components:Structural nodes, subframes, and battery trays now exceed 100 kilograms in single-casting configurations for skateboard platforms. Electric vehicle manufacturers are expanding orders for lightweight structural castings as battery weight drives chassis redesign, with Tesla's Giga Press installations in Texas and Berlin consolidating multi-part assemblies.
- Engine Components:Cylinder heads, engine blocks, and intake manifolds retain volume leadership in internal combustion powertrains.
- Suspension Parts:Control arms, knuckles, and brackets serve both traditional and electrified platforms with moderate die complexity.
Transmission housings hold installed capacity. Chassis components are rotating up the share rankings.
Application:
Customer vehicle electrification status determines casting alloy specifications, wall thickness tolerances, and thermal management integration requirements.
- Electric Vehicles:Battery enclosures, motor housings, and structural battery trays demand vacuum-assisted HPDC for porosity control in safety-critical welds. China's MIIT new-energy vehicle mandates and GB standards for lightweight materials create captive demand for high-specification HPDC capacity serving BYD and Tesla direct contracting models.
- Passenger Vehicles:Internal combustion and mild-hybrid platforms sustain volume demand for engine blocks, transmission cases, and turbocharger housings. The US EPA Corporate Average Fuel Economy standards compel OEMs to substitute aluminum castings for heavier steel assemblies in body structures and powertrains, maintaining foundry utilization across legacy architectures.
- Commercial Vehicles:Medium-duty truck transmission housings and bus chassis components emphasize durability over weight reduction.
- Luxury Vehicles:Premium brands specify higher silicon alloys and cosmetic surface finishes for visible underhood applications.
Passenger vehicles anchor absolute volume. Electric vehicles are climbing the fastest in capacity absorption.
Technology:
Process maturity creates a spectrum from commodity high-speed production to emerging semi-solid methods capturing premium structural applications.
- Cold Chamber Die Casting:Molten aluminum transfers from separate furnaces into shot chambers, eliminating iron contamination for high-integrity structural castings. Georg Fischer Limited anchors premium supply relationships with European OEMs through precision cold-chamber capabilities, serving BMW and Mercedes-Benz programs with integrated CT-scan quality verification.
- Semi-Solid Casting:Rheocasting and thixocasting processes offer superior mechanical properties for safety-critical chassis nodes, threatening conventional HPDC in premium segments with reduced porosity and heat-treatable strength.
- Conventional Die Casting:Hot-chamber methods dominate zinc and magnesium applications with faster cycle times.
- Gravity Die Casting:Permanent mold filling without pressure serves thick-walled components where surface finish requirements are relaxed.
Cold chamber processes command structural casting share. Semi-solid methods are gaining penetration in safety-critical nodes.
End User:
Supply chain position determines contract structure, with direct OEM engagement rewriting traditional Tier-1 intermediary roles.
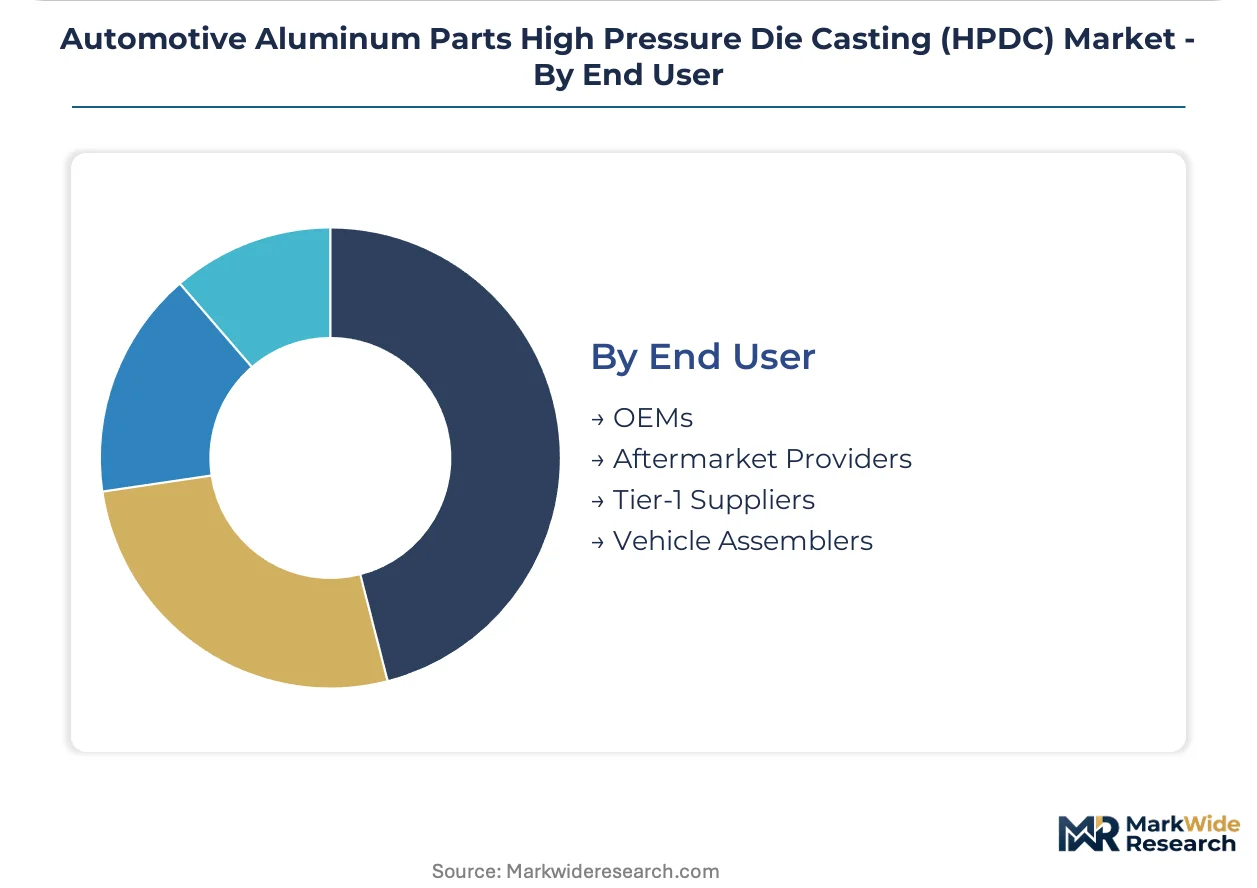
- OEMs:Volkswagen, Tesla, and BYP are consolidating procurement decisions at platform engineering centers rather than dispersed commodity buyers, specifying single-source mega-casting suppliers for entire vehicle families. Direct OEM-foundry contracting bypasses Tier-1 suppliers to secure dedicated casting capacity, rewriting traditional supply chain hierarchies.
- Tier-1 Suppliers:Continental, Bosch, and ZF retain transmission housing and engine component sourcing influence through integrated module assembly.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations purchase standardized casting kits.
- Aftermarket Providers:Repair and remanufacturing service revenue is rewriting traditional profit pools in automotive supply chains as extended vehicle lifecycles sustain replacement demand.
Tier-1 suppliers retain legacy volume. OEM direct contracting is accelerating fastest in EV platform sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HPDC consumption patterns diverge sharply across major automotive manufacturing bases, with European and Chinese producers prioritizing chassis-integrated mega-castings while North American capacity emphasizes transmission and powertrain enclosures.
Germany
BMW, Mercedes-Benz, and Volkswagen suppliers cluster around foundries in Baden-Württemberg and Bavaria, driving demand for dual-clutch transmission housings and structural battery trays. EU Green Deal CO2 fleet targets compel OEMs to achieve 55% emissions reduction by 2030, accelerating aluminum substitution in body structures. Stuttgart and Munich anchor precision cold-chamber capacity serving premium EV platform contracts.
China
BYD and Tesla direct contracting models are rewriting traditional supply chain hierarchies, with domestic EV production quotas creating captive demand for high-specification HPDC capacity. MIIT new-energy vehicle mandates and GB standards for lightweight materials tighten material specifications that foundries must meet for market access. Yangtze River Delta clusters around Shanghai concentrate mega-casting investments for skateboard architectures.
United States
EPA Corporate Average Fuel Economy standards push OEMs toward aluminum-intensive platforms, sustaining foundry utilization across legacy internal combustion architectures while EV transitions accelerate. Tesla's Giga Press installations in Texas consolidate structural bonding, thermal management, and corrosion protection into single-cycle operations. Southeast automotive corridors in Tennessee and South Carolina attract transmission housing capacity serving regional assembly plants.
India
Production-linked incentives for advanced manufacturing attract HPDC investment to serve domestic EV programs and export platforms. The PLI scheme for automotive manufacturing subsidizes capital equipment for cold-chamber capacity exceeding 4,000 tons locking force. Maharashtra and Gujarat industrial corridors concentrate new foundry investments targeting two-wheeler and passenger vehicle transmission demand.
Japan
METI industrial policy supports lightweight materials R&D, with JIS standards governing alloy specifications for safety-critical chassis nodes. Toyota and Honda platform engineering centers specify single-source mega-casting suppliers for hybrid and battery-electric vehicle families. Aichi Prefecture around Nagoya retains transmission housing volume leadership while Yokohama-Tokyo corridors develop next-generation semi-solid casting qualifications.
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market Competitive Environment
Capability concentration sits with specialized die engineering and precision cold-chamber operators; scale advantage sits with integrated foundry-to-assembly platforms serving global OEM footprints. The market structures around three tiers: mega-casting specialists with 6,000-ton-plus press capacity, mid-scale transmission housing producers serving legacy powertrain demand, and regional job shops capturing aftermarket repair and remanufacturing revenue. Dominant competitive moves include direct OEM-foundry contracting that bypasses Tier-1 intermediaries, and backward integration into die manufacturing to compress 12-18 month tooling lead times.
Among vertically integrated specialists, Nemak and Rheinmetall AG exemplify archetypes that combine defense-to-automotive technology transfer with structural casting expertise. Georg Fischer Limited anchors premium supply relationships through precision cold-chamber capabilities. These three occupy positions that straddle capability tiers, with foundry networks spanning multiple continents and integrated CT-scan quality verification systems that meet IATF 16949 certification timelines demanded by European and Japanese OEMs.
| Leading Market Players |
|---|
| Endurance Technologies Limited |
| Koch Enterprises (Gibbs Die Casting Corporation) |
| Nemak |
| Shiloh Industries |
| Bocar Group |
| Form Technologies Inc. (Dynacast) |
| Georg Fischer Limited |
| Ryobi Die Casting Ltd |
| Rheinmetall AG |
| Others |
Value Chain & Pricing Dynamics
Hardened steel die production clusters in specialized tooling corridors of Germany and Japan compress margin pools at foundries locked into fixed-price OEM contracts. Primary aluminum price volatility and energy cost surges in European smelting regions force tier-2 suppliers to absorb input spikes while mega-casting specialists with backward-integrated die manufacturing capture premium pricing power.
Pricing Analysis
Long-term offtake agreements dominate HPDC procurement, with Volkswagen and BMW platform engineering centers locking in multi-year capacity allocations for transmission housings and structural battery trays. Price differentiation rests on IATF 16949 certification tier and die locking force capability, with 6,000-ton-plus press operators commanding premiums over mid-scale legacy suppliers. Cost compression in standard transmission housing tiers is intensifying because Chinese foundries with MIIT-compliant capacity are exporting at thinner margins. Tier-1 module assemblers exhibit highest price sensitivity as OEMs consolidate direct foundry relationships, while luxury EV platforms show least sensitivity to secure vacuum-assisted HPDC for safety-critical chassis nodes.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for aluminum alloy feedstock and finished casting exports. Production gravity centers on Germany, China, and Japan, with Baden-Württemberg and Yangtze River Delta clusters anchoring precision cold-chamber capacity. The HPDC supply chain draws from primary aluminum smelters, hardened steel die forgers, and five-axis CNC machining specialists concentrated among fewer than twenty qualified suppliers globally. Single-source vulnerability permeates large-die manufacturing, where twelve-to-eighteen month lead times throttle capacity expansion. Distribution runs through direct OEM-foundry contracting channels that bypass traditional Tier-1 intermediaries, particularly for Tesla and BYD skateboard platform programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive HPDC is exiting a cyclical trough as EV platform standardization drives capital redeployment toward structural casting capacity. OEM procurement consolidation and battery-electric vehicle production quotas provide the cyclical impetus for foundry margin recovery.
For Market Incumbents: Insulate core transmission housing revenue through captive die manufacturing investments that compress tooling lead times and lock in BMW and Mercedes-Benz program continuity. Rheocasting and thixocasting substitution threats in safety-critical chassis nodes demand accelerated semi-solid casting qualifications to defend premium segment positioning. Backward integration into five-axis CNC die machining represents the priority capability lever for margin defense. For New Entrants and Emerging Players: India's PLI-subsidized automotive manufacturing corridors offer underpenetrated entry points for cold-chamber capacity targeting domestic two-wheeler and export passenger vehicle transmission demand. Maharashtra and Gujarat industrial zones present the most penetrable geography given subsidized capital equipment access and absence of entrenched mega-casting specialists. A qualified-by-association go-to-market approach—partnering with German or Japanese die engineering specialists to accelerate IATF 16949 timelines—enables faster OEM qualification. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated foundry-to-assembly platforms with proven 6,000-ton-plus press capacity and direct OEM contracting relationships across multiple continents. Long-term viability over a five-to-ten year window favors operators with CT-scan quality verification systems and integrated paint-pretreatment capabilities that match Tesla's Giga Press process intensification. The signal to monitor is solid-state battery pack architecture adoption, which would eliminate liquid cooling channel complexity and reshape structural casting specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die Manufacturing | Captive five-axis CNC capacity compresses twelve-to-eighteen month tooling bottlenecks that constrain rival expansion. |
| Vacuum-Assisted HPDC Qualification | Porosity control certification unlocks safety-critical battery tray contracts from Tesla and Rivian platform engineering. |
| Direct OEM-Foundry Contracting | Bypassing Tier-1 intermediaries secures dedicated capacity allocation for Volkswagen unified cell format programs. |
| Semi-Solid Casting Technology Investment | Rheocasting capabilities counter substitution threats in premium chassis nodes requiring heat-treatable strength. |
| Integrated Die-Casting-to-Paint Systems | Single-cycle thermal management and corrosion protection matches Tesla's Giga Press footprint compression. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and trade customs records. Primary interviews engaged OEM platform engineers, Tier-1 supplier procurement leads, foundry operations directors, and aftermarket distributors across Germany, China, the United States, and Japan. Bottom-up capacity modeling triangulated against top-down OEM aluminum content-per-vehicle projections validates volume estimates.
Forecast inputs incorporate vehicle class stratification, propulsion architecture evolution, content-per-vehicle trajectories, OEM tier supply positioning, and regional production cluster shifts. Segmentation dimensions span product type, application, technology, and end-user supply chain position. CAGRs derive from regression analysis of historical capacity utilization against projected EV platform ramp schedules and regulatory fleet targets. Aluminum alloy specification tightening under China's GB standards and the EU Green Deal's CO2 mandates inform demand elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum LME pricing, European energy costs, or EV adoption rates would shift the trajectory. Forecasts reflect assumptions about skateboard platform proliferation speed and semi-solid casting substitution timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Synchronous Timing Belts Market
Automotive Parts
ASEAN Automotive Bearings Market