
 Auxiliary Oil Cooler Market | 2026-2036
Auxiliary Oil Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Auxiliary Oil Cooler Market Analysis
Automotive electrification is consolidating demand patterns across the auxiliary oil cooler landscape. MAHLE leverages its thermal management portfolio to anchor European OEM supply chains for hybrid platforms. PWR Performance Products specializes in motorsport-derived cooling architectures that extend into high-performance road vehicle programs. Modine Manufacturing Company dominates industrial machinery applications through its geographic manufacturing footprint across North American and Asian production nodes.
An auxiliary oil cooler is a heat exchanger device, typically fabricated from aluminum alloys or stainless steel with fin-and-tube or plate-type architectures, designed to maintain optimal lubricant viscosity by dissipating thermal energy generated during mechanical operation. The unit prevents oil degradation, reduces component wear, and extends service intervals in engines, transmissions, and hydraulic systems operating under sustained load conditions. Air-cooled configurations retain cost advantages in mobile and aftermarket installations where plumbing complexity must stay minimal, while water-cooled and plate heat exchanger variants command preference in marine and power generation settings where space constraints and thermal density requirements intensify. Shell and tube architectures occupy mature positions within heavy industrial and offshore infrastructure, though their share of new project specifications faces displacement from compact plate-based alternatives.
The EPA enforces Corporate Average Fuel Economy standards that elevate thermal system efficiency requirements for internal combustion and hybrid powertrains, while the EU F-Gas Regulation and CE marking protocols govern refrigerant and pressure equipment compliance for coolers integrated into climate-controlled systems. Japan's METI energy efficiency frameworks and China's MIIT dual carbon goals further shape product design parameters and material selection criteria for suppliers targeting multi-regional certification. Stakeholders must monitor evolving battery thermal management integration strategies, as OEMs reassess whether dedicated auxiliary oil circuits remain distinct or merge into unified vehicle thermal architectures.
Market Dynamics
Automotive electrification is compressing demand for conventional auxiliary oil coolers while simultaneously creating new thermal management requirements for hybrid powertrains. EPA emissions standards and Euro 7 protocols are forcing OEMs to optimize every thermal interface, redirecting engineering resources toward integrated cooling architectures that merge lubrication circuits with battery and power electronics temperature control.
Growth Catalysts
- Euro 7 Protocols:Stringent thermal efficiency mandates for powertrain components are compelling European OEMs to specify supplemental oil cooling on hybrid platforms. The regulation treats lubricant temperature stability as a direct emissions control variable.
- Hybrid Platform Proliferation:Dual-powertrain vehicles require dedicated thermal circuits for electric motor bearings and reduction gearboxes. China's MIIT dual carbon goals are accelerating domestic hybrid production lines.
- Aluminum Fin-and-Tube Fabrication:Advances in brazing and micro-channel extrusion are reducing cooler weight by 15-20% versus legacy designs. Lightweighting priorities in Germany and the United States are pulling this technology into volume production.
Market Restraints
- Aluminum Price Volatility:Primary aluminum input costs fluctuate with energy pricing and Chinese smelter output decisions. Margin compression is acute for suppliers locked into annual OEM supply agreements without raw material pass-through clauses.
- Supplier Concentration in Jiangsu Province:A disproportionate share of global heat exchanger manufacturing capacity sits within a 200-kilometer radius in eastern China. Geopolitical friction or logistics disruption creates systemic supply risk.
- Unified Thermal Architecture Threat:Battery electric vehicles are eliminating dedicated engine oil circuits entirely. The addressable market for standalone auxiliary oil coolers contracts as BEV penetration rises in passenger vehicle segments.
Strategic Opportunities
- Commercial Vehicle Electrification:Heavy-duty electric trucks and buses retain multi-fluid thermal management needs. The United States and Germany are deploying demonstration fleets that require customized cooling solutions for axle and transmission lubricants.
- Marine Hybridization:Water-cooled plate heat exchanger variants are capturing specification share in yacht and workboat electrification programs. IMO emissions regulations are driving harbor craft toward hybrid diesel-electric architectures.
- Industrial Machinery Service Contracts:Equipment OEMs are bundling predictive maintenance with cooler replacement cycles. Aftermarket channel partnerships with mining and construction fleet operators create recurring revenue streams.
Industry Challenges
- Thermal Simulation Talent Scarcity:Computational fluid dynamics expertise for multi-physics lubrication cooling analysis commands premium compensation. Suppliers struggle to staff engineering teams capable of supporting OEM integrated thermal architecture development.
- Multi-Regional Certification Burden:Simultaneous EPA, ECHA REACH, and China GB standard compliance requires parallel testing protocols. Product launch timelines stretch as validation documentation must satisfy divergent documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auxiliary Oil Cooler Market |
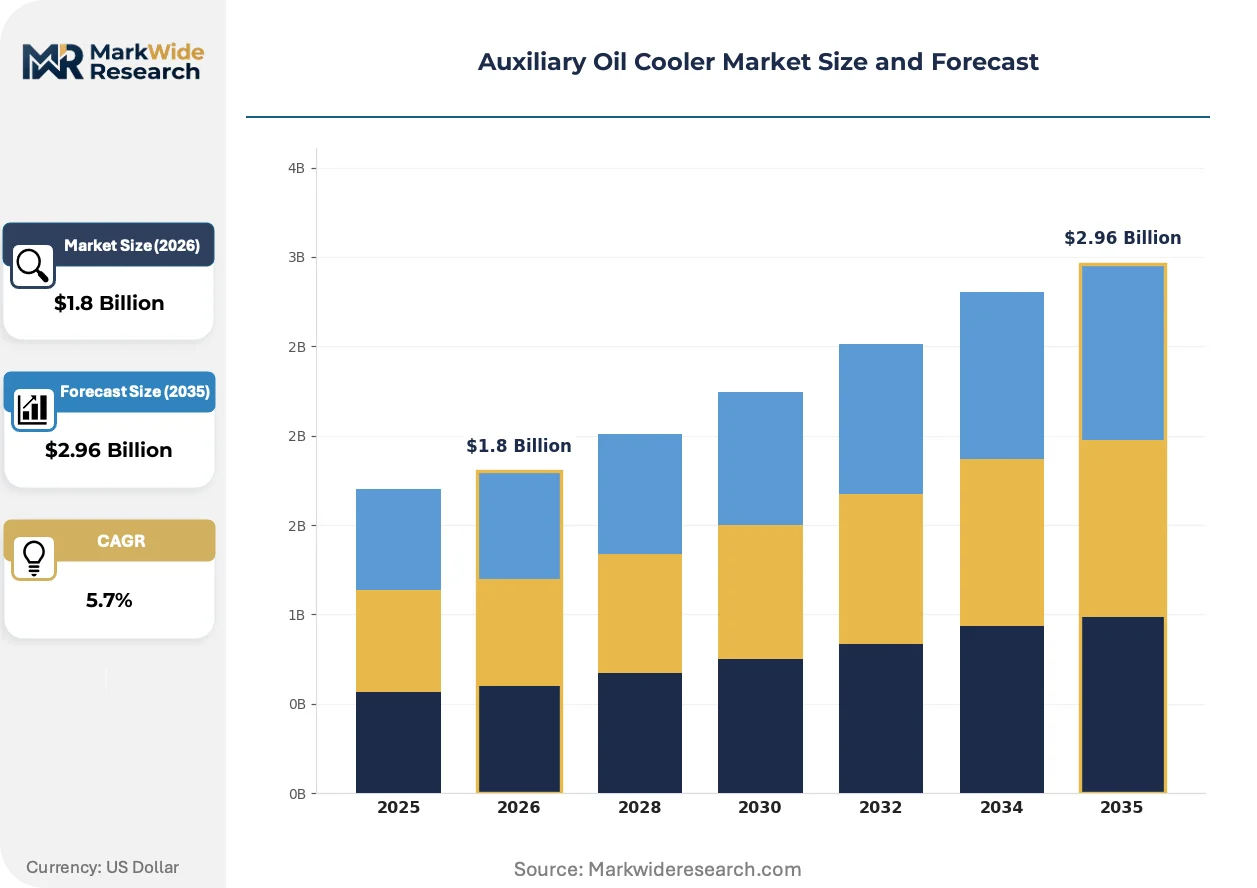
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Plate Heat Exchanger, Shell and Tube Application: Automotive, Industrial Machinery, Marine, Power Generation End User: OEMs, Aftermarket Providers, Fleet Operators, Equipment Manufacturers Installation: Onshore, Offshore, Mobile, Fixed |
| Companies Covered | PWR Performance Products, Fluidyne, Calsonic Kansei, MAHLE, Derale, Toyota, Hayden, AKG Thermal Systems, Modine Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auxiliary Oil Cooler Market Emerging Trajectories
Thermal management architectures are converging across powertrain subsystems, compressing the traditional separation between engine oil, transmission fluid, and battery cooling circuits. This integration is forcing cooler suppliers to reposition as system-level thermal partners rather than component vendors.
Additive manufacturing is absorbing complexity in prototype and low-volume production of optimized fin geometries. Motorsport and aerospace suppliers are adopting electron beam melting for titanium and aluminum lattice structures that maximize surface area within constrained packaging envelopes. The technology is absorbing development cycle compression pressure as OEMs demand functional prototypes within weeks rather than months.
EPA Corporate Average Fuel Economy enforcement is tightening thermal efficiency verification requirements for hybrid powertrain components. The regulation now treats lubricant operating temperature windows as measurable compliance variables, not merely durability factors. Suppliers serving the United States market are investing in embedded sensor integration to provide real-time thermal data logging for OEM certification submissions.
Fleet operators are consolidating supplier relationships around integrated thermal system providers capable of supporting multiple vehicle platforms. Single-source procurement for oil coolers, radiators, and charge air coolers is displacing fragmented component purchasing. This concentration is most visible in North American heavy-duty truck manufacturing, where vertical integration between powertrain and thermal system engineering is accelerating.
Auxiliary Oil Cooler Market Segmentation
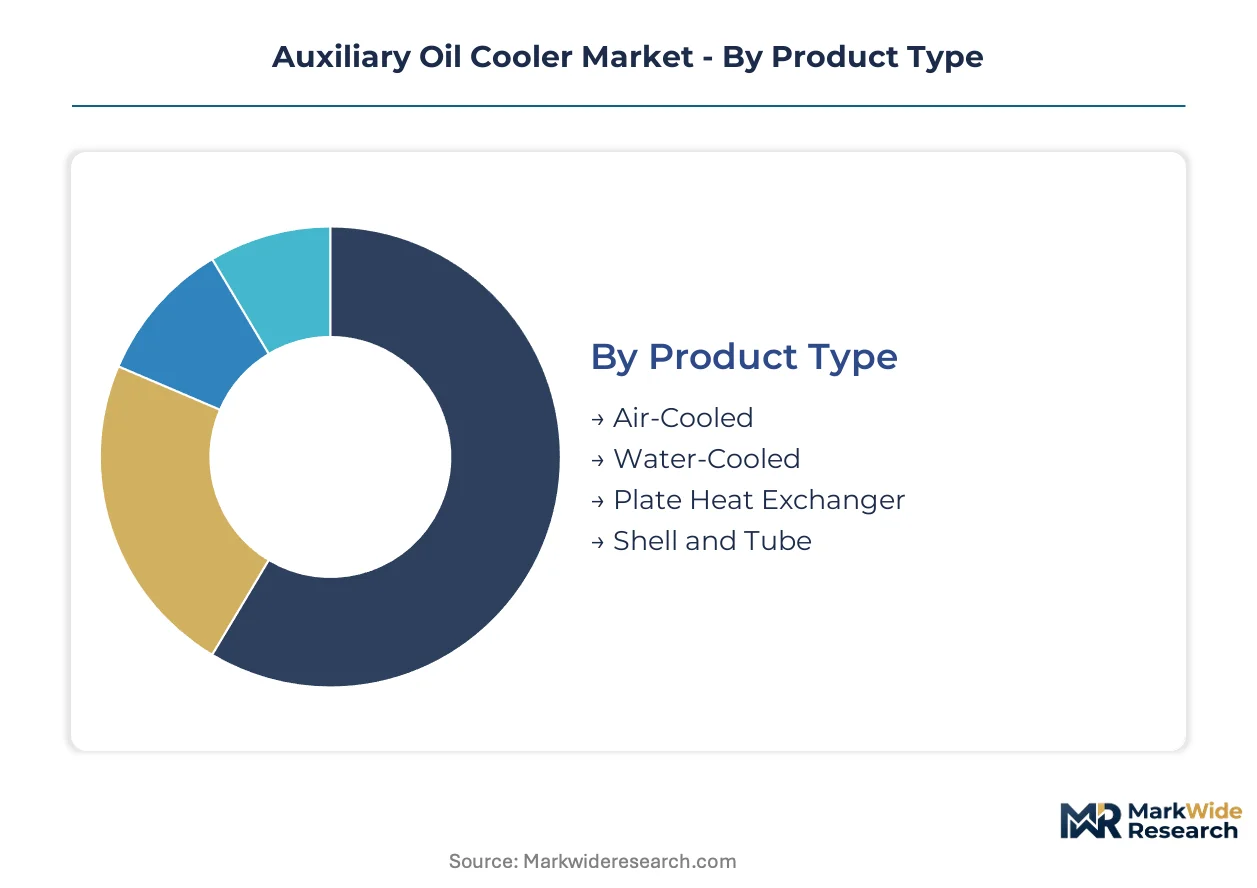
Auxiliary oil cooler procurement patterns diverge sharply between cost-sensitive high-volume automotive programs and premium-specification industrial installations. Suppliers must align fabrication capabilities and certification portfolios to the distinct technical and commercial requirements of each segment cluster.
Product Type:
Volume production concentrates in aluminum fin-and-tube architectures, while premium margins attach to compact plate-based alternatives for space-constrained applications.
- Air-Cooled:Aluminum fin-and-tube construction dominates mobile equipment and aftermarket replacement cycles. Demand from North American heavy-duty truck OEMs and German construction machinery manufacturers pulls this configuration into high-volume production with minimal plumbing complexity.
- Water-Cooled:Plate and tube-bundle architectures integrate into marine engine compartments and power generation enclosures where thermal density exceeds air-side dissipation capacity. Hybrid yacht programs in Italy and Norway specify these units for combined diesel-electric thermal management.
- Plate Heat Exchanger:Compact stainless steel or titanium plate stacks serve offshore platforms and chemical processing with severe space constraints.
- Shell and Tube:Traditional steel-tube-in-shell designs persist in refinery and heavy industrial infrastructure with established maintenance protocols.
Mature deployment sits with Shell and Tube configurations in legacy industrial estates. Newer deployment is concentrated in Plate Heat Exchanger formats for marine hybridization and offshore wind support vessels.
Application:
Customer technical requirements stratify between standardized automotive platforms and customized industrial specifications with extended validation cycles.
- Automotive:Hybrid powertrain thermal architectures demand multi-circuit coolers managing engine oil, transmission fluid, and electric motor bearing lubricants simultaneously. EPA Corporate Average Fuel Economy verification treats lubricant temperature stability as a compliance variable, forcing embedded sensor integration.
- Industrial Machinery:Mining excavators, agricultural combines, and construction equipment operate under sustained load conditions requiring robust cooler durability. German and Japanese OEMs bundle predictive maintenance algorithms with cooler replacement cycles to secure aftermarket revenue.
- Marine:IMO emissions regulations drive harbor craft and workboat electrification, expanding demand for corrosion-resistant water-cooled units in saltwater environments.
- Power Generation:Backup diesel and gas turbine installations require reliable lubrication cooling for continuous duty cycles in remote locations.
Procurement consolidation is most advanced in Automotive, where single-source thermal system contracts displace fragmented component purchasing. Specification fragmentation persists in Marine, where hull-form constraints demand customized packaging geometries.
End User:
Contract structures and margin profiles differ fundamentally between captive OEM supply agreements and independent aftermarket distribution channels.
- OEMs:Volume automotive and commercial vehicle manufacturers specify coolers within integrated thermal system procurement packages. Annual supply agreements with raw material pass-through clauses protect margins against aluminum price volatility.
- Aftermarket Providers:Independent distributors and service chains stock replacement units for aging vehicle and equipment fleets. Digital catalog standardization is reducing cross-reference friction for maintenance technicians.
- Fleet Operators:Mining, logistics, and utility companies negotiate direct supply contracts with predictive maintenance telemetry integration.
- Equipment Manufacturers:Industrial machinery OEMs source coolers as subsystems within powertrain or hydraulic module assemblies.
Long-term service revenue potential concentrates with Fleet Operators. Transactional volume expansion is concentrated in Aftermarket Providers serving the North American and European vehicle parc.
Installation:
Environmental exposure and accessibility constraints dictate material selection and maintenance protocol design across deployment contexts.
- Onshore:Fixed industrial plants and vehicle manufacturing facilities accommodate standard cooler formats with scheduled maintenance access.
- Offshore:Oil platforms and floating wind installations demand marine-grade coatings and redundant cooling circuits with remote monitoring capability.
- Mobile:Construction, agriculture, and mining equipment subjects coolers to vibration, contamination, and thermal cycling stress.
- Fixed:Stationary power generation and industrial process cooling permits optimized airflow and plumbing architectures without packaging constraints.
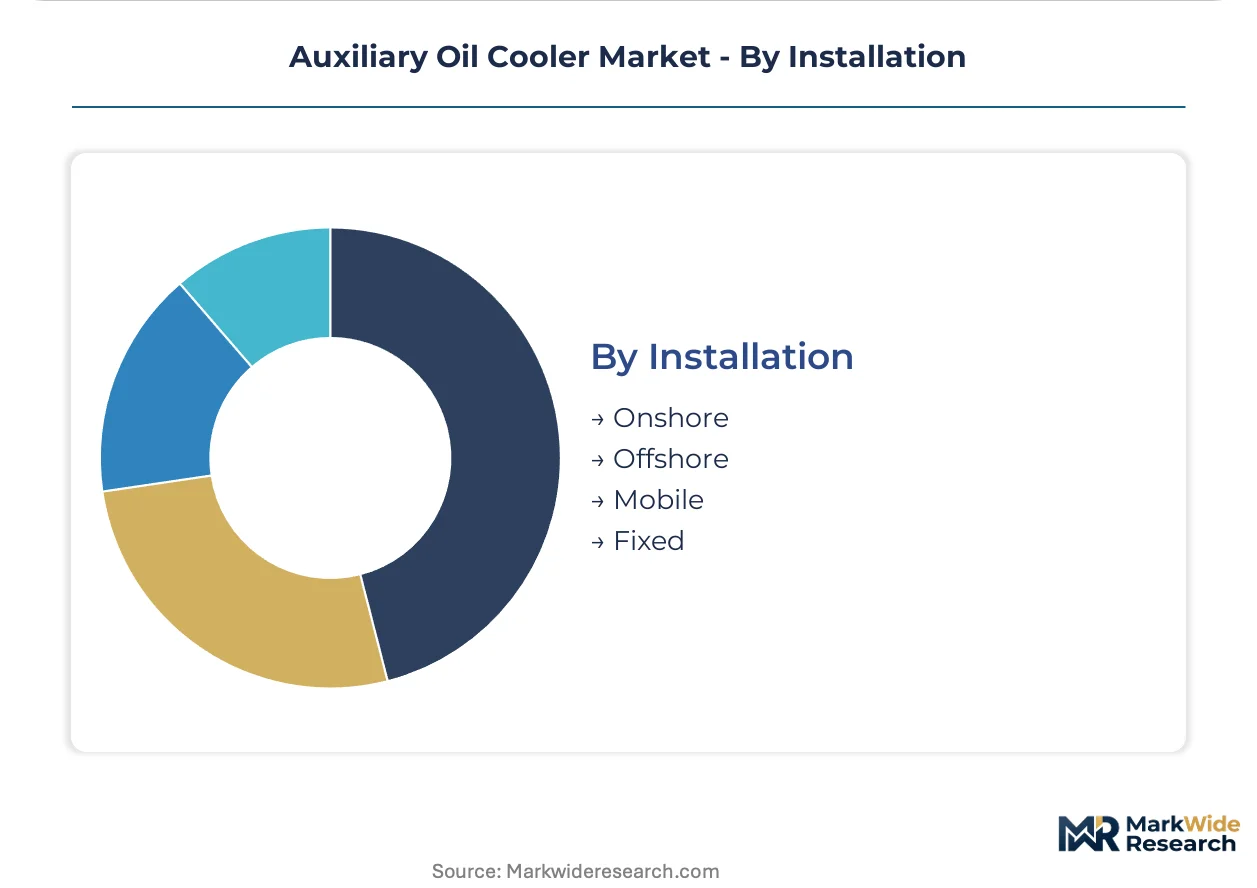
Specification complexity peaks in Offshore installations, where corrosion resistance and regulatory compliance multiply engineering requirements. Cost optimization pressure concentrates in Mobile applications, where weight and durability trade-offs determine competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Jiangsu Province concentrate heat exchanger manufacturing capacity within a 200-kilometer radius, creating systemic supply risk alongside efficiency advantages. This concentration shapes procurement patterns across automotive and industrial end-use sectors.
China
MIIT dual carbon goals accelerate domestic hybrid production lines requiring supplemental lubrication cooling. GB standards govern pressure equipment compliance for coolers integrated into climate-controlled systems. Yangtze River Delta manufacturing clusters in Jiangsu Province supply fin-and-tube architectures to German and US automotive OEMs.
Germany
KBA type-approval requirements enforce thermal efficiency verification for hybrid powertrain components. Euro 7 protocols treat lubricant temperature stability as a direct emissions control variable. Bavaria-based thermal management specialists anchor European OEM supply chains through integrated cooling system partnerships.
United States
EPA Corporate Average Fuel Economy standards elevate thermal system efficiency requirements for internal combustion and hybrid powertrains. NHTSA safety regulations influence cooler packaging and mounting specifications. Michigan and Ohio manufacturing corridors host heavy-duty truck OEMs consolidating single-source thermal system procurement.
Japan
METI energy efficiency frameworks shape product design parameters for suppliers targeting multi-regional certification. JIS standards govern material selection criteria for aluminum alloy heat exchangers. Kansai and Chubu industrial regions maintain precision fabrication capabilities for motorsport-derived cooling architectures.
India
PLI scheme incentives attract component manufacturing investment for hybrid and electric vehicle thermal systems. BIS certification requirements create parallel testing protocols for domestic and export market compliance. Tamil Nadu and Maharashtra automotive clusters expand capacity to serve European and North American OEM procurement.
Auxiliary Oil Cooler Market Vendor Landscape
Top-tier vendors anchor integrated thermal system supply, while mid-scale fabricators compete on cost and regional responsiveness. The vendor base stratifies between full-system providers capable of supporting OEM platform consolidation and component specialists serving aftermarket and industrial channels. Two strategic archetypes dominate: diversified thermal management conglomerates with multi-product portfolios, and focused heat exchanger specialists leveraging motorsport or industrial expertise. Competitive moves concentrate on backward integration into aluminum extrusion and brazing operations, plus strategic partnerships with battery thermal management developers.
Within the diversified conglomerate tier, MAHLE and Modine Manufacturing Company exemplify integrated thermal system positioning across automotive and industrial end-uses. PWR Performance Products occupies a specialist archetype, representing motorsport-derived cooling architectures that extend into high-performance road vehicle programs. These three entities collectively illustrate the competitive spectrum from volume-scale OEM supply to premium specification engineering.
| Leading Market Players |
|---|
| PWR Performance Products |
| Fluidyne |
| Calsonic Kansei |
| MAHLE |
| Derale |
| Toyota |
| Hayden |
| AKG Thermal Systems |
| Modine Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement teams in Germany and the United States negotiate annual supply agreements with raw material pass-through clauses, anchoring contract-based long-term offtake as the dominant pricing model across aluminum fin-and-tube architectures. This buyer concentration compresses margin flexibility for suppliers locked into volume commitments without spot-market escape hatches.
Pricing Analysis
Short lead-time premiums of 15-25% apply to emergency replacement orders from North American heavy-duty truck fleet operators, while spot inventory liquidation discounts emerge during OEM production pauses. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EPA-verified thermal efficiency units command sustained premiums, while uncertified aftermarket alternatives face price erosion from Chinese imports. Cost compression in standard-tier automotive supply is intensifying because annual contract renegotiations now embed aluminum LME linkage clauses. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement frameworks, whereas marine yacht builders demonstrate lowest sensitivity given hull-form customization requirements.
Supply Chain Analysis
Reverse-logistics flows for remanufactured coolers are expanding through German construction machinery OEM service contracts, capturing end-of-life units for core refurbishment. Manufacturing gravity draws from Jiangsu Province in China, Bavaria in Germany, and Michigan in the United States, with aluminum extrusion and brazing operations forming critical upstream dependencies. Single-source vulnerability concentrates in Jiangsu's 200-kilometer manufacturing radius, where geopolitical friction or energy rationing would cascade through global automotive thermal system supply. Distribution runs through captive OEM direct supply for volume automotive, aftermarket distributor networks for replacement cycles, and direct fleet operator contracts with predictive maintenance telemetry integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 protocols erect a cost-of-compliance barrier that favors incumbent suppliers with established KBA type-approval documentation and embedded sensor integration capabilities, marginalizing uncertified competitors.
For Market Incumbents: To counter unified thermal architecture displacement from battery electric vehicle proliferation, anchor defensive positioning through backward integration into aluminum micro-channel extrusion operations in Germany and captive supply of brazing alloys. Fortify certification moats by accelerating EPA Corporate Average Fuel Economy verification documentation for hybrid platform suppliers, converting compliance burden into switching-cost barriers. For New Entrants and Emerging Players: Additive manufacturing for optimized fin geometries offers technology-first entry into motorsport-derived cooling architectures extending to low-volume high-performance road vehicle programs. White-space concentration sits with marine hybridization in Italian and Norwegian yacht electrification, where water-cooled plate heat exchanger specifications remain fragmented and hull-form customization demands responsive engineering partnerships. Go-to-market execution should target direct OEM thermal system engineering collaborations rather than component catalog distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fabrication specialists in Japan's Kansai and Chubu industrial regions with dormant motorsport expertise and latent capacity for aerospace thermal management diversification. Long-term viability over a five-to-ten-year horizon rests on hybrid platform persistence in commercial vehicle segments where multi-fluid thermal management resists full electrification. Monitor EPA enforcement intensity and Euro 7 implementation timelines as inflection indicators for standalone auxiliary oil cooler demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of micro-channel brazing stock secures margin protection against LME volatility for German automotive OEM contracts. |
| Embedded Sensor Integration | Real-time thermal data logging satisfies EPA Corporate Average Fuel Economy verification requirements for hybrid powertrain certification submissions. |
| Marine Hybridization Partnership | Water-cooled plate heat exchanger specifications for IMO-regulated harbor craft electrification open premium-margin revenue streams. |
| Predictive Maintenance Telemetry | Fleet operator service contracts with mining and construction OEMs convert cooler replacement cycles into recurring aftermarket revenue. |
| Additive Manufacturing Adoption | Electron beam melting for titanium and aluminum lattice structures compresses prototype development cycles for motorsport-derived architectures. |
Methodological Framework
Document review covered EPA regulatory filings, ECHA REACH substance registrations, MIIT dual carbon policy documentation, and aluminum industry trade association reports, complemented by interviews with thermal management engineering directors at European and North American automotive OEMs, procurement leads at heavy-duty truck manufacturers, aftermarket distribution channel managers, and marine propulsion system integrators. Bottom-up demand modeling triangulated against top-down macroeconomic drivers across the analysis window.
Output projections span unit volume and value across product type, application, end user, and installation configuration dimensions, with propulsion architecture serving as an additional automotive-specific segmentation layer. CAGRs derive from regression analysis of historical procurement patterns and OEM platform rollout schedules, incorporating aluminum price elasticity coefficients and hybrid production line ramp assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained aluminum price volatility or accelerated battery electric vehicle penetration in passenger segments. Forecasts reflect assumptions regarding Euro 7 implementation timelines, EPA enforcement continuity, and Jiangsu Province manufacturing stability. Practitioners should monitor OEM integrated thermal architecture announcements and commercial vehicle electrification fleet deployment scales for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Automotive Electric Drivetrain Components Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
United States Ceramic Ball Bearings Market