
 Canada Automotive Parts Die Casting Market | 2026-2036
Canada Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Parts Die Casting Market Outlook
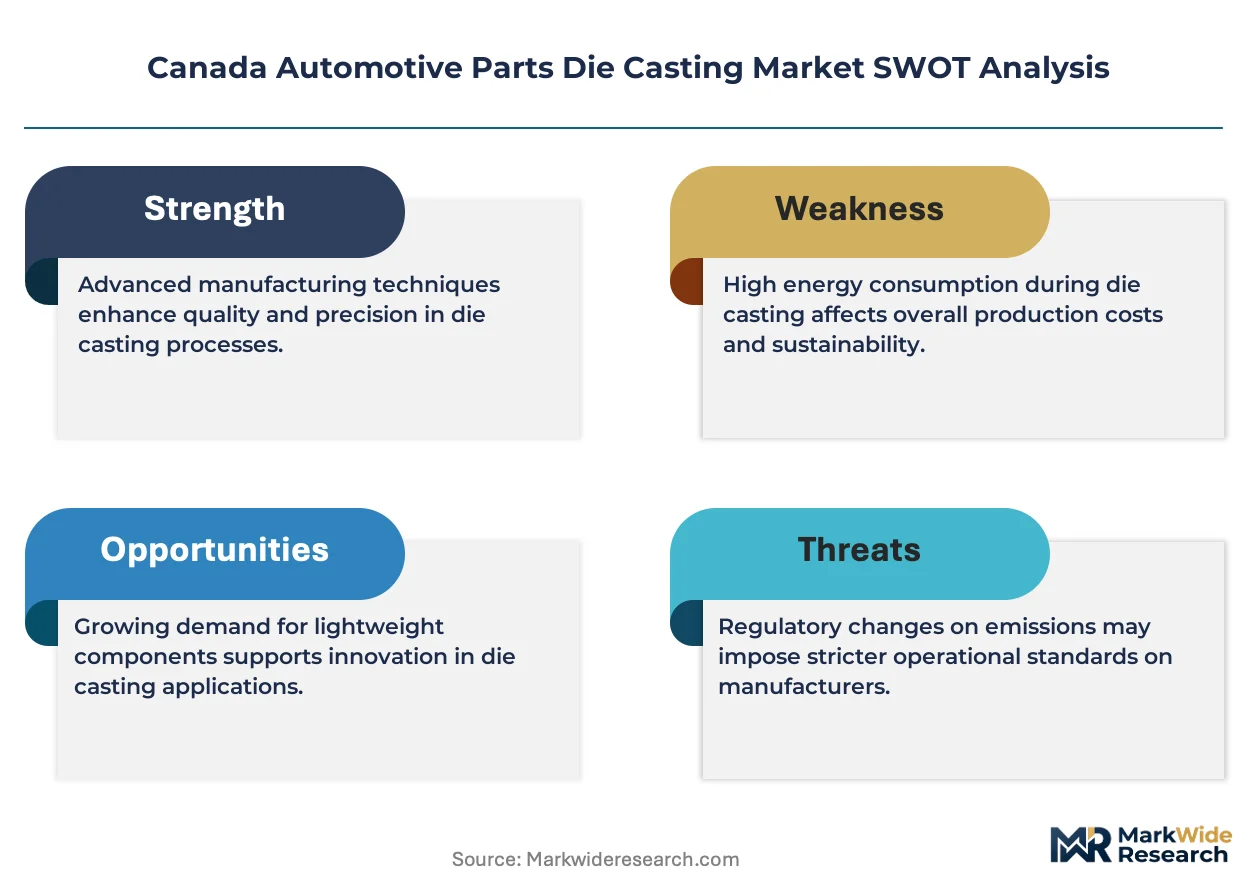
Aluminum is rebalancing traditional ferrous casting economics as OEMs pursue mass reduction targets for internal combustion and electrified platforms. Dynacast Inc. leverages its multi-site North American footprint to serve just-in-time transmission housing programs for Detroit Three transplant operations in Ontario. Endurance Technologies sustains cost-competitive magnesium cylinder head production through captive toolmaking and secondary machining integration. GIBBS DIE CASTING GROUP anchors its position via high-pressure aluminum die casting specialization for engine block architectures favored by domestic light truck manufacturers.
Automotive parts die casting employs high-pressure or gravity-fed molten metal injection into hardened steel molds to produce near-net-shape powertrain and structural components with tolerances typically within 0.1 mm; the process enables thin-wall geometries impossible with sand casting while delivering the thermal conductivity and strength-to-weight ratios critical for modern engine thermal management. Aluminum transmission housings dominate current volume given their penetration across both conventional and hybrid drivetrains, with magnesium engine blocks representing the fastest-expanding material segment as foundries resolve corrosion protection and creep resistance limitations. Primary casting operations capture the deepest margin pools due to capital intensity and mold design IP, while secondary machining stages face margin compression from automation-driven commoditization.
Environment and Climate Change Canada enforces increasingly stringent fleet emissions standards that directly mandate lightweighting across powertrain assemblies, while Transport Canada's Motor Vehicle Safety Regulations shape crashworthiness specifications affecting structural die cast component design. Health Canada coordinates with PMRA on occupational exposure limits for molten metal operations, influencing foundry capital allocation toward fume capture and automated pouring systems. Stakeholders must monitor how proposed federal zero-emission vehicle mandates redirect die casting demand from internal combustion engine blocks toward e-motor housings and battery tray structural nodes.
Market Dynamics
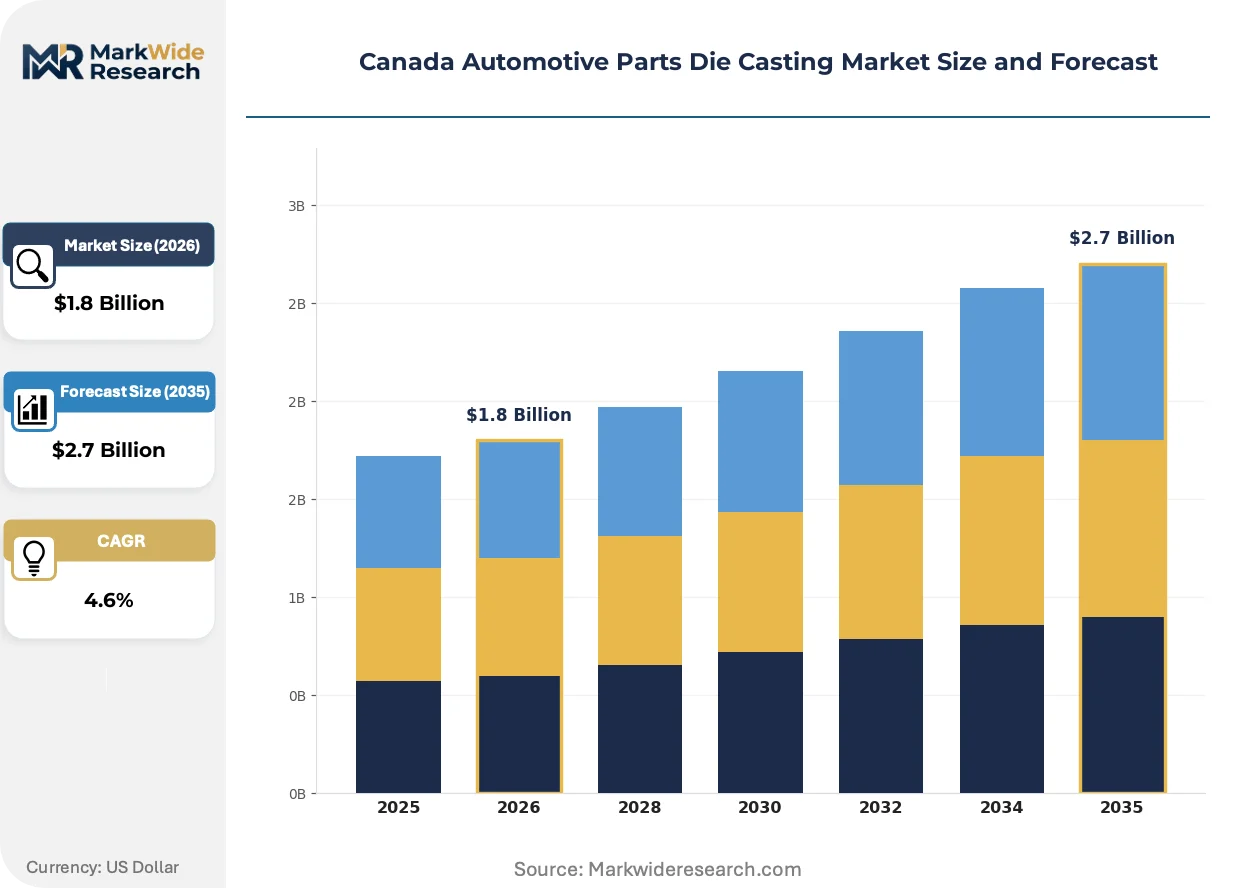
Environment and Climate Change Canada's fleet emissions mandates are forcing OEMs to shed mass from powertrain assemblies, redirecting die casting demand toward aluminum and magnesium alloys that preserve structural integrity at reduced weight.
Growth Catalysts
- Lightweighting mandates:Health Canada's proposed vehicle emissions framework updates compel domestic manufacturers to substitute ferrous castings with aluminum transmission housings.
- Ontario manufacturing corridor concentration:St. Thomas and Alliston assembly plant expansions generate just-in-time demand for precision-cast powertrain components within 150 kilometers of foundry operations.
- Hybrid drivetrain proliferation:Dual-powertrain architectures require aluminum housings that manage thermal loads across both internal combustion and electric motor systems.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings compress foundry margins on fixed-price OEM supply agreements.
- Magnesium corrosion limitations:Creep resistance and surface protection challenges restrict magnesium engine block adoption to niche performance applications.
- PMRA occupational exposure enforcement:Health Canada coordinated fume capture mandates require capital-intensive automated pouring system upgrades at legacy facilities.
Strategic Opportunities
- Battery tray structural nodes:Federal zero-emission vehicle mandates create white space for high-pressure aluminum die casting in electric vehicle chassis integration.
- E-motor housing specialization:Thermal management requirements for permanent magnet motors favor thin-wall die cast geometries over fabricated steel enclosures.
- Secondary machining integration:Captive CNC finishing operations capture margin pools currently lost to tier-two suppliers.
Industry Challenges
- Tooling engineer scarcity:Mold design IP development depends on specialized talent concentrated among retiring demographic cohorts in Windsor and Hamilton.
- Dual-platform tooling amortization:Simultaneous internal combustion and electric vehicle programs strain capital allocation across incompatible die specifications.
- Transport Canada crashworthiness certification:Structural die cast components face extended validation timelines for Motor Vehicle Safety Regulations compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Parts Die Casting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Housings, Engine Blocks, Cylinder Heads, Intake Manifolds Material: Aluminum, Zinc, Magnesium, Copper Manufacturing Stage: Primary Casting, Secondary Machining, Finishing, Tertiary Assembly End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | Dynacast Inc., Endurance Technologies, SYX Die Castings, Sandhar Group, Sunbeam Auto, GIBBS DIE CASTING GROUP, Castwel Autoparts, Sandar Technologies, ECO Die Castings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Parts Die Casting Market Strategic Shifts
Die casting technology is pivoting from standalone forming operations toward integrated manufacturing cells that combine molten metal injection with real-time quality verification and robotic finishing.
High-pressure vacuum-assisted die casting is converging with in-mold sensor networks to eliminate porosity defects in aluminum transmission housings. Tier-one suppliers serving Detroit Three transplant operations in Ontario are adopting these systems at replacement cycle intervals. The technology is converging with predictive maintenance platforms that extend die life beyond traditional 100,000-shot thresholds.
Environment and Climate Change Canada enforces progressively stringent fleet average emissions standards that explicitly credit mass reduction technologies. OEMs now specify aluminum content minimums in powertrain RFQs to secure regulatory compliance headroom. Light truck and SUV segments face the most aggressive lightweighting targets given their higher baseline curb weights.
Fleet procurement departments are consolidating supplier bases around single-source die casting partnerships with captive machining capability. Tier-one buyers are displacing multi-vendor spot purchasing with long-term program agreements that lock capacity at dedicated Ontario facilities. This concentration is most visible in transmission housing supply chains serving the Golden Horseshoe assembly corridor.
Canada Automotive Parts Die Casting Market Segmentation
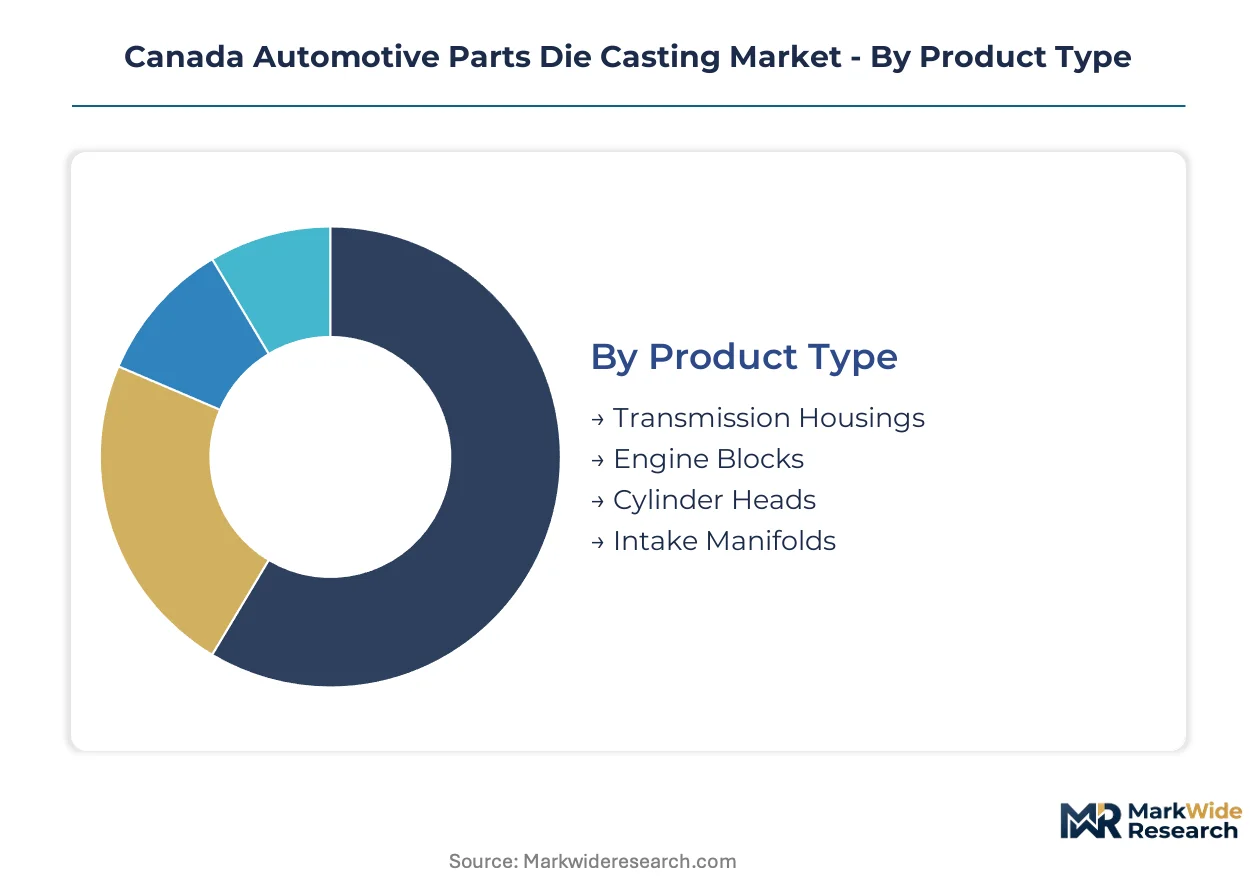
Die casting segmentation in Canada reflects divergent certification burdens across powertrain architectures. Material selection and manufacturing stage determine which components face Transport Canada crashworthiness validation versus Environment and Climate Change Canada emissions compliance pathways.
Product Type:
Transport Canada Motor Vehicle Safety Regulations impose distinct validation timelines on structural versus non-structural castings, with crashworthiness-certified components requiring extended homologation cycles.
- Transmission Housings:Aluminum alloy enclosures manage thermal loads across dual-powertrain architectures. St. Thomas and Alliston assembly plants generate concentrated demand within Ontario's Golden Horseshoe corridor for these thin-wall precision castings.
- Engine Blocks:High-pressure aluminum or magnesium architectures demand primary casting IP and secondary machining integration. Health Canada emissions framework updates are pressuring OEMs to lightweight these components for internal combustion and hybrid platforms.
- Cylinder Heads:Complex internal cooling channel geometries require gravity-fed or low-pressure die casting specialization.
- Intake Manifolds:Nylon-composite displacement in passenger cars has narrowed die cast demand to performance and commercial vehicle segments.
Leading the category by volume: Transmission Housings. Growing fastest: Engine Blocks.
Material:
Cost tiers separate commodity aluminum from premium magnesium and specialty copper alloys, with price volatility exposure varying by LME contract linkage.
- Aluminum:Dominates transmission housing and engine block production with favorable strength-to-weight ratios and established recycling infrastructure. Ontario foundries serving Detroit Three transplant operations concentrate capacity on this material tier.
- Magnesium:Fastest-expanding segment as foundries resolve corrosion protection and creep resistance limitations for powertrain applications. PMRA occupational exposure mandates drive automated pouring system adoption at facilities handling this material.
- Zinc:Limited to decorative and small structural automotive hardware given density disadvantages for powertrain components.
- Copper:Restricted to thermal management inserts and electrical busbar applications within hybrid drivetrain assemblies.
Volume leadership: Aluminum. Steepest expansion trajectory: Magnesium.
Manufacturing Stage:
Margin pools concentrate at the primary casting stage where mold design IP and capital intensity create barriers, while downstream stages face automation-driven commoditization.
- Primary Casting:Molten metal injection into hardened steel molds captures the deepest margins due to die life optimization and near-net-shape precision. Windsor and Hamilton foundries retain specialized tooling engineers for this stage.
- Secondary Machining:CNC finishing operations face margin compression from tier-two supplier competition but offer integration opportunities for tier-one suppliers.
- Finishing:Surface treatment and coating applications for corrosion protection, particularly critical for magnesium engine block commercialization.
- Tertiary Assembly:Component integration into sub-assemblies, often performed at OEM or tier-one facilities rather than captive foundry operations.
Deepest margin capture: Primary Casting. Fastest automation penetration: Secondary Machining.
End User:
Procurement consolidation around single-source partnerships favors tier-one suppliers with captive machining, displacing multi-vendor spot purchasing.
- OEMs:Direct sourcing of engine blocks and structural components with long-term program agreements locking capacity at dedicated Ontario facilities.
- Tier-1 Suppliers:Intermediate buyers consolidating transmission housing supply chains through just-in-time delivery contracts within 150 kilometers of Golden Horseshoe assembly plants.
- Aftermarket Providers:Replacement part demand for legacy vehicle fleets, limited by extended OEM part availability.
- Dealerships:Minimal direct die cast procurement, primarily accessing components through OEM parts distribution networks.
Contract concentration: Tier-1 Suppliers. Procurement consolidation target: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Die casting demand concentrates in Ontario's Golden Horseshoe corridor, where St. Thomas and Alliston assembly plants generate just-in-time procurement for aluminum transmission housings within 150 kilometers of foundry operations.
Ontario
St. Thomas and Alliston light truck and SUV expansions drive aluminum transmission housing orders through Windsor and Hamilton foundries. Environment and Climate Change Canada fleet emissions mandates pressure OEMs to lightweight powertrain components. The Golden Horseshoe manufacturing corridor surrounding Toronto anchors captive machining integration for tier-one suppliers serving Detroit Three transplant operations.
Quebec
Aluminum smelter proximity in Saguenay-Lac-Saint-Jean reduces feedstock logistics costs for secondary alloy production. Health Canada coordinates with PMRA on occupational exposure limits that shape foundry automation investments. Greater Montreal hosts specialized tooling engineering capacity supporting mold design IP development for precision cast components.
Alberta
Oil sands equipment manufacturing generates ancillary demand for heavy-duty cast components in industrial rather than automotive applications. The province's carbon pricing framework influences capital allocation decisions for energy-intensive primary casting operations. Edmonton and Calgary logistics hubs facilitate western distribution of die cast powertrain parts to Pacific Coast assembly plants.
British Columbia
Port of Vancouver transshipment activity supports aluminum alloy import flows from Asia-Pacific suppliers. The province's zero-emission vehicle mandate accelerates demand for e-motor housings and battery tray structural nodes. Lower Mainland manufacturing clusters near Vancouver specialize in secondary machining and surface finishing for magnesium corrosion protection.
Canada Automotive Parts Die Casting Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with tier-one suppliers consolidating around single-source partnerships while tier-two machining operations face margin compression from automation. The vendor base organizes around three archetypes: multi-site North American fabricators with just-in-time capability, cost-competitive magnesium specialists with captive toolmaking, and high-pressure aluminum die casting pure-plays. Competitive moves concentrate on secondary machining integration to capture margin pools and strategic partnerships to lock dedicated capacity at Ontario facilities.
Among North American-based operators, Dynacast Inc. and GIBBS DIE CASTING GROUP occupy positions within the high-pressure aluminum specialization tier, while Endurance Technologies exemplifies the integrated magnesium production archetype with captive capabilities.
| Leading Market Players |
|---|
| Dynacast Inc. |
| Endurance Technologies |
| SYX Die Castings |
| Sandhar Group |
| Sunbeam Auto |
| GIBBS DIE CASTING GROUP |
| Castwel Autoparts |
| Sandar Technologies |
| ECO Die Castings |
| Others |
Value Chain & Pricing Dynamics
High-pressure vacuum-assisted die casting adoption simultaneously compresses unit economics and consolidates supply power among Ontario foundries with capital reserves for automated pouring systems. Environment and Climate Change Canada emissions mandates force tier-one buyers into long-term program agreements that lock capacity at dedicated Golden Horseshoe facilities, embedding supply concentration into pricing structures.
Pricing Analysis
Volume leadership sits with aluminum transmission housings while magnesium engine blocks command premium margins. Pricing stratifies across primary casting, secondary machining, and finishing tiers based on capital intensity and mold design IP concentration. Cost compression in secondary machining intensifies because automation-driven commoditization erodes tier-two supplier margins. Tier-one OEMs exhibit lowest price sensitivity due to regulatory compliance requirements; aftermarket providers face highest sensitivity given spot purchasing patterns.
Supply Chain Analysis
Single-source vulnerability sits with primary aluminum feedstock flowing from Quebec smelters and LME contract-linked international suppliers. The Canadian automotive die casting supply chain draws from Quebec aluminum production, Chinese magnesium ingot imports, and domestic steel mold fabrication. Tariff exposure on magnesium imports represents the dominant structural risk. Distribution runs through just-in-time delivery networks within 150 kilometers of St. Thomas and Alliston assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where Health Canada coordinated PMRA occupational exposure mandates create capital barriers that protect incumbent foundries with automated fume capture systems.
For Market Incumbents: To counter tooling engineer scarcity in Windsor and Hamilton, prioritize captive CNC finishing integration to recapture margin pools from tier-two suppliers. Secure dedicated capacity lock-in agreements with Detroit Three transplant operations before federal zero-emission vehicle mandates redirect demand toward battery tray structural nodes. For New Entrants and Emerging Players: Aftermarket providers serving legacy light truck fleets represent the most penetrable buyer archetype given OEM part availability gaps. Target secondary machining specialization for magnesium corrosion protection as a white-space entry point. Pursue partnership-based go-to-market positioning with established Quebec aluminum smelters to secure feedstock cost advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multi-site North American fabricators seeking Ontario just-in-time capability. Long-term viability hinges on dual-platform tooling amortization across internal combustion and electric vehicle programs. Monitor federal zero-emission vehicle mandate implementation timelines as the critical inflection signal for demand redirection toward e-motor housings.| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Machining Integration | Captures margin pools from tier-two suppliers serving Detroit Three transplant operations. |
| Automated Pouring System Deployment | Addresses Health Canada PMRA occupational exposure mandates at legacy Ontario facilities. |
| Long-term Program Agreement Lock-in | Secures dedicated capacity with tier-one buyers consolidating around single-source partnerships. |
| Magnesium Corrosion Protection Specialization | Resolves creep resistance limitations blocking engine block commercialization. |
| Battery Tray Structural Node Development | Positions for federal zero-emission vehicle mandate-driven demand in electric vehicle chassis. |
Study Parameters
Industry association filings, Environment and Climate Change Canada regulatory databases, and vehicle production data formed the secondary backbone of this analysis. Primary interviews with tier-one supplier procurement officers, OEM platform engineers, Windsor foundry operations managers, and Health Canada regulatory affairs specialists combined with secondary validation. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored the quantitative framework.
Historical trendline analysis across automotive production cycles informed the projection methodology. The forecast framework segments by material tier, manufacturing stage, and propulsion architecture across the analysis window. CAGRs derive from regression analysis of production volume trajectories and content-per-vehicle assumptions. Aluminum price volatility exposure and tooling amortization schedules served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal zero-emission vehicle mandate implementation pace and primary aluminum LME contract swings. Forecasts reflect documented assumptions regarding St. Thomas and Alliston assembly plant expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Tappet Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Washer System Market