
 Automotive Parts Die Casting Market | 2026-2036
Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Parts Die Casting Market Analysis
The gap between premium structural castings and commodity engine brackets is shifting toward alloy sophistication and cavity complexity. Nemak dominates large-format aluminum battery housings for EV platforms. Linamar Corporation leverages its powertrain heritage to compete in transmission case consolidation. Ryobi Die Casting anchors Japanese OEM supply chains through precision high-pressure lines.
Automotive parts die casting is a metal-forming process where molten non-ferrous alloys—typically aluminum with 9-12% silicon content—are injected into hardened steel molds at pressures exceeding 1,000 bar to produce near-net-shape components with wall thicknesses below 3 millimeters. The primary purpose is mass production of lightweight, dimensionally stable parts that replace multiple stamped or welded assemblies in vehicle structures. Aluminum structural parts command the deepest margin pools as OEMs substitute cast nodes for stamped sheet-metal subframes. High-pressure die casting leads in volume throughput, while vacuum die casting captures premium pricing for porosity-critical safety components. Gravity die casting occupies a mature niche in aftermarket wheel and housing production where lower capital intensity offsets slower cycle times.
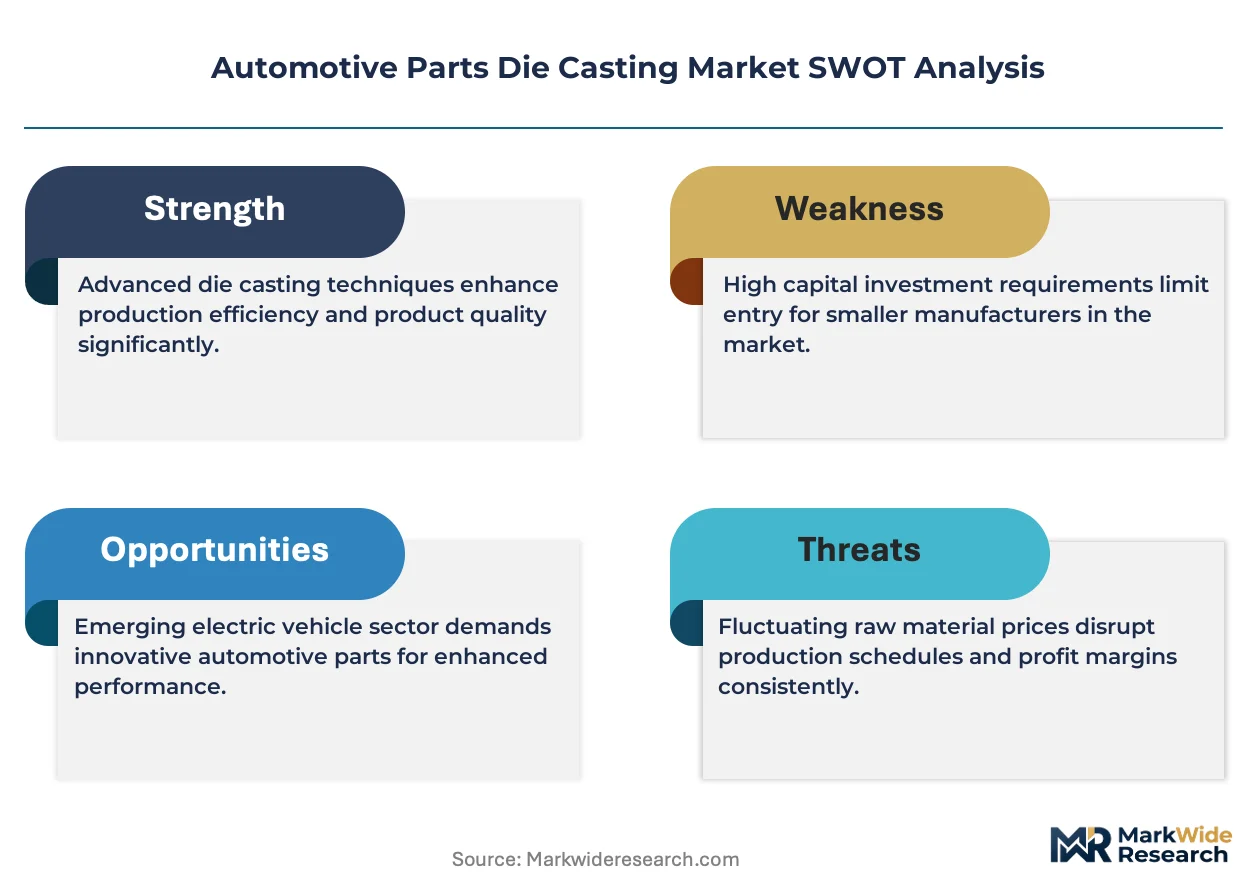
The EPA enforces foundry air-emission thresholds under the Clean Air Act that elevate scrubber investment for US-based die casters. REACH compliance in Europe restricts hexavalent chromium in mold coatings, pushing suppliers toward ceramic-based release agents. China's MEE implements dual carbon monitoring that ties foundry energy intensity to operating permits. Stakeholders must monitor how battery-electric platform architectures redistribute casting demand away from traditional engine blocks toward thermal management housings and structural battery trays.
Market Dynamics
Vehicle electrification is compressing traditional engine-block demand while simultaneously opening high-volume contracts for structural battery housings and thermal management modules. Foundries must retool for larger cavity dimensions and tighter porosity tolerances without sacrificing cycle economics.
Growth Catalysts
- EU F-Gas Regulation:Emissions benchmarks for foundry operations are accelerating capital deployment toward electric melting and regenerative thermal oxidizers across European supplier parks.
- Structural battery trays:OEM platform architectures now specify aluminum die-cast trays as primary load-bearing elements, creating dedicated capacity commitments from tier-one suppliers.
- China's dual carbon monitoring:MEE energy-intensity thresholds are filtering out smaller foundries and concentrating orders at scaled operators with certified low-carbon production.
Market Restraints
- Primary aluminum volatility:LME price swings and European smelter curtailments are compressing margin predictability for long-term OEM contracts.
- Tooling lead times:Hardened steel mold fabrication from specialized German and Japanese machine shops now extends 24-32 weeks, gating capacity expansion.
- REACH compliance friction:Hexavalent chromium restrictions in mold coatings are forcing costly reformulation of release-agent chemistries without performance guarantees.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives are attracting greenfield die-casting investments for export-oriented EV component manufacturing.
- Megacasting convergence:Integration of high-pressure die casting with in-mold joining is enabling single-piece rear underbody structures that eliminate 70-plus stamped parts.
- Closed-loop alloy recovery:OEMs are specifying post-consumer aluminum feedstock, creating premium pricing tiers for certified recycled-content castings.
Industry Challenges
- Process control engineering scarcity:Foundries face acute shortages of technicians capable of programming real-time shot-control systems for porosity-sensitive safety castings.
- Multi-material joining certification:Adhesive and mechanical fastening protocols for aluminum-to-steel interfaces lack standardized test regimes, delaying platform approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Parts Die Casting Market |
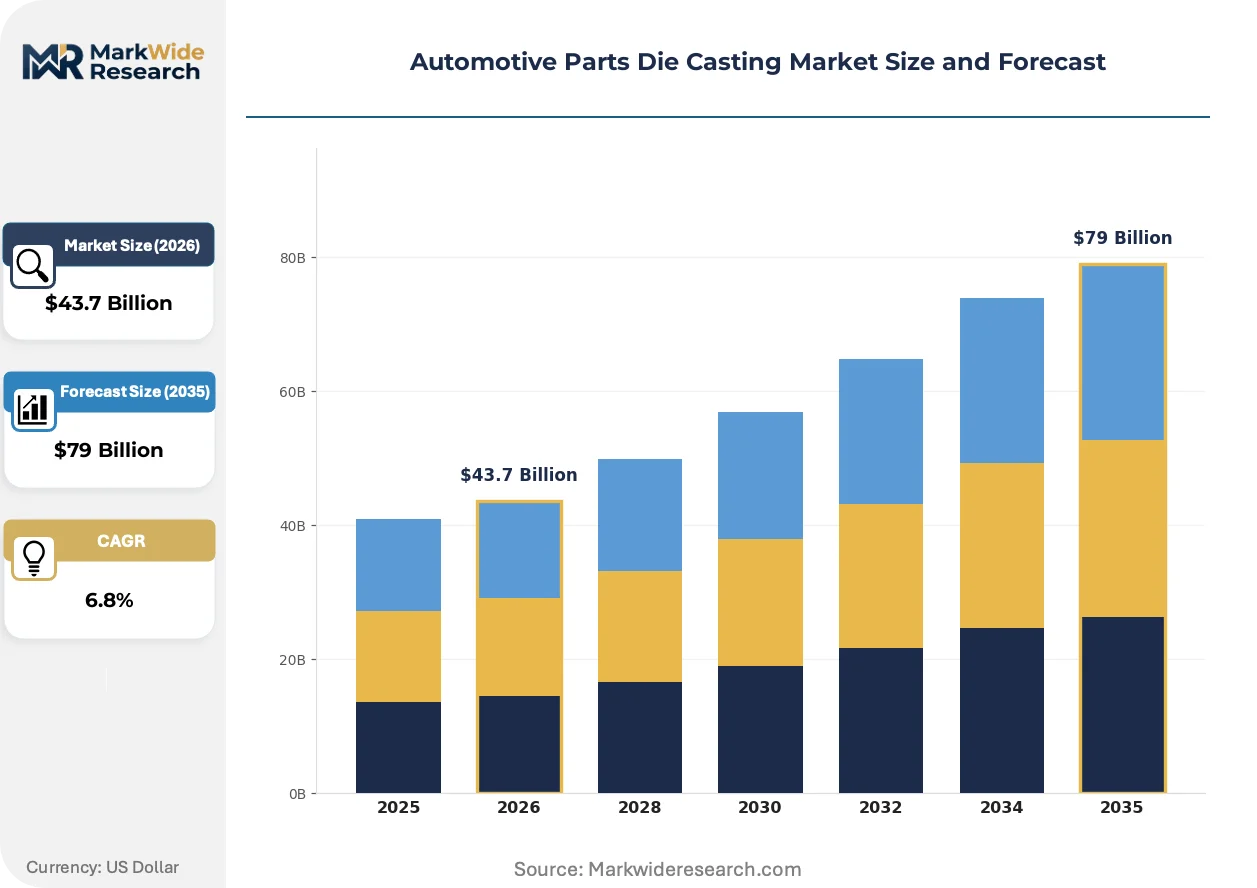
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Structural Parts, Housing Components Material: Aluminum, Magnesium, Zinc, Alloy End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Process Type: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting |
| Companies Covered | Linamar Corporation, Dynacast, Nemak, Endurance Technologies, Aludyne, Ryobi Die Casting, Martinrea International, GF Casting Solutions, Pace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Parts Die Casting Market Emerging Trajectories
Process digitization and alloy formulation advances are compressing development cycles for complex structural castings. Suppliers are racing to qualify next-generation equipment before platform engineering freezes lock in design choices.
Real-time shot monitoring using machine-vision and pressure-transducer feedback is unifying quality assurance with process control. Premium OEMs now mandate this capability for safety-critical structural nodes. The technology is compressing scrap rates and enabling just-in-sequence delivery without buffer inventory.
EPA Clean Air Act enforcement is elevating scrubber investment thresholds for US-based operations. Foundries in Michigan and Ohio are consolidating at sites with existing air-permit headroom rather than pursuing greenfield expansions. Smaller operators without capital reserves are exiting or selling to national platforms.
Buyer concentration among battery-electric platform architects is consolidating procurement at fewer foundries with proven large-format capability. Tier-one suppliers are responding with dedicated engineering cells co-located at OEM technical centers. Germany and China show the most pronounced concentration of these embedded development teams.
Automotive Parts Die Casting Market Segmentation
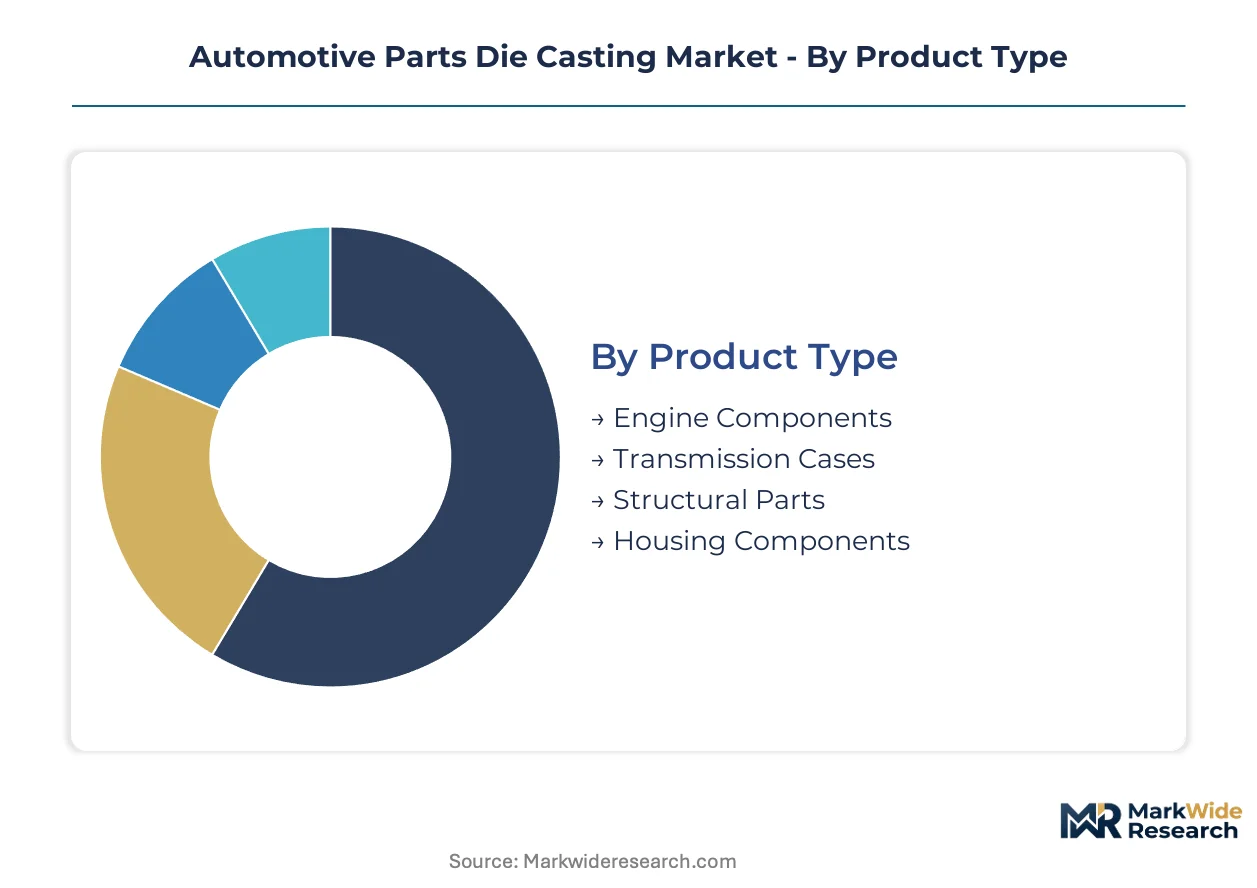
Automotive die casting procurement splits sharply between legacy powertrain programs and emerging EV architectures. Buyers now specify cavity complexity, alloy recyclability, and porosity certification as primary selection criteria rather than unit cost alone.
Product Type:
Platform engineering teams prioritize weight reduction targets and assembly elimination when specifying casting categories.
- Structural Parts:Aluminum nodes and subframe castings replace 30-70 stamped steel assemblies in unibody construction. German premium OEMs source these for lightweight chassis programs under stringent crash-performance protocols.
- Housing Components:Battery trays, thermal management modules, and inverter enclosures demand large-format cavities with sub-2% porosity tolerances. EV platform architects in China and Germany concentrate procurement here.
- Engine Components:Cylinder heads and blocks face compressing demand as electrification displaces internal combustion volumes.
- Transmission Cases:Hybrid transmissions sustain moderate volumes while pure-electric reductions erode long-term contracts.
Structural parts lead on scale; housing components lead on momentum.
Material:
Alloy selection hinges on strength-to-weight ratios, corrosion resistance, and OEM circular-economy mandates.
- Aluminum:Silicon-modified grades with 9-12% Si content dominate high-pressure applications. Recycled-content certifications now command premium pricing tiers from European and North American OEMs.
- Magnesium:AZ91D and AM60B alloys serve steering wheels, seat frames, and instrument panel beams where 30-40% mass reduction justifies higher raw material costs.
- Zinc:ZAMAK alloys occupy interior trim and small mechanical hardware with excellent surface finish and thin-wall capability.
- Alloy:Custom aluminum-silicon-magnesium formulations target specific strength and ductility requirements for safety-critical structural nodes.
Aluminum dominates installed capacity; magnesium claims the steepest expansion trajectory.
End User:
Procurement authority is consolidating at fewer decision points as platform architectures standardize.
- OEMs:Volkswagen Group, BMW, and Tesla retain direct sourcing for structural battery trays and megacast underbodies, bypassing traditional tier-one intermediaries.
- Tier-1 Suppliers:Continental, Bosch, and ZF procure transmission cases and thermal management housings under systems-integration contracts.
- Vehicle Assemblers:Contract manufacturers and EV startups source commodity brackets and small housings through consolidated supplier portals.
- Aftermarket Providers:Wheel manufacturers and repair part distributors rely on gravity die casting for lower-volume, design-frozen components.
OEMs lead on scale; tier-1 suppliers lead on momentum.
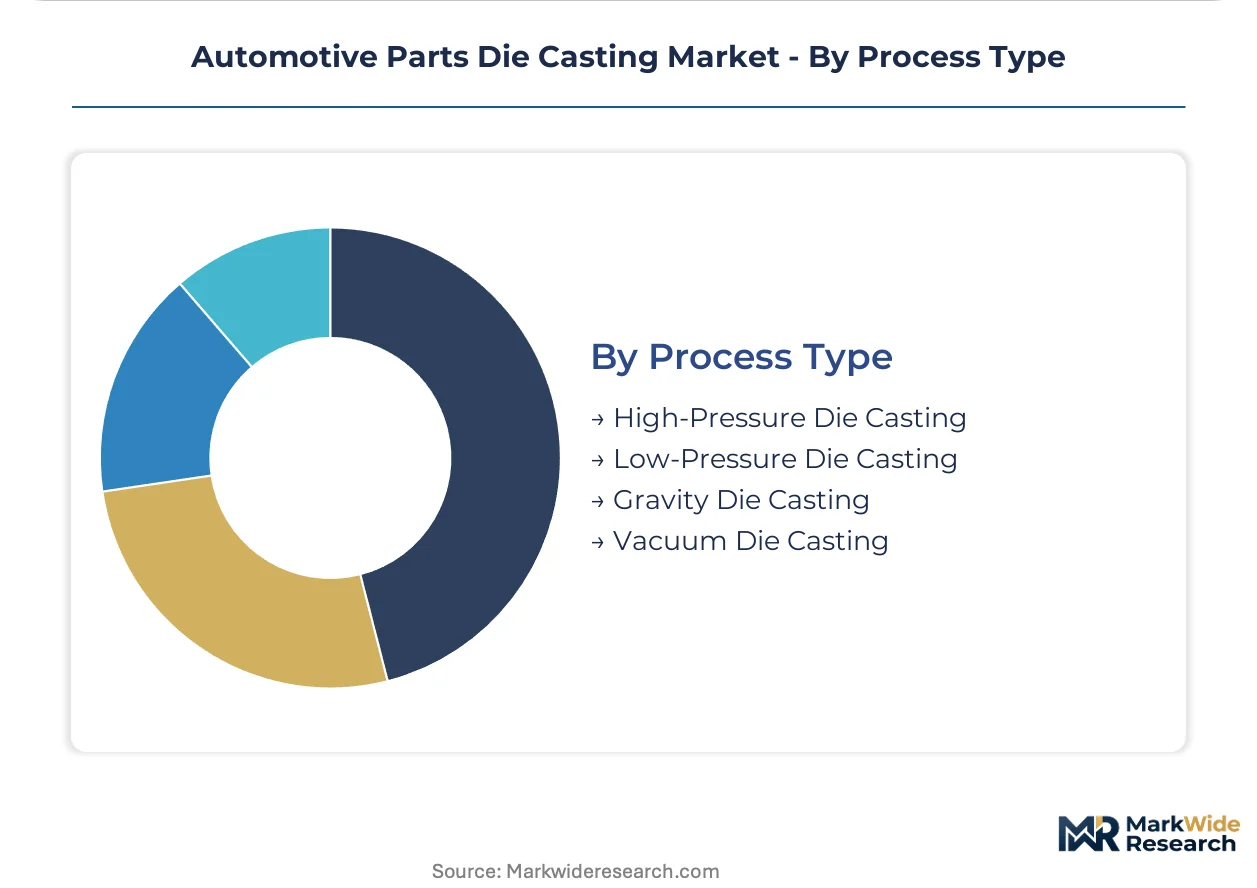
Process Type:
Capital intensity and cycle economics determine process selection for each component category.
- High-Pressure Die Casting:Molten metal injection above 1,000 bar achieves sub-3mm wall thicknesses at 60-90 second cycles. This process captures structural battery trays and megacast rear underbodies for Tesla and Chinese EV platforms.
- Vacuum Die Casting:Evacuated cavities before metal injection eliminate gas porosity for safety-critical brake caliper brackets and steering knuckles. Premium OEMs mandate this capability for structural nodes.
- Low-Pressure Die Casting:Controlled metal rise from below produces denser castings for wheels and suspension arms with moderate complexity.
- Gravity Die Casting:Manual or tilt-pour methods serve aftermarket wheels and low-volume housings where tooling costs must stay below $50,000.
High-pressure die casting leads on scale; vacuum die casting leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China demonstrate divergent pathways for die casting demand, with German OEMs prioritizing structural complexity while Chinese producers scale for battery-electric volume. Mexico and India are capturing relocation flows from higher-cost jurisdictions. The United States retains specialized capacity for powertrain heritage programs.
China
Domestic EV platforms from BYD and NIO are generating unprecedented demand for large-format battery housings and megacast rear underbodies. The MEE enforces dual carbon monitoring that ties foundry energy intensity directly to operating permits, filtering out smaller operators. Capacity concentrates in the Yangtze River Delta around Shanghai and Ningbo, where scaled suppliers serve Tesla Shanghai and local EV architects.
Germany
Premium OEMs including BMW and Mercedes-Benz source complex structural nodes for lightweight chassis programs under stringent crash-performance protocols. The EU F-Gas Regulation accelerates capital deployment toward electric melting and regenerative thermal oxidizers across supplier parks. Industrial density peaks in Bavaria and Baden-Württemberg, where embedded engineering cells co-locate at OEM technical centers.
United States
Legacy powertrain contracts sustain demand for transmission cases and engine components even as electrification compresses long-term volumes. The EPA enforces foundry air-emission thresholds under the Clean Air Act that elevate scrubber investment for Michigan and Ohio operations. Foundries are consolidating at sites with existing air-permit headroom rather than pursuing greenfield expansions.
Mexico
Proximity to US assembly plants positions Mexican foundries for just-in-sequence delivery of structural castings and thermal management housings. Trade integration under USMCA supports cross-border supply chains for EV platform components. Investment clusters in Nuevo León and the Bajío Region, where suppliers serve Tesla Austin and Detroit Three programs.
India
Export-oriented manufacturing for global EV supply chains is attracting greenfield die-casting investments under the PLI scheme for auto components. BIS certification requirements for aluminum alloy grades align domestic capacity with international OEM specifications. Production concentrates in Gujarat and Maharashtra, where suppliers target European and North American tier-one procurement.
Automotive Parts Die Casting Market Vendor Landscape
Top-tier vendors anchor large-format structural casting programs, while mid-scale operators compete on transmission case consolidation and thermal management modules. The vendor base stratifies across three capability tiers: integrated OEM-direct suppliers, tier-one systems integrators, and regional specialists serving aftermarket and commodity brackets. Dominant competitive moves include capacity expansion for megacasting cells and strategic partnerships for closed-loop alloy recovery certification.
Within the integrated OEM-direct tier, Nemak and Ryobi Die Casting represent contrasting geographic anchoring strategies. Nemak exemplifies the North American-European axis for battery housing dominance, while Ryobi Die Casting occupies a position within Japanese OEM supply chains through precision high-pressure lines. Linamar Corporation sits within the tier-one systems integrator archetype, leveraging powertrain heritage to compete in transmission case consolidation.
| Leading Market Players |
|---|
| Linamar Corporation |
| Dynacast |
| Nemak |
| Endurance Technologies |
| Aludyne |
| Ryobi Die Casting |
| Martinrea International |
| GF Casting Solutions |
| Pace Industries |
| Others |
Supply Flow & Price Mechanics
OEM consolidation around megacast structural programs is forcing foundries to absorb tooling amortization across longer contract horizons while negotiating raw-material pass-through clauses. This procurement shift compresses margin buffers for operators without scale-advantaged melting capacity or captive alloy supply.
Pricing Analysis
Capacity additions in China and Mexico are reshaping price floors for commodity aluminum housings while vacuum-capable European foundries maintain premium positioning. Contract-based long-term offtake dominates structural battery tray procurement, with price differentiation driven by porosity certification tier and recycled-content grade. Cost compression in standard high-pressure segments is intensifying because primary aluminum volatility outpaces hedging instruments. Aftermarket distributors show highest price sensitivity; OEM-direct structural programs show lowest.
Supply Chain Analysis
India's PLI scheme and Mexico's USMCA compliance requirements are reshaping sourcing patterns for export-oriented EV component manufacturing. Supply concentrates in China, Germany, and Mexico for large-format structural castings, with tooling fabrication dependencies in Japan and Germany. Raw material flows draw from primary aluminum smelters in Canada, Russia, and the Middle East, with secondary alloy recovery emerging in Europe and North America. Single-source vulnerability sits with specialized mold steel suppliers. Distribution runs through tier-one systems integrators co-located at OEM technical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive parts die casting has entered a late-cycle quality phase where alloy sophistication and cavity complexity separate viable operators from commodity casualties. The demand shift toward sub-2% porosity certification for safety-critical structural nodes justifies this framing.
For Market Incumbents: Acquire vacuum die casting capability and real-time shot monitoring technology to defend structural battery tray contracts against emerging Asian competitors. Consolidate at sites with existing air-permit headroom rather than greenfield expansion. Secure closed-loop alloy recovery certification before OEM circular-economy mandates harden procurement criteria. For New Entrants and Emerging Players: EV startup assemblers and second-tier hybrid powertrain suppliers represent underserved buyer archetypes with less stringent qualification timelines. Target India's export-oriented PLI corridor for greenfield capacity with BIS-certified alloy grades. Enter through gravity die casting for aftermarket wheels before migrating to high-pressure structural programs. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale operators possessing vacuum capability but lacking OEM-direct relationships. Five-to-ten-year viability favors foundries with certified low-carbon production under China's MEE thresholds or EU F-Gas compliance. Watch for inflection when megacast rear underbody programs reach platform engineering freeze at volume OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Megacasting Cell Investment | Enables single-piece rear underbody structures for Tesla and Chinese EV platforms. |
| Closed-Loop Alloy Recovery | Captures premium pricing tiers from European OEM circular-economy mandates. |
| Vacuum Die Casting Qualification | Meets BMW and Mercedes-Benz porosity protocols for safety-critical nodes. |
| Embedded Engineering Partnership | Co-locates development teams at OEM technical centers in Germany and China. |
| Electric Melting Conversion | Satisfies EU F-Gas Regulation thresholds for foundry emissions compliance. |
Methodological Framework
Bottom-up EV platform modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-one supplier procurement leads, foundry operations directors, and aftermarket distributors were validated against secondary sources including vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and customs records for aluminum alloy trade flows. Triangulation across these inputs ensures segment-level precision.
Input-output matrices map casting demand by vehicle propulsion architecture, content per vehicle, and regional production cluster across the projection horizon. Segmentation dimensions include product type, material grade, process technology, and end-user procurement authority. CAGRs derive from production volume trajectories weighted by alloy-specific content factors and platform standardization timelines. Forecast inputs incorporate MEE energy-intensity thresholds and REACH reformulation costs as regulatory constraints.
Underlying measurement precision varies by segment; structural battery trays and megacast underbodies carry tighter precision than commodity engine brackets due to visible OEM platform commitments. Forecasts reflect assumptions around electrification penetration and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Washer System Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Adaptive Engine Mounts Market