
 Clutch Pedal Kit Market | 2026-2036
Clutch Pedal Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Clutch Pedal Kit Market Analytics
Aftermarket distribution networks in Southeast Asia are reshaping how clutch pedal kit manufacturers reach repair shops and independent garages. KSR International leverages its North American manufacturing footprint to sustain consistent supply to tier-one OEM contracts. F-Tech anchors its competitive position through specialized hydraulic clutch actuation systems for Japanese passenger car platforms. WABCO competes aggressively in the commercial vehicle channel with integrated pedal modules that combine electronic sensors with mechanical linkage.
A clutch pedal kit comprises the pedal assembly, pivot bushings, return springs, and mounting hardware that translate driver foot force into clutch disengagement. Steel and aluminum stampings typically form the load-bearing structure, with plastic or composite covers reducing noise and corrosion susceptibility. Performance kits command premium positioning among enthusiast segments seeking adjustable pedal ratios and reinforced pivot points. Heavy-duty kits dominate margin pools in the commercial vehicle category, where fleet operators prioritize service intervals exceeding standard passenger car specifications.
EPA emissions compliance in the United States and EU Green Deal carbon benchmarks in Europe both pressure OEMs to optimize drivetrain efficiency, indirectly tightening clutch system durability standards. ANVISA in Brazil and NHTSA in the United States enforce distinct crashworthiness and pedal retention protocols that fragment certification requirements across manufacturing footprints. Stakeholders must monitor regulatory divergence between major automotive markets when allocating R&D and homologation budgets.
Market Dynamics
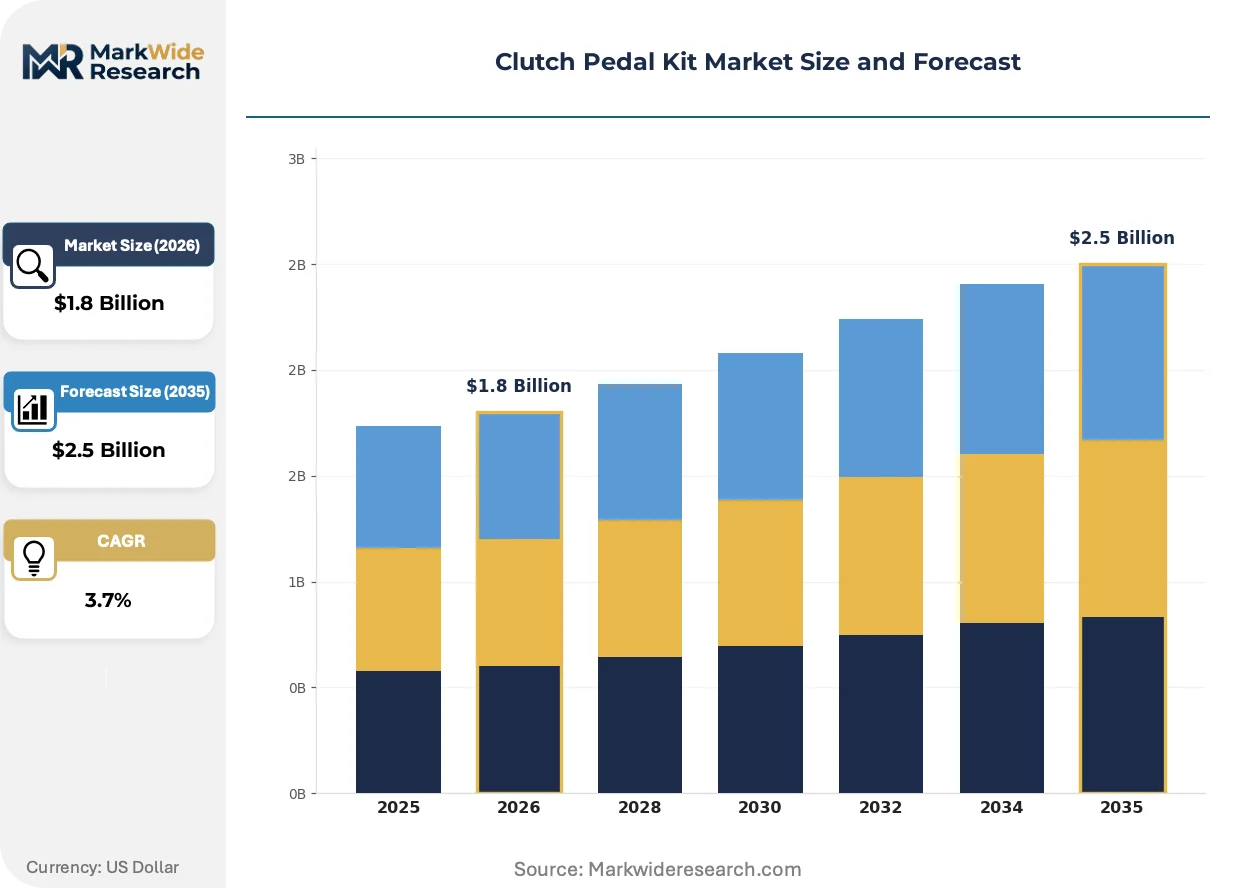
Fleet electrification timelines and residual internal combustion vehicle parc maintenance are creating divergent demand streams for clutch pedal kits, with commercial vehicle operators extending service intervals while passenger car volumes contract.
Growth Catalysts
- CONTRAN safety mandates:Brazil's commercial vehicle durability requirements are forcing OEMs to upgrade clutch control systems, expanding the addressable market for heavy-duty pedal assemblies in São Paulo state's logistics corridor.
- Hydraulic actuation technology:Specialized hydraulic clutch systems are penetrating Japanese passenger car platforms, reducing mechanical wear and extending replacement cycles in high-mileage applications.
- Integrated sensor modules:Electronic pedal position sensing is migrating into commercial vehicle channels, creating aftermarket upgrade demand as fleets retrofit aging trucks with telematics-compatible controls.
Market Restraints
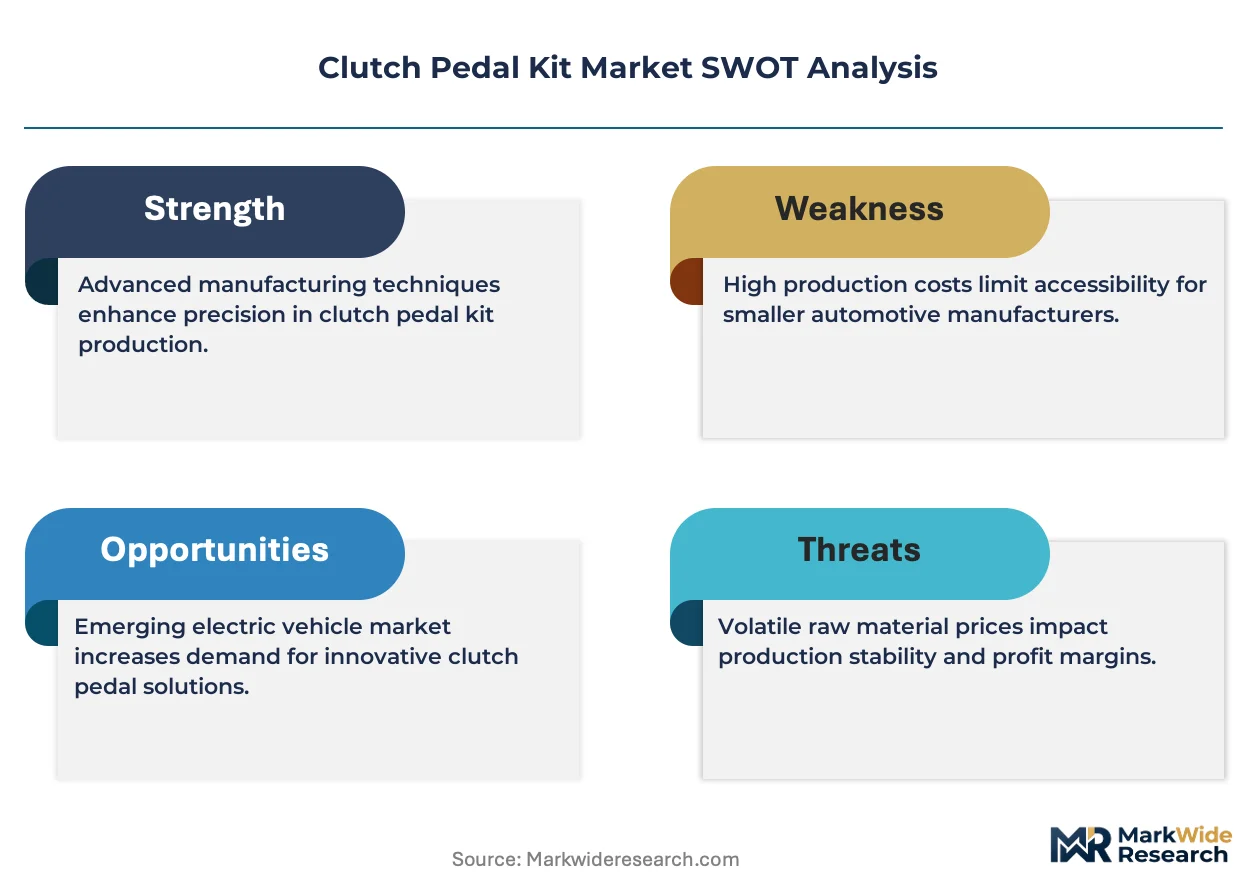
- Steel price volatility:Load-bearing stampings face input cost pressure from commodity fluctuations, compressing margins for standard-grade kit manufacturers without long-term supply contracts.
- Single-source pivot bushing supply:Southeast Asian forging capacity concentrates in Thai and Vietnamese facilities, creating vulnerability to regional logistics disruptions.
- Electrification substitution:Battery-electric commercial vehicles eliminate mechanical clutch systems entirely, permanently removing addressable units from forward fleet replacement schedules.
Strategic Opportunities
- Performance enthusiast segments:Adjustable pedal ratio kits command premium positioning among motorsport applications, with reinforced pivot points addressing durability gaps in track-day vehicle modifications.
- EU Green Deal carbon benchmarks:Drivetrain efficiency optimization mandates are tightening clutch system durability standards, creating certified-component upgrade pathways for European fleet operators.
- Direct-to-garage distribution:Digital procurement platforms are disintermediating traditional wholesale channels, enabling manufacturers to capture margin previously allocated to regional distributors.
Industry Challenges
- Homologation timeline compression:Divergent crashworthiness protocols between NHTSA and ANVISA are fragmenting certification requirements, forcing parallel testing tracks for multi-market suppliers.
- Legacy system integration:Electronic sensor modules must interface with mechanical linkage architectures designed decades prior, creating calibration complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clutch Pedal Kit Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kits, Performance Kits, Heavy-Duty Kits, Universal Kits Vehicle Type: Passenger Cars, Light Trucks, Motorcycles, Commercial Vehicles Material: Aluminum, Steel, Plastic, Composite End User: OEMs, Aftermarket Retailers, Repair Shops, Enthusiasts |
| Companies Covered | KSR International, F-Tech, WABCO, CJ Automotive, CTS, Brano Group, Samvardhana Motherson Group, Toyoda Iron Works, Batz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clutch Pedal Kit Market Evolving Landscape
Material substitution and electronic integration are redefining clutch pedal kit architectures, with durability specifications diverging sharply between electrification-resistant commercial segments and declining passenger car volumes.
Aluminum stampings are displacing traditional steel load-bearing structures in premium passenger car applications. European OEMs specify aluminum pedal assemblies to reduce unsprung mass and corrosion susceptibility in salt-exposed markets. The technology is migrating from luxury platforms into mid-range vehicle lines as stamping costs compress.
EPA emissions compliance protocols in the United States are indirectly tightening clutch system specifications through drivetrain efficiency optimization mandates. OEMs now specify pedal assemblies with reduced friction losses and tighter manufacturing tolerances to meet fleet-wide carbon targets. Commercial vehicle channels face the most stringent durability adjustments, with service interval requirements extending substantially beyond historical passenger car benchmarks.
Aftermarket procurement behavior is fragmenting as independent garages source components through specialized e-commerce platforms rather than traditional wholesale distributors. Southeast Asian repair shops now place direct orders with manufacturers, bypassing regional warehousing layers. This channel shift concentrates in Indonesia and Vietnam, where logistics infrastructure improvements enable reliable direct delivery to dispersed garage networks.
Clutch Pedal Kit Market Segmentation
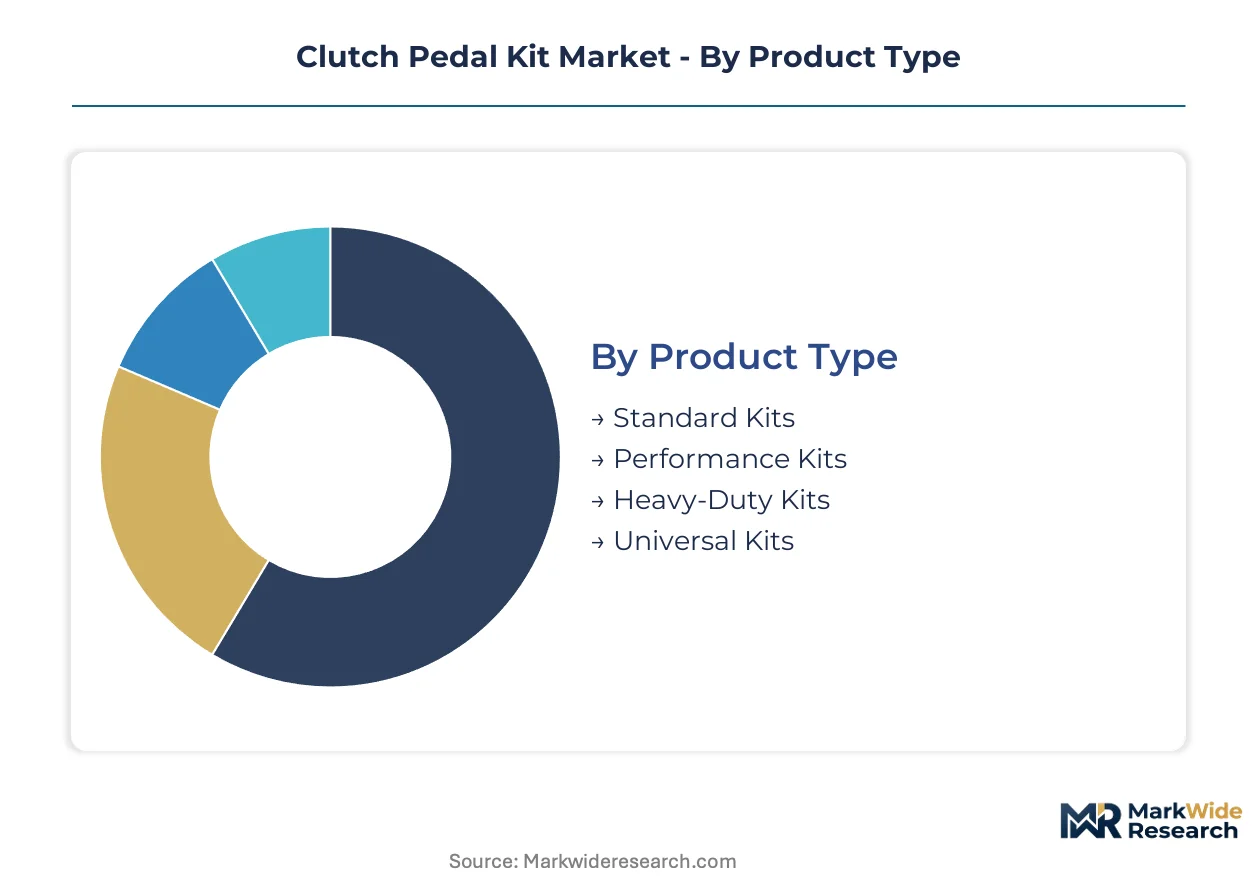
Clutch pedal kit manufacturers face divergent service interval requirements across vehicle categories, with commercial fleets demanding extended durability while passenger car volumes contract. Aftermarket channels exhibit distinct procurement patterns between independent garages and enthusiast segments, reshaping how suppliers allocate inventory and technical support resources.
Product Type:
After-sales-service intensity varies sharply across kit categories, with heavy-duty applications requiring technical field support and performance segments demanding specialized installation guidance.
- Standard Kits:Basic assemblies with stamped steel load-bearing structures and polymer covers serve high-volume replacement cycles in aging passenger car parc. Demand concentrates in Southeast Asian independent garage networks where cost-sensitive procurement dominates.
- Performance Kits:Adjustable pedal ratios and reinforced pivot points address motorsport applications with track-day vehicle modifications. Enthusiast segments in Germany and Japan drive premium positioning through specialized e-commerce channels.
- Heavy-Duty Kits:Extended service interval specifications exceed passenger car benchmarks for logistics fleet operators.
- Universal Kits:Cross-platform compatibility reduces inventory carrying costs for aftermarket distributors serving fragmented vehicle parc.
Heavy-Duty Kits hold the largest share; momentum sits with Performance Kits.
Vehicle Type:
Cost tier differentiation separates premium OEM specifications from economy aftermarket replacements, with commercial vehicle channels commanding substantial margin premiums.
- Passenger Cars:Contracting production volumes in electrifying markets compress addressable units, though residual internal combustion parc sustains replacement demand. European OEMs specify aluminum assemblies to meet EU Green Deal carbon benchmarks through mass reduction.
- Commercial Vehicles:Fleet operators in Brazil's São Paulo logistics corridor prioritize service intervals exceeding standard specifications under CONTRAN safety mandates. Heavy-duty pedal assemblies capture dominant margin pools in this channel.
- Light Trucks:Mixed-use applications bridge passenger car and commercial durability requirements.
- Motorcycles:Compact form factors demand specialized pivot geometry and reduced component count.
Commercial Vehicles command premium pricing; Passenger Cars retain volume leadership despite structural decline.
Material:
Supply concentration in Southeast Asian forging capacity creates vulnerability to regional logistics disruptions, particularly for steel load-bearing components.
- Aluminum:Unsprung mass reduction and corrosion resistance in salt-exposed markets drive specification in European luxury platforms. Stamping cost compression enables migration into mid-range vehicle lines.
- Steel:Commodity price volatility pressures margin structures for manufacturers lacking long-term supply contracts. Thai and Vietnamese forging facilities concentrate global capacity for load-bearing stampings.
- Plastic:Noise dampening and aesthetic finishing in cover applications.
- Composite:Emerging formulations target weight reduction with enhanced fatigue resistance.
Steel retains cost-driven volume dominance; Aluminum gains share fastest in premium specifications.
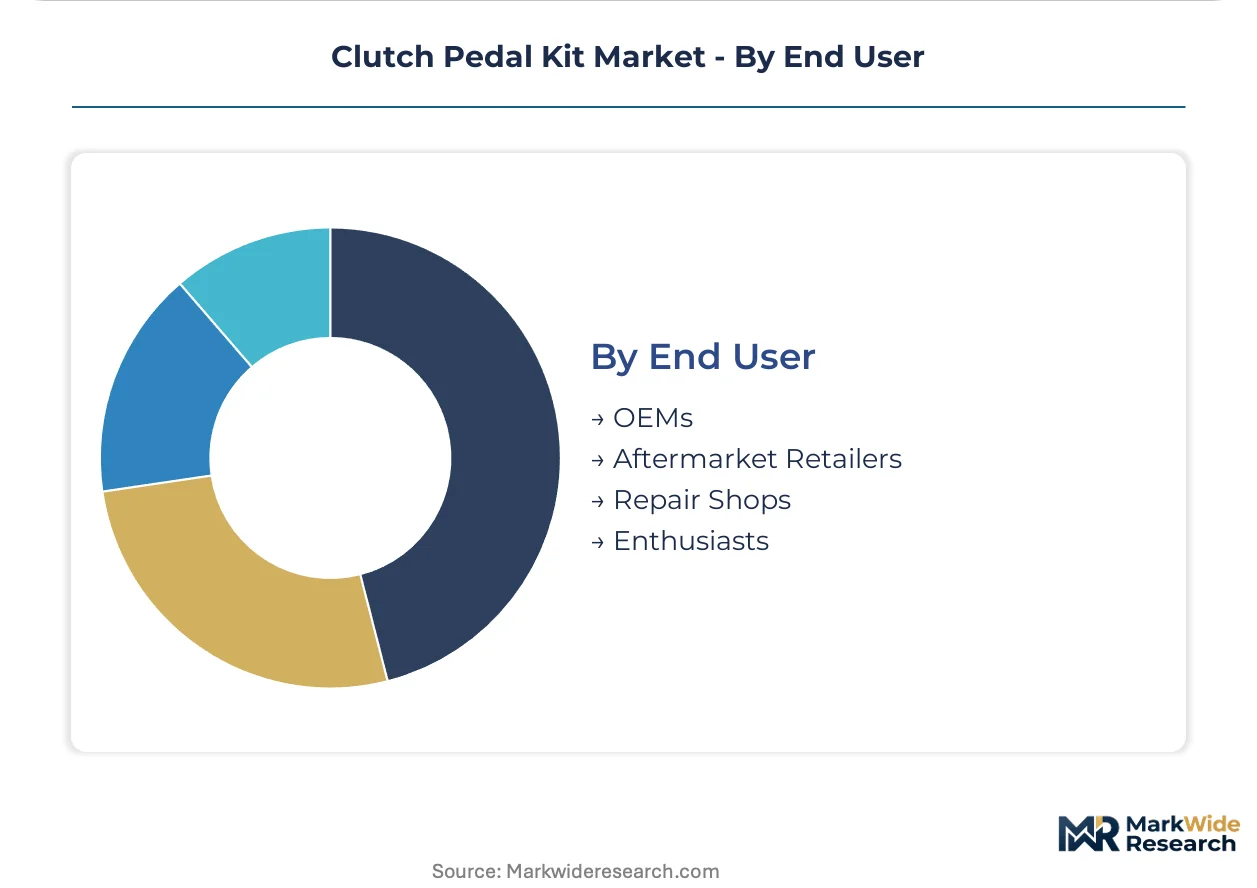
End User:
Customer type determines channel economics, with direct-to-garage procurement disintermediating traditional wholesale layers in digitally mature markets.
- OEMs:Tier-one contracts demand consistent supply and tight manufacturing tolerances to meet EPA emissions compliance through drivetrain efficiency optimization. KSR International leverages North American manufacturing footprint to sustain these relationships.
- Aftermarket Retailers:Regional warehousing layers face margin compression as Indonesian and Vietnamese repair shops place direct manufacturer orders through specialized e-commerce platforms.
- Repair Shops:Technical support requirements and installation training needs differentiate service levels.
- Enthusiasts:Customization demand and brand loyalty create niche premium opportunities.
OEMs anchor revenue stability; Aftermarket Retailers face the steepest channel restructuring pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal underwrites Brazil's logistics corridor dominance for heavy-duty clutch systems. European rail freight networks connecting the Rhine-Ruhr industrial belt to Mediterranean ports sustain aluminum stamping demand for premium passenger vehicles. The Trans-Siberian Railway corridor enables just-in-time component flows to Russian aftermarket distributors despite sanctions complexity.
United States
EPA emissions compliance protocols tighten clutch system specifications through drivetrain efficiency mandates. NHTSA crashworthiness protocols enforce distinct pedal retention standards that fragment certification requirements. Detroit's automotive cluster concentrates OEM contract manufacturing for tier-one suppliers serving domestic light truck platforms.
Germany
EU Green Deal carbon benchmarks drive aluminum pedal assembly specifications for mass reduction in salt-exposed markets. KBA vehicle type approval mandates extend durability testing protocols for commercial vehicle control systems. Stuttgart's supplier ecosystem anchors development of adjustable ratio performance kits for enthusiast segments.
Brazil
CONTRAN safety mandates force OEM upgrades to heavy-duty clutch control systems in expanding commercial fleets. ANVISA commercial vehicle durability requirements tighten alongside logistics operator modernization of aging truck parc. São Paulo state's industrial corridor clusters OEM assembly plants with aftermarket distribution hubs serving Mercosur markets.
Japan
METI industrial standards guide hydraulic actuation technology penetration into passenger car platforms for reduced mechanical wear. PMDA automotive component oversight ensures traceability in safety-critical control systems. Nagoya's Chubu manufacturing belt concentrates precision forging capacity for pivot bushing supply to Southeast Asian assembly operations.
India
BIS automotive component standards harmonize with ASEAN technical regulations for export-oriented manufacturing. PLI scheme incentives attract stamping capacity investments for domestic commercial vehicle platforms. Tamil Nadu's Sriperumbudur industrial zone hosts OEM assembly plants sourcing heavy-duty kits for logistics fleet expansion.
Clutch Pedal Kit Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with forging and stamping expertise. The market structure consolidates around tier-one automotive suppliers with captive OEM relationships, while mid-scale fabricators compete on aftermarket channel access. Two strategic archetypes dominate: integrated pedal module suppliers combining electronic sensing with mechanical linkage, and pure-play stamping houses serving cost-sensitive replacement cycles. Competitive moves concentrate on geographic footprint expansion into Brazilian logistics corridors and direct-to-garage digital channel development.
Within the integrated systems tier, WABCO and F-Tech exemplify divergent specialization vectors. WABCO occupies a position representing commercial vehicle channel concentration with sensor-integrated modules. F-Tech anchors the hydraulic actuation specialization visible in Japanese platform supply. KSR International sits within the North American manufacturing archetype sustaining consistent tier-one OEM contract fulfillment. These three entities collectively illustrate how geographic manufacturing footprints align with distinct regulatory compliance requirements across EPA, EU Green Deal, and CONTRAN mandate jurisdictions.
| Leading Market Players |
|---|
| KSR International |
| F-Tech |
| WABCO |
| CJ Automotive |
| CTS |
| Brano Group |
| Samvardhana Motherson Group |
| Toyoda Iron Works |
| Batz |
| Others |
Value Network & Pricing Analysis
The Port of Santos container terminal's freight cost dynamics amplify pricing power for Thai and Vietnamese forging facilities while forcing three-tier price differentiation across OEM, fleet, and independent garage buyer archetypes.
Pricing Analysis
Volume-discount tiering structures separate long-term OEM contracts from spot aftermarket purchases, with fleet procurement leveraging multi-year offtake agreements for heavy-duty assemblies. Price differentiation hinges on CONTRAN certification grade and after-sales technical support bundling. Cost compression in standard-grade kits is intensifying because Brazilian logistics operators consolidate supplier relationships. Independent garages in Southeast Asia exhibit highest price sensitivity; European OEMs demonstrate least.
Supply Chain Analysis
Export-control regimes limiting precision forging technology flows to Southeast Asian facilities concentrate pivot bushing supply in Thai and Vietnamese stamping operations. Load-bearing steel stampings and aluminum extrusions draw from Japanese and German raw material processing. Single-source vulnerability pervades the pivot bushing tier where Nagoya's Chubu belt feeds regional assembly. Distribution runs through São Paulo state's industrial corridor clusters anchoring Mercosur aftermarket reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in direct-to-garage digital procurement, as Indonesian and Vietnamese repair shops disintermediate traditional wholesale layers and create niche entry points for specialized kit suppliers.
For Market Incumbents: Pre-empt electrification substitution by anching heavy-duty kit portfolios in Brazil's expanding commercial fleet parc under CONTRAN mandate pressure. Deepen backward integration into aluminum stamping capacity to capture EU Green Deal-driven specification shifts. Lock long-term supply contracts with Thai forging facilities to neutralize commodity volatility exposure.
For New Entrants and Emerging Players: Direct-to-garage e-commerce platforms in Indonesia and Vietnam represent the most penetrable entry point for standard kit distribution. Performance enthusiast segments in Germany and Japan offer premium positioning through adjustable ratio specialization. Anchor go-to-market strategy on specialized technical installation content bypassing incumbent distributor relationships.
For Investors and Strategic Acquirers: ANVISA commercial vehicle durability requirement tightening reshapes the acquisition landscape toward certified-component manufacturers with Brazilian regulatory track records. Long-term viability frames around electrification-resistant commercial segments with extended service interval specifications. Target acquisition archetype: mid-scale fabricators with captive OEM relationships and Southeast Asian forging partnerships. Watch fleet electrification timeline acceleration as inflection indicator forcing portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive supply of pivot bushings neutralizes Thai-Vietnamese logistics disruption vulnerability for tier-one contracts. |
| Direct-to-Garage Digital Platform Launch | Bypassing São Paulo wholesale layers captures margin compression from Indonesian repair shop procurement shifts. |
| CONTRAN Certification Investment | Heavy-duty kit approval unlocks Brazil logistics fleet modernization spend concentrated in industrial corridor. |
| Hydraulic Actuation Technology Licensing | METI-guided Japanese platform penetration reduces mechanical wear claims in high-mileage applications. |
| Aluminum Stamping Capacity Expansion | EU Green Deal mass reduction mandates drive European OEM specification migration from steel load-bearing structures. |
Research Methodology
Operator-level perspectives from OEM platform engineers, aftermarket distributor procurement heads, fleet maintenance directors, and independent garage owners anchored the qualitative base. Secondary validation drew from vehicle production databases, IHS Markit registration data, ANVISA compliance filings, and CONTRAN safety mandate documentation. Bottom-up kit volume estimates triangulated with top-down automotive production forecasts across the analysis window.
Scenario-bracketing framed projections across electrification penetration rates and commercial fleet replacement cycles. Segmentation dimensions modeled encompass vehicle class, kit category tier, material specification, and end-user channel. CAGRs derived from regression against historical replacement cycle data and OEM content-per-vehicle trajectories. Industry-specific inputs incorporated EPA emissions compliance trajectory and EU Green Deal carbon benchmark tightening schedules.
Macroeconomic conditions sit as an overlay; deviation in steel commodity pricing and Brazilian real exchange rates would shift the trajectory. Forecasts reflect documented assumptions on fleet electrification timing and regulatory enforcement intensity. Material shifts in battery-electric commercial vehicle adoption pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Bumper Beam Market