
 In Pipe Hydro Systems Market | 2026-2036
In Pipe Hydro Systems Market Size, Share, and Industry Trends Forecast 2026-2036
In Pipe Hydro Systems Market Intelligence
The integration of real-time monitoring sensors and predictive analytics into turbine control systems is narrowing the gap between energy generation potential and actual output. Lucid Energy Inc. leverages this data-centric approach to optimize energy capture in large municipal water conduits. Rentricity Inc. competes by offering modular systems tailored for smaller-diameter pipes within industrial and commercial facilities. HS Dynamic Energy specializes in customized turbine solutions for specific flow rate conditions.
In pipe hydro systems are a class of micro-hydropower technology designed to generate electricity from excess pressure and flow within water distribution networks. These systems typically replace or augment pressure-reducing valves, converting previously dissipated energy into usable power, often with outputs ranging from 5 kW to 100 kW. Turbine-based systems represent the core of the market, while integrated sensors are the fastest-growing product type. Within applications, water supply and treatment projects for municipal end-users constitute the largest revenue stream.
Regulations such as the US EPA's guidelines on water infrastructure efficiency and the EU's Water Framework Directive create market incentives by promoting energy recovery. In India, state-level Renewable Purchase Obligations allow water utilities to meet clean energy targets by deploying these systems. The key decision for system integrators is whether to standardize product offerings for broad applicability or to pursue high-margin customization for complex industrial sites.
Market Dynamics
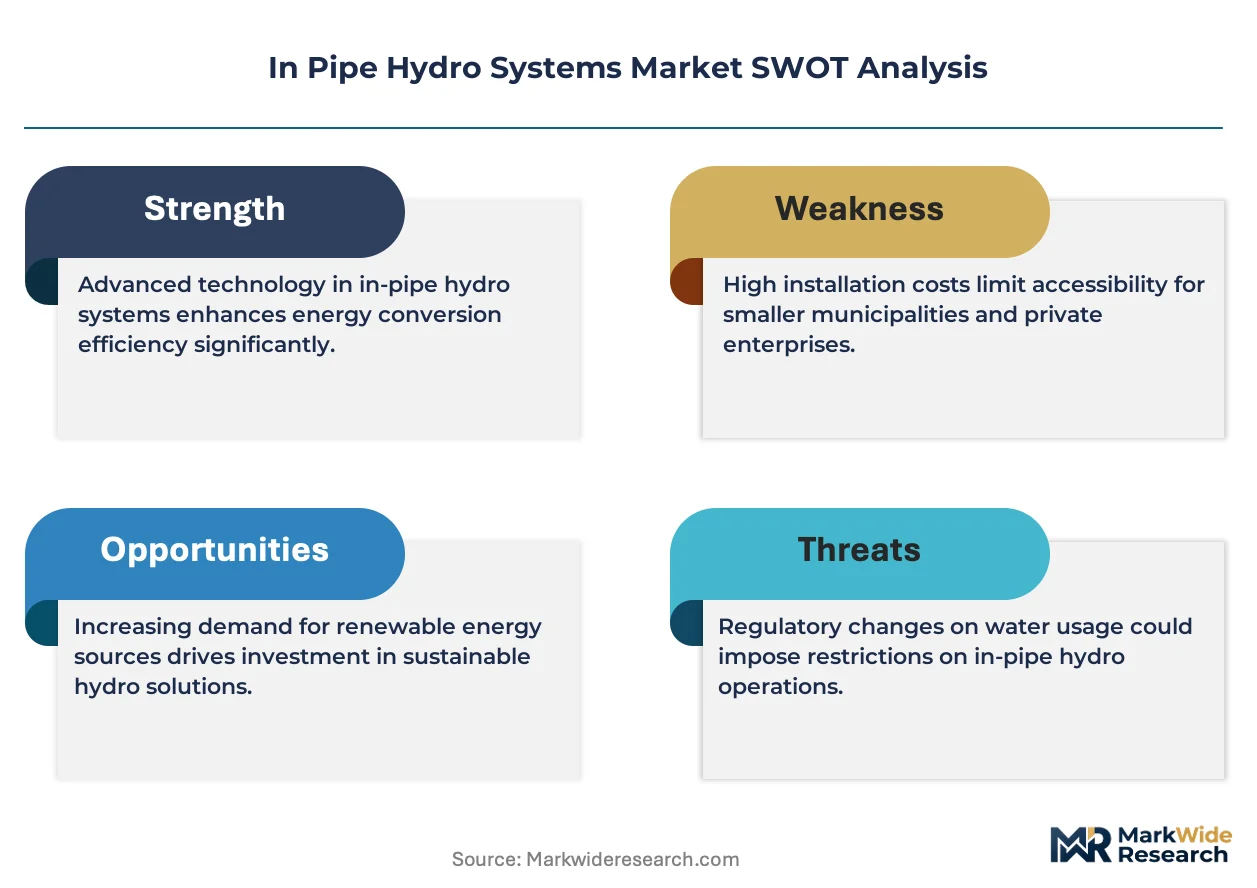
The central dynamic shaping the in-pipe hydro systems market is the push by municipal and agricultural water managers to monetize energy recovery. This effort is driven by regulatory mandates for efficiency, transforming what was once a cost center for pressure management into a revenue-generating asset.
Growth Catalysts
- Regulatory Frameworks:The EU Green Deal and similar policies incentivize energy recovery within water infrastructure, compelling utilities to evaluate and adopt technologies that capture previously wasted energy from pressure reduction processes.
- Agricultural Modernization:Large-scale irrigation projects, particularly in water-intensive agricultural economies like India and Brazil, are integrating in-pipe hydro to reduce their substantial operational energy costs and improve water management efficiency.
- Technology Maturation:Advances in turbine design and the integration of smart sensors are improving the efficiency and reliability of micro-hydropower systems, making them a more viable investment for a wider range of flow conditions.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment required for turbine purchase, system integration, and civil works remains a primary barrier for many budget-constrained municipal water authorities and industrial clients.
- Flow Rate Variability:Inconsistent water flow and pressure within many existing distribution networks can lead to suboptimal turbine performance and unpredictable power output, complicating the financial case for deployment.
- Incumbent Technology Preference:Many facility managers and civil engineers continue to specify traditional, non-generating pressure-reducing valves (PRVs) due to their lower cost, simplicity, and long-established reliability track record.
Strategic Opportunities
- System Retrofitting in Industrial Facilities:A significant opportunity exists in retrofitting systems into private-sector infrastructure, such as large industrial cooling loops, commercial HVAC systems, and manufacturing plant water circuits, which offer stable flow rates.
- Hybrid Energy Systems:Pairing in-pipe hydro with other distributed energy resources, like solar PV or battery storage, creates resilient power solutions for remote pumping stations or off-grid water treatment facilities.
- Emerging Economies' Infrastructure Buildout:New water infrastructure projects in rapidly urbanizing regions of Southeast Asia and Africa present a clean-slate opportunity to design-in energy recovery systems from the outset, bypassing legacy constraints.
Industry Challenges
- Legacy System Integration:Interfacing modern, data-driven hydro systems with aging municipal water pipes and legacy SCADA control platforms presents significant technical and operational hurdles, often requiring custom engineering solutions.
- Specialized Skills Shortage:The market faces a deficit of technicians and engineers who possess the combined expertise in fluid dynamics, power electronics, and data analytics required to properly install, commission, and optimize these systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Pipe Hydro Systems Market |
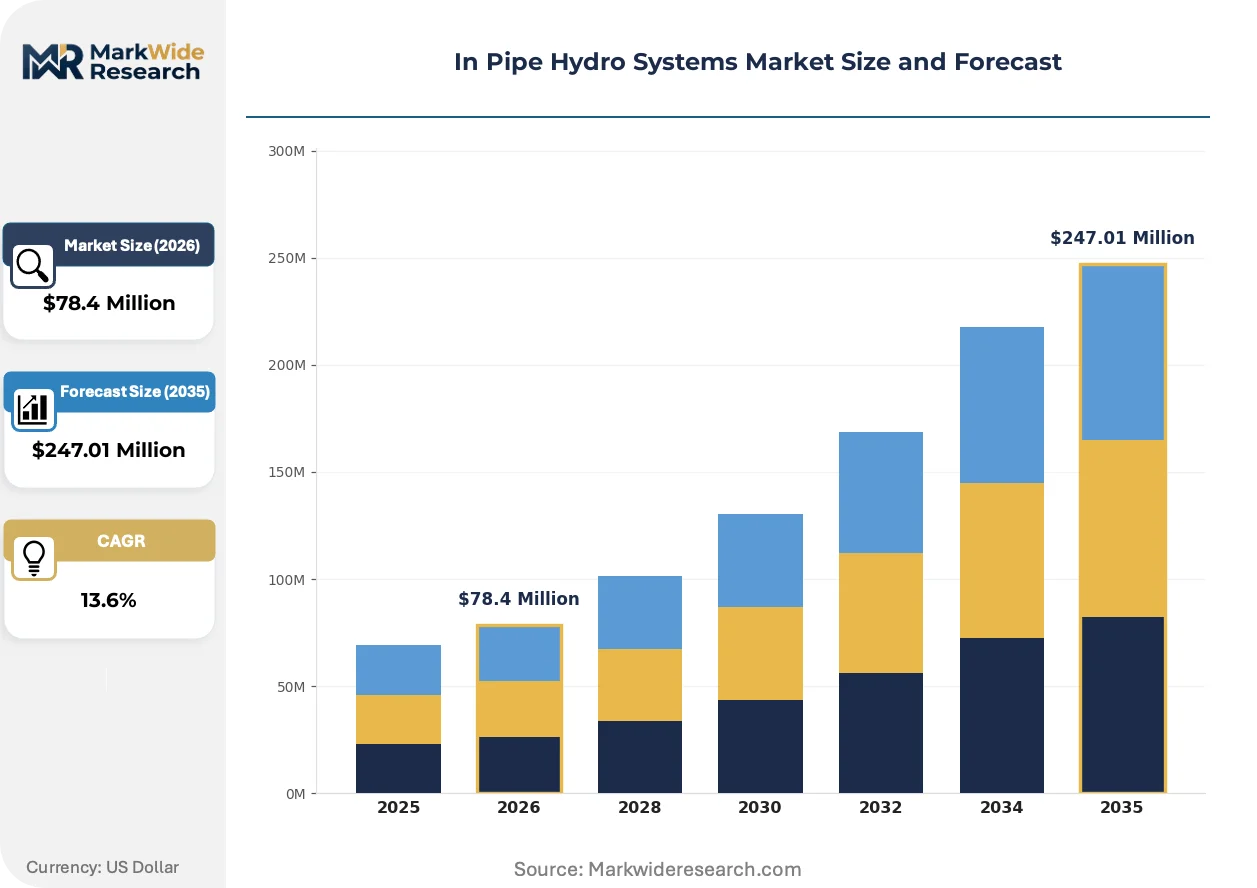
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $247.01 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pump, Turbine, Valve, Sensor Application: Water Treatment, Irrigation, Drainage, Water Supply Installation Type: Above Ground, Below Ground, Embedded, Portable End User: Municipal, Industrial, Agricultural, Commercial |
| Companies Covered | Lucid Energy Inc., Rentricity Inc., Leviathan Energy, Xinda Green Energy Co. Limited, Natel Energy, HydroFlex, Verdant Power, Tecnoturbine, HS Dynamic Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Pipe Hydro Systems Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of modular hardware design and data-driven performance optimization. This combination allows for more precise energy capture across a wider spectrum of pipe diameters and flow conditions, expanding the addressable market beyond large municipal conduits.
Real-time monitoring sensors embedded within turbine assemblies provide continuous data streams on flow, pressure, and operational health. Municipal water authorities are the primary adopters of these sensor-rich systems to enable predictive maintenance and verify performance against contractual benchmarks. This data-centric approach is collapsing the information gap between theoretical energy potential and actual kilowatt-hours generated, thereby improving project bankability.
In India, state-level Renewable Purchase Obligations (RPOs) are altering the economic calculus for water utilities. These regulations compel electricity distributors to source a portion of their power from clean energy, creating a ready market for the electricity generated by in-pipe hydro systems. Water treatment and supply facilities in states with aggressive targets are most affected, viewing these systems as a new source of operational revenue.
A notable behavioral change involves a pivot from capital expenditure to performance-based contracting models. Instead of purchasing equipment outright, some end-users partner with specialized firms that finance, install, and operate the systems in exchange for a share of the energy savings. This model is gaining traction in the United States and parts of Europe where municipal budgets face constraints but efficiency mandates are strict.
In Pipe Hydro Systems Market Segmentation
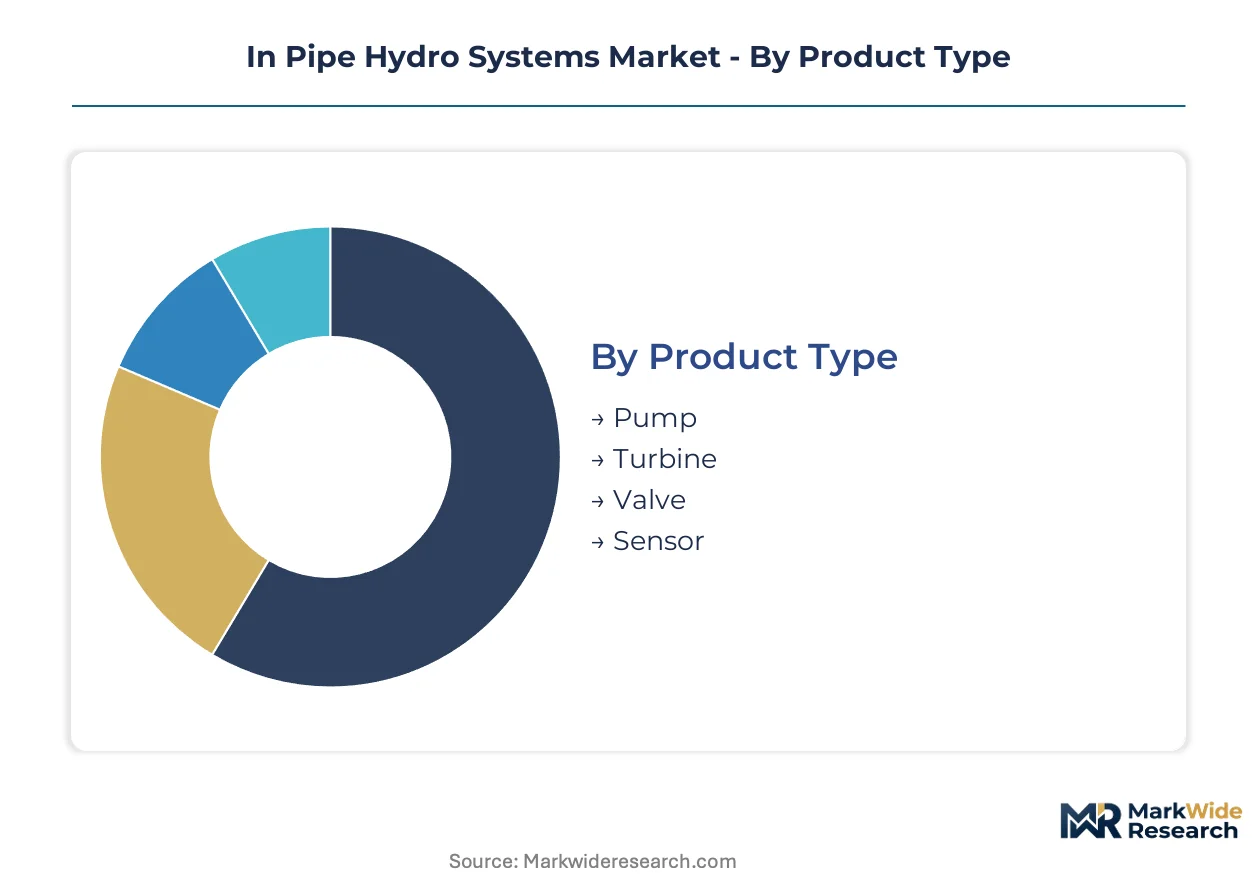
Market segmentation provides a structured view of the in-pipe hydro systems landscape, illustrating how diverse product types, applications, installation methods, and end-users contribute to the overall market dynamics. Understanding these distinct segments helps stakeholders identify specific growth opportunities and tailor solutions for varying operational requirements across global water infrastructure.
Product Type:
The product type segmentation delineates the functional components employed across the energy recovery spectrum within water networks.
- Turbine:These systems convert kinetic energy from flowing water into electricity through rotational mechanical action, forming the core of in-pipe hydro generation. Demand concentrates within large municipal water conduits in regions like the United States, driven by the imperative to monetize pressure management.
- Sensor:Integrated real-time monitoring devices collect continuous data on flow, pressure, and operational parameters, enabling predictive analytics and performance optimization. Municipal water authorities in Europe are primary adopters, seeking to verify system performance against contractual benchmarks.
- Pump:Hydro systems can utilize reverse-running pumps as turbines for energy generation in specific low-head applications within distribution networks.
- Valve:Pressure-reducing valves dissipate excess energy, but some advanced designs integrate micro-hydro elements for small-scale power recovery.
Established volume favors turbine-based systems; emerging adoption favors integrated sensor technologies.
Application:
Application segmentation highlights the diverse operational contexts where in-pipe hydro systems deliver value and reduce energy consumption.
- Water Supply:These projects involve generating electricity from pressure mains and distribution networks that deliver potable water to end-users. Municipal end-users in Germany constitute the largest revenue stream, driven by infrastructure efficiency mandates.
- Irrigation:Systems deployed in large-scale agricultural water delivery channels convert excess pressure into power for pumps or other farm operations. Countries like India and Brazil are integrating these systems to reduce substantial operational energy costs.
- Water Treatment:Hydro systems recover energy from water flows within treatment plants, reducing operational energy consumption for various processes.
- Drainage:Energy recovery from gravity-fed drainage systems or wastewater networks represents a niche application where consistent flow conditions exist.
Water supply projects drive the largest revenue, while agricultural irrigation systems are expanding most quickly.
Installation Type:
Installation type segmentation reflects the varied deployment strategies for integrating hydro systems into existing or new infrastructure.
- Below Ground:These installations integrate hydro turbines directly into buried pipelines, often replacing or augmenting existing pressure-reducing valves. Municipal water utilities in France frequently choose this method for discreet energy recovery within urban networks.
- Above Ground:Systems are housed in accessible structures or pipe sections, simplifying maintenance and monitoring for operators. Industrial facilities in Japan favor above-ground setups for cooling loops and process water, offering stable flow rates.
- Embedded:Hydro components are designed into new pipeline construction or integrated within existing infrastructure during major upgrade projects.
- Portable:Mobile or temporary units provide flexible energy generation for remote sites or emergency power in various water transfer scenarios.
Below ground installations offer discreet integration, while above ground systems provide greater accessibility and cost efficiency for maintenance.
End User:
End-user segmentation highlights the diverse stakeholders driving demand and leveraging in-pipe hydro systems for energy recovery.
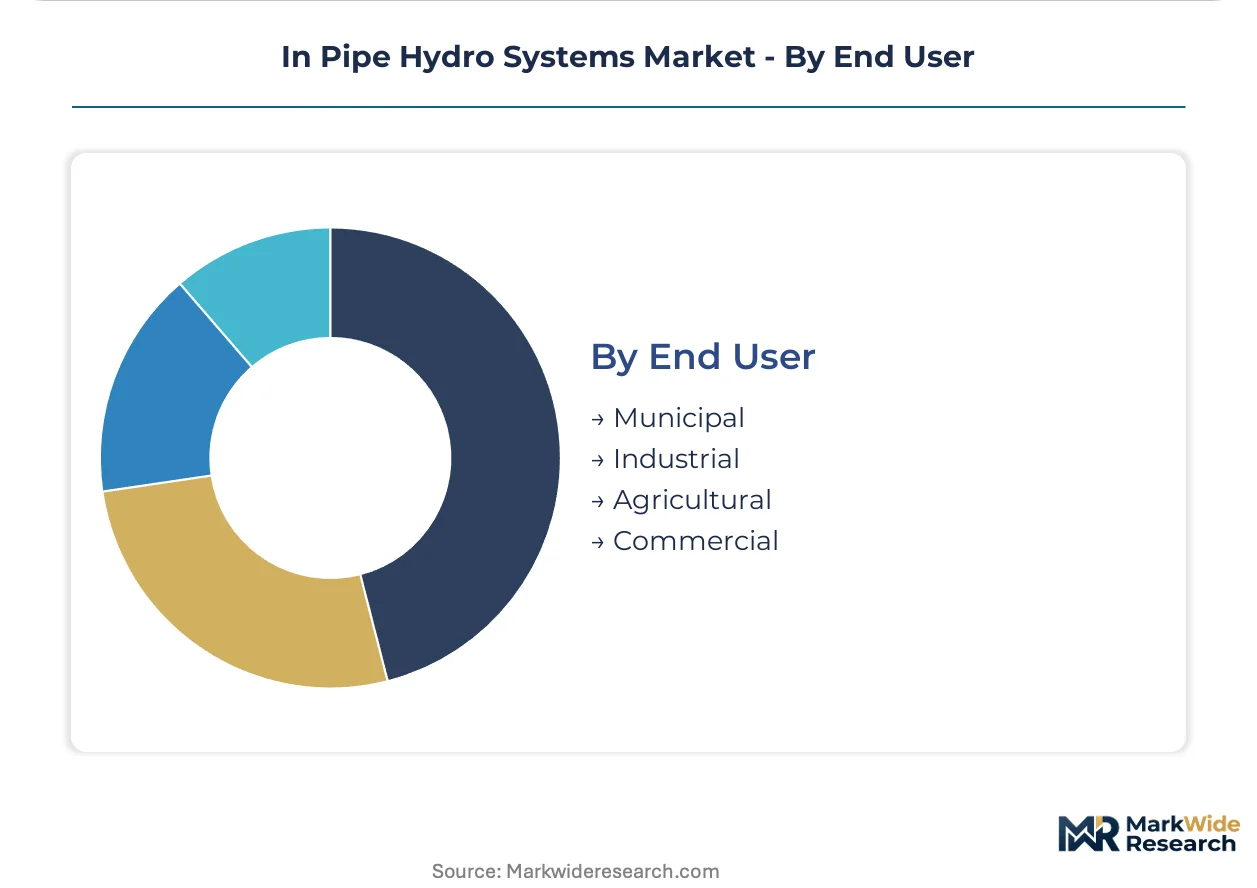
- Municipal:City water departments and public utilities deploy these systems within their vast water distribution and treatment networks. Regulatory mandates from the US EPA compel these entities to prioritize energy recovery and efficiency.
- Agricultural:Large-scale farms and irrigation districts integrate hydro systems to offset electricity costs for pumping and improve water management. Brazil's agricultural sector represents a significant growth area due to extensive irrigation needs and energy demands.
- Industrial:Manufacturing plants and processing facilities utilize hydro systems within their internal water circuits for process optimization and energy savings.
- Commercial:Smaller-scale applications in large commercial buildings, campuses, or data centers recover energy from water loops and HVAC systems.
Municipal end-users represent the largest current market, with agricultural applications driving significant market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering firms export advanced in-pipe hydro systems to municipal water authorities across Europe, enhancing water infrastructure efficiency. This technology converts previously wasted pressure into usable power. The expanding global market seeks energy recovery solutions for water networks.
United States
Demand for in-pipe hydro systems in the United States stems from the need to upgrade aging water infrastructure and reduce operational costs. The US EPA's guidelines on water infrastructure efficiency provide strong incentives for utilities to adopt energy recovery technologies. Water districts in California are actively exploring these systems to manage energy consumption in their extensive water delivery networks.
Germany
Germany's market for in-pipe hydro systems is driven by stringent environmental regulations and a focus on renewable energy integration. The EU Green Deal incentivizes energy recovery within water infrastructure, compelling German utilities to evaluate micro-hydropower solutions. Municipal water authorities in cities like Berlin are implementing these systems to achieve energy independence and reduce their carbon footprint.
India
India's agricultural sector presents a significant demand driver for in-pipe hydro systems, particularly in large-scale irrigation projects. State-level Renewable Purchase Obligations (RPOs) allow water utilities to meet clean energy targets by deploying these systems. Regions such as Maharashtra are seeing increased adoption to offset substantial energy costs associated with water pumping.
Brazil
Brazil's extensive agricultural economy and vast irrigation needs create substantial opportunities for in-pipe hydro systems to reduce energy expenditure. The country's national water resource policies encourage efficient water management and energy recovery in agricultural settings. The agricultural sector around São Paulo is actively investing in these technologies to improve economic viability and sustainability.
France
French municipal water utilities prioritize discreet and efficient energy recovery solutions within their urban networks. The EU's Water Framework Directive promotes sustainable water management, which includes energy efficiency measures. Cities like Paris are increasingly integrating below-ground in-pipe hydro installations to generate power without impacting urban aesthetics.
In Pipe Hydro Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the in-pipe hydro systems sector. The market exhibits a tiered structure, with established industrial giants alongside agile technology developers. Strategic archetypes include integrated solution providers offering end-to-end services, niche turbine manufacturers focusing on specific flow conditions, and data analytics specialists optimizing system performance. Companies are pursuing geographic expansion and strategic partnerships to broaden their market reach and integrate complementary technologies.
Within the integrated solutions segment, Lucid Energy Inc. exemplifies a data-centric approach, optimizing energy capture in large municipal water conduits through advanced monitoring. Rentricity Inc. occupies a position among modular system providers, tailoring its offerings for smaller-diameter pipes within industrial and commercial facilities. HS Dynamic Energy represents specialists focusing on customized turbine solutions, addressing specific flow rate conditions and unique project requirements across various applications. These players collectively demonstrate the market's differentiation across scale, customization, and technological integration.
| Leading Market Players |
|---|
| Lucid Energy Inc. |
| Rentricity Inc. |
| Leviathan Energy |
| Xinda Green Energy Co. Limited |
| Natel Energy |
| HydroFlex |
| Verdant Power |
| Tecnoturbine |
| HS Dynamic Energy |
| Others |
Cost & Logistics Intelligence
German engineering firms' specialized production capacity for in-pipe hydro systems directly influences pricing power across Europe. This concentration affects the cost structure for municipal water utilities seeking advanced energy recovery solutions.
Pricing Analysis
The pricing gap between established turbine-based systems and next-generation sensor-integrated solutions influences market dynamics. Project-based pricing dominates, reflecting the significant system integration and civil works required for deployment. Customization level for specific flow conditions and comprehensive after-sales service bundles drive price differentiation. Pricing softness stems from the continued preference for lower-cost, non-generating pressure-reducing valves, making budget-constrained municipal end-users highly price-sensitive.
Supply Chain Analysis
Export control regimes, particularly those governing high-precision manufacturing components, could impact the in-pipe hydro systems supply chain. Supply concentrates in Germany for advanced engineering, Japan for industrial components, and East Asia for sensor arrays, drawing from specialized high-precision turbine components and power electronics. Single-source vulnerability for these specialized inputs represents a structural supply chain risk. Distribution typically occurs through direct sales channels to municipal utilities and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-pipe hydro systems market is experiencing a cyclical recovery, driven by renewed global investments in water infrastructure upgrades. This trend creates opportunities for strategic positioning across various stakeholder groups.
For Market Incumbents: Entrench core market positions by deepening integration capabilities for real-time monitoring sensors and predictive analytics. Acquire smaller technology firms specializing in data optimization to counter agile modular system providers. Expand geographic reach into underserved municipal markets in Southeast Asia, leveraging established project management expertise. Invest in R&D for advanced turbine designs to maintain efficiency leadership against competitor offerings.
For New Entrants and Emerging Players: Underpenetration in rapidly urbanizing regions of Southeast Asia offers significant market entry points for in-pipe hydro systems. Target industrial facilities, such as cooling loops and HVAC systems, which provide predictable flow rates and clear energy savings. Offer performance-based contracting models to reduce upfront capital outlay for budget-sensitive clients. Focus on modular, easily deployable solutions tailored for diverse pipe diameters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized firms integrating advanced sensor technology and predictive analytics into hydro systems. Long-term viability is strong, supported by persistent regulatory mandates for water infrastructure efficiency and energy recovery. Target acquisition profiles include agile modular system providers like Rentricity Inc. or data analytics specialists optimizing energy capture. The signal to watch is the accelerated adoption of performance-based contracting models by municipal utilities, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion into India and Brazil | Captures demand from large-scale agricultural irrigation projects seeking energy cost reduction. |
| Offering Performance-Based Contracting Models | Lowers upfront financial barriers for municipal water authorities and industrial clients. |
| Increased Investment in Sensor Integration R&D | Optimizes energy capture and enables predictive maintenance for enhanced system reliability. |
| Development of Modular System Solutions | Addresses smaller diameter pipes in industrial and commercial facilities for broader applicability. |
| Integration with Hybrid Energy Systems | Enhances power resilience for remote pumping stations and off-grid water treatment facilities. |
Research Approach
Desk research of regulatory filings, industry reports, and company financial statements preceded structured interviews with water utility managers, civil engineers, turbine manufacturers, and system integrators. This approach combined primary insights with secondary validation, ensuring data accuracy and market relevance. Bottom-up data aggregation and top-down market sizing provided robust triangulation of market estimates. Our methodology integrated qualitative perspectives with quantitative analysis.
Assumptions regarding global water infrastructure spending and renewable energy policy evolution were held fixed across the analysis window. The analytical framework modeled market dynamics across product type, application, installation type, end-user, and regional policy environment. Compound Annual Growth Rates were derived from historical growth trends and projected demand forecasts. Key inputs included water infrastructure investment levels and regional renewable energy mandates.
Macroeconomic conditions sit as an overlay; deviation in global interest rates or energy prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory incentives and technological advancements. Material shifts in water infrastructure funding or policy direction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market