
 Europe Positive Displacement Pumps Market | 2026-2036
Europe Positive Displacement Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Positive Displacement Pumps Market Intelligence
A widening capital-intensity gap between integrated and modular producers is rotating competitive advantage toward firms with captive foundry and precision-machining capabilities. NETZSCH Pumps & Systems leverages its in-house elastomer compounding to dominate progressive cavity pump supply for viscous fluids. Sulzer Ltd anchors its position through deep vertical integration in Switzerland and Germany, sustaining margin control across the value chain. KSB SE & Co KGaA competes on scale, operating one of Europe's largest dedicated pump test facilities for validation-intensive industries.
Positive displacement pumps transfer fixed fluid volumes per cycle through mechanical displacement, achieving suction pressures from near-vacuum to thousands of bar depending on rotor geometry and sealing configuration; their primary purpose is metering, shearsensitive handling, and high-viscosity transfer across process industries. Gear pumps lead the product type category in installed base across European lubrication systems, though diaphragm pumps capture faster growth in chemical processing where zero-leakage compliance commands price premiums. Within end user segments, food and beverage applications sit at the mature margin pool, while water treatment infrastructure renewal in France and Italy drives volume expansion for electric-drive screw pumps.
EMA's machinery safety directives, REACH substance restrictions, and the EU Green Deal's industrial emissions benchmarks collectively shape pump material selection, seal chemistry, and energy efficiency certification across the continent. CE marking requirements under the Machinery Directive enforce documented pressure containment validation, creating compliance barriers for non-European suppliers. Stakeholders must monitor how the F-Gas Regulation's expanding scope affects refrigerant pump architectures in HVAC applications and whether national transpositions of the Energy Efficiency Directive accelerate premium-tier electric motor retrofits.
Market Dynamics
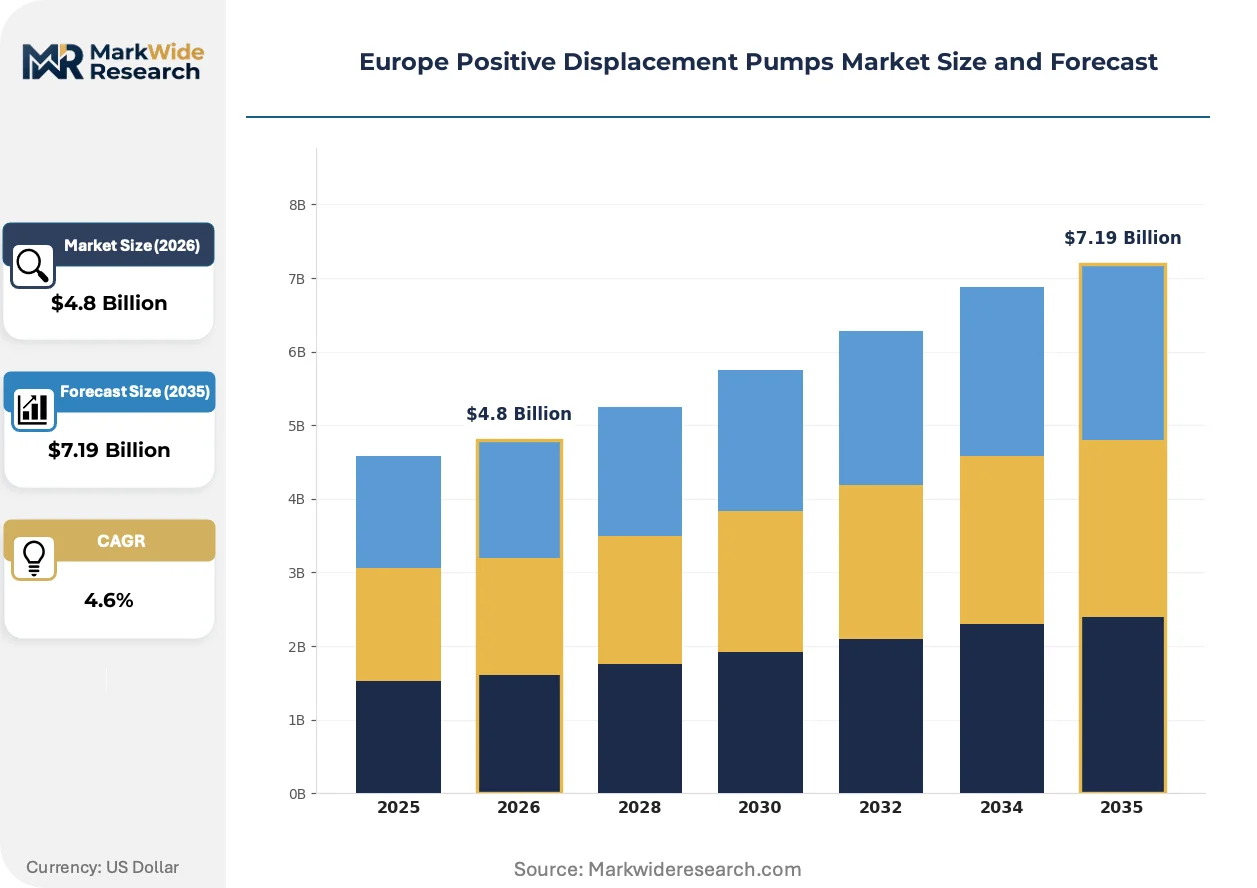
REACH substance restrictions and the EU Green Deal's effluent mandates are forcing simultaneous material redesign and energy efficiency upgrades across European pump manufacturing, compressing product development cycles while opening premium pricing tiers for compliant architectures.
Growth Catalysts
- Water treatment infrastructure renewal:France and Italy are accelerating electric-drive screw pump deployment to meet EU Green Deal industrial emissions benchmarks. Municipal utilities anchor volume procurement.
- REACH compliance deadlines:Seal-less pump architectures gain preference in chemical processing clusters across Germany's industrial corridor. Zero-leakage specifications command technical validation premiums.
- Elastomer compounding advances:In-house material science capabilities enable progressive cavity pumps to handle increasingly viscous process fluids. Food and beverage pasteurization lines drive specification upgrades.
Market Restraints
- Specialized alloy input volatility:Duplex stainless steel and nickel-based superalloy prices fluctuate with energy-intensive European smelter output. Foundry capacity constraints in Central Europe amplify cost pass-through friction.
- CE marking documentation burden:Machinery Directive pressure containment validation requires third-party notified body involvement. Non-European suppliers face extended market entry timelines.
- Centrifugal pump substitution in low-viscosity applications:Standard water handling and thin-liquid transfer increasingly default to lower-cost centrifugal alternatives. Positive displacement architectures retreat to specialized duty cycles.
Strategic Opportunities
- Hydrogen economy fluid handling:Electrolyzer and fuel cell manufacturing in the Netherlands and Belgium creates demand for precision metering of corrosive electrolytes. Diaphragm pump specifications are evolving for hydrogen-specific chemistries.
- CSRD-aligned predictive maintenance:Sensor-integrated pump systems enable scope 3 emissions tracking for corporate sustainability reporting. Industrial end-users in Germany and France prioritize connected architectures.
- Pharmaceutical aseptic processing:Single-use pump technologies reduce cross-contamination risk in biologics manufacturing. Swiss and German pharmaceutical clusters drive validation-intensive procurement.
Industry Challenges
- Precision machining skill scarcity:Tight-tolerance rotor and stator manufacturing requires specialized tool-and-die expertise. German and Swiss technical training pipelines struggle to replenish retiring cohorts.
- F-Gas Regulation scope uncertainty:HVAC refrigerant pump architectures face redesign pressure as the regulation expands. Manufacturers delay capex commitments pending final delegated act clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Positive Displacement Pumps Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Diaphragm Pumps, Piston Pumps, Screw Pumps End User: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage Technology: Hydraulic, Pneumatic, Electric, Manual Application: HVAC, Lubrication System, Fuel Delivery, Waste Management |
| Companies Covered | Flowserve Corporation, NETZSCH Pumps & Systems, Sulzer Ltd, Xylem Inc, Fristam Pumps KG (GmbH & Co.), KSB SE & Co KGaA, Alfa Laval AB, SPX FLOW, Ingersoll Rand Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Positive Displacement Pumps Market Strategic Shifts & Innovations
Digitalization and material science advances are restructuring how European pump manufacturers capture value, with software-enabled service models and advanced elastomer formulations displacing traditional hardware-centric competition.
Magnetically driven seal-less architectures are bifurcating the chemical processing segment. BASF and Bayer specification engineers now mandate zero-emission pump designs for new plant construction. This technology compression is eliminating mechanical seal suppliers from mid-tier procurement while elevating integrated system vendors.
The F-Gas Regulation's expanding refrigerant restrictions are forcing HVAC pump redesigns across European climate systems. Manufacturers must validate new elastomer compatibilities with low-GWP alternatives. Heat pump OEMs in Germany and Poland are accelerating qualification timelines to maintain product certification.
Industrial buyers are unbundling aftermarket service from initial equipment procurement. Chemical processors in the Rhine-Ruhr region now contract predictive maintenance separately through third-party specialists. This channel fragmentation pressures traditional OEM service revenue models while opening independent service provider entry points.
Europe Positive Displacement Pumps Market Segmentation
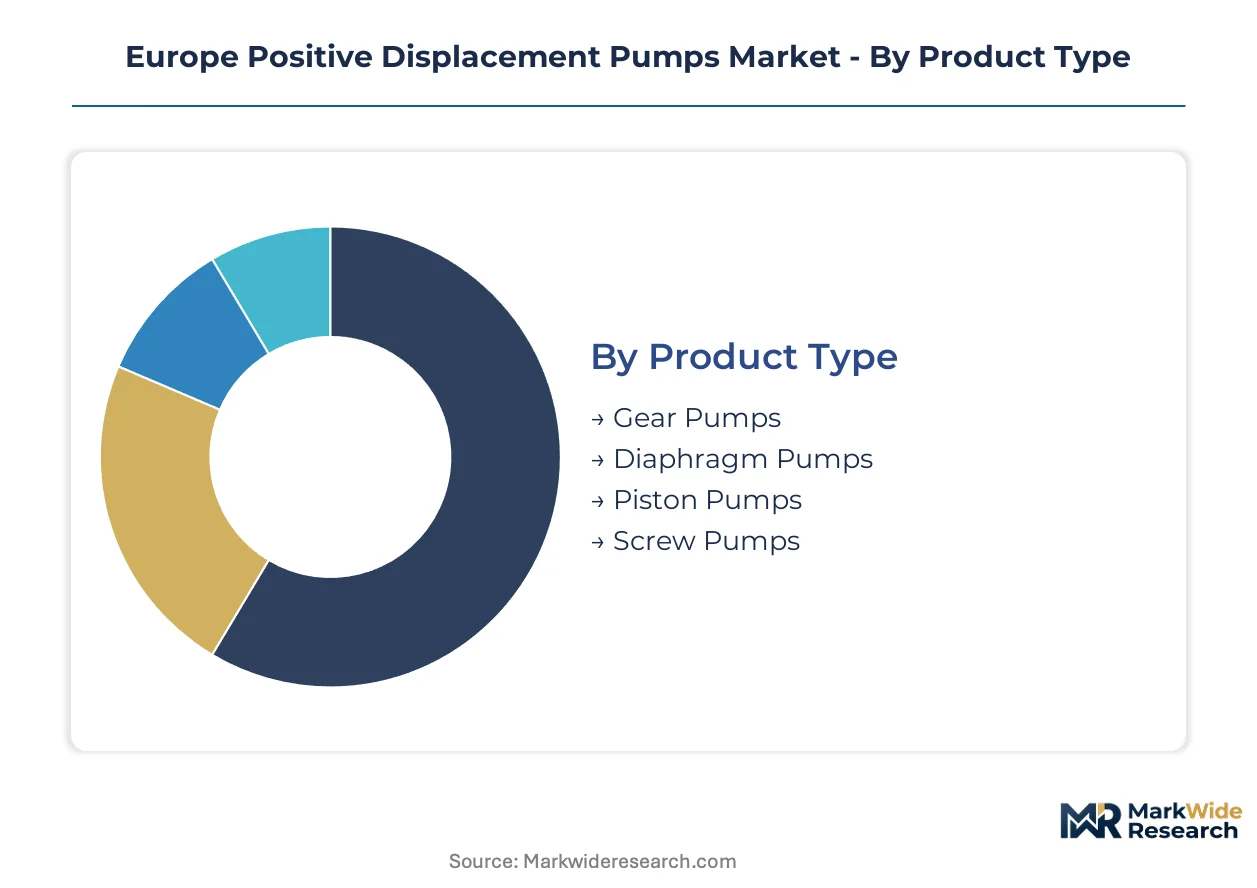
Pump specification varies sharply across European industrial corridors, with REACH compliance and EU Green Deal effluent mandates fragmenting procurement requirements. Segment boundaries increasingly follow regulatory pressure points rather than traditional viscosity-duty classifications.
Product Type:
Margin pools concentrate in seal-less architectures where zero-leakage validation commands technical premiums from chemical processors.
- Gear Pumps:External and internal gear configurations dominate lubrication circuits across German automotive manufacturing. Established installed base in Rhine-Ruhr industrial clusters sustains replacement demand despite centrifugal encroachment in thin-fluid applications.
- Diaphragm Pumps:Air-operated double-diaphragm designs transfer corrosive electrolytes for Netherlands and Belgium hydrogen electrolyzer manufacturing. REACH substance restrictions on mechanical seal materials accelerate specification shifts toward elastomer-diaphragm isolation.
- Piston Pumps:High-pressure triplex configurations meter precise volumes in Italian pharmaceutical aseptic processing lines.
- Screw Pumps:Progressive cavity and twin-screw architectures handle viscous refinery residuals in Polish petrochemical corridors.
Gear pumps hold installed capacity. Diaphragm pumps are rotating up the share rankings.
End User:
Volume procurement concentrates where EU-funded infrastructure renewal intersects with emissions benchmarking deadlines.
- Oil & Gas:North Sea decommissioning and Norwegian continental shelf maintenance sustain demand for high-pressure piston units. Exploration capital discipline compresses greenfield specification opportunities toward brownfield reliability upgrades.
- Water Treatment:French and Italian municipal utilities deploy electric-drive screw pumps for sludge handling and effluent transfer. EU Green Deal industrial emissions benchmarks mandate efficiency upgrades across aging treatment infrastructure.
- Chemical Processing:Germany's industrial corridor anchors seal-less specification leadership for BASF and Bayer plant construction.
- Food & Beverage:Swiss and German pasteurization lines specify hygienic progressive cavity pumps for viscous product transfer.
Water treatment captures volume acceleration. Chemical processing commands margin premiums.
Technology:
Power source selection tracks facility electrification trajectories and compressed air infrastructure maturity across European manufacturing.
- Hydraulic:High-torque radial piston drives anchor mobile machinery applications in German construction equipment. Fluid power density advantages persist where electric motor sizing constraints limit alternatives.
- Pneumatic:Intrinsically safe operation without spark risk sustains specification in French and Belgian chemical handling. Air-operated diaphragm architectures dominate where explosive atmosphere classifications apply.
- Electric:Premium-efficiency motor retrofits accelerate under national Energy Efficiency Directive transpositions.
- Manual:Portable barrel and drum pumps serve maintenance and small-batch transfer in distributed industrial facilities.
Electric drives gain specification share fastest. Pneumatic retains hazardous-duty strongholds.
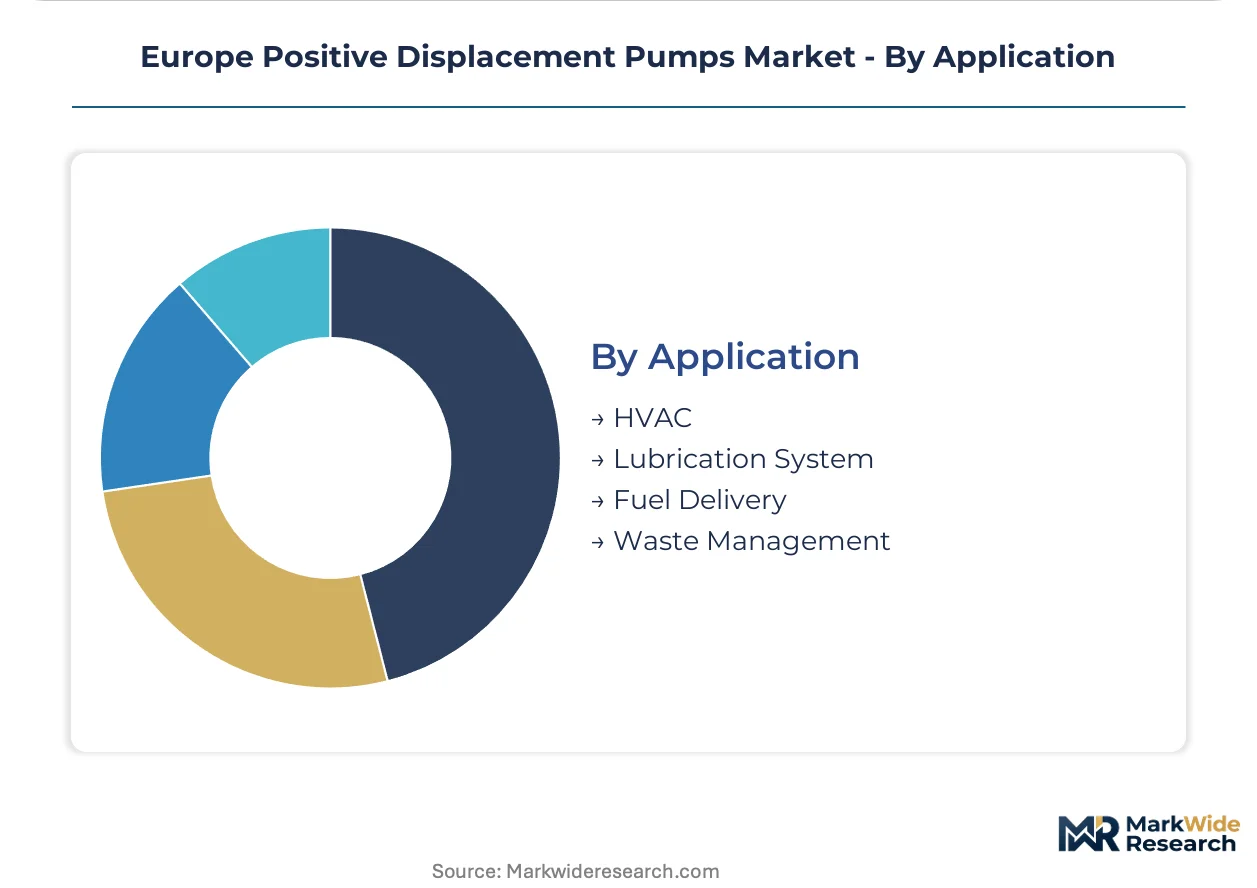
Application:
Climate system refrigerant handling faces architectural disruption from F-Gas Regulation scope expansion.
- HVAC:Heat pump OEMs in Germany and Poland qualify new elastomer compatibilities for low-GWP refrigerant chemistries. Circulating pump specifications must validate performance across expanded operating envelopes.
- Lubrication System:Automotive and aerospace manufacturing in Stuttgart and Toulouse sustain demand for precision gear pump metering. Integrated powertrain testing facilities require contamination-critical fluid delivery.
- Fuel Delivery:Marine and power generation applications in Mediterranean ports specify heavy-fuel oil transfer architectures.
- Waste Management:Sludge and biosolid handling in Benelux anaerobic digestion facilities deploy progressing cavity designs.
Lubrication systems anchor steady-state demand. HVAC faces regulatory-driven specification churn.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pump manufacturers command pricing premiums through REACH-compliant seal-less architectures, while Italian and Polish suppliers compete on cost efficiency in standard gear and screw pump categories. This pricing-power asymmetry concentrates margin capture in the Rhine-Ruhr and southern German industrial corridors.
Germany
Water treatment utilities in North Rhine-Westphalia are expanding diaphragm pump procurement to meet EU Green Deal effluent standards. ECHA substance restrictions under REACH are pushing manufacturers toward seal-less pump architectures. BASF and Bayer specification engineers in Ludwigshafen and Leverkusen now mandate zero-emission pump designs for new plant construction.
France
Municipal utilities in the Île-de-France and Provence-Alpes-Côte d'Azur regions are accelerating electric-drive screw pump deployment for sludge handling. The EU Green Deal's industrial emissions benchmarks mandate efficiency upgrades across aging treatment infrastructure. Chemical processing clusters around Lyon specify air-operated diaphragm pumps where explosive atmosphere classifications apply.
Italy
Pharmaceutical aseptic processing lines in Lombardy and Emilia-Romagna drive validation-intensive procurement of high-pressure piston pumps. National transpositions of the Energy Efficiency Directive accelerate premium-tier electric motor retrofits. Food and beverage pasteurization facilities in Parma specify hygienic progressive cavity pumps for viscous product transfer.
Netherlands
Electrolyzer and fuel cell manufacturing in Rotterdam and Eindhoven creates demand for precision metering of corrosive electrolytes. Diaphragm pump specifications are evolving for hydrogen-specific chemistries under EU Green Deal industrial decarbonization targets. The Port of Rotterdam's hydrogen hub anchors fluid handling infrastructure investment.
Poland
Petrochemical corridors in Pomerania and Silesia deploy progressive cavity and twin-screw architectures for viscous refinery residuals. Heat pump OEMs in Warsaw accelerate qualification timelines for new elastomer compatibilities with low-GWP refrigerants under the F-Gas Regulation. Foundry capacity constraints amplify cost pass-through friction for specialized alloy inputs.
Europe Positive Displacement Pumps Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European positive displacement pumps market. The vendor base concentrates around integrated manufacturers with captive foundry capabilities and precision-machining assets, while modular assemblers compete on delivery speed for standardized configurations. Two strategic archetypes dominate: vertically integrated specialists with in-house elastomer compounding, and scale-driven diversified industrials operating extensive test and validation facilities. Competitive moves center on backward integration into alloy supply chains and geographic expansion through distribution partnerships in hydrogen economy clusters.
Among Germany-based integrated manufacturers, NETZSCH Pumps & Systems and KSB SE & Co KGaA exemplify the technology-leadership archetype through material science capabilities and validation infrastructure. Sulzer Ltd represents the Swiss precision-engineering tradition with deep manufacturing integration across Alpine and German production bases. These three firms anchor the premium tier where REACH compliance and zero-leakage specifications command technical validation premiums from chemical processors and water treatment utilities.
| Leading Market Players |
|---|
| Flowserve Corporation |
| NETZSCH Pumps & Systems |
| Sulzer Ltd |
| Xylem Inc |
| Fristam Pumps KG (GmbH & Co.) |
| KSB SE & Co KGaA |
| Alfa Laval AB |
| SPX FLOW |
| Ingersoll Rand Inc |
| Others |
Cost & Logistics Intelligence
Captive foundry utilization rates above 80 percent in Germany and Switzerland compress cost curves for integrated manufacturers while elevating price floors for modular assemblers dependent on spot-market alloy procurement. Scale concentration in Central European precision-machining corridors bifurcates the vendor base between margin-capturing specialists and price-competitive standard-product suppliers.
Pricing Analysis
Configured-to-order pricing for seal-less diaphragm pumps commands 40-60 percent premiums over catalog gear pump configurations. Contract-based long-term offtake dominates procurement in Germany's chemical processing corridor, where BASF and Bayer specification engineers prioritize REACH-compliant validation over unit cost. Price differentiation hinges on certification grade—CE-marked pressure containment documentation and in-house elastomer compounding capabilities separate premium tiers from standard offerings. Cost compression in economy-tier lubrication pumps intensifies as centrifugal alternatives capture thin-fluid applications, while water treatment utilities in France and Italy exhibit lowest price sensitivity due to EU-funded infrastructure renewal timelines.
Supply Chain Analysis
Strait of Hormuz transit exposure for nickel-bearing superalloy feedstock amplifies input cost volatility for European foundries. Manufacturing concentration centers on Germany, Switzerland, and Italy, with specialized duplex stainless steel sourcing from Finnish and Swedish smelters. Raw material dependencies include nickel-based superalloys, fluoropolymer elastomers, and rare-earth magnetic alloys for seal-less drive architectures. Single-source vulnerability in precision-machining tool supply from German and Swiss specialty manufacturers constrains capacity expansion. Distribution runs through OEM-direct channels for large chemical processors and authorized distributor networks for maintenance-replacement operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European pump manufacturing is consolidating around scarce precision-machining expertise and captive elastomer formulation capabilities, creating defensive moats for integrated players and entry barriers for modular competitors. The capability gap in qualified tool-and-die engineering talent constrains supply elasticity across the Rhine-Ruhr and Alpine industrial corridors.
For Market Incumbents: Secure backward integration into specialty alloy supply chains through long-term offtake agreements with Nordic smelters to buffer against energy-intensive European foundry output volatility. Deepen in-house elastomer compounding capabilities to defend margin position against emerging modular assemblers in Eastern Europe. Prioritize certification investment in CSRD-aligned predictive maintenance architectures to capture service-revenue unbundling trends in German chemical processing clusters. For New Entrants and Emerging Players: Aftermarket service fragmentation in the Rhine-Ruhr region offers white-space penetration where incumbent OEMs retain legacy bundled pricing. Target Netherlands and Belgium hydrogen electrolyzer manufacturing with diaphragm pump configurations engineered for corrosive electrolyte chemistries. Establish third-party predictive maintenance contracts as the primary go-to-market angle, leveraging sensor integration to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated specialists with captive foundry operations and established aftermarket service contracts. Long-term viability over the next decade favors targets with in-house material science capabilities and REACH-compliant product architectures already validated by ECHA substance restrictions. Monitor F-Gas Regulation delegated act clarity as the inflection signal—final scope determinations will trigger HVAC pump redesign capex cycles and consolidate specification authority among elastomer-compounding leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Long-term offtake agreements with Finnish and Swedish smelters stabilize input costs against energy price volatility. |
| CSRD-Aligned Predictive Maintenance Platform | Sensor-integrated architectures enable scope 3 emissions tracking for corporate sustainability reporting compliance. |
| Hydrogen-Specific Diaphragm Qualification | Electrolyzer manufacturing in Rotterdam and Eindhoven demands pumps validated for corrosive electrolyte chemistries. |
| Elastomer Compounding Capacity Expansion | In-house material science capabilities differentiate progressive cavity pump offerings for viscous fluid handling. |
| CE Marking Validation Infrastructure | Documented pressure containment testing creates compliance barriers for non-European suppliers seeking market entry. |
Research Approach
The analysis maps diaphragm, gear, piston, and screw pump sub-sectors, each validated through maintenance directors at chemical processing facilities, plant engineers in water treatment utilities, OEM procurement teams in automotive manufacturing, and aftermarket service heads in industrial distribution. Primary interviews with these stakeholders combined with secondary validation from ECHA substance restriction databases, EU Green Deal implementation tracking, customs and trade data for alloy inputs, and SEC filings from listed pump manufacturers. Bottom-up unit economics and top-down industrial production indices were triangulated to establish market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, end-use industry, power source technology, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, efficiency upgrade mandates, and hydrogen economy infrastructure buildout trajectories. Industry-specific forecast inputs incorporated REACH compliance deadlines and national Energy Efficiency Directive transpositions.
Forecasts assume regulatory continuity in REACH substance restrictions, EU Green Deal emissions benchmarks, and F-Gas Regulation scope definitions; material policy shifts would require re-modeling of material selection and architectural redesign assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market