
 Dosing Pumps Market | 2026-2036
Dosing Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Dosing Pumps Market Analysis
Aftermarket service revenue is narrowing toward predictive maintenance contracts and remote diagnostics platforms. Grundfos Holding A/S leverages its digital service infrastructure to capture recurring revenue from water treatment operators. ProMinent GmbH anchors its position through deep specialization in chemical-resistant polymer engineering for aggressive media. IDEX Corporation extends its footprint via modular pump architectures that reduce field commissioning time for process engineers.
A dosing pump is a positive-displacement device engineered to deliver precise, repeatable volumes of liquid or chemical additives into a process stream, typically achieving accuracy within ±1% of setpoint through controlled stroke length, frequency modulation, or peristaltic tube compression. These systems serve critical functions in water purification, pharmaceutical batching, and industrial chemical processing where deviation from specified injection rates risks product quality, regulatory non-compliance, or equipment damage. Diaphragm pumps command the largest installed base due to their seal-less design and compatibility with corrosive reagents, while peristaltic configurations gain specification in pharmaceutical aseptic transfer where fluid isolation prevents cross-contamination. Digital technology represents the fastest-expanding segment as electromechanical actuators with embedded flow sensors displace pneumatic timing circuits in facilities pursuing Industry 4.0 integration.
EPA discharge standards under the Clean Water Act mandate precise chemical dosing at municipal treatment plants, directly elevating specification requirements for accuracy and traceability. FDA cGMP guidelines for pharmaceutical manufacturing enforce validation protocols that favor pumps with certified calibration records and material compliance documentation. The EU F-Gas Regulation and REACH chemical restrictions further shape material selection and sealing technologies for equipment deployed in European process industries. Stakeholders must evaluate how regulatory convergence on digital traceability and material transparency will reshape supplier qualification criteria and aftermarket service obligations across their installed base.
Market Dynamics
Digital pump architectures are compressing replacement cycles as electromechanical actuators with embedded flow sensors displace pneumatic timing circuits across municipal water treatment and chemical processing facilities. This technology shift elevates specification requirements for accuracy, traceability, and predictive maintenance integration.
Growth Catalysts
- EPA Clean Water Act enforcement:Municipal treatment plants face escalating discharge compliance mandates that require precision chemical dosing with full audit trails, directly elevating demand for digitally traceable pump systems.
- Pharmaceutical aseptic transfer protocols:Peristaltic configurations gain specification in biologics manufacturing where fluid isolation prevents cross-contamination between batches.
- German process engineering clusters:Specification intensity for diaphragm and peristaltic systems concentrates in Baden-Württemberg and Bavaria, where chemical-resistant polymer engineering capabilities anchor supplier qualification criteria.
Market Restraints
- Specialized fluoropolymer supply concentration:PTFE and PFA diaphragm materials rely on a narrow supplier base concentrated in Western Europe and Japan, exposing pump manufacturers to input cost volatility and allocation risk.
- EU F-Gas Regulation material restrictions:Sealing compound formulations face reformulation requirements that extend R&D timelines and certification costs for equipment deployed in European process industries.
- Magnetic drive centrifugal substitutes:Seal-less centrifugal pumps capture share in lower-pressure chemical transfer applications where precision dosing is secondary to volumetric throughput.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO cGMP enforcement and PLI scheme incentives for active pharmaceutical ingredient production create specification demand for validated dosing systems with certified calibration records.
- Electromechanical-predictive analytics convergence:Embedded vibration and flow sensors combined with edge computing enable condition-based maintenance contracts that shift revenue from equipment sales to recurring service platforms.
- Modular field-commissioning architectures:Pre-configured pump skids with standardized interfaces reduce commissioning time for process engineers in brownfield chemical facility upgrades.
Industry Challenges
- Calibration technician scarcity:Precision pump validation requires specialized metrology expertise that outpaces vocational training pipeline output in North American and European industrial regions.
- Legacy DCS integration complexity:Digital pump actuators must interface with decades-old distributed control systems through protocol converters that introduce latency and diagnostic blind spots.
- REACH substance documentation burden:Material compliance certification for wetted components demands extensive supply chain traceability that smaller pump assemblers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dosing Pumps Market |
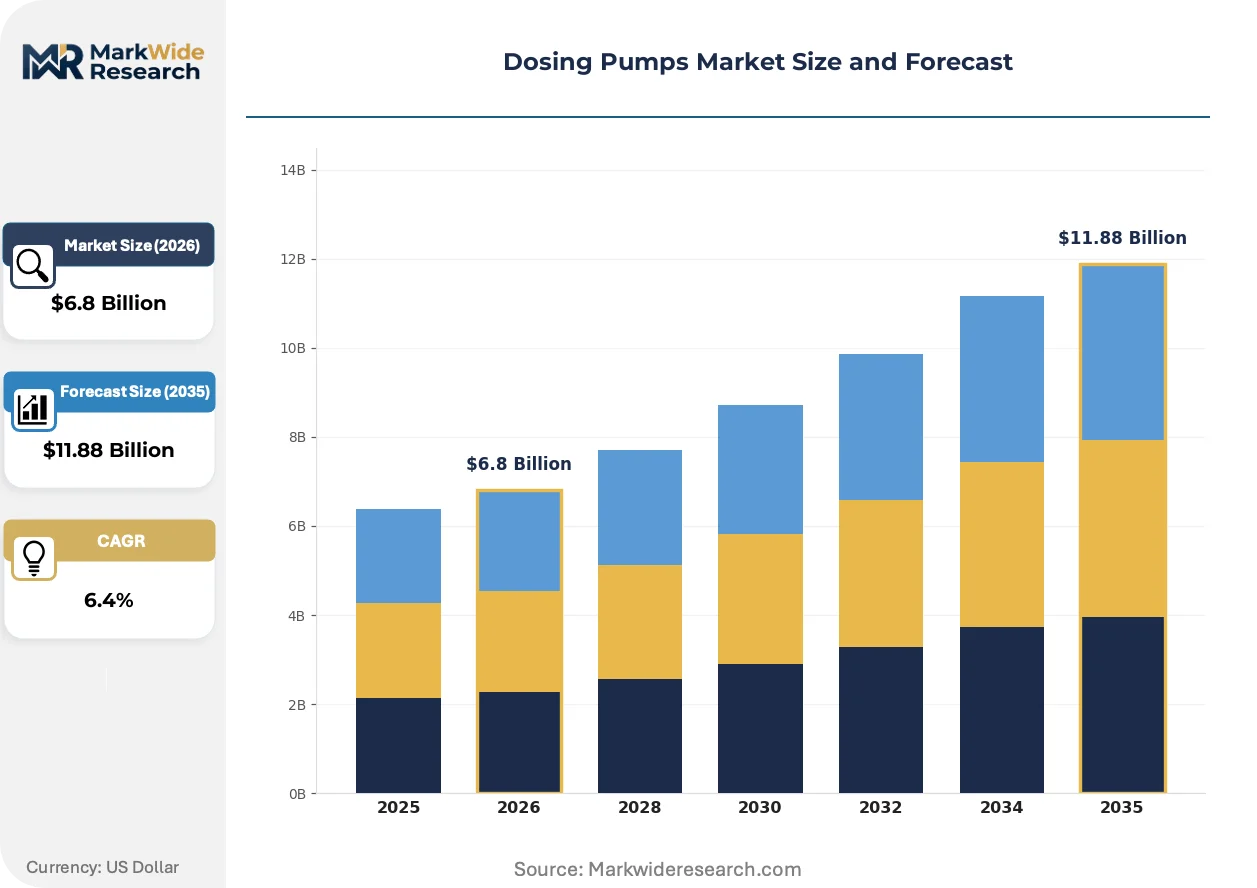
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Peristaltic Pumps, Gear Pumps, Piston Pumps End User: Chemical Manufacturing, Water Treatment, Pharmaceuticals, Food Processing Technology: Electromechanical, Pneumatic, Hydraulic, Digital Application: Metering, Chemical Injection, Fertilizer Application, Disinfection |
| Companies Covered | Grundfos Holding A/S, ProMinent GmbH, IDEX Corporation, SEKO S.p.A., Watson-Marlow Fluid Technology Solutions, LEWA GmbH, SPX Flow, Netzsch Pumpen & Systeme GmbH, Blue-White Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dosing Pumps Market Emerging Trajectories
Electromechanical actuation is displacing pneumatic control across precision fluid handling, compressing the gap between process sensor data and pump response. This convergence of mechanical precision with digital intelligence reshapes competitive differentiation around predictive capability rather than hardware durability alone.
Smart diaphragm pump architectures are hybridizing mechanical stroke control with real-time flow feedback loops. Water treatment operators in Germany and the Netherlands adopt these systems at accelerated pace to meet tightening effluent discharge limits. The technology is hybridizing equipment vendor business models toward subscription-based diagnostic platforms that capture recurring revenue from municipal operators.
EU F-Gas Regulation and REACH chemical restrictions are forcing reformulation of sealing technologies and wetted material specifications. Industrial consequence includes extended supplier qualification timelines and elevated documentation burdens for pump manufacturers serving European process industries. Pharmaceutical and fine chemical segments respond by consolidating supplier panels around vendors with established EU regulatory compliance infrastructure.
Specification authority is migrating from plant maintenance departments to centralized engineering procurement functions with standardized digital requirements. Distributor networks face disintermediation pressure as direct vendor relationships with predictive service platforms bypass traditional channel margins. This shift concentrates most visibly in North American municipal water utilities consolidating vendor panels under enterprise asset management frameworks.
Dosing Pumps Market Segmentation
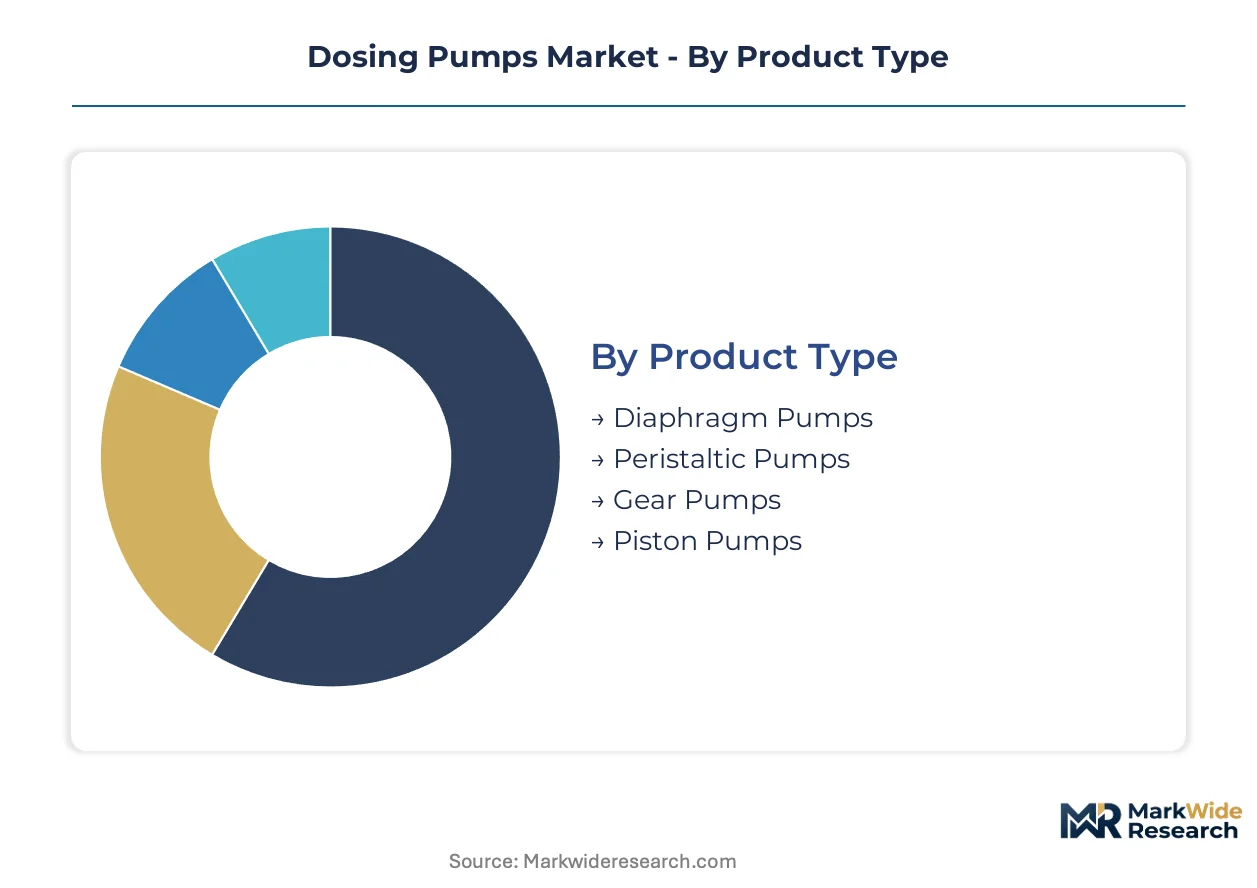
Dosing pump specifications diverge sharply across process environments. Chemical resistance requirements, precision tolerances, and regulatory traceability demands create distinct technical profiles for each application vertical.
Product Type:
End-use environments span aggressive chemical handling to sterile pharmaceutical transfer, demanding fundamentally different sealing and displacement architectures.
- Diaphragm Pumps:Seal-less designs isolate process fluid from mechanical components through elastomer or PTFE diaphragm displacement. Municipal water treatment facilities in Germany specify these systems for sodium hypochlorite and coagulant dosing under tightening EPA discharge mandates.
- Peristaltic Pumps:Fluid compression through reinforced tubing eliminates contamination risk entirely. Biologics manufacturers in Baden-Württemberg deploy peristaltic configurations where batch isolation prevents cross-contamination between high-value pharmaceutical products.
- Gear Pumps:Positive displacement through meshing rotors suits viscous polymer and resin metering in chemical processing.
- Piston Pumps:High-pressure precision for hydraulic fracturing chemical injection and industrial boiler feedwater treatment.
The dominant share belongs to Diaphragm Pumps, while Peristaltic Pumps is closing the gap fastest.
End User:
Procurement authority concentrates in engineering departments with distinct validation protocols and total cost-of-ownership frameworks.
- Chemical Manufacturing:Aggressive media handling drives specification for fluoropolymer-wetted components and redundant sealing architectures. Process engineering clusters in Germany's Rhine-Neckar metropolitan region anchor demand intensity for corrosion-resistant systems.
- Water Treatment:Municipal and industrial effluent compliance elevates digital traceability requirements. Dutch utilities lead adoption of smart diaphragm architectures with embedded flow feedback loops.
- Pharmaceuticals:FDA cGMP and EMA validation protocols enforce certified calibration records and material compliance documentation for all wetted surfaces.
- Food Processing:EHEDG and 3-A sanitary standards govern pump selection for additive dosing in dairy and beverage applications.
Chemical Manufacturing commands the largest installed base, though Pharmaceuticals is expanding most quickly on biologics manufacturing capacity buildouts.
Technology:
Control methodology determines accuracy bandwidth, maintenance intervals, and integration complexity with existing distributed control infrastructure.
- Electromechanical:Stepper motor and servo-driven actuation achieves stroke length precision within ±1% of setpoint. Edge computing integration enables condition-based maintenance contracts that shift vendor revenue toward recurring service platforms.
- Digital:Embedded flow sensors and real-time feedback loops displace pneumatic timing circuits in Industry 4.0 deployments. German municipal operators adopt these systems at accelerated pace to meet tightening effluent discharge limits.
- Pneumatic:Compressed air actuation persists in explosive atmosphere installations where electrical ignition risks dominate.
- Hydraulic:High-force displacement for viscous slurry handling and high-pressure chemical injection applications.
Electromechanical systems anchor current procurement volumes, while Digital architectures are gaining share fastest on predictive maintenance convergence.
Application:
Precision requirements scale from bulk nutrient distribution to trace-level disinfectant residuals, fragmenting specification criteria across use cases.
- Metering:Continuous proportional dosing for polymer make-down and coagulant feed in clarification processes. Accuracy demands concentrate in North American municipal utilities consolidating vendor panels under enterprise asset management frameworks.
- Disinfection:Chlorine, chloramine, and ozone dosing for potable water and wastewater effluent compliance. EPA Clean Water Act enforcement directly elevates specification requirements for full audit trail capabilities.
- Chemical Injection:Downstream oilfield applications and process chemical addition in refining operations.
- Fertilizer Application:Precision agriculture systems for nutrient delivery in controlled-environment horticulture.
Metering applications retain the dominant specification volume, though Disinfection is climbing the fastest on regulatory compliance intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water utilities in the Netherlands demonstrate the lowest price elasticity, absorbing premium electromechanical systems for effluent compliance, while Indian pharmaceutical contract manufacturers exhibit acute cost sensitivity despite CDSCO enforcement tightening.
Germany
Process engineering clusters in Baden-Württemberg and Bavaria drive specification intensity for fluoropolymer-wetted diaphragm systems. The EU F-Gas Regulation and REACH chemical restrictions force extended supplier qualification timelines for sealing compound reformulations. LEWA GmbH anchors manufacturing presence in Leonberg, where chemical-resistant polymer engineering capabilities concentrate.
United States
EPA Clean Water Act enforcement elevates digital traceability requirements across 16,000 municipal treatment facilities. Discharge compliance mandates from the EPA directly accelerate replacement cycles for pneumatic timing circuits. Specification authority concentrates in Texas and California utilities consolidating vendor panels under enterprise asset management frameworks.
India
CDSCO cGMP enforcement and PLI scheme incentives for active pharmaceutical ingredient production create validated dosing system demand. The country's national pharmaceutical regulator tightens calibration record requirements for export-oriented facilities. Maharashtra and Gujarat host expanding CDMO capacity where peristaltic configurations prevent cross-contamination between biologics batches.
Netherlands
Dutch utilities lead European adoption of smart diaphragm architectures with embedded flow feedback loops. National effluent discharge limits under the EU Water Framework Directive exceed standard stringency. Rotterdam and Amsterdam municipal operators deploy predictive maintenance contracts that shift vendor revenue toward recurring service platforms.
China
Dual carbon goals and MEE discharge standards elevate precision chemical dosing investments in municipal water treatment. The national environmental regulator enforces traceability requirements that favor digital pump architectures. Yangtze River Delta chemical processing clusters specify modular pump skids for brownfield facility upgrades.
Dosing Pumps Market Vendor Landscape
Capability concentration sits with specialized European fabricators possessing fluoropolymer engineering depth; scale advantage sits with diversified fluid handling conglomerates serving multi-industry portfolios. The vendor base structures across three tiers: precision specialists with certified calibration infrastructure, diversified industrials with predictive service platforms, and regional assemblers competing on commissioning speed. Dominant competitive moves include backward integration into polymer compounding for diaphragm materials and technology licensing agreements for electromechanical actuator architectures.
Within the precision specialist tier, Grundfos Holding A/S and ProMinent GmbH occupy positions defined by digital service infrastructure and chemical-resistant polymer engineering respectively. IDEX Corporation exemplifies the diversified industrial archetype through modular pump architectures. SEKO S.p.A. and Watson-Marlow Fluid Technology Solutions represent European and UK-based specialists whose geographic origins align with regional regulatory compliance infrastructure. These named entities serve as anchors for understanding how competitive positioning fragments across capability depth versus geographic coverage trade-offs.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| ProMinent GmbH |
| IDEX Corporation |
| SEKO S.p.A. |
| Watson-Marlow Fluid Technology Solutions |
| LEWA GmbH |
| SPX Flow |
| Netzsch Pumpen & Systeme GmbH |
| Blue-White Industries |
| Others |
Supply Flow & Price Mechanics
Leonberg's fluoropolymer compounding capacity anchors diaphragm material supply for European pump manufacturers, translating polymer feedstock allocation decisions directly into tiered equipment pricing power. Chemical-resistant polymer engineering capabilities concentrate in this Stuttgart metropolitan cluster, where PTFE and PFA formulation expertise enables premium positioning for compliant sealing architectures.
Pricing Analysis
Predictive maintenance contracts and remote diagnostics platforms now drive lifetime value capture, displacing transactional equipment sales as the dominant revenue model. Three-tier pricing structure across premium, standard, and economy levels separates validated systems with certified calibration records from basic pneumatic configurations. Cost compression in municipal utility procurement is intensifying because enterprise asset management frameworks consolidate vendor panels around predictive service capabilities. Indian pharmaceutical contract manufacturers exhibit acute price sensitivity despite tightening CDSCO enforcement, while Dutch water utilities absorb premium electromechanical systems with minimal elasticity.
Supply Chain Analysis
Contract manufacturing for electromechanical actuators concentrates in Germany, Japan, and Taiwan, where precision motor and sensor fabrication capabilities anchor digital pump assembly. Supply draws from specialized fluoropolymer resin producers in Western Europe and Japan for diaphragm materials, plus precision-machined ceramic components for plunger and seal architectures. Single-source vulnerability runs through PTFE compound formulation intellectual property held by a narrow supplier base. Distribution runs through direct vendor relationships with municipal operators and pharmaceutical OEMs, bypassing traditional distributor networks where predictive platforms enable disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dosing pump markets approach a platform-economics inflection as predictive service platforms displace hardware transactions, with interoperability between embedded sensors and enterprise asset management systems determining competitive survival.
For Market Incumbents: Insulate installed base relationships through backward integration into fluoropolymer compounding for captive diaphragm supply, reducing allocation risk from Western European resin suppliers. Deepen certification infrastructure for FDA cGMP and EPA audit trail compliance to defend against modular pump skid entrants targeting brownfield commissioning speed.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat pharmaceutical corridors offer underpenetrated specification demand where CDSCO calibration record requirements outpace established vendor compliance infrastructure. Target peristaltic configurations for biologics CDMOs preventing cross-contamination, leveraging rapid commissioning architectures to bypass incumbent predictive service moats.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical-predictive analytics convergence plays over legacy pneumatic specialists facing compressed replacement cycles. Long-term viability hinges on recurring revenue platform scale rather than unit shipment volume. Watch for municipal utility enterprise asset management consolidation waves as inflection signals for predictive service platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Compounding | Captive PTFE diaphragm supply insulates LEWA GmbH and ProMinent GmbH from resin allocation volatility. |
| Predictive Maintenance Platform Deployment | Grundfos Holding A/S shifts municipal water utility revenue toward recurring diagnostic subscriptions. |
| Modular Pump Skid Standardization | IDEX Corporation reduces field commissioning time for brownfield chemical facility upgrades. |
| CDSCO cGMP Certification Investment | Validated calibration records unlock Indian pharmaceutical API manufacturing contract opportunities. |
| Edge Computing Sensor Integration | Embedded flow feedback loops enable Dutch utilities to exceed EU Water Framework Directive discharge limits. |
Methodological Framework
Cross-validation between primary interviews with plant engineers, municipal procurement directors, pharmaceutical validation specialists, and aftermarket service managers anchors the qualitative findings against secondary sources including EPA enforcement databases, ECHA REACH substance registrations, CDSCO cGMP inspection records, and customs trade flows for fluoropolymer resin imports. Bottom-up triangulation across equipment shipment data and top-down validation through process industry capital expenditure disclosures ensure dimensional consistency.
Calibration against historical replacement cycle patterns and regulatory compliance cost trajectories informs the projection framework across the analysis window. Segmentation dimensions span pump architecture type, control technology methodology, end-use industry vertical, and regional regulatory cluster intensity. CAGRs derive from installed base turnover rates and digital upgrade penetration curves, with specific inputs including municipal utility enterprise asset management adoption timelines and pharmaceutical biologics manufacturing capacity buildouts.
Practitioners should monitor EPA Clean Water Act enforcement intensity, EU F-Gas Regulation reformulation timelines, and fluoropolymer resin supplier consolidation for early signals requiring forecast revision. Cross-checking against Cefic chemical industry investment surveys and American Water Works Association infrastructure spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market