
 Gear Pump Market | 2026-2036
Gear Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Pump Market Analysis
OEM-direct procurement channels is rewriting how gear pump manufacturers reach end users in construction and agriculture. Bosch Rexroth AG leverages its captive hydraulics distribution to control specification decisions at major equipment builders. Danfoss anchors European demand through its regional manufacturing footprint and aftermarket parts network. Parker Hannifin Corporation competes on breadth, extending its motion and control portfolio into integrated pump-motor assemblies.
A gear pump is a positive-displacement rotary pump employing intermeshing gears to transfer fluid at rates typically from 0.5 to 250 gallons per minute, with pressure ratings spanning 1,000 to 5,000 psi depending on design and materials. External gear configurations dominate mature industrial hydraulic systems where cost sensitivity and proven durability outweigh efficiency premiums. Internal gear variants capture expanding share in chemical processing applications requiring lower pulsation and gentler shear characteristics. Servo-controlled technology leads margin pools as end users demand variable flow rates without throttling losses.
The US EPA regulates hydraulic fluid spill containment and disposal, while EU REACH restricts certain seal and coating chemistries, forcing reformulation of wetted components. ISO 4406 cleanliness standards govern particle contamination limits, creating aftermarket filtration demand tied to pump warranty compliance. Stakeholders must monitor how electrification of mobile hydraulics reshapes displacement requirements and thermal management specifications.
Market Dynamics
Electrification of mobile hydraulic systems is compressing displacement requirements and forcing thermal management redesigns across gear pump architectures. This shift from engine-driven to electric-motor power sources is reshaping specification criteria at major construction and agriculture OEMs.
Growth Catalysts
- EU REACH chemical restrictions:Seal and coating reformulations are accelerating material innovation in wetted components, opening premium positioning for compliant suppliers.
- Construction equipment hydraulics:Earthmoving and material handling machinery anchor replacement demand cycles tied to infrastructure capital deployment.
- Servo-controlled variable flow:Electronic displacement control eliminates throttling losses and commands margin premiums in precision fluid handling applications.
Market Restraints
- Alloy steel price volatility:Gear and housing material costs fluctuate with commodity markets, compressing margin predictability for mid-tier manufacturers.
- German industrial automation corridor concentration:Demand clustering in Bavaria and Baden-Württemberg creates geographic exposure to regional capital expenditure cycles.
- Axial piston pump substitution:Higher-efficiency alternatives capture share in pressure-critical applications above 3,000 psi.
Strategic Opportunities
- India PLI scheme for machinery:Domestic manufacturing incentives attract component localization for construction and agricultural equipment supply chains.
- Aftermarket filtration services:ISO 4406 cleanliness compliance creates recurring revenue streams tied to pump warranty maintenance protocols.
- Integrated pump-motor assemblies:Electrification convergence with permanent magnet motor technology enables compact power-dense system architectures.
Industry Challenges
- Contamination control expertise:Fluid cleanliness specification and filtration system integration require specialized application engineering talent in short supply.
- Legacy hydraulic system integration:Retrofit compatibility with existing reservoir and valve architectures complicates new product adoption timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Pump Market |
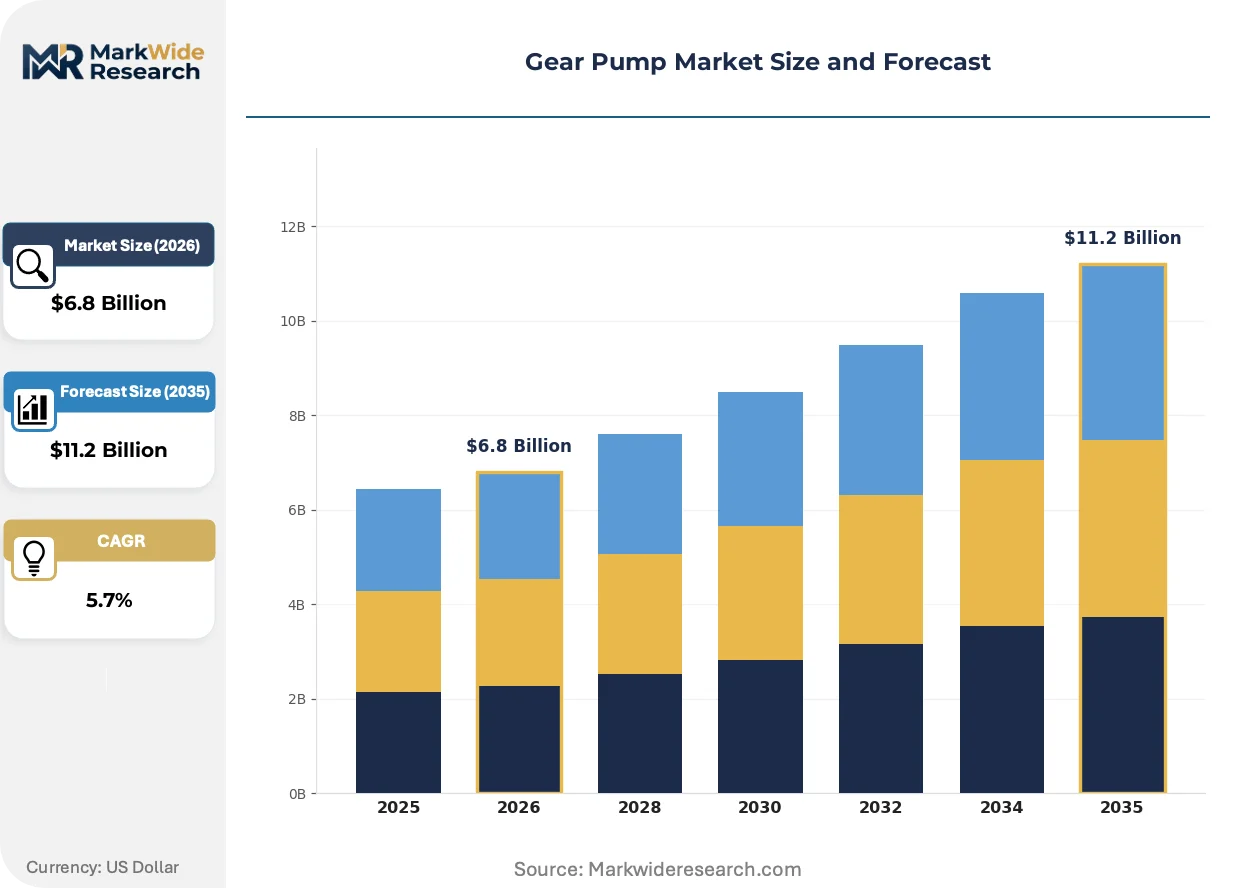
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Hydraulic Systems, Fuel Transfer, Chemical Processing, Water Management Type: External Gear, Internal Gear, Gear Set, Rotary Vane End User: Aerospace, Marine, Construction, Agriculture Technology: Positive Displacement, Variable Displacement, Servo-Controlled, Manual Control |
| Companies Covered | Danfoss, Kawasaki Heavy Industries, Bosch Rexroth AG, Casappa S.p.A., HYDAC International GmbH, Parker Hannifin Corporation, Bucher Hydraulics, Marzocchi Pompe S.p.A., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Pump Market Emerging Trajectories
Sensor integration and predictive analytics are penetrating gear pump systems, converting mechanical components into data-generating assets. This instrumentation wave is redefining value capture from hardware sales to performance-guarantee contracts.
Smart pump monitoring using embedded pressure and temperature transducers is digitizing maintenance scheduling and failure prediction. Fleet operators in material handling and construction are adopting these systems fastest, driven by uptime cost sensitivity. Real-time vibration analysis is digitizing traditional preventive maintenance intervals into condition-based interventions.
US EPA spill containment rules are tightening hydraulic fluid handling requirements across mobile equipment categories. The regulations mandate secondary containment and rapid response protocols for fluid power systems. Construction equipment operating in environmentally sensitive zones faces the strictest compliance burdens, accelerating sealed-system redesigns.
Direct OEM specification control is displacing distributor-led technical selection in construction and agriculture channels. Major equipment builders now embed hydraulic engineers who dictate pump architecture during early design phases. This concentration is most pronounced in Germany's industrial automation corridor and US Midwest agricultural machinery manufacturing clusters.
Gear Pump Market Segmentation
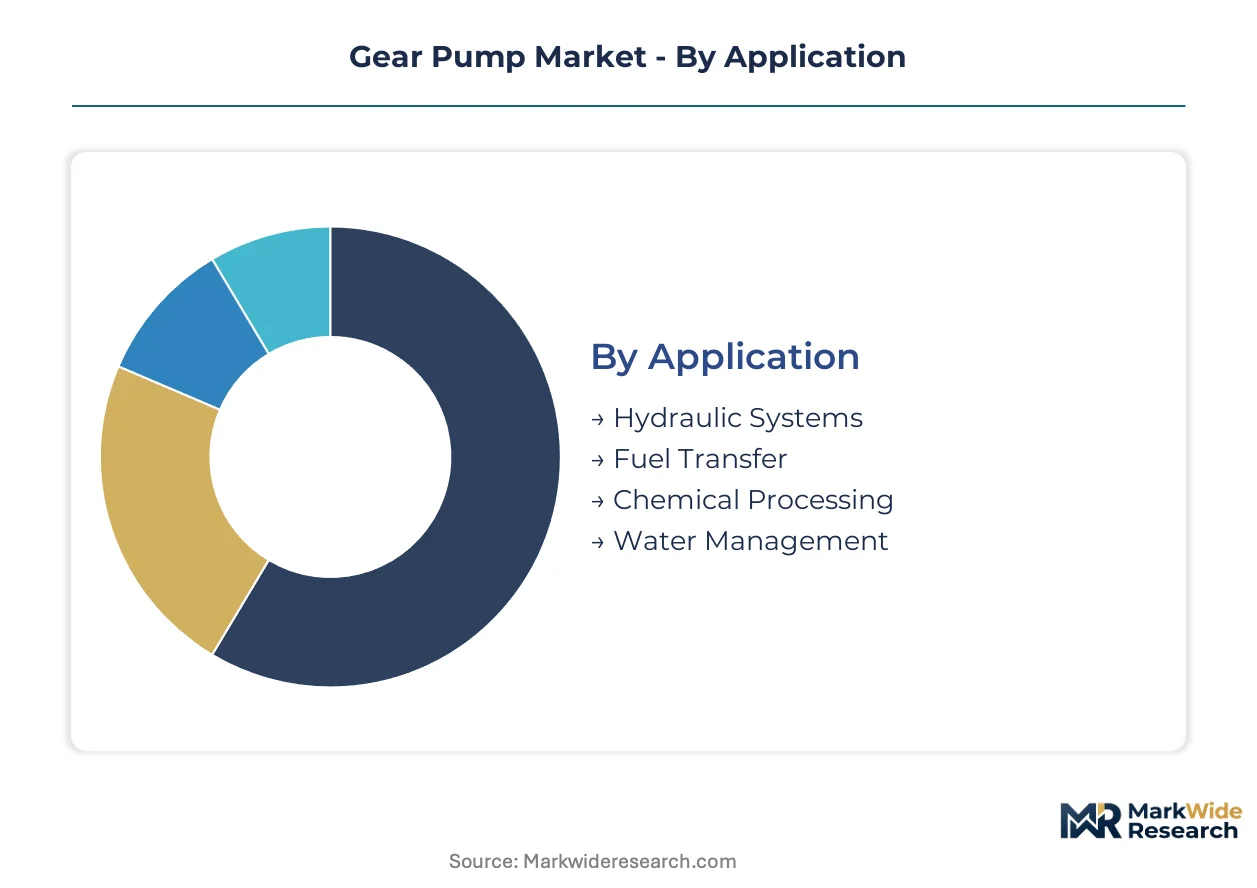
Gear pump specification varies sharply by duty cycle and fluid characteristics. Application context determines pressure ratings, material selection, and control architecture. Procurement decisions cascade from these technical boundaries into supplier qualification and aftermarket service requirements.
Application:
Hydraulic power transmission spans construction equipment, industrial machinery, and mobile platforms with divergent pressure and contamination tolerance profiles.
- Hydraulic Systems:These pumps deliver pressurized fluid to cylinders and motors at 1,000–5,000 psi in earthmoving equipment and factory automation. Demand clusters in Germany's industrial automation corridor where precision fluid handling commands capital investment priority.
- Fuel Transfer:Low-pressure, high-volume configurations handle diesel and aviation fuel with tight leakage specifications. Marine bunkering and agricultural equipment refueling anchor replacement cycles in coastal and rural distribution networks.
- Chemical Processing:Corrosion-resistant alloys and sealed bearing designs manage aggressive fluids with minimal shear. Internal gear variants gain preference here for pulsation-sensitive dosing operations.
- Water Management:Potable water and wastewater applications require NSF-certified materials and sanitary quick-disconnect features. Municipal infrastructure and desalination plants drive specification compliance overhead.
Established volume favors Hydraulic Systems; emerging adoption favors Chemical Processing.
Type:
Architectural geometry determines efficiency trade-offs, noise signatures, and manufacturing cost structures across the installed base.
- External Gear:Intermeshing spur or helical gears in separate housings dominate mature industrial hydraulics. US construction equipment OEMs specify these for proven durability in high-cycle earthmoving applications where cost sensitivity outweighs efficiency premiums.
- Internal Gear:A crescent-shaped partition separates inner and outer gears, reducing pulsation and enabling higher viscosity handling. Chemical processing and food-grade applications in the EU adopt these for gentler shear characteristics under REACH material compliance.
- Gear Set:Modular cartridge designs allow field replacement without full pump removal. Fleet maintenance operations in agriculture value reduced downtime against higher initial component cost.
- Rotary Vane:Eccentric cam-driven vanes compete in low-pressure, high-speed niches where gear meshing losses prove prohibitive. Compressor lubrication and HVAC refrigerant circulation represent marginal addressable share.
External Gear retains the largest installed base; Internal Gear climbs the fastest on chemical compatibility requirements.
End User:
Customer archetypes impose distinct certification, reliability, and service network demands that reshape go-to-market economics.
- Aerospace:FAA and EASA certification cycles demand traceable materials and redundant sealing. Landing gear actuation and flight control hydraulics tolerate minimal failure rates at extreme temperature swings.
- Marine:Classification society rules from Lloyd's Register and DNV govern seawater corrosion resistance. Deep-sea pressure compensation and splash-zone installation drive specialized housing designs.
- Construction:Earthmoving and material handling machinery anchor the highest absolute unit demand. EPA spill containment rules now mandate secondary containment for hydraulic systems in environmentally sensitive zones.
- Agriculture:Seasonal intensity and remote operation prioritize field serviceability over specification optimization. Midwest US equipment manufacturing clusters concentrate OEM procurement decisions.
Construction commands current revenue concentration; Aerospace yields the steepest expansion trajectory on fleet renewal cycles.
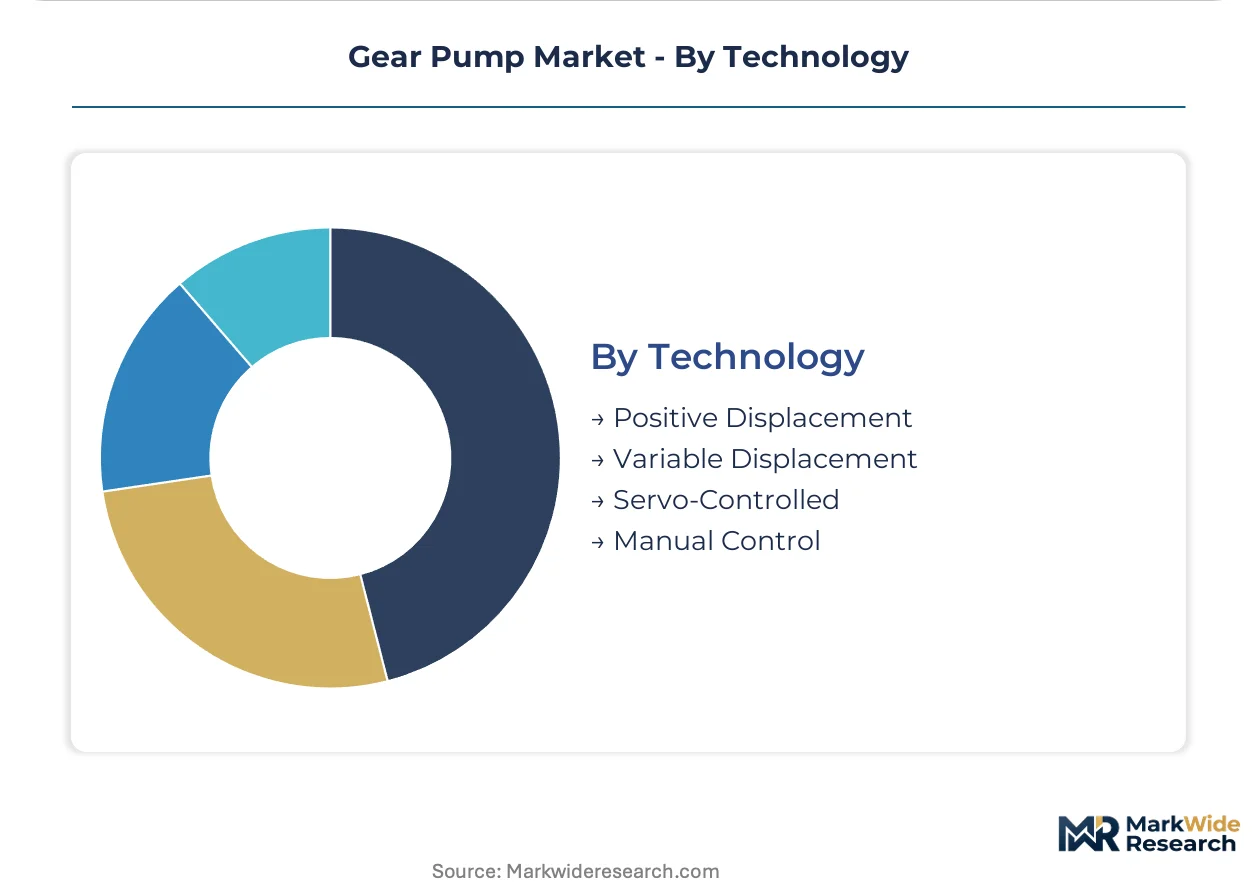
Technology:
Control methodology determines energy efficiency, system integration complexity, and margin capture potential.
- Positive Displacement:Fixed displacement per revolution provides simplicity and cost minimization. Legacy industrial hydraulics and basic agricultural implements retain this architecture for maintenance accessibility.
- Variable Displacement:Mechanical or hydraulic compensation adjusts output to load demand without throttling losses. Mobile equipment electrification is compressing displacement requirements and forcing thermal management redesigns in these units.
- Servo-Controlled:Electronic displacement control via integrated position feedback eliminates throttling losses entirely. Precision fluid handling in German automation corridors and semiconductor manufacturing commands margin premiums.
- Manual Control:Hand-operated bypass or stroke adjustment persists in auxiliary and emergency systems. Developing market infrastructure and backup power applications sustain residual demand.
Servo-Controlled systems gain share fastest on electrification convergence; Positive Displacement retains cost-driven volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's hydraulic component distribution reach into Central European manufacturing clusters. Port of Hamburg container throughput anchors fluid power equipment import velocity for Northern European construction equipment builders. This infrastructure geometry shapes regional demand concentration.
Germany
Bavaria's industrial automation corridor drives precision fluid handling capital expenditure at machine tool OEMs. EU REACH chemical restrictions force seal and coating reformulations across wetted pump components. Stuttgart and Munich engineering clusters concentrate servo-controlled gear pump specification authority at major equipment builders.
United States
Midwest agricultural machinery manufacturing clusters anchor replacement demand cycles for external gear configurations. EPA spill containment rules mandate secondary containment for hydraulic systems in environmentally sensitive construction zones. Illinois and Iowa equipment OEMs embed hydraulic engineers who dictate pump architecture during early design phases.
China
Yangtze River Delta construction equipment production volumes compress displacement requirements as electrification reshapes mobile hydraulic architectures. MIIT industrial machinery standards tighten material traceability for export-bound components. Shanghai and Suzhou manufacturing hubs concentrate domestic gear pump fabrication for regional construction machinery supply chains.
India
PLI scheme incentives for construction and agricultural machinery attract component localization investments from multinational hydraulics suppliers. BIS certification requirements govern pressure equipment safety standards for domestic market access. Maharashtra and Gujarat industrial corridors concentrate capital deployment in fluid power system manufacturing.
Japan
Chubu region precision machinery exports sustain demand for low-pulsation internal gear variants in semiconductor manufacturing equipment. METI energy efficiency regulations accelerate servo-controlled displacement adoption in factory automation systems. Nagoya industrial cluster expertise in mechatronics integration commands premium positioning for electronic pump control architectures.
Gear Pump Market Vendor Landscape
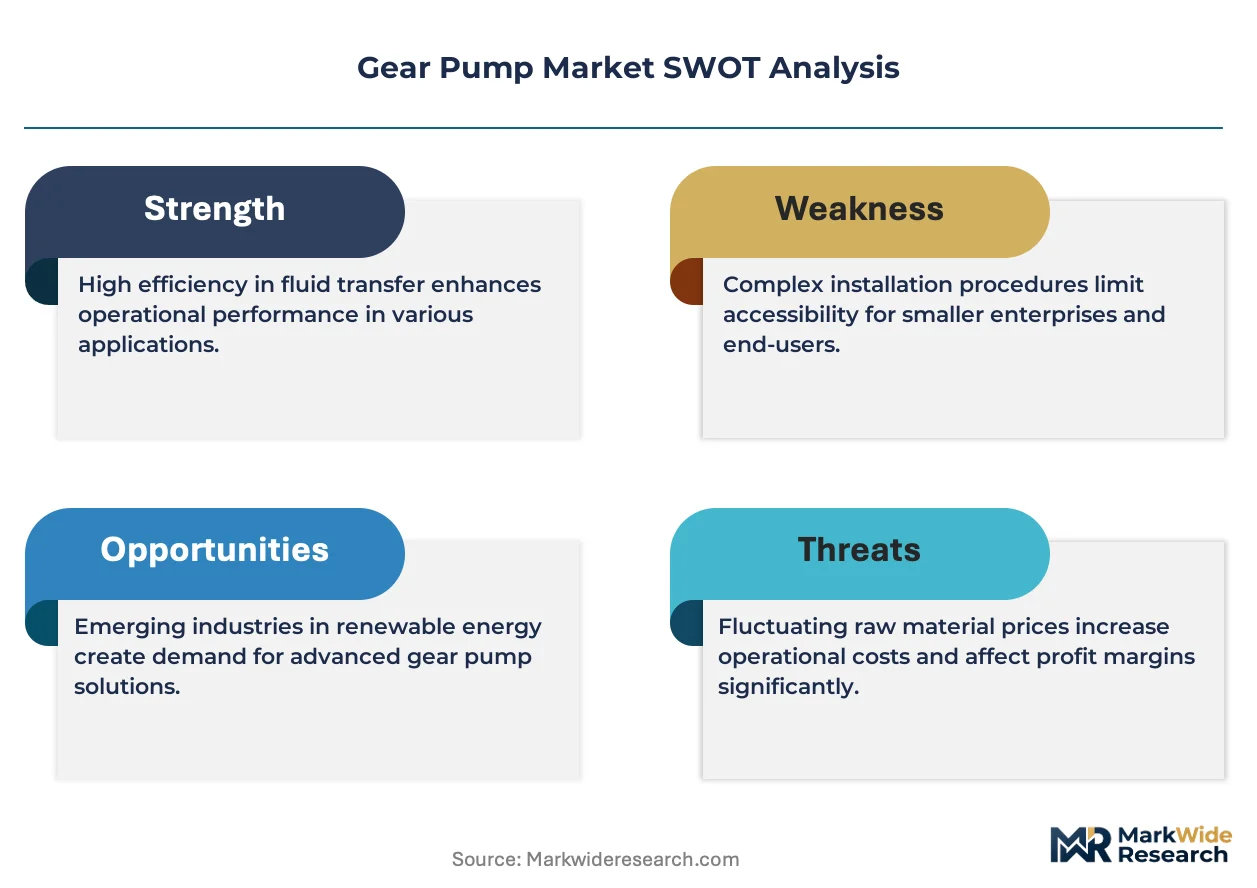
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three structural tiers: diversified motion-control conglomerates with captive hydraulics divisions, mid-scale regional specialists with focused geographic footprints, and niche engineering houses serving extreme-environment applications. Consolidation pressure runs highest among mid-tier European fabricators facing alloy steel cost volatility. Strategic moves cluster on integrated pump-motor assembly development and aftermarket filtration service expansion.
Among diversified motion-control conglomerates, Danfoss and Bosch Rexroth AG occupy positions reflecting captive distribution control over specification decisions at major equipment builders. Parker Hannifin Corporation sits within the breadth-driven tier, extending portfolio coverage into integrated system architectures. These three anchors exemplify how scale and specification authority concentrate competitive advantage in construction and agriculture channels.
| Leading Market Players |
|---|
| Danfoss |
| Kawasaki Heavy Industries |
| Bosch Rexroth AG |
| Casappa S.p.A. |
| HYDAC International GmbH |
| Parker Hannifin Corporation |
| Bucher Hydraulics |
| Marzocchi Pompe S.p.A. |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Alloy steel price volatility determines both tiered pricing spreads and supply chain configuration across gear pump manufacturing. Raw material cost swings compress margin predictability for mid-tier fabricators while concentrating procurement power among diversified motion-control conglomerates with captive metallurgy sourcing.
Pricing Analysis
Volume-discount tiering structures stratify across premium servo-controlled, standard variable-displacement, and economy fixed-displacement configurations. Certification grade under EU REACH and ISO 4406 cleanliness compliance create pricing premiums alongside brand positioning. Cost compression in economy external gear segments is intensifying as Chinese fabricators expand export capacity. Agricultural OEMs in the US Midwest exhibit highest price sensitivity, while German automation corridor buyers prioritize precision fluid handling over unit cost.
Supply Chain Analysis
Export-control regimes on permanent magnet motor technology constrain integrated pump-motor assembly flows from Japan and China. Manufacturing gravity centers on Germany, China, and India for component fabrication and final assembly. Supply chains draw from specialty alloy steel mills in South Korea and Japan, precision bearing suppliers in Germany, and seal compound formulators subject to REACH restrictions. Single-source vulnerability concentrates in rare-earth magnet sourcing for servo-controlled architectures. Distribution runs through OEM-direct specification channels displacing traditional distributor technical selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contamination control engineering talent scarcity constrains aftermarket filtration service expansion and smart pump monitoring deployment timelines. This capability gap separates specification winners from commodity suppliers across construction and agriculture channels.
For Market Incumbents: Insulate specification authority at major construction and agriculture OEMs through embedded hydraulic engineering partnerships and captive distribution control. Deepen backward integration into alloy steel sourcing to offset commodity volatility. Accelerate ISO 4406 compliance service bundling to lock in aftermarket revenue streams against emerging filtration specialists. For New Entrants and Emerging Players: Establish a beachhead in India PLI scheme construction machinery component localization before multinational hydraulics suppliers consolidate regional manufacturing footprints. Target chemical processing internal gear applications where REACH compliance creates qualification barriers for established external gear specialists. Lead with sensor-integrated predictive maintenance offerings to bypass traditional channel relationships. For Investors and Strategic Acquirers: The market sits at an electrification transition phase that favors integrated pump-motor assembly capabilities over standalone component suppliers. Long-term viability hinges on servo-controlled displacement technology and permanent magnet motor integration expertise. Watch for inflection signals in construction equipment battery-electric platform announcements from major OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Pump-Motor Assembly Development | Electrification convergence with permanent magnet motor technology enables compact power-dense architectures for mobile hydraulics. |
| Aftermarket Filtration Service Expansion | ISO 4406 cleanliness compliance creates recurring revenue tied to pump warranty maintenance protocols at fleet operators. |
| India PLI Scheme Localization | Domestic manufacturing incentives attract component investment for construction and agricultural equipment supply chains. |
| Sensor-Integrated Predictive Maintenance Platform | Embedded pressure and temperature transducers digitize maintenance scheduling for uptime-sensitive material handling fleets. |
| EU REACH Compliant Material Reformulation | Seal and coating chemistry innovation opens premium positioning for compliant suppliers in chemical processing applications. |
Methodological Framework
The analysis maps hydraulic systems, fuel transfer, chemical processing, and water management applications, each validated through OEM procurement teams, aftermarket service directors, and plant maintenance engineers. Primary fieldwork combined equipment builder specification interviews with secondary triangulation against customs trade data, SEC filings from diversified motion-control conglomerates, and MIIT industrial machinery standards documentation. Bottom-up unit demand modeling and top-down value chain sizing cross-validated segment-level outputs.
Assumptions held fixed include electrification penetration rates in mobile hydraulics and alloy steel price normalization trajectories, while variable displacement adoption and REACH enforcement intensity were stress-tested across scenarios. Segmentation dimensions encompassed application context, gear architecture type, end-user certification requirements, and control methodology. CAGRs derived from installed base replacement cycles and capital expenditure elasticity models, with specific inputs from construction equipment production forecasts and semiconductor manufacturing equipment order flows.
Sensitivities concentrate around battery-electric construction equipment deployment timelines and rare-earth magnet supply disruption events. Forecasts reflect documented assumptions regarding OEM specification behavior and regulatory enforcement consistency. Material shifts in EPA spill containment rule stringency or EU REACH chemical restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
End Suction Pump Market