
 Global Solar Water Pump Systems Market | 2026-2036
Global Solar Water Pump Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Water Pump Systems Market Outlook
DC-to-AC variable frequency drive integration is reconfiguring how solar water pump systems convert photovoltaic output into mechanical lift. Grundfos Holding A/S leverages its electronics manufacturing depth to dominate premium submersible controller assemblies. LORENTZ GmbH anchors its position through proprietary maximum power point tracking algorithms purpose-built for off-grid conditions. Shakti Pumps (India) Limited competes on manufacturing scale, sustaining cost leadership across India's vast agricultural distributor network.
Solar water pump systems are electromechanical installations that combine photovoltaic arrays with centrifugal or positive-displacement pumps to extract and transport water without grid electricity, typically operating at 24V to 400V DC depending on head requirements and daily insolation profiles. The primary commercial purpose is to displace diesel-powered irrigation and borehole pumping in locations where grid extension proves economically unviable. Submersible configurations now capture the dominant share of agricultural deployments due to their suitability for deep groundwater extraction across arid and semi-arid zones. Surface pump architectures retain relevance in shallow well and river lift applications where lower capital outlays attract smallholder budgets. Photovoltaic technology leads the energy conversion segment, though wind-solar hybrid designs are gaining structural traction in regions with complementary seasonal wind patterns.
India's Ministry of New and Renewable Energy, the US Department of Agriculture REAP program, and the EU Green Deal's F-Gas Regulation collectively shape equipment subsidies, pump efficiency mandates, and refrigerant-based system compliance across major demand centers. India's PLI scheme for solar module manufacturing is tightening domestic content requirements, altering supply chain economics for system assemblers sourcing photovoltaic components. Stakeholders must monitor how evolving national renewable energy targets and groundwater extraction limits interact to determine viable addressable markets.
Market Dynamics
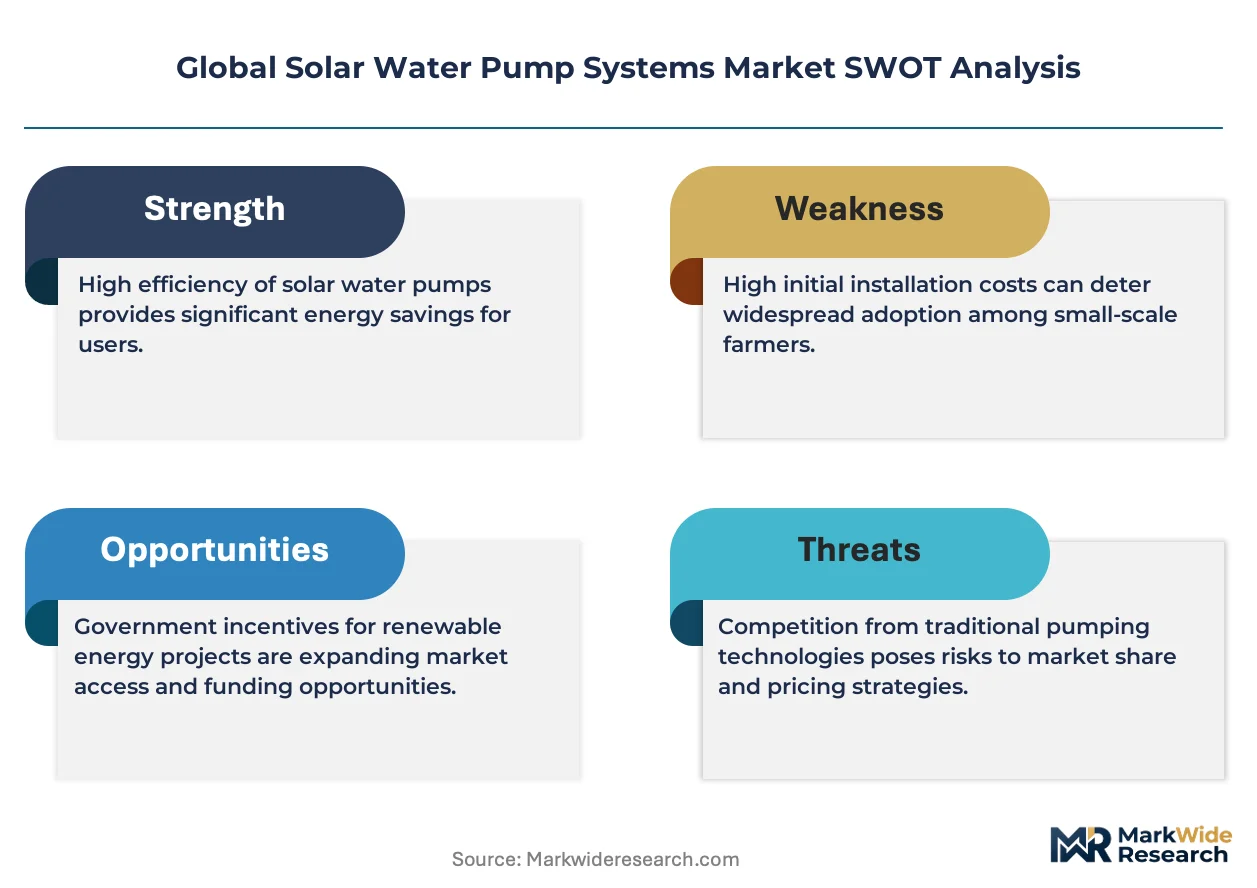
Photovoltaic module cost deflation is compressing system-level economics faster than distribution networks can absorb, forcing assemblers to consolidate controller manufacturing or cede margin to module suppliers.
Growth Catalysts
- India's PM-KUSUM scheme:The subsidy framework for off-grid agricultural pumps is accelerating deployment across Maharashtra and Gujarat, with state nodal agencies streamlining interconnection approvals for submersible configurations.
- Groundwater depletion mandates:Regulatory caps on diesel-powered borehole extraction in Rajasthan and Telangana are pushing smallholder farmers toward solar alternatives for irrigation scheduling.
- DC-to-AC variable frequency drives:These controller technologies are expanding addressable head ranges for centrifugal pumps, enabling single installations to serve multiple crop cycles across variable topography.
Market Restraints
- Polysilicon supply concentration:Ingot and wafer production clusters in specific East Asian manufacturing zones create input cost volatility that propagates through module pricing to system integrators.
- Deep groundwater technical limits:Submersible pump efficiency degrades beyond 150-meter head requirements, restricting viable deployment in hard-rock aquifer zones across the Deccan Plateau.
- US REAP program complexity:USDA administrative burden and seasonal funding windows create application friction that delays farmer procurement decisions beyond optimal planting schedules.
Strategic Opportunities
- Kenya's agricultural extension networks:Underpenetrated smallholder clusters in the Rift Valley present white space for pay-as-you-go pump financing models bundled with agronomic advisory services.
- Wind-solar hybrid convergence:Complementary seasonal generation profiles in coastal Tamil Nadu and Gujarat enable higher capacity factors for irrigation cooperatives with dual-source arrays.
- EU F-Gas Regulation phase-down:Refrigerant-based cooling mandates for ancillary equipment are creating retrofit demand for thermally integrated solar pumping systems in Southern European horticulture.
Industry Challenges
- Controller firmware integration:Maximum power point tracking algorithm calibration for variable insolation profiles requires embedded systems expertise scarce in traditional pump distributor networks.
- BIS certification timelines:Indian standards body testing queues for submersible motor assemblies extend lead times by 8-14 weeks, compressing seasonal installation windows for monsoon-dependent farmers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Water Pump Systems Market |
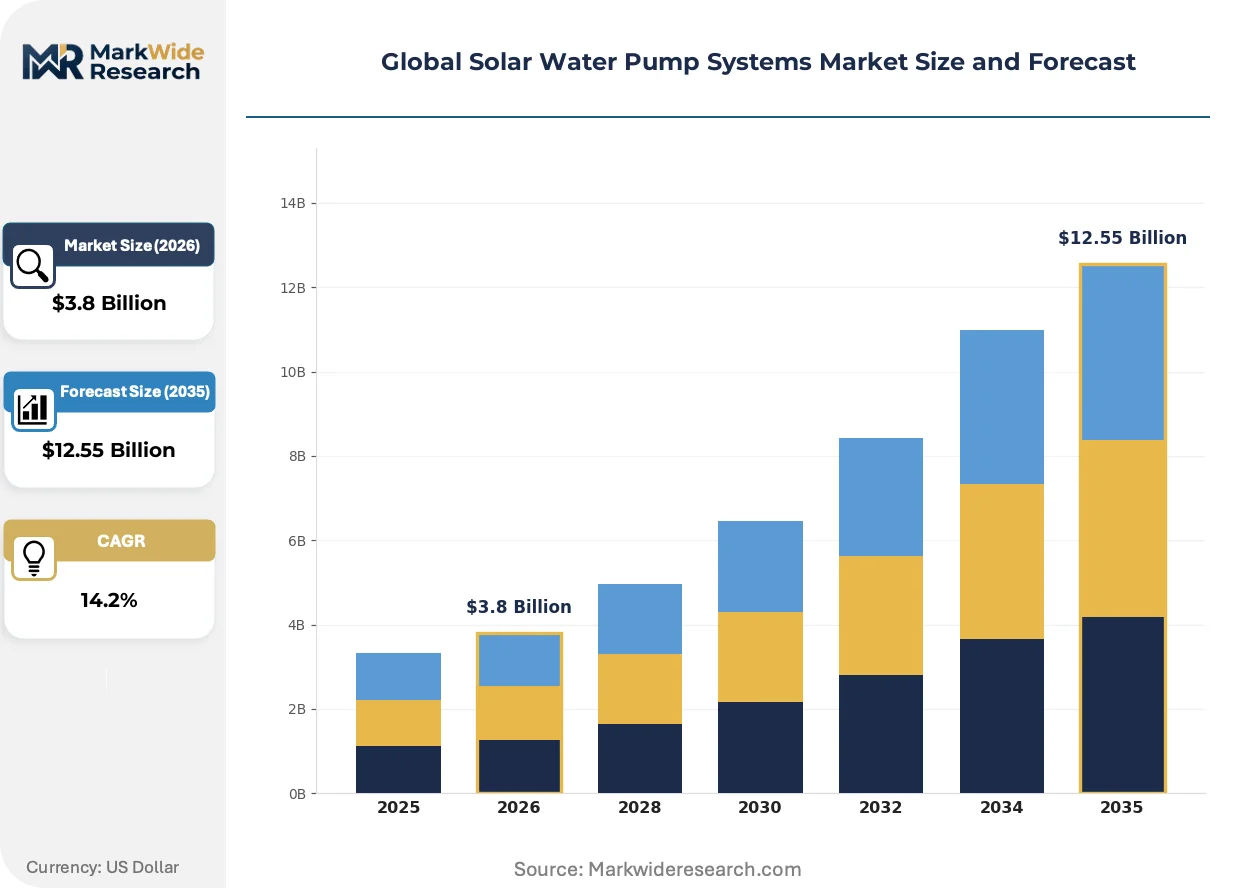
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Surface, Solar Hybrid, DC Solar Application: Agriculture, Residential, Industrial, Commercial Technology: Photovoltaic, Solar Thermal, Wind-Solar Hybrid, Other End User: Farmers, Municipalities, Water Utilities, NGOs |
| Companies Covered | Shakti Pumps (India) Limited, Grundfos Holding A/S, LORENTZ GmbH, KSB SE & Co. KGaA, Franklin Electric, Xylem Inc., Kirloskar Brothers Ltd., Waaree Energies Ltd., C.R.I. Pumps Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Water Pump Systems Market Strategic Shifts
Electronics manufacturing depth is becoming the primary competitive differentiator as pump hardware commoditizes and intelligence migrates toward controller assemblies.
Permanent magnet synchronous motor technology is migrating from industrial process applications into agricultural submersible pumps. Large horticulture operations in Spain and Italy are adopting these motors for their partial-load efficiency advantages. The shift is compressing energy consumption per cubic meter lifted, forcing traditional induction motor suppliers to add variable frequency drive compatibility or retreat to shallow-well segments.
REACH substance restrictions on electronics manufacturing are reshaping supply chain qualification requirements for controller assemblies. The European Chemicals Agency's expanded candidate list is forcing Asian contract manufacturers to reformulate solder alloys and conformal coatings. System assemblers serving EU markets are responding by dual-sourcing from qualified European electronics foundries, adding 12-18% to controller bill-of-materials.
Farmer purchasing committees in India's Maharashtra and Karnataka are consolidating procurement authority away from individual distributors. These cooperative structures are negotiating directly with system integrators for volume pricing and standardized service terms. The disintermediation is most visible in sugarcane belt districts where irrigation scheduling coordination across contiguous landholdings favors uniform pump specifications.
Global Solar Water Pump Systems Market Segmentation
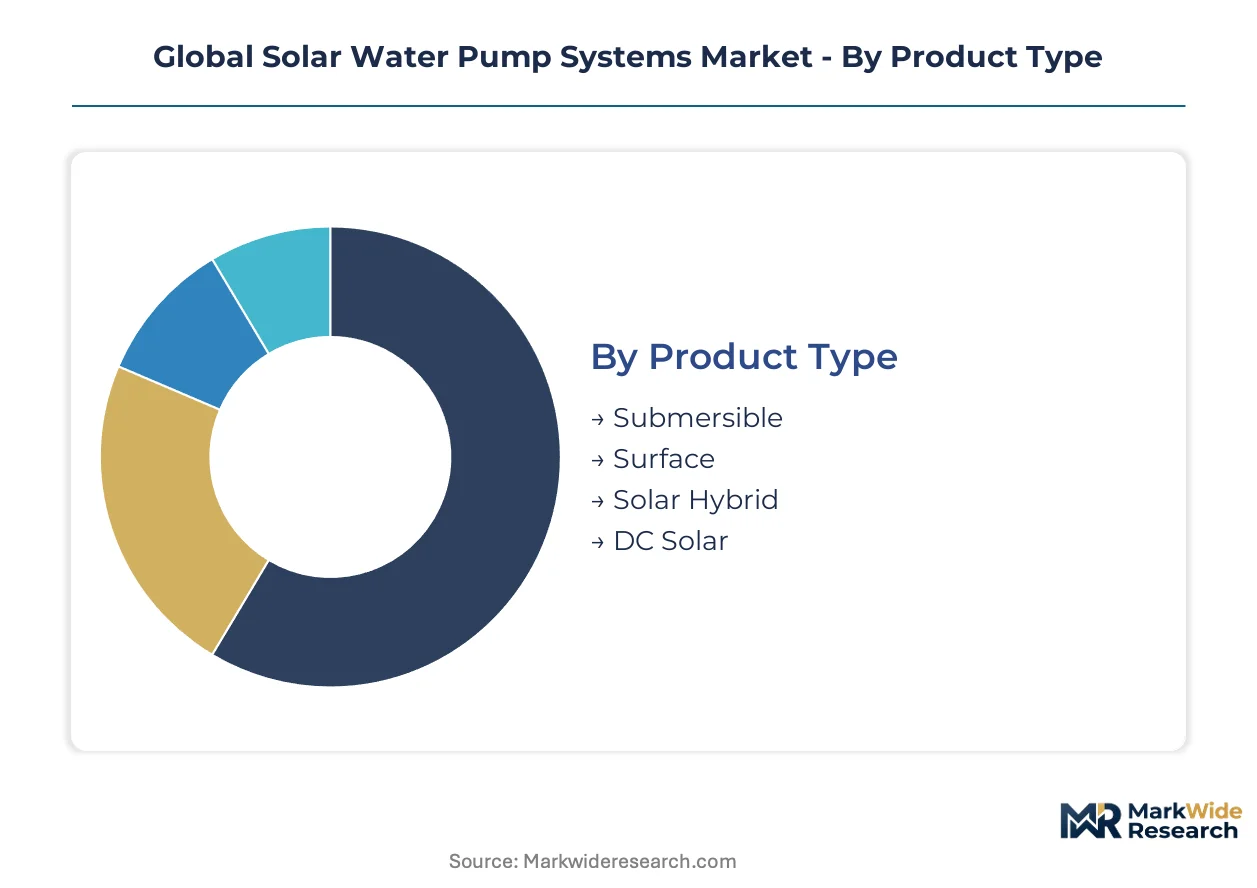
Solar water pump system configurations diverge sharply in service complexity and component replacement cycles. Submersible installations demand specialized borehole retrieval capabilities that reshape distributor economics, while surface architectures enable faster field repairs. Understanding these segment-specific service footprints clarifies where aftermarket revenue pools concentrate.
Product Type:
After-sales intensity varies dramatically across pump architectures, with submersible configurations requiring borehole extraction equipment and trained technicians that reshape distributor profitability models.
- Submersible:Motor and pump assemblies operate fully immersed at depths exceeding 50 meters, sealed against groundwater intrusion through multi-stage mechanical seals. Demand concentrates across India's Deccan Plateau and Rajasthan's hard-rock aquifers where diesel displacement mandates from the country's groundwater authority accelerate conversion. Deep-bore technical requirements limit viable installer networks, compressing margin capture for assemblers lacking captive service infrastructure.
- Surface:Centrifugal or positive-displacement units mount above water level, drawing through suction lines for shallow wells and river lift applications. Smallholder clusters in Kenya's Rift Valley and Ethiopia's Awash Valley favor these configurations for capital accessibility and field-repair simplicity. Lower technical barriers enable broader distributor participation, fragmenting pricing power across informal supply chains.
- Solar Hybrid:Dual-source architectures integrate photovoltaic with grid or diesel fallback for irrigation scheduling flexibility. Large horticulture operations in Spain's Almería province deploy these for compliance with EU F-Gas Regulation phase-down timelines.
- DC Solar:Direct-current systems eliminate inverter losses for low-head, low-flow applications across remote pastoral zones. Australian cattle stations and Namibian communal conservancies favor these for standalone reliability.
By volume, Submersible leads. By growth pace, Solar Hybrid is ahead.
Application:
Cost tier stratification separates capital-intensive commercial deployments from smallholder budgets, with financing structure rather than technology specification determining addressable market boundaries.
- Agriculture:Irrigation scheduling for field crops, orchards, and livestock watering dominates installed capacity, with pump sizing calibrated to crop water requirements and seasonal insolation curves. India's PM-KUSUM scheme subsidization across Maharashtra and Gujarat sugarcane belts is accelerating submersible adoption where groundwater depletion mandates restrict diesel extraction. Cooperative procurement committees in these districts are consolidating purchasing authority, disintermediating traditional distributor networks.
- Residential:Domestic water supply and pressure boosting for rural homesteads operates at smaller scale, typically below 2kW array capacity. Kenyan pay-as-you-go financing models bundled with agronomic advisory services are expanding access across underpenetrated smallholder clusters.
- Industrial:Process water supply and cooling tower makeup for remote mining and manufacturing sites requires higher reliability guarantees. South African platinum belt operations specify wind-solar hybrid configurations for complementary seasonal generation.
- Commercial:Horticulture nurseries, golf course irrigation, and hospitality water features prioritize aesthetic integration and noise constraints. Southern European greenhouse operators are retrofitting thermally integrated systems under EU F-Gas refrigerant mandates.
Agriculture captures the largest revenue pool. Residential installations are expanding most quickly through distributed financing innovation.
Technology:
Supply concentration in photovoltaic module manufacturing is compressing system integrator margins, forcing controller specialization as the primary differentiation vector.
- Photovoltaic:Silicon-based cell arrays convert solar irradiance directly to electrical output, with monocrystalline configurations dominating agricultural deployments for space-constrained installations. Polysilicon supply concentration in East Asian manufacturing zones propagates input cost volatility through module pricing.
- Solar Thermal:Concentrated heat drives organic Rankine cycle or absorption pumping for high-temperature process applications. Limited deployment in Middle Eastern desalination pilot projects.
- Wind-Solar Hybrid:Complementary seasonal generation profiles enable higher capacity factors for irrigation cooperatives. Coastal Tamil Nadu and Gujarat installations leverage monsoon wind patterns against post-monsoon solar peaks.
- Other:Emerging thermoelectric and piezoelectric conversion mechanisms remain laboratory-scale without commercial traction.
Photovoltaic dominates installed base. Wind-Solar Hybrid is gaining share fastest through capacity factor optimization.
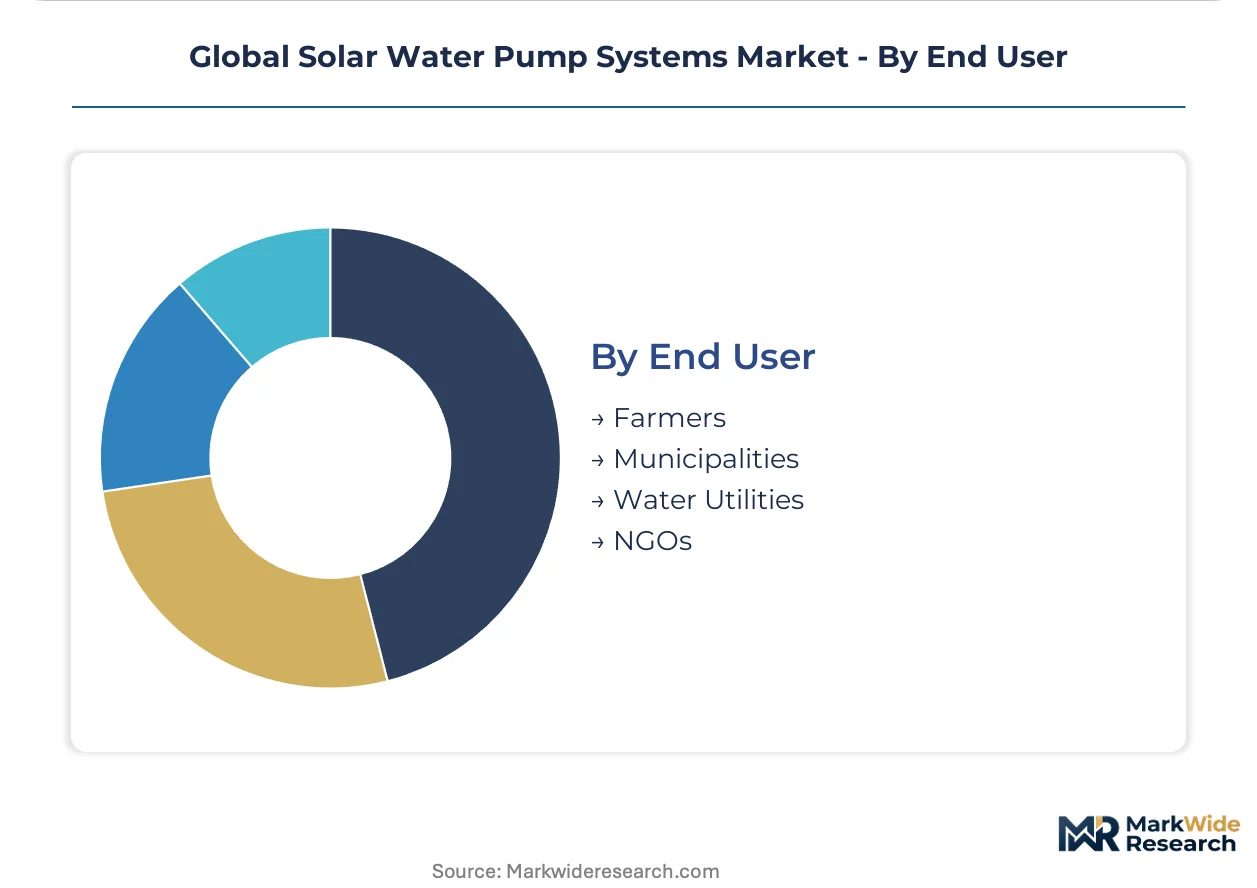
End User:
Customer type determines procurement authority structure, with consolidated purchasing committees commanding volume pricing unavailable to individual smallholders.
- Farmers:Individual smallholders and cooperative members constitute the volume base, with irrigation scheduling decisions tied to monsoon timing and crop cycles. India's BIS certification queues for submersible motor assemblies compress seasonal installation windows.
- Municipalities:Rural water supply schemes and village-level distribution networks require standardized specifications for maintenance interoperability. Procurement through state nodal agencies streamlines interconnection approvals.
- Water Utilities:Regional bulk water suppliers specify higher head ranges and redundancy configurations for distribution network reliability.
- NGOs:Development finance and climate adaptation programming targets frontier markets with grant-subsidized deployment models. Administrative burden from US REAP program complexity delays procurement beyond optimal planting schedules in comparable contexts.
Farmers represent the deepest volume base. Municipalities are climbing the fastest as decentralized infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder farmers in India's agrarian belt concentrate procurement authority through cooperative structures, while Sub-Saharan Africa's decentralized irrigation networks attract pay-as-you-go financing innovation. Kenya's Rift Valley and Ethiopia's Awash Valley represent frontier expansion zones for surface pump configurations.
India
Maharashtra and Gujarat sugarcane belts drive submersible pump demand as groundwater depletion mandates restrict diesel extraction. The PM-KUSUM scheme subsidizes off-grid agricultural pumps through state nodal agencies streamlining interconnection approvals. Cooperative procurement committees in these districts consolidate purchasing authority and disintermediate traditional distributor networks.
United States
Remote agricultural operations in California's Central Valley and Texas High Plains seek diesel displacement for irrigation scheduling flexibility. The USDA REAP program provides equipment subsidies, though administrative burden and seasonal funding windows create application friction. Midwest grain belt farmers face compressed procurement timelines that delay decisions beyond optimal planting schedules.
Kenya
Rift Valley smallholder clusters represent underpenetrated demand for surface pump configurations with shallow-well accessibility. Pay-as-you-go financing models bundled with agronomic advisory services expand access across pastoral and mixed farming zones. Nairobi-based agricultural extension networks coordinate deployment logistics for distributed irrigation cooperatives.
Germany
Baden-Württemberg and Bavaria horticulture operations specify thermally integrated systems under EU F-Gas Regulation refrigerant phase-down mandates. Precision agriculture adoption in the Rhine Valley favors variable frequency drive compatibility for energy efficiency compliance. Stuttgart industrial clusters supply controller electronics to system integrators serving Southern European greenhouse operators.
Australia
Northern Territory cattle stations and Queensland pastoral zones favor DC solar configurations for standalone reliability in remote grid-absent locations. The country's national renewable energy agency coordinates demonstration programs for solar thermal pilot projects. Perth-based mining operations in the Pilbara specify wind-solar hybrid arrays for complementary seasonal generation profiles.
Global Solar Water Pump Systems Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where electronics manufacturing depth determines margin capture. Consolidation pressures favor assemblers with captive controller production or established agricultural distributor networks. Three archetypes dominate: premium submersible specialists with embedded systems expertise, scale-driven manufacturers serving price-sensitive smallholder markets, and hybrid solution providers integrating photovoltaic with auxiliary power sources. Competitive moves concentrate on backward integration into controller firmware and strategic partnerships with state nodal agencies for subsidy program access.
Among European pump specialists, Grundfos Holding A/S and LORENTZ GmbH occupy positions emphasizing controller intelligence and off-grid algorithm optimization. Shakti Pumps (India) Limited represents the scale-driven archetype, leveraging manufacturing depth across India's vast agricultural distributor network. These three exemplify how competitive positioning diverges between premium electronics integration and cost leadership through production scale.
| Leading Market Players |
|---|
| Shakti Pumps (India) Limited |
| Grundfos Holding A/S |
| LORENTZ GmbH |
| KSB SE & Co. KGaA |
| Franklin Electric |
| Xylem Inc. |
| Kirloskar Brothers Ltd. |
| Waaree Energies Ltd. |
| C.R.I. Pumps Private Limited |
| Others |
Value Chain & Pricing Dynamics
Polysilicon ingot and wafer production clusters in East Asian manufacturing zones concentrate margin capture upstream, forcing system integrators to compete on controller firmware and service attach rather than module arbitrage. This upstream concentration compresses hardware margins and redistributes value toward electronics manufacturing depth and captive distribution networks.
Pricing Analysis
Cost-plus contracts with polysilicon price indexation dominate module procurement, passing through input volatility to system assemblers. Pricing stratifies across premium, standard, and economy tiers based on controller intelligence depth and BIS certification status. Cost compression in standard-tier submersible configurations is intensifying because photovoltaic module deflation outpaces distribution network absorption. Smallholder farmers in Kenya and Ethiopia exhibit highest price sensitivity, while Indian cooperative procurement committees command volume leverage that compresses per-unit pricing.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from East Asian polysilicon suppliers have become critical liquidity tools for module distributors. Manufacturing draws from China, Vietnam, and Malaysia for cell and module assembly, with Germany and Japan supplying precision controller electronics. Raw material dependencies center on high-purity polysilicon, copper magnet wire, and rare-earth permanent magnets. Single-source vulnerability in MPPT controller firmware creates chokepoint risk. Distribution runs through state nodal agencies in India, agricultural extension networks in Kenya, and USDA-certified dealers in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service revenue pools from borehole retrieval contracts and predictive maintenance subscriptions are expanding faster than hardware shipments, reframing competitive advantage around field service density and firmware update recurring revenue.
For Market Incumbents: Pre-empt margin erosion from photovoltaic commoditization by backward integration into controller firmware development and captive borehole service infrastructure. Defend against emerging Chinese scale players by accelerating BIS certification timelines through direct standards body engagement. Prioritize vertical integration into permanent magnet synchronous motor production to capture efficiency-tier premium pricing. For New Entrants and Emerging Players: Build out pay-as-you-go financing infrastructure targeting Kenya's Rift Valley smallholder clusters where distributor penetration remains shallow. Capture white space in wind-solar hybrid configurations for Tamil Nadu and Gujarat irrigation cooperatives with complementary seasonal generation profiles. Lead with agronomic advisory service bundling to differentiate beyond hardware specifications. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale assemblers with captive controller production and established state nodal agency relationships across India's PM-KUSUM scheme. Long-term viability hinges on service revenue attach rates exceeding hardware margin compression. Monitor BIS certification queue lengths as an inflection indicator for seasonal installation capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Firmware Backward Integration | Captures margin migrating from commoditized photovoltaic modules toward MPPT algorithm intelligence. |
| State Nodal Agency Partnership | Secures preferential subsidy program access under India's PM-KUSUM scheme across Maharashtra and Gujarat. |
| Pay-as-you-Go Financing Infrastructure | Unlocks Kenya's Rift Valley smallholder demand through mobile-money repayment and agronomic advisory bundling. |
| Permanent Magnet Motor Transition | Addresses EU F-Gas Regulation efficiency mandates while compressing energy consumption per cubic meter lifted. |
| Borehole Service Captive Buildout | Creates recurring revenue from retrieval contracts and predictive maintenance in deep aquifer zones. |
Study Parameters
Desk research of customs trade databases, state renewable energy agency procurement records, and BIS certification registries preceded structured interviews with system integrator procurement heads, agricultural cooperative committee members, borehole drilling contractors, and controller firmware engineers. Primary fieldwork across Maharashtra, Gujarat, and Karnataka validated secondary estimates of PM-KUSUM scheme deployment velocity. Bottom-up unit economics modeling triangulated against top-down subsidy allocation forecasts.
Assumptions held photovoltaic module cost deflation, PLI scheme domestic content requirements, and groundwater extraction regulatory caps fixed across the analysis window, while varying monsoon timing, cooperative procurement consolidation rates, and BIS certification processing speeds. Segmentation dimensions modeled include pump architecture, application intensity, technology conversion type, and end-user procurement authority structure. CAGRs derived from polynomial trend fitting against historical subsidy disbursement curves and insolation-adjusted utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese module suppliers into controller assembly would shift outcomes substantially. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Grease Pump Market