
 Power Battery Sealant Market | 2026-2036
Power Battery Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Power Battery Sealant Market Insights
Multi-sourced procurement of specialty chemical inputs is recalibrating competitive dynamics across the power battery sealant supply base. Henkel AG & Co. KGaA leverages its adhesive technology portfolio to anchor European EV battery contracts. Dow Inc. competes through silicone-based formulations optimized for thermal cycling endurance. Momentive Performance Materials specializes in high-purity silicone systems for premium automotive platforms.
Power battery sealant encompasses elastomeric and thermosetting compounds engineered to prevent electrolyte leakage, suppress thermal propagation, and maintain dielectric integrity across temperature ranges exceeding 150°C, typically formulated from silicone, polyurethane, or epoxy chemistries with filler loadings between 30% and 70% by weight. Silicone-based formulations occupy the dominant position in electric vehicle applications due to their flame-retardant properties and wide operational temperature window. Automotive Batteries represents the fastest-expanding application segment as OEMs redesign pack architectures around cell-to-pack integration, while epoxy-based systems retain margin concentration in industrial stationary storage where long service life outweighs material cost premiums.
China's NMPA enforces GB standards for battery thermal safety that directly dictate sealant flame-retardancy thresholds and testing protocols. The EU Battery Regulation and REACH compliance frameworks restrict hazardous substance content in sealant chemistries, reshaping formulation R&D priorities for suppliers seeking European market access. Stakeholders must monitor evolving certification requirements across multiple jurisdictions to align product development with diverging regional safety mandates.
Market Dynamics
Cell-to-pack battery architectures are compressing module-level sealant volumes while elevating thermal runaway protection requirements, forcing suppliers to reformulate for single-component structural bonding.
Growth Catalysts
- EU Battery Regulation:Mandatory carbon footprint declarations and recycled content thresholds are compelling sealant suppliers to certify bio-based silicone feedstocks for European EV qualification.
- Automotive OEMs:Cell-to-pack integration eliminates module housings, concentrating sealant demand into high-performance thermal interface materials at the pack enclosure level.
- Silicone chemistry advances:Two-part addition-cure systems with 5-minute gel times are enabling automated dispensing lines to match gigafactory cycle rates.
Market Restraints
- Silicone raw material concentration:Precursor supply clusters in China's Jiangsu and Zhejiang provinces, exposing non-Chinese formulators to feedstock disruption risks.
- REACH authorization costs:ECHA scrutiny of tin-based catalysts is forcing reformulation investments that compress margins for mid-tier European suppliers.
- Curing speed limitations:Epoxy systems require 4-6 hour cure cycles incompatible with automotive takt times, restricting them to stationary storage applications.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting sealant suppliers to establish localized compounding operations.
- Solid-state battery platforms:Sulfide electrolyte chemistries demand hermetic sealing against moisture ingress, opening premium formulation contracts with next-generation cell developers.
- Direct-to-gigafactory technical service:On-site application engineering support is displacing traditional distributor channels for high-volume automotive contracts.
Industry Challenges
- Thermal propagation testing certification:GB 38031 and UN 38.3 test protocols require 6-12 month validation cycles that delay new product commercialization.
- Application robotics integration:Sealant dispensing systems must synchronize with battery pack assembly lines running sub-60-second cycle times, demanding co-development investments with automation vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Battery Sealant Market |
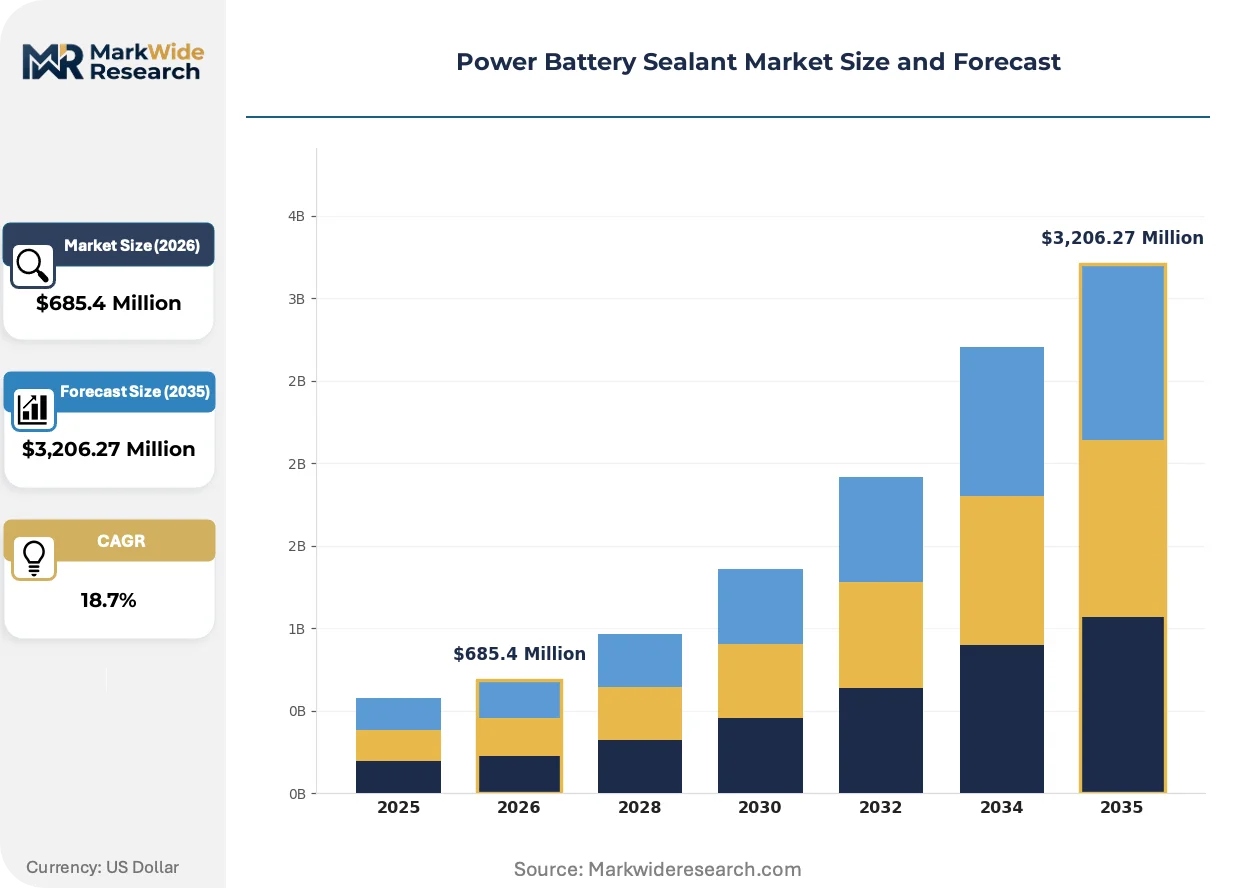
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Sealing Compounds, Adhesives, Gaskets, Sealant Tapes Application Type: Automotive Batteries, Consumer Electronics, Industrial Batteries, Renewable Energy Storage Formulation Type: Silicone-based, Polyurethane-based, Epoxy-based, Acrylic-based Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Dow Inc., Sika AG, H.B. Fuller Company, Wacker Chemie AG, Momentive Performance Materials, DuPont de Nemours, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Battery Sealant Market Trends and Innovations
Thermal management priorities are overriding legacy mechanical sealing specifications, compressing the performance gap between commodity and specialty formulations while elevating flame-retardancy testing protocols.
Additive-cured silicone systems with integrated phase-change fillers are rewriting thermal interface design rules for cell-to-pack architectures. EV manufacturers in Germany and China are specifying these materials for direct cell bonding applications. The technology is compressing the supplier base by disqualifying formulators lacking high-purity filler processing capabilities.
REACH restriction proposals targeting organotin catalysts are forcing reformulation roadmaps across European sealant operations. Suppliers must validate alternative platinum-based cure systems without compromising pot life or adhesion profiles. Automotive battery pack assemblers in Hungary and Poland are demanding pre-certified alternatives to de-risk their supply agreements.
Buyer consolidation around tier-one battery manufacturers is concentrating procurement leverage with CATL, BYD, and LG Energy Solution. Long-term offtake agreements with minimum volume guarantees are displacing spot purchasing for automotive-grade sealants. This pattern is most pronounced in China's Yangtze River Delta battery manufacturing corridor.
Power Battery Sealant Market Segmentation
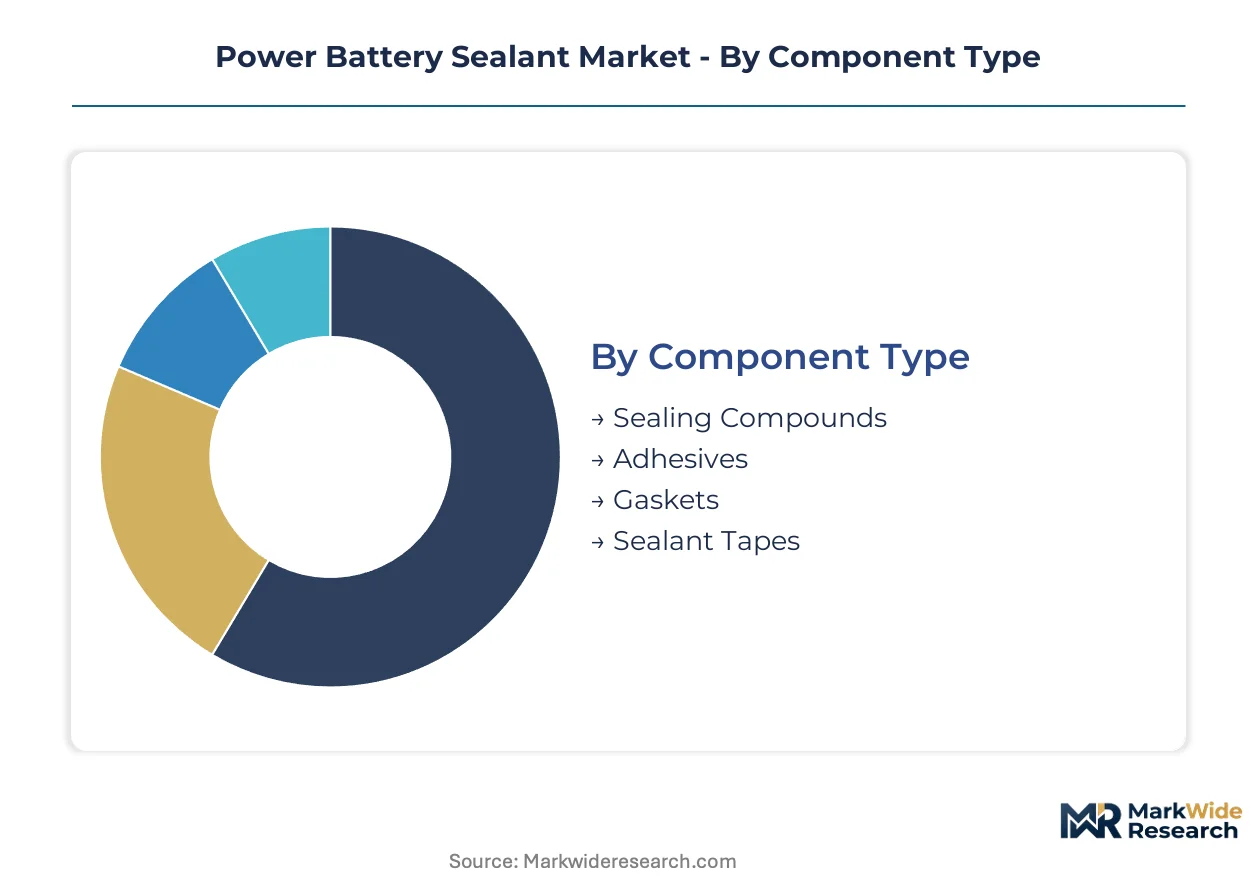
Power battery sealant procurement patterns diverge sharply across formulation chemistries and end-use specifications. Component selection directly determines compliance with thermal runaway protocols and automated dispensing compatibility.
Component Type:
Supply concentration among specialty chemical formulators favors integrated adhesive-sealant portfolios over single-product suppliers.
- Sealing Compounds:Elastomeric formulations with 30-70% mineral filler loading dominate cell-to-pack enclosure sealing. CATL and BYD specify these materials for direct battery housing applications where flame-retardancy ratings must exceed UL 94 V-0.
- Adhesives:Two-part addition-cure silicones with sub-5-minute gel times enable automated dispensing at gigafactory cycle rates. LG Energy Solution and SK On procurement contracts favor suppliers with on-site technical service capabilities in Poland and Hungary.
- Gaskets:Pre-cured silicone profiles compress to form redundant sealing barriers in module-to-pack transitions. Stationary storage installers in Germany specify these for maintenance-accessible joints.
- Sealant Tapes:Pressure-sensitive adhesive-backed foams provide temporary fixturing during pack assembly. Consumer electronics battery manufacturers in Japan utilize these for rapid prototyping workflows.
Today's leader: Sealing Compounds. Tomorrow's challenger: Adhesives.
Application Type:
End-use volume distribution concentrates in automotive platforms, though margin profiles favor industrial stationary storage.
- Automotive Batteries:Cell-to-pack architectures eliminate module housings, compressing sealant volumes while elevating thermal interface material specifications. Tesla's 4680 cell production in Texas and Nevada drives demand for single-component structural bonding systems.
- Industrial Batteries:Long service life requirements justify epoxy-based formulations despite 4-6 hour cure cycles. Data center operators in Virginia and Frankfurt specify these for 20-year operational horizons.
- Consumer Electronics:Miniaturization demands ultra-thin sealant tapes with dielectric integrity below 1mm thickness. Smartphone manufacturers in South Korea and Taiwan drive specification tightening.
- Renewable Energy Storage:Utility-scale installations in California and Gujarat specify fire-resistant silicone systems for outdoor enclosure sealing. Grid interconnection standards mandate 25-year weathering resistance.
Automotive Batteries command current procurement volumes. Renewable Energy Storage presents the steepest expansion trajectory.
Formulation Type:
Raw material precursor geography in China's Jiangsu and Zhejiang provinces shapes competitive access to silicone-based systems.
- Silicone-based:Addition-cure systems with platinum catalysts deliver flame-retardancy and -60°C to 200°C operational windows. European REACH restrictions on organotin catalysts accelerate platinum-based formulation adoption.
- Epoxy-based:Rigid thermosetting systems with excellent dielectric strength serve stationary storage where thermal cycling demands are moderate. Industrial battery assemblers in the US Midwest favor these for cost-sensitive utility contracts.
- Polyurethane-based:Moisture-cure systems offer processing flexibility at ambient temperatures. Secondary automotive suppliers in Mexico utilize these for retrofit and repair applications.
- Acrylic-based:UV-cure formulations enable rapid processing for consumer electronics micro-battery sealing. Electronics contract manufacturers in Shenzhen specify these for high-mix, low-volume production.
Silicone-based formulations anchor automotive qualification. Epoxy-based systems defend industrial margins.
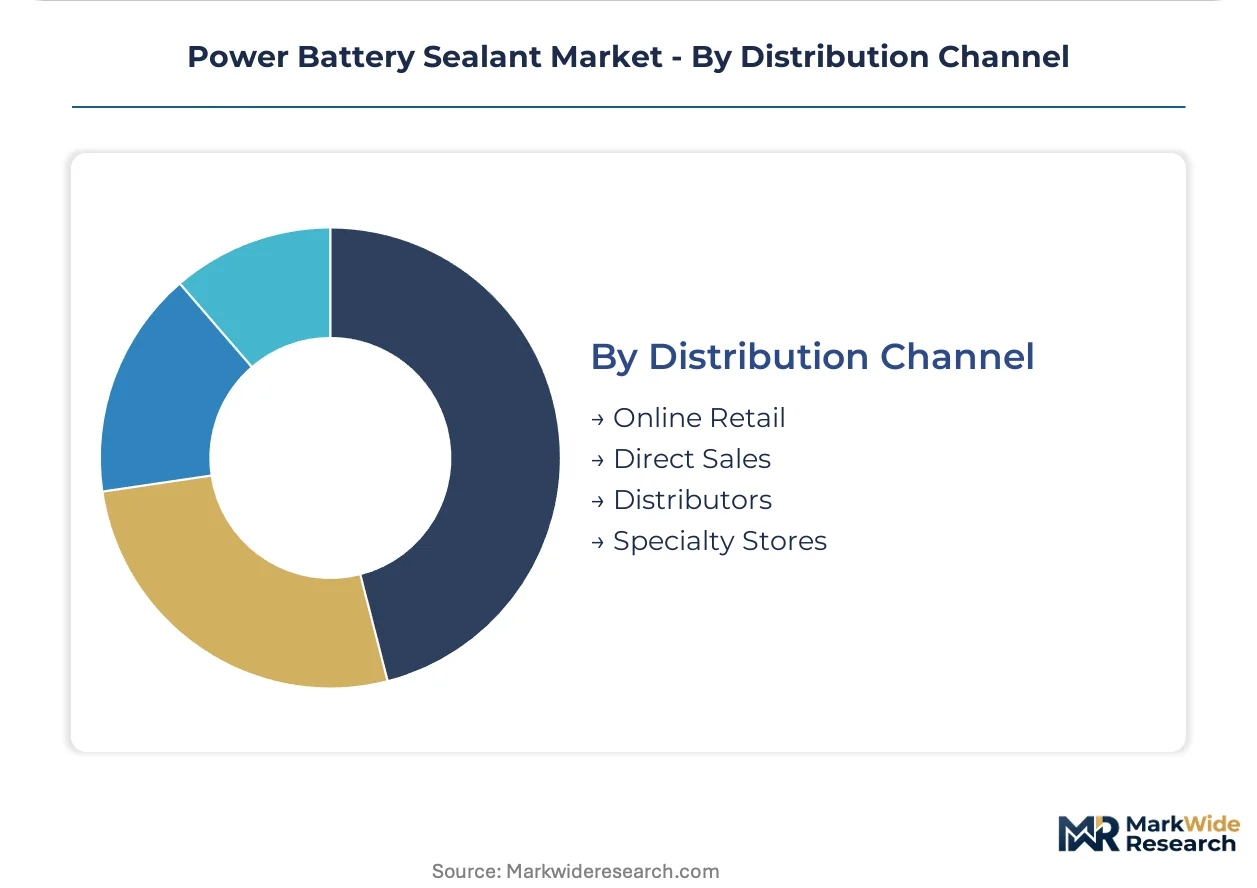
Distribution Channel:
High-volume automotive contracts displace traditional distributor relationships with direct technical partnerships.
- Direct Sales:Long-term offtake agreements with minimum volume guarantees dominate CATL, BYD, and LG Energy Solution procurement. On-site application engineering support is mandatory for qualification.
- Distributors:Regional chemical distributors serve mid-tier battery assemblers and aftermarket repair operations. Inventory stocking agreements in Rotterdam and Singapore support just-in-time delivery.
- Online Retail:E-commerce platforms capture small-lot orders from research institutions and prototype developers. Technical datasheets and SDS accessibility drive platform selection.
- Specialty Stores:Localized outlets serve maintenance, repair, and overhaul operations for industrial battery fleets. Forklift battery service providers in Germany rely on these for same-day availability.
Direct Sales captures automotive volume. Distributors retain aftermarket relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors procurement concentration for power battery sealant systems, with gigafactory clusters in Changzhou and Ningbo driving formulation demand. Cell-to-pack integration mandates from CATL and BYD are reshaping material specifications across China's EV manufacturing corridor.
China
NMPA's GB 38031 thermal safety protocols enforce flame-retardancy thresholds that dictate sealant qualification timelines. The MIIT's dual carbon goals accelerate demand for bio-based silicone feedstocks in Ningbo and Changzhou gigafactories. Jiangsu and Zhejiang provinces concentrate precursor supply, exposing formulators to geographic concentration risks.
Germany
ECHA's REACH restrictions on organotin catalysts force platinum-based reformulation investments from sealant suppliers seeking automotive qualification. The EU Battery Regulation's carbon footprint declarations compel bio-based feedstock certification for European EV contracts. Hungarian and Polish battery assembly plants demand pre-certified alternatives to de-risk supply agreements.
United States
IRA production tax credits for domestic battery manufacturing attract sealant suppliers to establish localized compounding near Tesla's Texas and Nevada operations. NHTSA safety standards and EPA environmental compliance frame material selection for automotive applications. Virginia data center operators specify epoxy systems for 20-year stationary storage installations.
South Korea
METI-aligned battery safety standards through KATS influence sealant flame-retardancy specifications for LG Energy Solution and SK On procurement. The Seoul Capital Area's R&D concentration drives specification tightening for ultra-thin dielectric tapes in consumer electronics. Busan-Ulsan industrial corridors host automated dispensing line integration for gigafactory cycle rates.
India
BIS certification requirements for battery thermal safety create compliance barriers for imported sealant formulations. The PLI scheme for advanced chemistry cell manufacturing attracts suppliers to establish localized compounding in Gujarat and Tamil Nadu. Maharashtra's emerging EV manufacturing clusters specify silicone-based systems for cell-to-pack enclosure sealing.
Power Battery Sealant Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state battery sealing and automated dispensing integration. The supplier base concentrates around integrated adhesive-sealant portfolios rather than single-product specialists. Three archetypes dominate: diversified chemical conglomerates with automotive qualification history, silicone-focused formulators with high-purity processing capabilities, and regional compounders serving aftermarket repair channels. Competitive moves center on direct-to-gigafactory technical partnerships and backward integration into silicone precursor supply.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Dow Inc. exemplify portfolio breadth across automotive adhesive-sealant systems. Momentive Performance Materials occupies a position within the high-purity silicone specialist tier. These three entities represent distinct competitive positioning vectors: European automotive contract anchoring, North American materials science integration, and premium formulation specialization for thermal management applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Dow Inc. |
| Sika AG |
| H.B. Fuller Company |
| Wacker Chemie AG |
| Momentive Performance Materials |
| DuPont de Nemours |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Formulation chemist concentrations in Germany's Ruhr Valley and China's Jiangsu province create labor-cost differentials that widen pricing spreads between premium automotive-grade sealants and economy-tier industrial formulations. These geographic skill clusters enable European suppliers to command certification premiums while Asian compounders capture volume through automated production.
Pricing Analysis
Silicone precursor cost pass-through dominates pricing structures, with platinum-catalyzed formulations commanding premiums over tin-catalyzed alternatives amid REACH-driven reformulation. Price differentiation rests on UL 94 V-0 certification tier and volume scale, with automotive OEMs least sensitive and aftermarket repair channels most sensitive. Pricing pressure intensifies as CATL and BYD consolidate procurement leverage through minimum-volume offtake agreements.
Supply Chain Analysis
GB 38031 and UN 38.3 certification gating restricts qualified suppliers to those with 6-12 month validation capabilities, concentrating supply among established formulators. Geographic supply clusters in China, Germany, and South Korea anchor silicone precursor access, with raw material dependencies on methyl chlorosilane, platinum catalysts, and high-purity mineral fillers. Single-source vulnerability runs through Jiangsu and Zhejiang precursor plants. Distribution runs through direct technical partnerships for automotive volume and regional distributors for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power battery sealant market functions as a stable compounder, with regulatory-mandated thermal safety upgrades ensuring persistent demand for qualified formulations regardless of EV sales volatility.
For Market Incumbents: Hedge against organotin catalyst obsolescence by accelerating platinum-based reformulation roadmaps ahead of ECHA restriction timelines. Secure backward integration into silicone precursor supply through joint ventures in Zhejiang or captive processing agreements. Defend automotive qualification positions by embedding on-site technical service teams at gigafactory locations in Hungary and Poland.
For New Entrants and Emerging Players: Launch via specialty distributor partnerships targeting India's PLI-subsidized battery manufacturing clusters in Gujarat and Tamil Nadu. Solid-state battery sealing for sulfide electrolyte platforms presents the most penetrable white-space segment. Pursue direct-to-gigafactory technical service contracts as the primary go-to-market angle, bypassing traditional distributor channels.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with automotive adhesive portfolios are the most active acquirers in this space, seeking high-purity silicone processing capabilities. The market exhibits long-term viability through the 5-10 year window as cell-to-pack architectures elevate thermal interface material specifications. Watch solid-state battery platform announcements as the critical inflection signal for premium formulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursor Supply | Secures feedstock access against Jiangsu and Zhejiang concentration risks for European formulators. |
| Platinum-Based Reformulation Investment | Pre-certifies alternatives ahead of ECHA organotin restrictions for Hungarian and Polish battery plants. |
| Direct-to-Gigafactory Technical Service Deployment | Displaces distributor channels for CATL and LG Energy Solution procurement contracts. |
| Solid-State Battery Sealing Development | Captures premium formulation contracts with next-generation sulfide electrolyte cell developers. |
| India PLI Localization | Establishes compounding operations in Gujarat to serve advanced chemistry cell manufacturing incentives. |
Research Methodology
Direct dialogue with sealant formulation chemists, automotive battery pack procurement leads, gigafactory operations managers, and ECHA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from NMPA GB standard filings, ECHA restriction proposals, customs trade data for silicone precursor flows, and SEC disclosures from diversified chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry, application segment, and regional production cluster dimensions.
Segment-level projections across silicone, epoxy, polyurethane, and acrylic chemistries combined with automotive, industrial, consumer electronics, and renewable energy storage end-use splits produced volume and value outputs. CAGRs derived from regression analysis of historical EV battery production growth rates, regulatory implementation timelines, and cell-to-pack architecture adoption curves. Key inputs included gigafactory capacity announcements, thermal propagation testing certification queues, and REACH reformulation investment disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden NMPA protocol revisions or Jiangsu precursor supply disruptions. Projections reflect assumptions on EV penetration rates, regulatory harmonization trajectories, and solid-state battery commercialization timing. A model refresh is warranted upon material change in EU Battery Regulation carbon footprint declaration enforcement or solid-state platform production scale announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Breathing Battery Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Lead Acid Battery Market
Batteries
Watch Battery Market
Batteries
Rear Rack Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
N-Type Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Utility Battery Market
Batteries
Power Tool Batteries Market
Batteries
Battery Maintainer Market
Batteries
Marine Low-Voltage Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Li-Mno2 Button Battery Market
Batteries
India Lead-Acid Battery Market