
 Global Mobile Hydraulic Pump Market | 2026-2036
Global Mobile Hydraulic Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Hydraulic Pump Market Foresight
The EU F-Gas Regulation is restructuring capital allocation across European pump suppliers by mandating lower-global-warming-potential refrigerants in climate-controlled operator cabs, which indirectly tightens hydraulic system thermal management requirements. Danfoss leverages its integrated electro-hydraulic portfolio to preempt compliance costs in German construction OEM supply chains. Kawasaki Precision Machinery anchors high-pressure piston pump production for Japanese excavator manufacturers with exacting durability standards. Bosch Rexroth dominates aftermarket distribution density through authorized service networks spanning North American mining corridors.
A mobile hydraulic pump converts mechanical rotational energy into pressurized fluid flow to transmit power in off-highway equipment, typically operating at pressures from 250 to 700 bar with displacement volumes calibrated to engine torque curves and load cycle profiles. Its primary purpose is to enable precise force modulation for boom articulation, drivetrain propulsion, and implement control in vehicles where electrical actuation lacks sufficient power density. Piston pumps command the dominant margin pool in high-pressure construction and mining applications where volumetric efficiency above ninety percent justifies unit premium positioning. Gear pumps sustain volume leadership in agricultural machinery where cost-per-unit sensitivity and moderate pressure requirements predominate. Electro-hydraulic technology is displacing conventional load-sensing architectures in material handling equipment as fleet operators prioritize fuel telemetry integration.
The EPA Tier 4 Final framework and the EU Green Deal's embedded carbon reporting through CSRD are tightening design verification protocols for hydraulic components sold into regulated markets. Japan's METI energy efficiency standards for construction machinery create parallel compliance obligations for pumps deployed in Komatsu and Hitachi OEM configurations. China's GB standards on non-road mobile machinery emissions, administered by MEE, are extending comparable technical barriers for suppliers accessing domestic excavator production. Stakeholders must monitor divergence between regional efficiency test cycles to avoid engineering redundant product variants that fragment scale economics.
Market Dynamics
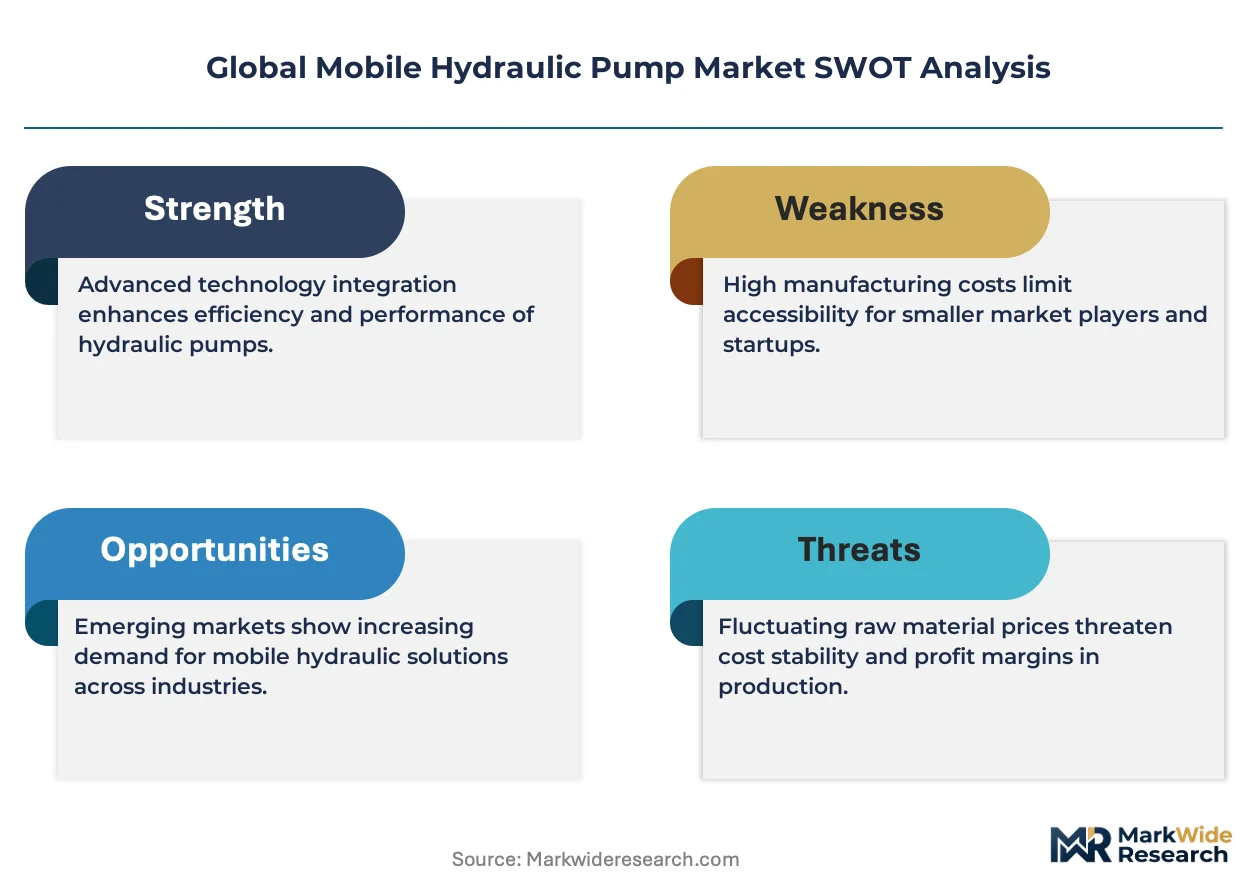
Electro-hydraulic architectures are compressing the addressable market for conventional load-sensing pumps as construction OEMs redesign powertrains around fuel telemetry integration and regenerative energy recovery systems.
Growth Catalysts
- EPA Tier 4 Final compliance:Diesel particulate filters and selective catalytic reduction systems demand higher-efficiency hydraulic circuits to preserve engine power density in excavator fleets.
- Japanese excavator replacement cycle:Komatsu and Hitachi OEMs are refreshing high-pressure piston pump specifications for 20-ton-class machines ahead of METI energy efficiency deadlines.
- German precision manufacturing clusters:Stuttgart and Munich industrial corridors concentrate variable displacement pump R&D alongside automotive-tier supplier ecosystems.
Market Restraints
- Specialized alloy supply concentration:High-purity steel forgings for piston pump barrels source predominantly from Austrian and Swedish specialty mills, creating input cost volatility.
- Electrification substitution:Battery-electric construction prototypes in Nordic markets eliminate hydraulic powertrains entirely for sub-10-ton equipment classes.
- EU F-Gas Regulation thermal constraints:Lower-GWP refrigerants in climate-controlled cabs reduce hydraulic oil cooling capacity, forcing pump redesign cycles.
Strategic Opportunities
- Indian agricultural mechanization:Tractor OEMs in Punjab and Haryana are upgrading from manual implements to hydraulic hitch systems, opening gear pump volume.
- Electro-hydraulic convergence:Integration of servo-controlled variable pumps with CAN-bus telemetry enables predictive maintenance contracts for rental fleet operators.
- CSRD embedded carbon reporting:EU construction equipment lessors now require pump suppliers to disclose Scope 3 emissions, creating first-mover advantage for certified low-carbon production.
Industry Challenges
- Hydraulics-electronics integration expertise:OEM engineering teams lack embedded software competency for electro-hydraulic control algorithm development.
- Regional certification divergence:Parallel EPA, METI, and GB standard test cycles force redundant validation protocols without mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Hydraulic Pump Market |
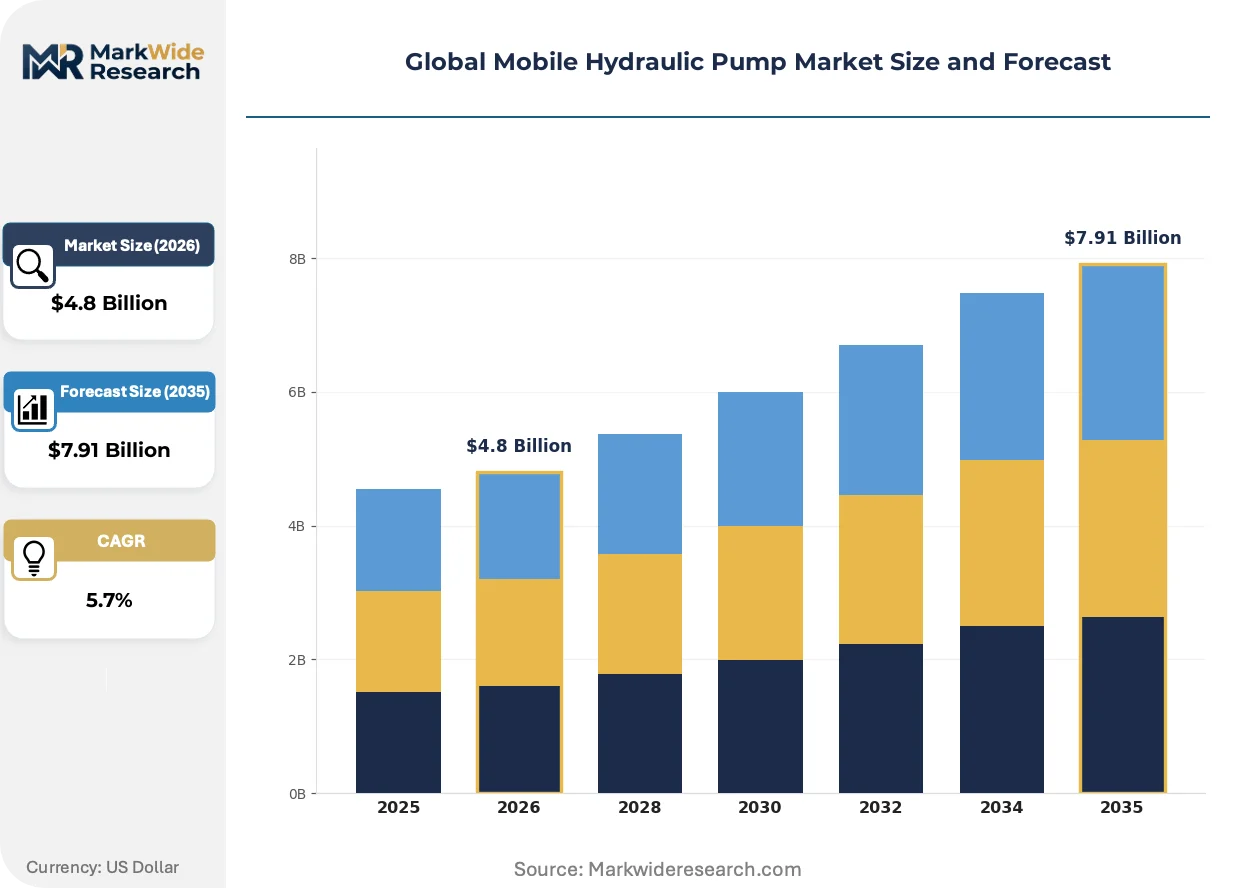
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Pumps, Gear Pumps, Vane Pumps, Axial Pumps, Radial Pumps Technology: Variable Displacement, Fixed Displacement, Electro-Hydraulic, Load-Sensing, Pressure Compensated Application: Construction Equipment, Agricultural Machinery, Material Handling Equipment, Mining Machinery, Forestry Equipment End User: OEMs, Aftermarket Suppliers, Equipment Rental Services, Fleet Operators, Maintenance Providers |
| Companies Covered | Danfoss, Kawasaki Precision Machinery, Parker Hannifin, Linde Hydraulics, Bucher Hydraulics, Eaton, Bondioli & Pavesi, Continental Hydraulics, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Hydraulic Pump Market Shifts & Advancements
Digital pump controls and closed-loop electro-hydraulic systems are collapsing the traditional separation between power generation and motion control in off-highway equipment architectures.
Electro-hydraulic pump systems is automating load-sensing functions previously managed by mechanical compensators. Mining truck OEMs in Western Australia are specifying these architectures for autonomous haulage fleets where remote diagnostic capability overrides upfront cost premiums. The technology is automating operator skill requirements while compressing aftermarket service revenue for conventional pump rebuilders.
EU F-Gas Regulation refrigerant phase-down is tightening thermal management specifications for hydraulic circuits in climate-controlled construction equipment. Pump suppliers must now validate performance across wider oil temperature ranges to maintain volumetric efficiency. German excavator manufacturers are responding with dual-circuit cooling architectures that segregate powertrain and cab thermal loads.
Fleet telemetry integration is reshaping procurement specifications for hydraulic components. Construction equipment lessors in the United States now require ISO-standardized CAN-bus data outputs from all pump-mounted sensors, replacing proprietary analog interfaces. This standardization enables cross-brand fleet management platforms that aggregate fuel consumption and duty cycle data across mixed OEM populations.
Global Mobile Hydraulic Pump Market Segmentation
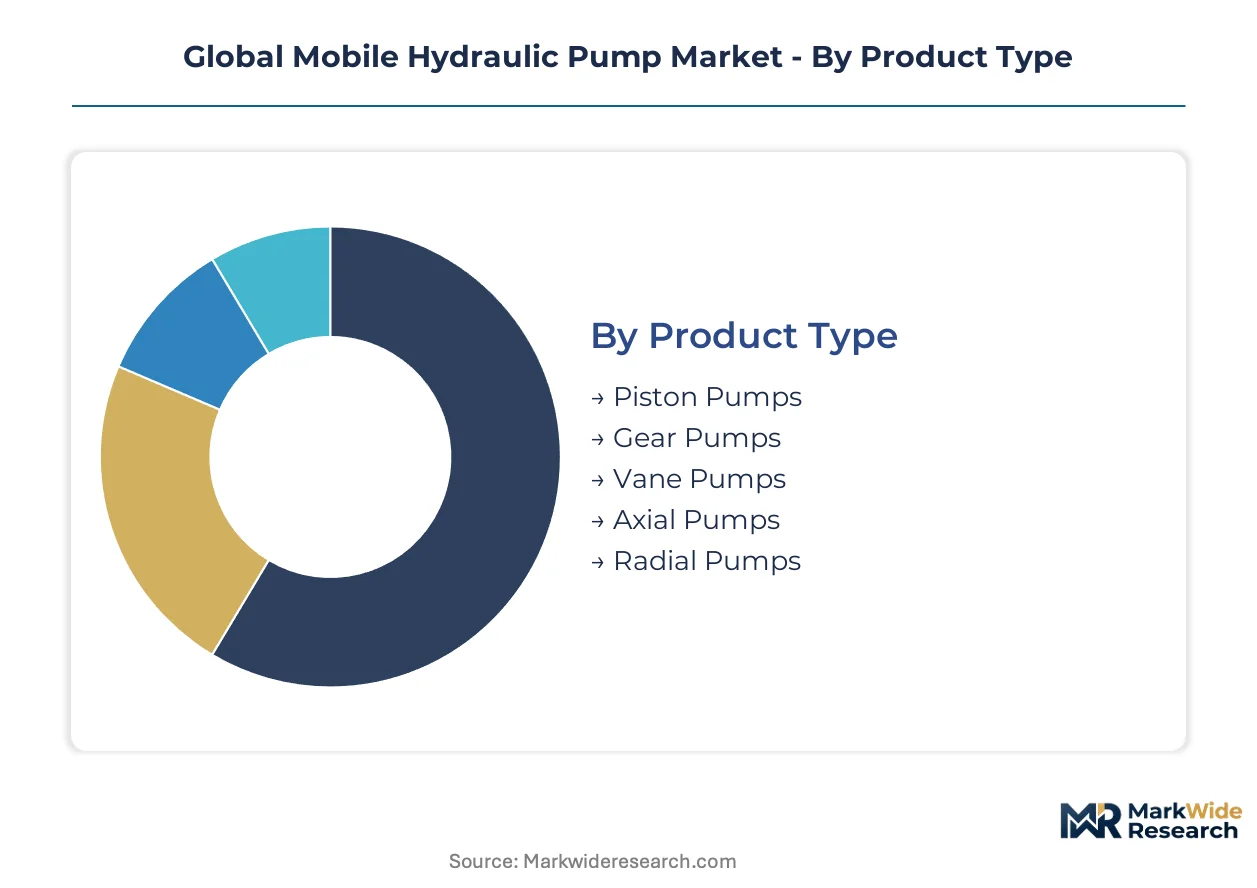
Mobile hydraulic pump procurement patterns diverge sharply across equipment categories, with construction OEMs prioritizing volumetric efficiency above ninety percent while agricultural buyers optimize for cost-per-unit thresholds. Technology selection increasingly correlates with regulatory compliance obligations rather than pure performance metrics.
Product Type:
Purchasing decisions in this category track pressure requirements and duty cycle intensity, with high-barrel-forging specifications commanding premium positioning in mining and heavy construction fleets.
- Piston Pumps:High-pressure axial and radial piston configurations achieve volumetric efficiency exceeding ninety percent through precision-machined barrel-and-plunger assemblies. Demand concentrates in German and Japanese excavator manufacturing corridors where Komatsu and Hitachi OEMs specify exacting durability standards for 20-ton-class machines.
- Gear Pumps:External and internal gear architectures deliver moderate-pressure fluid transfer through meshing tooth profiles with simpler manufacturing tolerances than piston alternatives. Agricultural machinery OEMs in India's Punjab and Haryana states source these units for tractor hydraulic hitch systems where cost sensitivity dominates specification sheets.
- Vane Pumps:Sliding vane mechanisms within eccentric cam rings provide consistent flow at intermediate pressures for material handling equipment.
- Axial Pumps:Swashplate-controlled axial piston arrangements enable compact packaging for integrated powertrain modules in compact construction equipment.
- Radial Pumps:Multiple piston arrangements radiating from a central shaft deliver high torque density for wheel loader drivetrain applications.
Volume sits with gear pumps in agricultural replacement cycles; growth tilts toward piston pumps as mining fleet specifications tighten.
Technology:
Control architecture selection now determines fuel telemetry compatibility and regenerative energy recovery capability, reshaping R&D allocation across supplier engineering centers.
- Variable Displacement:Swashplate angle modulation matches pump output to instantaneous load demand, eliminating throttling losses in excavator boom circuits. Stuttgart and Munich industrial corridors concentrate development of these units where German construction OEMs integrate them with electro-hydraulic control systems for EPA Tier 4 Final compliance.
- Electro-Hydraulic:Servo-controlled variable pumps with CAN-bus telemetry outputs enable predictive maintenance contracts and autonomous equipment operation. Western Australian mining truck fleets specify these architectures for autonomous haulage systems where remote diagnostic capability overrides upfront cost premiums.
- Fixed Displacement:Constant output per revolution suits applications with steady load profiles and minimal speed variation requirements.
- Load-Sensing:Mechanical compensator systems maintain pressure differential across directional valves, now compressing in addressable market as electronic controls displace hydraulic intelligence.
- Pressure Compensated:Automatic flow reduction at maximum pressure settings protects downstream components in mixed-duty equipment.
Fixed displacement retains volume in cost-constrained agricultural segments; electro-hydraulic configurations are climbing the fastest as fleet telematics standardize.
Application:
Equipment category dictates pressure range, contamination tolerance, and thermal management requirements, with each vertical maintaining distinct supplier qualification protocols.
- Construction Equipment:Excavators, loaders, and dozers require pumps rated for 350-700 bar continuous operation with rapid response to joystick inputs. Japanese OEM replacement cycles for 20-ton excavators are refreshing specifications ahead of METI energy efficiency deadlines, concentrating demand in Komatsu and Hitachi supply chains.
- Mining Machinery:Haul trucks and hydraulic shovels demand extreme-duty components with barrel forgings sourced from Austrian and Swedish specialty steel mills.
- Agricultural Machinery:Tractors and implements prioritize reliability in dusty environments with moderate pressure requirements below 250 bar.
- Material Handling Equipment:Forklifts and telehandlers balance compact packaging with precise load positioning for warehouse and port operations.
- Forestry Equipment:Harvesters and forwarders require robust sealing against debris ingestion in remote operating environments.
Construction equipment holds the dominant revenue share; mining machinery is expanding most quickly as autonomous fleet deployment accelerates.
End User:
Procurement authority distribution varies by equipment age, with OEMs controlling specification for new machines and independent channels capturing wear-component replacement.
- OEMs:Original equipment manufacturers integrate pumps at assembly based on engine torque curves and hydraulic circuit simulations. North American construction equipment OEMs now require ISO-standardized CAN-bus data outputs from all pump-mounted sensors, replacing proprietary analog interfaces for cross-brand fleet management compatibility.
- Fleet Operators:Large rental and construction companies negotiate direct supply agreements for standardized maintenance protocols across mixed OEM populations.
- Aftermarket Suppliers:Independent distributors serve replacement demand through authorized and parallel import channels.
- Equipment Rental Services:Short-term asset owners prioritize rapid exchange programs over rebuild economics for hydraulic components.
- Maintenance Providers:Independent repair shops perform field service and component rebuilding for aged equipment outside warranty coverage.
Aftermarket channels handle the highest transaction volume; fleet operators are gaining procurement influence fastest as telematics enable usage-based component tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and Germany's Stuttgart industrial corridor concentrate mobile hydraulic pump manufacturing through tax-advantaged tooling investments and precision engineering clusters.
United States
Construction equipment OEMs in Illinois and Texas drive demand for high-pressure piston pumps as fleet replacement cycles accelerate. EPA Tier 4 Final emissions standards force hydraulic circuit redesigns to preserve engine power density. The Midwest industrial corridor around Chicago anchors aftermarket distribution networks serving North American mining corridors.
Germany
Variable displacement pump procurement dominates Stuttgart and Munich manufacturing clusters as construction OEMs integrate electro-hydraulic architectures. EU F-Gas Regulation mandates lower-GWP refrigerants in climate-controlled cabs, tightening thermal management requirements for hydraulic systems. Bavarian precision engineering ecosystems concentrate R&D for fuel telemetry-compatible pump controls.
Japan
Komatsu and Hitachi OEMs refresh specifications for 20-ton-class excavator pumps ahead of METI energy efficiency deadlines. The Nagoya-Tokyo industrial belt concentrates high-pressure piston production with exacting durability standards. Japanese steel forgings from specialty mills supply barrel components for mining machinery exports.
China
GB standards administered by MEE on non-road mobile machinery emissions extend technical barriers for domestic excavator production. The Yangtze River Delta special economic zones host pump assembly operations serving construction equipment OEMs. Sichuan-Chongqing manufacturing bases supply gear pumps for agricultural mechanization in western provinces.
India
Tractor OEMs in Punjab and Haryana upgrade from manual implements to hydraulic hitch systems, opening gear pump volume. The country's agricultural mechanization programs accelerate procurement of moderate-pressure pumps for smallholder farming equipment. Gujarat industrial corridors concentrate forging capacity for hydraulic component supply chains.
Global Mobile Hydraulic Pump Market Competitive Landscape
German producers anchor the premium-tier electro-hydraulic segment; Japanese specialists hold the high-pressure piston pump tier for excavator OEMs. The vendor base splits between consolidated multinational hydraulics divisions and mid-cap regional fabricators serving aftermarket channels. Three archetypes dominate: integrated motion-control conglomerates, precision-forging specialists, and electro-hydraulic convergence players. Competitive moves center on strategic partnerships for CAN-bus telemetry integration and selective capacity expansion in Indian agricultural corridors.
Within the integrated motion-control tier, Danfoss A/S and Bosch Rexroth AG exemplify electro-hydraulic portfolio breadth. Kawasaki Precision Machinery Co., Ltd. anchors Japanese-origin piston pump supply for construction OEMs with exacting durability requirements. These three entities represent distinct geographic and technological positioning without overlapping core specializations.
| Leading Market Players |
|---|
| Danfoss |
| Kawasaki Precision Machinery |
| Parker Hannifin |
| Linde Hydraulics |
| Bucher Hydraulics |
| Eaton |
| Bondioli & Pavesi |
| Continental Hydraulics |
| Bosch Rexroth |
| Others |
Supply & Pricing Matrix
Electro-hydraulic pump manufacturing is concentrating production in German and Japanese precision engineering clusters, simultaneously elevating R&D cost structures and compressing margin flexibility for tier-two suppliers. This technological transition tightens pricing power around barrel-forging quality tiers while fragmenting procurement options for construction OEMs seeking EPA Tier 4 Final compliance.
Pricing Analysis
Short lead-time premiums for high-pressure piston pumps command substantial markups over standard-delivery contracts, while spot inventory of gear pumps trades at discounts in agricultural replacement cycles. Three-tier pricing structure across premium electro-hydraulic, standard variable displacement, and economy fixed-displacement levels reflects certification grade and volumetric efficiency thresholds. Cost compression in gear pump tiers is intensifying because Indian tractor OEMs consolidate procurement around Punjab-based fabricators. Fleet operators exhibit lowest price sensitivity for electro-hydraulic configurations with CAN-bus telemetry, while independent aftermarket channels drive hardest bargaining on legacy load-sensing architectures.
Supply Chain Analysis
Freight cost volatility from Austrian and Swedish specialty steel mills to German and Japanese pump assembly corridors is amplifying input cost unpredictability for high-pressure barrel forgings. Supply concentrates in Germany, Japan, and China, with high-purity steel forgings drawing from European specialty metallurgy and precision machining equipment resting on German and Japanese capital goods exports. Single-source vulnerability around Austrian forging capacity for mining-grade piston barrels exposes suppliers to alloy price swings. Distribution runs through authorized OEM service networks in North American mining corridors and independent aftermarket channels serving aged equipment fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where Austrian and Swedish specialty steel forging capacity props pricing for high-pressure piston pump tiers, insulating incumbent margin structures from full competitive erosion.
For Market Incumbents: Deepen backward integration into high-purity steel forging supply through captive arrangements with Austrian specialty mills, insulating barrel production from alloy cost volatility. Expand electro-hydraulic R&D capacity in Stuttgart and Munich clusters to preempt EPA Tier 4 Final compliance redesign cycles. Lock in long-term supply agreements with Komatsu and Hitachi OEMs ahead of METI energy efficiency deadline refreshes for 20-ton excavator specifications. For New Entrants and Emerging Players: Enter via Indian agricultural mechanization corridors in Punjab and Haryana, where tractor hydraulic hitch upgrades create gear pump volume without entrenched incumbent relationships. Target moderate-pressure fixed-displacement segments where cost-per-unit sensitivity outweighs electro-hydraulic performance premiums. Pursue distribution partnerships with Gujarat-based forging houses to bypass European metallurgy bottlenecks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of electro-hydraulic convergence specialists with embedded software competency and CAN-bus telemetry integration. Long-term viability across the analysis window favors suppliers with demonstrated EPA, METI, and GB standard compliance rather than pure-play mechanical pump fabricators. Monitor divergence between regional efficiency test cycles as inflection signal for redundant validation cost burdens that fragment scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Forging | Captive Austrian steel supply secures barrel quality for mining-grade piston pumps. |
| Electro-Hydraulic Control System Development | CAN-bus telemetry integration enables predictive maintenance contracts with Western Australian mining fleets. |
| Indian Agricultural Corridor Expansion | Punjab and Haryana tractor OEM relationships open gear pump volume in mechanizing markets. |
| Multi-Regulatory Compliance Certification | Simultaneous EPA, METI, and GB validation eliminates redundant product variant engineering. |
| Aftermarket Service Network Density Buildout | Authorized distribution in North American mining corridors captures replacement cycle revenue. |
Research Methodology
Document review covered customs and trade data, SEC filings from listed hydraulics suppliers, and equipment OEM technical specifications, complemented by interviews with maintenance directors at construction fleet operators, procurement leads at Japanese excavator manufacturers, aftermarket service heads in North American mining corridors, and plant engineers at German precision manufacturing clusters. Secondary validation drew from EPA regulatory filings, METI energy efficiency standard documentation, and EU F-Gas Regulation implementation guidance. Bottom-up pump shipment data triangulated against top-down construction equipment production estimates across the analysis window.
Cross-referencing historical volume patterns with panel input from OEM procurement teams and fleet operator maintenance planners shaped the analytical framework. Segmentation dimensions modeled include pump architecture, control technology, equipment application, and regional regulatory cluster. CAGRs derived from equipment replacement cycle timing, emissions compliance deadline phasing, and agricultural mechanization program trajectories. Industry-specific forecast inputs incorporated excavator fleet refresh schedules and specialty steel forging capacity utilization.
Revisions become necessary when Austrian or Swedish specialty mill capacity constraints intensify, when battery-electric construction equipment penetration accelerates beyond current Nordic market prototypes, or when regional efficiency test cycles achieve mutual recognition eliminating redundant validation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Suction Pump Market