
 Hydraulic Dosing Pump Market | 2026-2036
Hydraulic Dosing Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Dosing Pump Market Intelligence
Asset-light leasing models for precision fluid-handling equipment is reconfiguring competitive entry barriers across the hydraulic dosing pump landscape. Grundfos leverages its service-network density to bundle predictive maintenance with rental contracts. Lewa GmbH anchors its position through backward integration into diaphragm materials and proprietary drive systems. IDEX Corporation competes via modular platform architectures that reduce lead times for chemical injection skids.
A hydraulic dosing pump is a positive-displacement device that transmits force from a hydraulic fluid to a process diaphragm or piston, achieving flow accuracies within one percent and discharge pressures exceeding 1,000 bar for critical chemical metering. Its primary commercial purpose is injecting exact volumes of reagents, coagulants, or additives into water, hydrocarbon, or process streams without contamination or leakage. Diaphragm pumps dominate municipal water treatment due to zero-emission sealing requirements and long maintenance intervals. Electro-hydraulic actuation is displacing mechanical alternatives in offshore chemical injection, where remote modularity reduces platform staffing. Piston pump configurations sustain margin pools in high-pressure polymer and pharmaceutical applications demanding pulsation-free delivery.
The EPA enforces maximum contaminant level compliance through certified metering accuracy, while the EU F-Gas Regulation pressures refrigerant and fluorochemical processors to adopt leak-proof dosing architectures. ISO 9001 and ATEX directives further segment market access by certifying manufacturers for hazardous-zone deployment. Stakeholders must monitor how carbon-border adjustment mechanisms and PFAS restriction timelines redirect capital from conventional chemical plants toward green hydrogen and carbon-capture facilities that require next-generation dosing precision.
Market Dynamics
Electro-hydraulic actuation architectures are compressing maintenance intervals and platform staffing requirements across offshore chemical injection operations, while tightening discharge standards in municipal water treatment force asset replacement cycles that favor precision metering over legacy mechanical systems.
Growth Catalysts
- EPA Clean Water Act enforcement:Maximum contaminant level mandates drive certified metering accuracy upgrades across US municipal utilities, accelerating diaphragm pump procurement for zero-emission sealing compliance.
- Green hydrogen electrolysis scaling:Precise caustic and acid dosing requirements in gigawatt-scale electrolyzer installations create demand for high-pressure hydraulic metering systems with pulsation-free delivery profiles.
- German chemical manufacturing clusters:Concentrated specialty chemical production around Ludwigshafen and Leverkusen sustains premium pump procurement for polymer and pharmaceutical applications demanding discharge pressures exceeding 1,000 bar.
Market Restraints
- Specialized alloy input volatility:Hastelloy and titanium diaphragm materials face price instability from concentrated mining operations, compressing margin pools for manufacturers without captive supply arrangements.
- EU F-Gas Regulation friction:Leak-proof dosing mandates for fluorochemical processors extend certification timelines and restrict market access for architectures failing ATEX hazardous-zone compliance.
- Peristaltic pump substitution:Lower-capital tubing-based systems capture share in low-pressure municipal applications where one-percent accuracy thresholds are not mandatory.
Strategic Opportunities
- Carbon-capture solvent dosing:Amine and chilled ammonia capture facilities require next-generation precision injection for corrosive chemical handling, opening white space in North American and Middle Eastern project pipelines.
- Asset-light leasing penetration:Predictive maintenance bundling through service-network density models reduces customer capex barriers and extends manufacturer revenue visibility across multi-year contracts.
- ISO 9001 quality mandate expansion:Third-party certification requirements in pharmaceutical and food additive processing create preference premiums for documented traceability and calibration protocols.
Industry Challenges
- Hydraulic fluid compatibility expertise:Specialized tribology knowledge for high-pressure seal design remains concentrated among aging engineering workforces, constraining workforce scaling for OEM service operations.
- Legacy SCADA integration complexity:Brownfield chemical plants require costly protocol bridging to connect electro-hydraulic actuation systems with established distributed control architectures.
- PFAS restriction timeline uncertainty:Evolving fluoropolymer bans threaten diaphragm material supply chains while replacement elastomer validation cycles extend product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Dosing Pump Market |
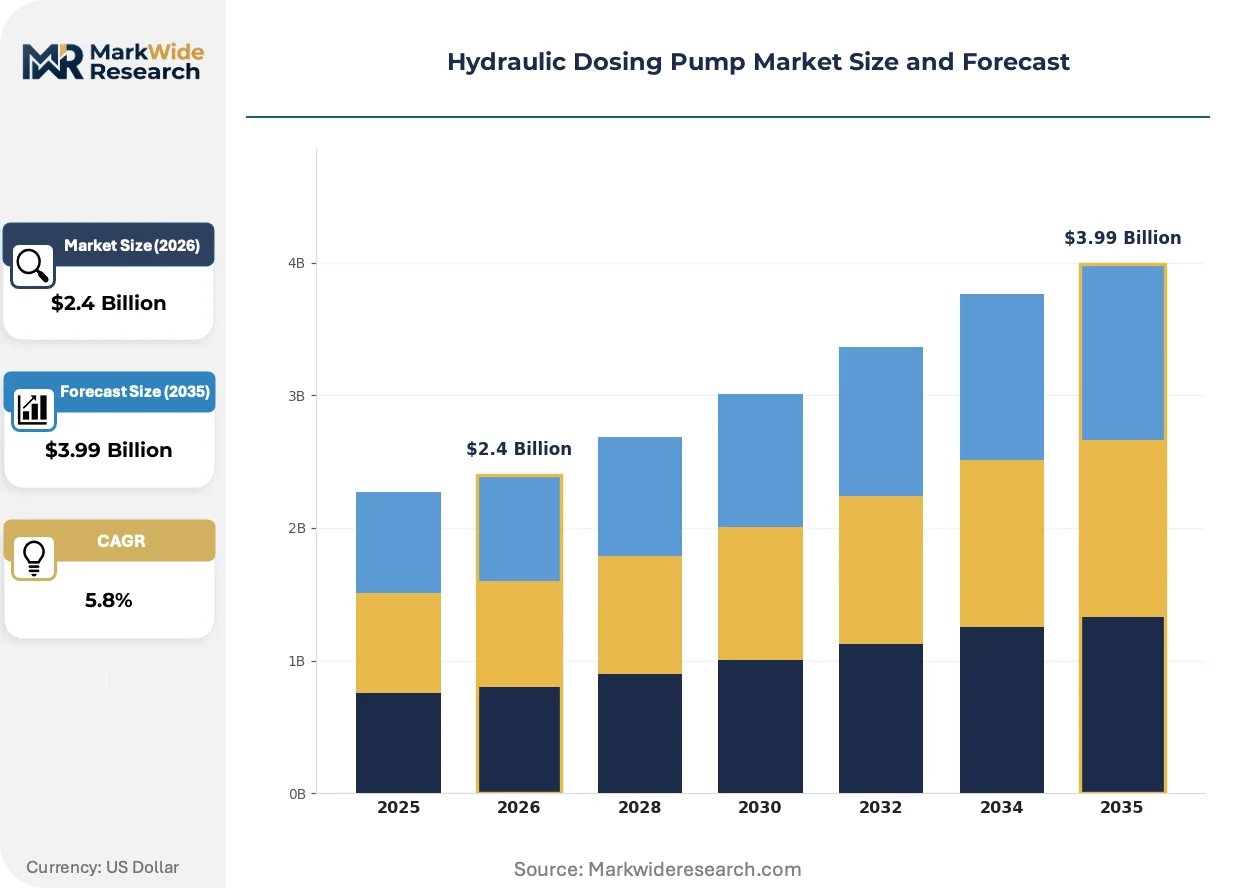
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Piston Pumps, Plunger Pumps, Rotary Pumps Technology: Mechanical Actuation, Electro-Hydraulic, Pneumatic-Hydraulic, Manual Control Application: Water Treatment, Chemical Injection, Food & Beverage Processing, Agriculture Irrigation End User: Municipal Facilities, Chemical Manufacturers, Food Processing Plants, Crop Farms |
| Companies Covered | Dover Corporation, Milton Roy, Grundfos, Nikkiso Co., Ltd., Seko S.p.A., ProMinent GmbH, Lewa GmbH, SPX FLOW, IDEX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Dosing Pump Market Strategic Shifts & Innovations
Digital telemetry architectures and predictive algorithms are embedding intelligence directly into hydraulic dosing systems, compressing the traditional separation between mechanical metering and process control layers while enabling remote diagnostic capabilities.
Electro-hydraulic actuation is digitizing offshore chemical injection operations by replacing mechanical linkage systems with servo-controlled pressure modulation. North Sea and Gulf of Mexico platform operators are adopting these architectures to eliminate manual stroke adjustment visits. This convergence is digitizing staffing models while reducing helicopter transport costs for unmanned platform configurations.
The EU F-Gas Regulation is tightening leak-proof requirements for refrigerant and fluorochemical processors, mandating double-diaphragm monitoring and secondary containment architectures. German and French chemical manufacturers are retrofitting existing skids to comply with phased containment standards. High-pressure polymer applications face the steepest compliance costs, driving preference for manufacturers with in-house diaphragm material capabilities.
Service unbundling is fragmenting traditional pump procurement patterns as municipal utilities separate capital equipment acquisition from long-term maintenance obligations. US water treatment districts are adopting performance-based contracts that transfer uptime risk to OEM service networks. This reconfiguration is most visible in California and Texas markets where staff attrition has eroded in-house hydraulic maintenance expertise.
Hydraulic Dosing Pump Market Segmentation
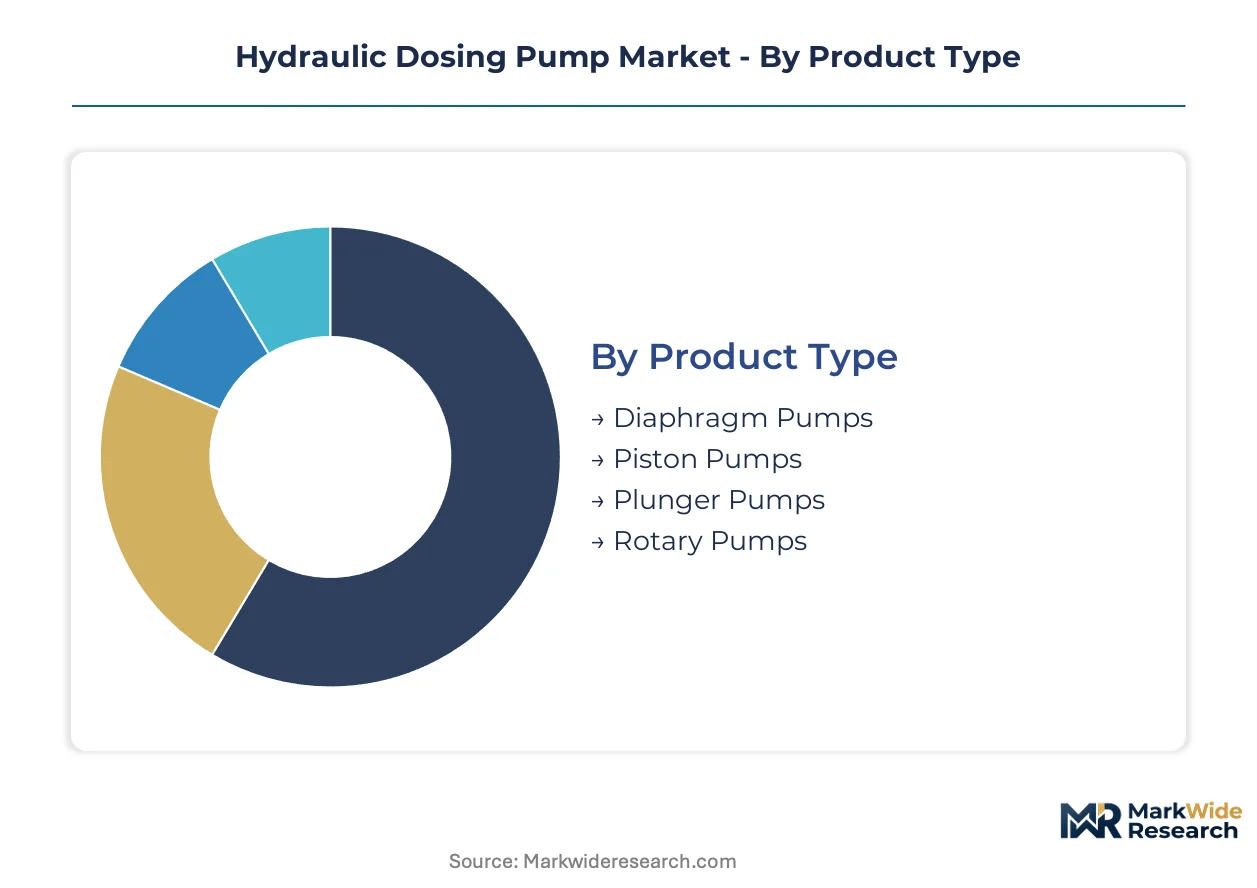
Hydraulic dosing pump procurement patterns diverge sharply across pressure requirements, automation sophistication, and regulatory exposure. Understanding these segment boundaries clarifies why diaphragm architectures command municipal premiums while piston systems sustain industrial margins.
Product Type:
Use-case spectrum spans zero-emission sealing mandates at municipal utilities through ultra-high-pressure polymer processing.
- Diaphragm Pumps:These positive-displacement units isolate process fluid from hydraulic oil through elastomer or PTFE membranes, achieving leak-free operation critical for EPA Clean Water Act compliance. German municipal utilities around Ludwigshafen and Leverkusen specify these for chlorine and coagulant dosing where any contamination triggers discharge violations.
- Piston Pumps:Precision-machined cylindrical plungers deliver pulsation-free flow at pressures exceeding 1,000 bar for pharmaceutical and specialty chemical synthesis. German chemical manufacturing clusters sustain premium procurement here, driven by polymer applications demanding exact stoichiometric ratios.
- Plunger Pumps:Hardened ceramic or coated steel plungers handle abrasive slurries in mining and wastewater grit removal with simpler maintenance protocols than diaphragm alternatives.
- Rotary Pumps:Eccentric screw and gear configurations address high-viscosity polymer and food additive metering where shear-sensitive fluids degrade under reciprocating action.
The dominant share belongs to Diaphragm Pumps, while Piston Pumps is closing the gap fastest.
Technology:
Automation intensity separates capital-light mechanical installations from digitally integrated electro-hydraulic platforms.
- Electro-Hydraulic:Servo-controlled pressure modulation enables remote stroke adjustment and real-time flow correction via SCADA integration. North Sea platform operators adopt these architectures to eliminate helicopter transport for manual intervention on unmanned installations.
- Mechanical Actuation:Cam-driven and linkage systems persist in budget-constrained municipal districts where simple reliability outweighs precision demands, particularly in US rural water treatment facilities facing staff attrition.
- Pneumatic-Hydraulic:Compressed-air-driven units serve explosive atmospheres in offshore oil and gas chemical injection where electrical spark risks mandate ATEX-compliant actuation alternatives.
- Manual Control:Hand-adjusted stroke mechanisms survive in small-scale agriculture and developing-economy water treatment where electrification remains incomplete and technical labor is abundant.
Electro-Hydraulic architectures are expanding most quickly, though Mechanical Actuation retains volume leadership in replacement cycles.
Application:
Regulatory stringency creates tiered demand profiles from life-critical potable water through discretionary crop inputs.
- Water Treatment:Coagulant, disinfectant, and pH correction dosing for municipal and industrial effluent compliance. EPA enforcement and ISO 9001 quality mandates accelerate diaphragm pump replacement cycles across US utilities.
- Chemical Injection:Corrosion inhibitors, scale preventatives, and methanol injection for upstream oil and gas production. Offshore platforms in the Gulf of Mexico drive electro-hydraulic adoption for remote modularity.
- Food & Beverage Processing:Sanitary-grade dosing of flavorings, preservatives, and cleaning agents under FDA and EFSA hygiene protocols.
- Agriculture Irrigation:Fertigation and pesticide metering where lower pressure tolerances and peristaltic pump substitution pressure margins.
Water Treatment commands the largest installed base, while Chemical Injection shows the steepest expansion trajectory.
End User:
Customer sophistication ranges from federally regulated utilities through fragmented farm operations with divergent maintenance capabilities.
- Municipal Facilities:City and regional water authorities with mandated procurement transparency and long-term service contracts. California and Texas districts increasingly unbundle capital acquisition from predictive maintenance obligations.
- Chemical Manufacturers:Integrated petrochemical and specialty chemical producers with in-house tribology expertise and captive maintenance workforces. German clusters around BASF and Bayer facilities represent concentrated premium demand.
- Food Processing Plants:Dairy, beverage, and packaged goods facilities requiring documented calibration traceability under FDA Hazard Analysis frameworks.
- Crop Farms:Individual and cooperative agricultural operations with price-sensitive procurement and minimal technical staffing for hydraulic system upkeep.
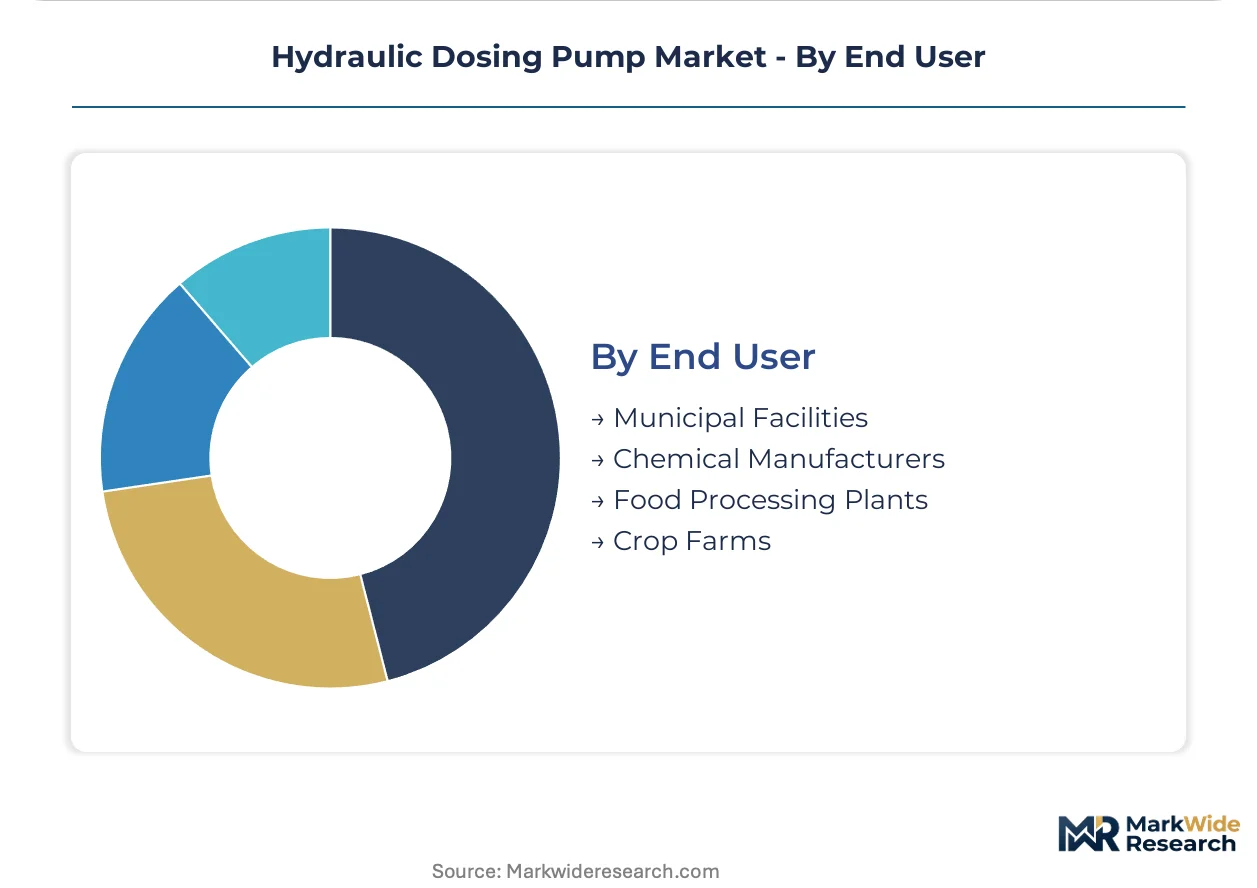
Municipal Facilities anchor current revenue, while Chemical Manufacturers are gaining share fastest through green hydrogen electrolyzer scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German chemical manufacturing clusters, where precision specifications command premium multiples, while US municipal utilities face compressed margins from standardized procurement mandates and service-unbundling pressures.
United States
EPA Clean Water Act enforcement drives certified metering accuracy upgrades across municipal water districts, with California and Texas utilities adopting performance-based contracts that transfer uptime risk to OEM service networks. The IRA's water infrastructure funding accelerates diaphragm pump replacement cycles for zero-emission sealing compliance. Houston's petrochemical corridor sustains demand for high-pressure chemical injection systems.
Germany
Municipal upgrades around Ludwigshafen and Leverkusen combine with specialty chemical manufacturing clusters to sustain premium procurement for polymer and pharmaceutical applications. The EU F-Gas Regulation mandates double-diaphragm monitoring architectures, extending certification timelines for leak-proof dosing compliance. BASF and Bayer facility concentrations anchor discharge pressure requirements exceeding 1,000 bar.
China
Gigawatt-scale green hydrogen electrolyzer installations generate precise caustic and acid dosing demand for high-pressure hydraulic metering with pulsation-free delivery profiles. MEE discharge standard tightening forces asset replacement cycles favoring precision over legacy mechanical systems. Yangtze River Delta chemical processors retrofit skids for next-generation corrosion-resistant architectures.
Saudi Arabia
Carbon-capture project pipelines in the Eastern Province require amine and chilled ammonia precision injection for corrosive chemical handling, opening white space in Middle Eastern dosing equipment procurement. The country's national industrial development programs prioritize localized service-network density for predictive maintenance bundling. NEOM's green hydrogen ambitions amplify high-pressure metering specifications.
Japan
Offshore platform operators in the East China Sea adopt electro-hydraulic actuation to eliminate helicopter transport for manual stroke adjustment on unmanned installations. METI energy transition directives redirect capital from conventional chemical plants toward hydrogen and carbon-capture facilities demanding next-generation dosing precision. Osaka-based engineering consultancies specify servo-controlled pressure modulation for remote modularity.
Hydraulic Dosing Pump Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on materials and drive technologies. The vendor base stratifies between consolidated multinational pump groups with captive service networks and mid-cap diaphragm material specialists with backward integration into elastomer supply. Three archetypes dominate: asset-light leasing platforms bundling predictive maintenance, in-house diaphragm producers controlling critical seal technologies, and modular skid architects compressing chemical injection lead times. Competitive moves concentrate on geographic service-network expansion and technology licensing for electro-hydraulic architectures.
Among European-based precision specialists, Lewa GmbH and ProMinent GmbH exemplify the in-house materials tier, with German GmbH structures signaling captive diaphragm production and proprietary drive system control. Grundfos anchors the asset-light service platform archetype through network-density leasing models. IDEX Corporation represents the modular systems approach with platform architectures reducing deployment timelines. These three patterns—materials verticalization, service bundling, and modular integration—define the competitive fault lines.
| Leading Market Players |
|---|
| Dover Corporation |
| Milton Roy |
| Grundfos |
| Nikkiso Co., Ltd. |
| Seko S.p.A. |
| ProMinent GmbH |
| Lewa GmbH |
| SPX FLOW |
| IDEX Corporation |
| Others |
Cost & Logistics Intelligence
Rhine-Ruhr corridor freight costs compress margin pools for diaphragm material shipments, concentrating pricing power with German manufacturers possessing captive elastomer production while forcing tiered procurement strategies among buyers lacking backward integration.
Pricing Analysis
Configured-to-order pricing for 1,000-bar polymer injection systems commands 40-60% premiums over standard municipal diaphragm units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—ATEX-compliant electro-hydraulic architectures for offshore platforms price above ISO 9001-only water treatment configurations. Pricing pressure stems from peristaltic pump substitution in low-accuracy municipal segments. Crop farms exhibit highest price sensitivity; German chemical manufacturers show lowest, prioritizing pulsation-free delivery over capital outlay.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk for rare-earth magnet components in servo-controlled electro-hydraulic actuators. Diaphragm manufacturing concentrates in Germany, Japan, and Switzerland; Hastelloy and titanium sourcing draws from Australian mining operations and Chinese refining facilities. Single-source vulnerability persists for PTFE membrane substrates facing PFAS restriction uncertainty. Distribution runs through OEM-direct channels for large chemical manufacturers and specialized fluid-handling distributors for municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as service-unbundling separates capital equipment from predictive maintenance contracts, creating niche entry points for specialized diaphragm material suppliers and regional leasing platforms.
For Market Incumbents: Build captive service-network density moats through predictive maintenance bundling that transfers uptime risk from municipal utilities. Add electro-hydraulic certification capacity in Hamburg to preempt EU F-Gas Regulation compliance delays. Peristaltic pump substitution in low-pressure water treatment threatens volume share; counter via performance-based contracting that monetizes accuracy guarantees. For New Entrants and Emerging Players: Pursue carbon-capture solvent dosing white space in Saudi Arabia's Eastern Province where amine injection specifications outrun incumbent service coverage. Target green hydrogen electrolyzer installations in China's Yangtze River Delta as the most penetrable segment given caustic dosing precision requirements and limited local electro-hydraulic expertise. Deploy asset-light leasing models with remote telemetry to bypass capital barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized diaphragm material divisions lacking standalone service infrastructure. Five-to-ten-year viability hinges on PFAS replacement elastomer validation timelines and carbon-border adjustment mechanism implementation pace. Watch for inflection when green hydrogen project pipelines convert feasibility studies to firm electrolyzer orders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diaphragm Materials | Lewa GmbH's captive elastomer production insulates margin pools from Hastelloy price volatility. |
| Electro-Hydraulic Platform Standardization | IDEX Corporation's modular architectures compress chemical injection skid lead times for Gulf of Mexico operators. |
| Predictive Maintenance Service Bundling | Grundfos leverages network density to convert municipal utilities from capex to opex procurement models. |
| ATEX Hazardous-Zone Certification Investment | ProMinent GmbH extends market access for offshore chemical injection amid EU regulatory tightening. |
| Green Hydrogen Electrolyzer Partnership | Nikkiso Co., Ltd. positions pulsation-free dosing systems for gigawatt-scale caustic handling in Chinese installations. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers at municipal water utilities, procurement leads at German chemical manufacturers, aftermarket service heads at OEM networks, and technical R&D directors at diaphragm material suppliers and refined through secondary validation against EPA enforcement records, EU F-Gas Regulation implementation timelines, SEC 10-K filings from listed pump manufacturers, customs trade data for Hastelloy and titanium imports, and ISO 9001 certification registries. Bottom-up unit economics triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include pump architecture type, actuation technology tier, application regulatory stringency, end-user maintenance capability, and regional chemical manufacturing cluster density. CAGRs derived from installed base replacement cycles and green hydrogen capacity buildout trajectories. Industry-specific inputs incorporated electrolyzer dosing specifications and carbon-capture solvent injection requirements.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or rare-earth magnet pricing would shift the trajectory. Forecasts reflect documented assumptions on PFAS restriction timelines and carbon-border adjustment implementation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Circulators Market