
 Horizontal Pumping Systems (HPS) Market | 2026-2036
Horizontal Pumping Systems (HPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Pumping Systems (HPS) Market Foresight
Subscription-based predictive maintenance is decoupling hardware sales from recurring revenue streams in the Horizontal Pumping Systems landscape. Baker Hughes leverages its digital twin platform to anchor long-term service contracts with upstream operators. Schlumberger Limited differentiates through integrated artificial lift portfolios that extend across the well lifecycle. Flowserve Corporation specializes in corrosion-resistant alloy configurations for sour service environments.
Horizontal Pumping Systems are skid-mounted multistage centrifugal or positive displacement pump assemblies engineered for surface fluid injection and transfer duties, typically rated for pressures exceeding 5,000 psi and flow rates tailored to wellbore deliverability. Their primary purpose centers on artificial lift optimization, waterflood injection, and produced fluid gathering in oilfield operations. Centrifugal Pumps dominate unit shipments across high-volume water handling applications where efficiency curves favor continuous duty cycles. Screw Pumps occupy premium margin pools in heavy crude and multiphase service where positive displacement metering proves essential. Diaphragm Pumps are gaining traction in chemical processing and water treatment segments requiring zero-leakage containment.
EPA emissions regulations and API 610/674 design standards govern material selection, mechanical seal specifications, and fugitive emission limits for surface-installed pumping equipment in US oilfield service. OSHA process safety management requirements mandate hazard analysis for HPS installations handling flammable or toxic fluids above threshold quantities. Buyers must weigh total lifecycle cost against upfront capital outlay as predictive analytics and remote monitoring reshape procurement criteria and vendor selection frameworks.
Market Dynamics
Pad drilling intensification in the Permian Basin is compressing well spacing and multiplying fluid handling volumes per surface location, forcing operators to consolidate artificial lift infrastructure into higher-capacity modular HPS skids rather than dispersed single-well units.
Growth Catalysts
- EPA Tier 4 Emissions Standards:Tightening fugitive emission limits for surface equipment are accelerating replacement cycles for legacy pumping systems across Texas and New Mexico oilfields.
- Multiphase Metering Integration:Downhole sensor networks are expanding real-time optimization capabilities that tether HPS performance to reservoir dynamics.
- Waterflood Expansion:Secondary recovery projects in mature Permian formations are concentrating injection pump demand around centralized surface facilities.
Market Restraints
- Superalloy Supply Concentration:Corrosion-resistant alloy forgings for sour service pumps depend heavily on a limited supplier base in Pennsylvania and Ohio.
- API 674 Certification Burden:Positive displacement pump validation protocols extend lead times by four to six months for custom-engineered units.
- Electrification Substitution:Progressing cavity pumps and electric submersible pumps are capturing marginal barrels in low-pressure artificial lift applications.
Strategic Opportunities
- Argentina Vaca Muerta Development:Unconventional shale expansion is creating demand for surface pumping infrastructure without established local supply chains.
- Hydrogen Blending Infrastructure:Pipeline injection specifications are opening specification windows for diaphragm pump configurations in energy transition applications.
- Remote Monitoring Convergence:Edge computing and vibration analytics are enabling predictive service models that extend vendor relationships beyond hardware delivery.
Industry Challenges
- Rotordynamics Specialist Scarcity:High-speed multistage pump design expertise is concentrating at a handful of engineering consultancies in Houston.
- Legacy SCADA Integration:Brownfield automation protocols are forcing costly middleware development for digital twin deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horizontal Pumping Systems (HPS) Market |
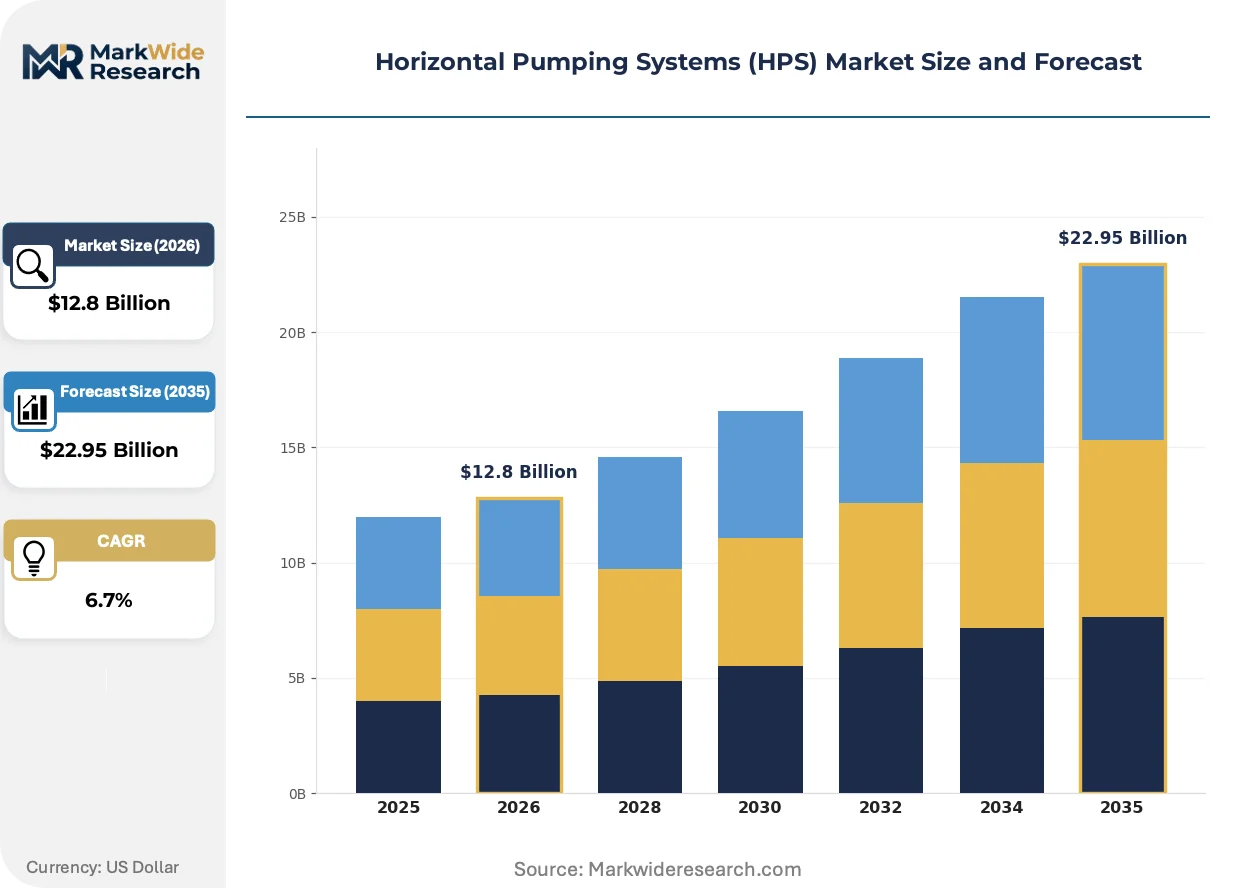
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Screw Pumps, Diaphragm Pumps, Peristaltic Pumps Application: Water Treatment, Oil & Gas, Chemical Processing, Agriculture End User: Utilities, Industrial Manufacturing, Construction, Mining Material: Stainless Steel, Cast Iron, Plastic, Alloy |
| Companies Covered | Schlumberger Limited, Baker Hughes, General Electric, Halliburton, National Oilwell Varco, Flowserve Corporation, Weatherford International, Xylem Inc., Ebara Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Pumping Systems (HPS) Market Shifts & Advancements
Digital instrumentation is penetrating surface pumping equipment faster than downhole systems, rewriting how operators contract for reliability and recasting vendor relationships around uptime guarantees rather than unit sales.
Edge-mounted vibration sensors coupled with cloud-based diagnostic algorithms are automating bearing failure prediction and dispatching maintenance crews before catastrophic seal damage occurs. Mid-size Permian operators lacking in-house reliability engineering are adopting these systems fastest, often bundled into five-year service agreements. The technology is automating the transition from reactive repair schedules to condition-based intervention, compressing unplanned downtime intervals by half.
EPA methane detection mandates and Texas Railroad Commission air quality enforcement are tightening mechanical seal specifications and driving adoption of dual-seal configurations with barrier fluid monitoring. Fabricators serving the Delaware Basin are retooling weld procedures to meet revised NACE MR0175/ISO 15156 sour service limits for hydrogen sulfide exposure. The regulatory pressure is most acute in New Mexico portions of the Permian, where state environmental rules exceed federal baselines.
Integrated service contracting is displacing discrete equipment procurement as operators seek single-source accountability for artificial lift performance. Engineering-procurement-construction firms are consolidating vendor tiers and demanding lifecycle cost guarantees that shift compressor and pump selection authority away from field engineers. This pattern is visible among Permian pure-play producers who have outsourced surface facility operations to specialized contractors.
Horizontal Pumping Systems (HPS) Market Segmentation
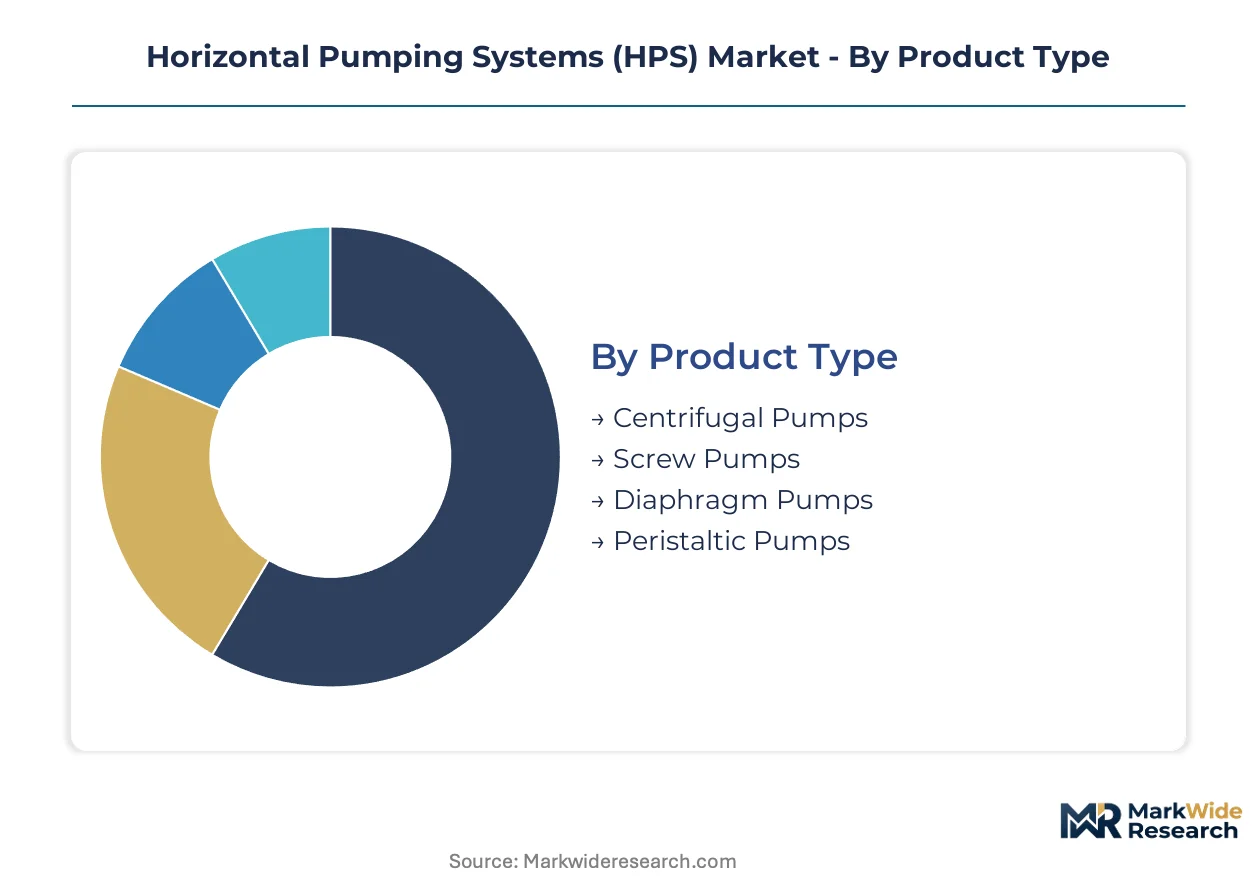
Horizontal Pumping Systems procurement diverges sharply between standardized catalog units and engineered-to-order configurations. Specification complexity cascades through product architecture, application severity, end-user capital discipline, and material metallurgy. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization dominates.
Product Type:
Customization intensity spans from off-the-shelf centrifugal assemblies to fully engineered positive displacement trains, with standardization economics governing procurement patterns across each tier.
- Centrifugal Pumps:Multistage radial flow designs dominate high-volume water handling and secondary recovery injection. Demand clusters in Permian Basin waterflood operations where EPA Tier 4 emission standards accelerate replacement of legacy surface units. Modular skid packaging allows operators to scale capacity incrementally across multi-well pads.
- Screw Pumps:Progressive cavity and twin-screw configurations meter heavy crude and multiphase streams with positive displacement precision. API 674 certification requirements extend lead times, but sour service specifications in Delaware Basin H2S environments sustain premium positioning. Downhole sensor integration enables real-time speed adjustment tied to reservoir drawdown.
- Diaphragm Pumps:Zero-leakage containment suits chemical processing and hydrogen blending infrastructure. Energy transition pipeline specifications are opening specification windows for barrier-fluid configurations.
- Peristaltic Pumps:Hose compression mechanics handle abrasive slurries and shear-sensitive fluids in mining tailings and agricultural fertigation. Lower pressure ratings constrain oilfield adoption.
Most installed capacity flows through Centrifugal Pumps. Expansion is steepest in Screw Pumps.
Application:
Operating environment severity dictates material specifications, seal configurations, and maintenance intervals across application tiers.
- Oil & Gas:Artificial lift optimization, waterflood injection, and produced fluid gathering drive specification complexity. Pad drilling intensification in Texas and New Mexico multiplies fluid handling volumes per surface location, consolidating demand around higher-capacity modular skids.
- Water Treatment:Municipal and industrial wastewater handling favors standardized centrifugal architectures with lower engineering overhead. Continuous duty cycles emphasize efficiency curves over corrosion resistance.
- Chemical Processing:Aggressive media compatibility demands alloy selection per NACE MR0175/ISO 15156 sour service limits. Dual mechanical seal configurations with barrier fluid monitoring satisfy EPA methane detection mandates.
- Agriculture:Irrigation and fertigation applications prioritize capital efficiency over longevity. Peristaltic and centrifugal units dominate where abrasive well water accelerates wear.
Oil & Gas commands the dominant share of engineered-to-order revenue. Water Treatment represents the largest unit volume channel.
End User:
Capital deployment discipline and in-house engineering capability segment procurement behavior across buyer categories.
- Utilities:Municipal water and wastewater authorities emphasize lifecycle cost guarantees and long-term service contracts. Predictive maintenance subscriptions are displacing discrete equipment procurement fastest among this cohort.
- Industrial Manufacturing:Process reliability requirements favor integrated service contracting with single-source accountability. Vibration analytics and edge computing adoption concentrates here.
- Construction:Temporary dewatering and fluid transfer needs favor rental and short-cycle procurement. Standardized centrifugal units dominate with minimal customization.
- Mining:Abrasive slurry handling and remote site logistics drive demand for robust peristaltic and diaphragm configurations. Harsh operating environments accelerate replacement cycles.
Industrial Manufacturing captures the steepest expansion trajectory as outsourcing of surface facility operations extends vendor relationships beyond hardware delivery. Utilities anchor the largest installed base.
Material:
Corrosion resistance requirements and superalloy supply concentration govern material selection economics.
- Stainless Steel:Austenitic and duplex grades balance cost and corrosion resistance across water treatment and moderate oilfield service. Fabricators in Pennsylvania and Ohio concentrate forging capacity for sour service specifications.
- Alloy:Nickel-based superalloys and specialty stainless formulations withstand hydrogen sulfide exposure in Delaware Basin sour gas production. Limited supplier base extends lead times four to six months for custom-engineered units.
- Cast Iron:Lower-cost option for non-corrosive water handling and agricultural applications. Commoditized supply chain supports rapid delivery.
- Plastic:Polymer housings and linings handle aggressive chemicals and sanitary requirements in food-grade and pharmaceutical processing. Temperature and pressure limits constrain oilfield adoption.
Stainless Steel dominates unit shipments. Alloy commands the premium margin tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates engineered-to-order demand for high-pressure artificial lift systems, while China scales standardized centrifugal production for water handling infrastructure. Argentina's Vaca Muerta formation attracts foreign fabrication investment despite nascent local supply chains.
United States
Pad drilling intensification across the Permian Basin multiplies fluid handling volumes per surface location, consolidating procurement around modular skid-mounted systems. EPA Tier 4 emissions standards and Texas Railroad Commission air quality enforcement accelerate replacement cycles for legacy pumping equipment. Houston anchors engineering consultancy concentration for high-speed multistage pump rotordynamics design.
China
Municipal water treatment expansion and industrial wastewater retrofit programs drive centrifugal pump demand at scale. GB standards and MIIT equipment efficiency mandates shape procurement specifications for surface pumping infrastructure. Yangtze River Delta manufacturing clusters specialize in cast iron and stainless steel pump fabrication for domestic and export markets.
Argentina
Vaca Muerta shale development creates demand for sour service pumping systems without established local alloy forging capacity. National hydrocarbon regulator enforcement of surface facility standards forces operators to import API-certified equipment. Neuquén Basin drilling campaigns concentrate artificial lift procurement from international vendors.
Germany
Industrial process reliability requirements favor integrated service contracting over discrete equipment procurement. REACH chemical compatibility regulations and CE marking conformity shape material selection for chemical processing pump applications. Ruhr industrial corridor and Bavarian manufacturing zones concentrate precision pump engineering expertise.
Saudi Arabia
Secondary recovery waterflood expansion in mature oilfields drives high-volume injection pump demand. National regulator enforcement of sour service specifications per NACE MR0175 limits supplier qualification to alloy-capable fabricators. Eastern Province oilfield clusters concentrate procurement authority for centralized surface facility projects.
Horizontal Pumping Systems (HPS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service companies anchoring premium engineered-to-order tiers while regional fabricators capture standardized water handling volumes. Market structure concentrates around three strategic archetypes: full-lifecycle service integrators, corrosion-resistant alloy specialists, and scale-driven centrifugal producers. Consolidation through strategic partnerships and portfolio diversification into predictive maintenance subscriptions represent the dominant competitive vectors reshaping vendor relationships.
Within the full-lifecycle service integrator tier, Schlumberger Limited and Baker Hughes exemplify archetypes that tether hardware delivery to long-term performance contracts. Flowserve Corporation occupies a position among corrosion-resistant alloy specialists serving sour service environments. These three companies represent distinct strategic postures: service-led integration, materials engineering depth, and application-specific reliability positioning.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes |
| General Electric |
| Halliburton |
| National Oilwell Varco |
| Flowserve Corporation |
| Weatherford International |
| Xylem Inc. |
| Ebara Corporation |
| Others |
Supply & Pricing Matrix
EPA Tier 4 emissions standards and Texas Railroad Commission air quality enforcement gate both qualified supply and premium-tier pricing access for Horizontal Pumping Systems, concentrating certified fabrication capacity among Pennsylvania and Ohio alloy forgers while forcing buyers to absorb extended lead times and sour service premiums for compliant equipment.
Pricing Analysis
Capacity additions in Yangtze River Delta manufacturing clusters are reshaping price floors for standardized centrifugal units, compressing margins on cast iron and austenitic stainless configurations while API 674-certified positive displacement pumps sustain three-tier pricing stratification across premium alloy, standard duplex, and economy cast iron grades. Price differentiation hinges on NACE MR0175 certification tier and bundled predictive maintenance subscriptions. Pricing pressure runs through water treatment segments as Chinese fabricators scale export volumes. Municipal utilities show highest price sensitivity; Permian operators prioritize lifecycle cost guarantees over upfront capital.
Supply Chain Analysis
Nickel-based superalloy forgings rest on a limited supplier base concentrated in Pennsylvania, Ohio, and select German Ruhr corridor foundries, creating single-source vulnerability for sour service pump configurations handling Delaware Basin hydrogen sulfide exposure. Raw material dependencies span cobalt-chromium alloys, duplex stainless steel feedstock, and specialized barrier fluid formulations. Distribution runs through engineering-procurement-construction firms consolidating vendor tiers for integrated service contracts. Tariff exposure on Chinese cast iron components adds cost volatility to standardized unit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Horizontal Pumping Systems market functions as a geographic-arbitrage play where Argentina's Vaca Muerta development offers first-mover premiums absent local alloy forging infrastructure, while Chinese standardized production erodes margin pools in water treatment applications.
For Market Incumbents: Anchor predictive maintenance subscriptions as the primary defensive moat against Schlumberger and Baker Hughes integrated service portfolios, while securing captive supply of nickel-based superalloy forgings through backward integration into Pennsylvania forging capacity to mitigate four-to-six-month lead time vulnerability. For New Entrants and Emerging Players: Capture modular skid packaging white space in Neuquén Basin Vaca Muerta campaigns where national hydrocarbon regulator enforcement forces API-certified equipment imports without established local fabrication, leveraging rental-service hybrid models to bypass capital-intensive alloy forging barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional corrosion-resistant alloy specialists because superalloy supply concentration and NACE MR0175 certification burdens create natural fragmentation ceilings that favor consolidation. Five-to-ten year viability hinges on predictive maintenance attach rates. Watch Argentina drilling permit velocity as inflection indicator for international fabrication demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Baker Hughes digital twin deployments anchor five-year service contracts with Permian operators. |
| Backward Integration into Alloy Forging | Flowserve captive supply of Pennsylvania superalloy capacity insulates against sour service lead time volatility. |
| Argentina Market Entry Partnership | International vendors bypass Vaca Muerta supply chain gaps through Neuquén Basin EPC alliances. |
| API 674 Certification Investment | Positive displacement pump validation protocols extend moats against Chinese centrifugal commoditization. |
| Hydrogen Blending Specification Development | Diaphragm pump configurations capture energy transition pipeline injection opportunities ahead of CE marking harmonization. |
Research Methodology
Direct dialogue with artificial lift engineers, reliability directors at Permian operators, EPC procurement leads, superalloy forging plant managers, and aftermarket service heads grounded segmentation boundaries, combined with triangulation against API certification databases, EPA enforcement records, Texas Railroad Commission air quality filings, and customs trade data for pump and pump part HS codes.
Bottom-up unit economics across centrifugal, screw, diaphragm, and peristaltic pump configurations were cross-validated against top-down oilfield capital expenditure patterns and water treatment infrastructure budgets throughout the projection horizon. Segmentation dimensions modeled include product architecture, application severity, end-user capital discipline, and material metallurgy grade. CAGRs were derived from installed base replacement cycles and pad drilling intensification trajectories.
Regulatory enforcement variance, superalloy supply disruption, and electrification substitution by progressing cavity pumps are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
End Suction Pump Market