
 Solar Pump Market | 2026-2036
Solar Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Pump Market Intelligence
Skilled solar technician availability is collapsing across Sub-Saharan Africa and South Asia, constraining installation velocity and after-sales service networks. Grundfos Holding A/S leverages its decentralized training academies to sustain technician pipelines in East Africa. Shakti Pumps (India) Limited anchors its competitive position through deep rural distribution networks spanning tier-3 and tier-4 Indian districts. LORENTZ GmbH differentiates via German-engineered DC submersible systems optimized for off-grid boreholes.
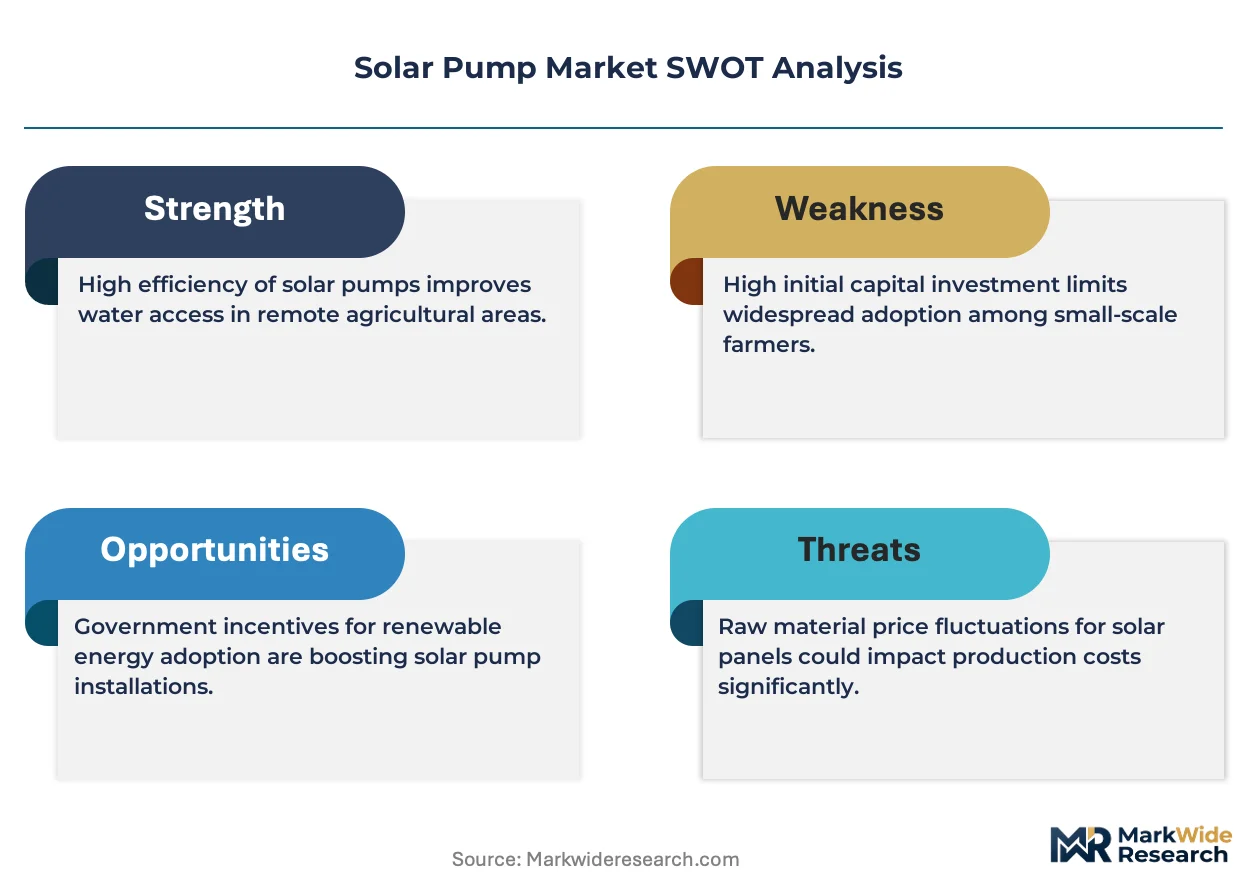
A solar pump converts photovoltaic energy into mechanical power for fluid movement, typically achieving 3-10 cubic meters per hour discharge rates across head ranges of 10-200 meters depending on motor configuration and array sizing. Submersible pumps dominate agricultural irrigation applications due to superior efficiency in deep groundwater extraction, while surface pumps retain cost advantages in shallow river and pond-fed systems. Photovoltaic systems command the technology segment by installed base, though hybrid configurations pairing solar with grid or diesel backup are gaining traction where water demand exceeds daylight generation windows. Agricultural end users represent the primary demand pool, with residential and commercial segments trailing due to higher upfront capital requirements and longer payback periods.
India's Ministry of New and Renewable Energy administers the PM-KUSUM scheme, which subsidizes solar pump adoption for farmers while mandating domestic content requirements that reshape supplier qualification criteria. The International Electrotechnical Commission publishes IEC 62253 performance standards that define testing protocols for solar pumping systems, creating a baseline for cross-border procurement and warranty enforcement. Stakeholders must monitor evolving subsidy disbursement timelines and local content thresholds, as these policy levers determine effective market access more fundamentally than raw technology cost curves.
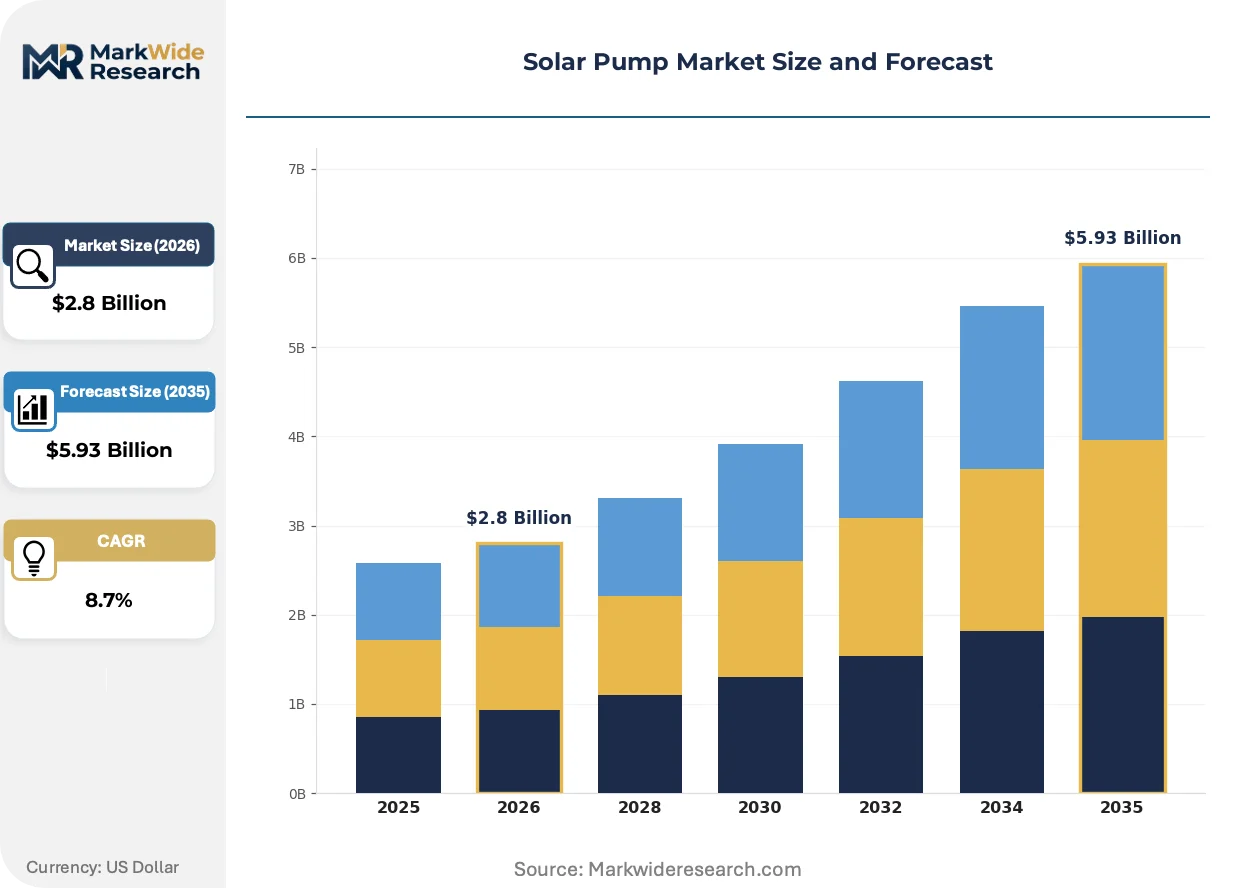
Market Dynamics
Photovoltaic module cost deflation is compressing system economics faster than installation capacity can expand, creating a bottleneck where qualified technician supply constrains deployment velocity across rural markets.
Growth Catalysts
- PM-KUSUM scheme subsidies:India's Ministry of New and Renewable Energy underwrites capital expenditure for agricultural solar pumps, mandating domestic content requirements that reshape supplier qualification criteria.
- Groundwater depletion urgency:Farmers in Gujarat, Rajasthan, and Maharashtra face aquifer collapse, forcing migration from diesel-powered extraction to photovoltaic-powered alternatives.
- DC submersible efficiency gains:Brushless permanent magnet motors achieve 25-30% higher conversion efficiency than AC induction equivalents, reducing array sizing requirements for deep borehole applications.
Market Restraints
- Polysilicon price volatility:Raw material swings in photovoltaic wafer production transmit directly to system landed costs, compressing installer margins and delaying farmer purchase decisions.
- Technician pipeline collapse:Sub-Saharan Africa and South Asia face acute shortages of certified solar electricians, extending installation backlogs and degrading after-sales service coverage.
- Diesel generator substitution economics:Where subsidized fuel persists, fossil backup systems retain lifecycle cost advantages despite higher operating expenditure.
Strategic Opportunities
- Hybrid system convergence:Configurations pairing photovoltaic arrays with grid or diesel backup capture demand where water requirements exceed daylight generation windows.
- Tier-3 distribution penetration:Deep rural networks spanning India's tier-4 districts remain undersupplied relative to stated PM-KUSUM enrollment targets.
- IEC 62253 certification expansion:Standardized performance testing protocols enable cross-border procurement and warranty enforcement, reducing buyer uncertainty in emerging markets.
Industry Challenges
- Domestic content compliance complexity:India's PLI scheme and DGFT local value-add mandates force foreign component suppliers into joint venture structures or tariff exposure.
- Groundwater-electricity nexus governance:State-level electricity regulators struggle to coordinate solar pump deployment with aquifer recharge mandates, creating policy friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Pump Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Pumps, Submersible Pumps, Borehole Pumps, Centrifugal Pumps Application: Agricultural Irrigation, Wastewater Treatment, Drinking Water Supply, Industrial Use End User: Agriculture, Residential, Commercial, Industrial Technology: Photovoltaic Systems, Hybrid Systems, Solar Thermal Systems, Grid-Connected |
| Companies Covered | Grundfos Holding A/S, Shakti Pumps (India) Limited, Xylem Inc., LORENTZ GmbH, Kirloskar Brothers Ltd., KSB SE & Co. KGaA, Franklin Electric Co. Inc., Alpex Solar Ltd, Bright Solar Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Pump Market Strategic Shifts & Innovations
System architecture is pivoting from standalone photovoltaic arrays toward intelligent hybrid configurations, while procurement patterns compress from multiyear capital cycles to performance-guaranteed service agreements.
DC brushless submersible pump architecture is displacing conventional AC induction systems in deep borehole applications. Agricultural cooperatives in water-stressed districts are specifying permanent magnet motors for head requirements exceeding 100 meters. This technology shift is displacing the historical dominance of surface-mounted centrifugal pumps in medium-depth extraction.
India's CEA technical standards for grid-interactive solar pumps are tightening inverter synchronization requirements. The regulations force manufacturers to redesign power electronics for anti-islanding compliance. Off-grid and weak-grid agricultural zones face retrofit obligations that favor integrated system suppliers over component assemblers.
Farmer procurement is migrating from equipment purchase toward water-as-a-service contracts where installers retain asset ownership. This model transfers performance risk from capital-constrained smallholders to technology providers. Eastern Rajasthan and northern Gujarat exhibit the fastest contract penetration where groundwater access uncertainty heightens risk aversion.
Solar Pump Market Segmentation
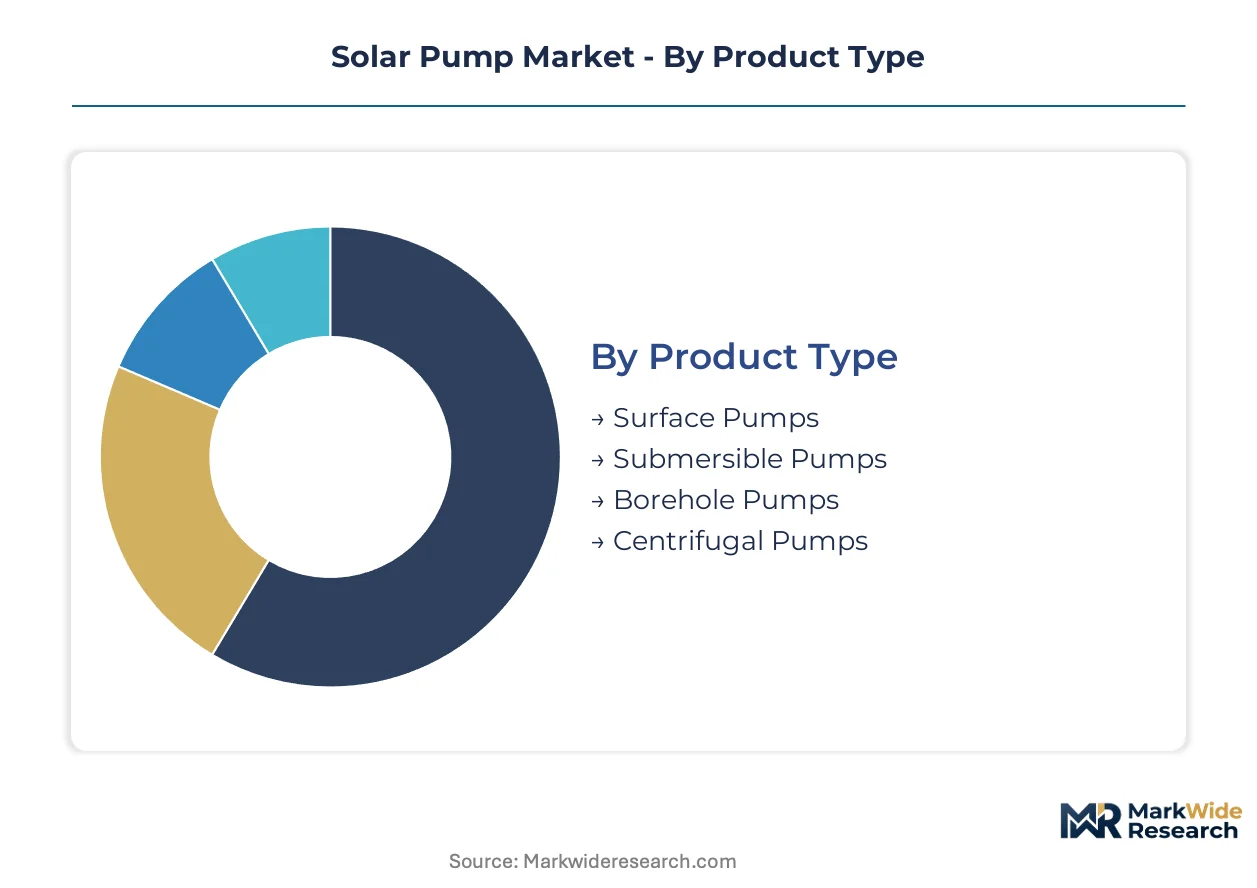
Solar pump procurement channels diverge sharply by segment depth and technical complexity. Submersible systems flow through specialized irrigation dealers, while surface pumps reach farmers via general agricultural supply networks.
Product Type:
Distribution channels stratify by installation complexity and technical support requirements.
- Surface Pumps:Shallow water extraction systems deploy centrifugal or positive displacement mechanisms for river-fed and pond-fed irrigation. Demand clusters in India's eastern rice belts where water tables sit within 7 meters of surface, constrained by seasonal flow variability and silt intrusion.
- Submersible Pumps:Sealed motor-pump units operate below water level, achieving superior efficiency in deep borehole applications through brushless permanent magnet DC architecture. Gujarat and Rajasthan farmers specify these for head requirements exceeding 100 meters where aquifer depletion forces ever-deeper drilling.
- Borehole Pumps:Slim-diameter submersible designs fit narrow well casings common in African rural water programs.
- Centrifugal Pumps:Impeller-based systems dominate surface water transfer with lower capital thresholds.
By volume, Surface Pumps leads. By growth pace, Submersible Pumps is ahead.
Application:
Cost tiers separate capital-intensive municipal projects from distributed agricultural deployments.
- Agricultural Irrigation:The dominant deployment channel addresses smallholder water security across arid and semi-arid cropping zones. India's PM-KUSUM scheme channels subsidy flows toward this segment, with Maharashtra's horticulture belts and Rajasthan's groundnut regions exhibiting densest penetration.
- Wastewater Treatment:Solar-powered aeration and transfer systems serve decentralized sewage facilities in peri-urban India and African secondary cities. Capital recovery timelines extend versus agricultural equivalents due to lower electricity tariff displacement value.
- Drinking Water Supply:Community-scale rural water schemes leverage solar pumping for off-grid boreholes.
- Industrial Use:Process water and cooling applications remain nascent due to reliability requirements.
Agricultural Irrigation commands installed base. Wastewater Treatment climbs fastest on urban infrastructure gaps.
End User:
Customer type determines financing structure and service model intensity.
- Agriculture:Individual smallholders and cooperative entities drive procurement through subsidized capital programs and emerging water-as-a-service contracts. Risk aversion from groundwater access uncertainty accelerates performance-guaranteed arrangements in eastern Rajasthan.
- Residential:Rural homesteads and remote villas specify small-scale systems for domestic water security. Higher per-capita capital burden limits penetration outside donor-funded development programs.
- Commercial:Agribusiness estates and rural hospitality operators deploy mid-scale systems.
- Industrial:Mining and processing facilities require hybrid configurations for 24-hour reliability.
Agriculture dominates unit shipments. Commercial segments expand most quickly on corporate sustainability mandates.
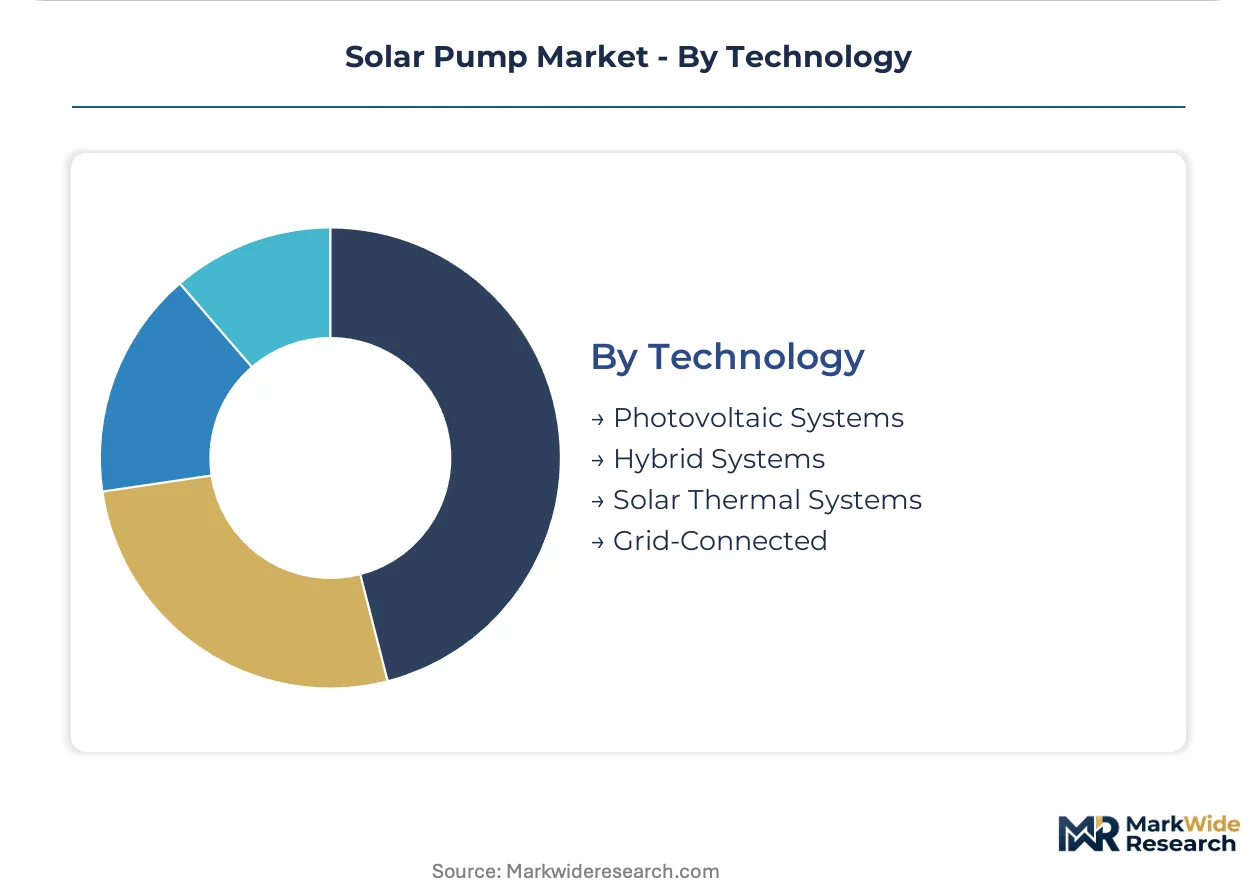
Technology:
Maturity gradients separate proven photovoltaic architectures from emerging hybrid configurations.
- Photovoltaic Systems:Direct-coupled DC arrays power pumps without battery storage, maximizing simplicity and minimizing maintenance in remote settings. India's CEA technical standards for grid-interactive variants are tightening inverter synchronization requirements, forcing power electronics redesigns.
- Hybrid Systems:Configurations pairing solar with grid or diesel backup capture demand where water requirements exceed daylight generation windows. Northern Gujarat dairy cooperatives specify these for evening livestock watering obligations.
- Solar Thermal Systems:Concentrated heat-to-mechanical conversion retains niche applicability in high-temperature industrial process pumping.
- Grid-Connected:Export-oriented arrays face regulatory complexity under evolving net metering frameworks.
Photovoltaic Systems anchors installed capacity. Hybrid Systems gains share fastest on reliability demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of New and Renewable Energy anchors the dominant geography through PM-KUSUM scheme administration, with CEA technical standards tightening synchronization requirements for grid-interactive systems. Deployment concentrates in states where groundwater depletion intersects high solar irradiance.
India
Gujarat, Rajasthan, and Maharashtra drive agricultural irrigation demand as aquifer collapse forces diesel-to-solar transitions. PM-KUSUM subsidies underwrite capital expenditure while mandating domestic content requirements that reshape supplier qualification criteria. Eastern Rajasthan's dairy cooperatives are pioneering water-as-a-service contracts where installers retain asset ownership.
China
Photovoltaic module manufacturing scale and cost deflation position the country as the upstream supply anchor for global system assembly. MIIT industrial policy prioritizes brushless permanent magnet motor development for export-oriented pump integration. Zhejiang and Jiangsu provinces host concentrated production clusters serving South Asian and African markets.
United States
California's Central Valley agricultural operators deploy solar pumping for groundwater sustainability compliance under SGMA aquifer management mandates. FERC interconnection rules and state-level net metering frameworks create regulatory complexity for grid-interactive configurations. The Imperial Valley irrigation district exhibits densest penetration where electricity tariff displacement value justifies capital outlay.
Germany
LORENTZ GmbH's engineering heritage positions the country as a premium DC submersible technology source for off-grid borehole applications. EU Green Deal agricultural decarbonization targets channel subsidy flows toward photovoltaic irrigation retrofits. Bavaria's precision agriculture sector specifies German-engineered systems for head requirements exceeding 150 meters.
Kenya
East African rural water programs leverage solar pumping for community-scale borehole supply in off-grid arid zones. The country's national energy regulator coordinates rural electrification authority funding with groundwater development initiatives. Turkana and Marsabit counties exhibit fastest deployment velocity where diesel logistics costs compound system economics.
Solar Pump Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with German-engineered specialists commanding premium positioning while Indian fabricators capture volume through subsidy-channel access. The vendor base stratifies across three tiers: integrated multinational pump manufacturers with solar divisions, dedicated solar pumping specialists with regional anchoring, and domestic component assemblers serving price-sensitive agricultural procurement. Grundfos Holding A/S exemplifies the multinational archetype through decentralized training academy deployment. Shakti Pumps (India) Limited represents the domestic specialist model. Competitive moves concentrate on distribution network deepening in tier-3 and tier-4 districts and IEC 62253 certification acquisition for cross-border warranty enforceability.
Within the multinational tier, Grundfos Holding A/S and Xylem Inc. occupy positions defined by service infrastructure scale and agricultural application heritage. Among dedicated solar pumping specialists, LORENTZ GmbH anchors the premium DC submersible segment through German engineering positioning, while Shakti Pumps (India) Limited exemplifies the domestic distribution archetype with tier-4 rural network penetration. Kirloskar Brothers Ltd. and KSB SE & Co. KGaA represent established pump manufacturers extending into photovoltaic integration. Franklin Electric Co. Inc. and Alpex Solar Ltd sit within the component integration tier. Bright Solar Limited occupies a position in the Indian domestic assembly segment.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Shakti Pumps (India) Limited |
| Xylem Inc. |
| LORENTZ GmbH |
| Kirloskar Brothers Ltd. |
| KSB SE & Co. KGaA |
| Franklin Electric Co. Inc. |
| Alpex Solar Ltd |
| Bright Solar Limited |
| Others |
Cost & Logistics Intelligence
India's CEA technical standards for grid-interactive solar pumps gate both supplier qualification and price differentiation simultaneously, as anti-islanding compliance requirements force power electronics redesigns that separate integrated system suppliers from component assemblers on cost and certification tiers.
Pricing Analysis
Price spreads between German-engineered DC submersible systems and Indian domestic assemblies exceed threefold across equivalent head ratings. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 62253 certification status, brushless permanent magnet motor efficiency grades, and bundled after-sales service coverage. Cost compression in the economy tier intensifies as polycrystalline module spot prices transmit volatility downstream. Smallholder agricultural cooperatives in water-stressed districts exhibit highest price sensitivity, while commercial agribusiness estates prioritize reliability guarantees over capital outlay minimization.
Supply Chain Analysis
China and India anchor photovoltaic module and pump motor manufacturing respectively, with Zhejiang and Jiangsu provinces hosting concentrated production clusters while Gujarat and Maharashtra assemble finished systems for PM-KUSUM channel distribution. Polysilicon wafers, rare-earth permanent magnets, and power electronics components constitute critical input dependencies. Single-source vulnerability concentrates in brushless motor controller integrated circuits. Distribution runs through specialized irrigation dealers for submersible systems and general agricultural supply networks for surface pump configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-as-a-service contract penetration in eastern Rajasthan and northern Gujarat is accelerating faster than hardware shipment growth, creating a service-attach opportunity where performance-guaranteed arrangements transfer asset ownership risk from capital-constrained farmers to technology providers.
For Market Incumbents: Fortify technician training academy deployment across Sub-Saharan Africa and South Asia to defend against installation backlog accumulation and after-sales service degradation. Deepen backward integration into permanent magnet motor production to offset rare-earth price volatility exposure. Prioritize IEC 62253 certification maintenance as domestic content mandates reshape supplier qualification criteria under India's PLI scheme. For New Entrants and Emerging Players: Anchor in India's tier-4 districts where PM-KUSUM enrollment targets exceed current supply penetration, particularly in Maharashtra's horticulture belts and eastern Rajasthan's dairy cooperatives. Target hybrid system configurations for northern Gujarat livestock watering applications where evening demand exceeds daylight generation. Pursue water-as-a-service contract origination as the primary go-to-market mechanism to bypass farmer capital constraints. For Investors and Strategic Acquirers: India's evolving PLI scheme and DGFT local value-add mandates reshape the acquisition landscape by forcing foreign component suppliers into joint venture structures or tariff exposure. Position for five-to-ten year horizon viability by targeting integrated system suppliers with captive training infrastructure and tier-3 distribution networks. Monitor PM-KUSUM subsidy disbursement velocity as the critical inflection signal for deployment capacity expansion versus demand constraint scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Academy Expansion | Grundfos-style decentralized academies address certified electrician shortages constraining installation velocity across rural African and South Asian markets. |
| Permanent Magnet Motor Backward Integration | In-house production of brushless DC architectures reduces array sizing requirements and insulates margins from rare-earth price swings. |
| Water-as-a-Service Contract Origination | Performance-guaranteed arrangements transfer groundwater access risk from smallholders to installers in eastern Rajasthan and northern Gujarat. |
| IEC 62253 Certification Investment | Standardized testing protocols enable cross-border procurement and warranty enforcement for German-engineered premium positioning. |
| Tier-4 Distribution Network Deepening | Shakti Pumps-style rural penetration captures PM-KUSUM subsidy flows in Maharashtra and Rajasthan districts undersupplied relative to enrollment targets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of CEA technical standards documentation, PM-KUSUM scheme administrative records, and IEC 62253 testing protocols. Interviews with solar pump system engineers, agricultural cooperative procurement officers, MNRE subsidy administrators, irrigation dealer network managers, and groundwater development authority planners informed demand-side validation. Secondary sources include customs trade data for photovoltaic module flows, SEC filings from listed pump manufacturers, and project development databases tracking rural water scheme deployments. Bottom-up shipment estimates triangulate against top-down subsidy disbursement records.
Segmentation dimensions modeled span product type, application, end user, and technology configuration across the analysis window. Photovoltaic versus hybrid system splits, submersible versus surface pump architecture, and agricultural versus municipal end-use categories structure volume and value outputs. CAGRs derive from fitted adoption curves calibrated to PM-KUSUM enrollment trajectories and diesel-to-solar substitution elasticity in groundwater-depleted districts. Forecast inputs incorporate polysilicon price transmission coefficients and technician pipeline expansion assumptions.
Underlying assumptions cover subsidy disbursement continuity, domestic content compliance feasibility, and aquifer recharge policy coordination, with deviation risk concentrated in PLI scheme local value-add threshold adjustments and state-level electricity regulatory fragmentation. Recalibration cycles align with material shifts in PM-KUSUM fund release schedules and CEA technical standard revision timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
US Industrial Pump Market