
 Chemical Pump Market | 2026-2036
Chemical Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Pump Market Analysis
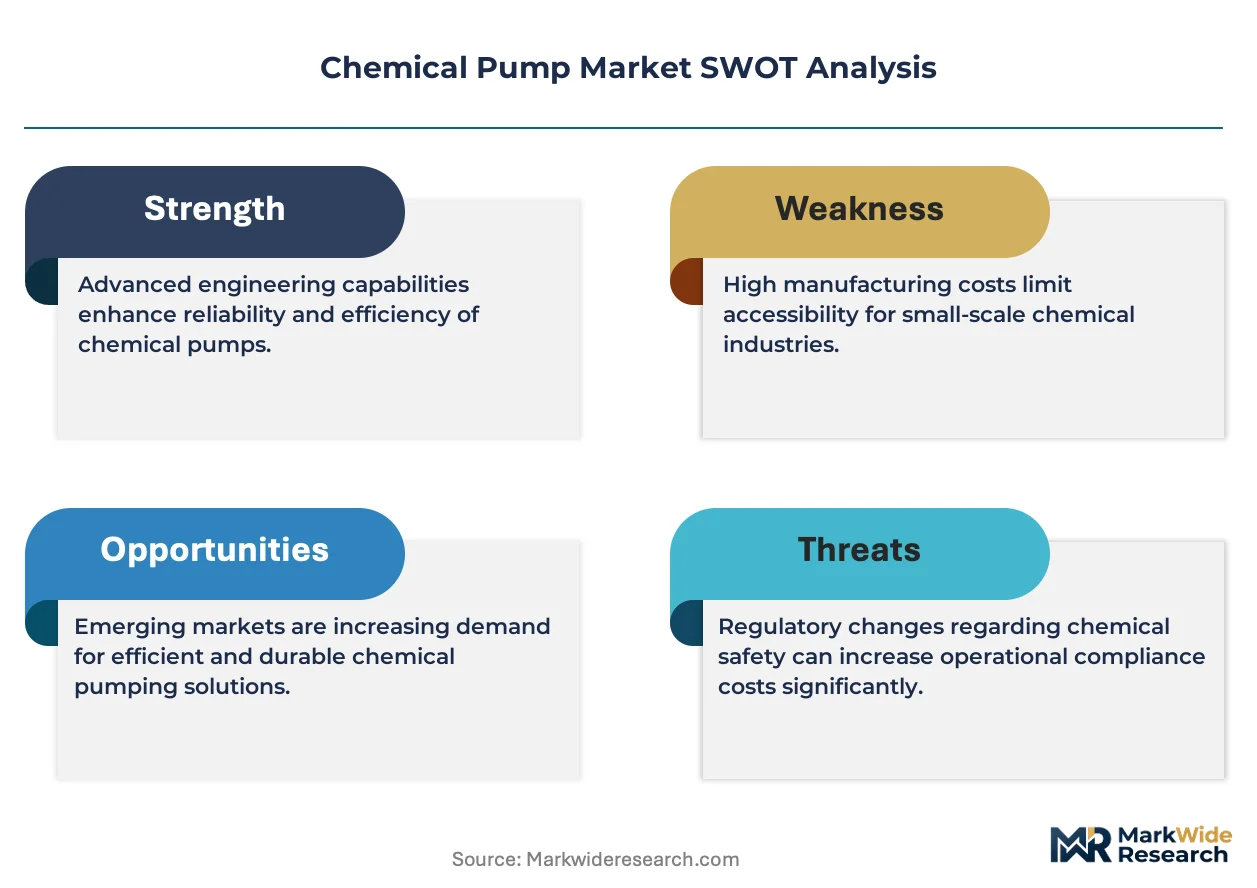
German specialty steel foundries and precision casting houses is realigning output toward super-duplex and Hastelloy pump housings as sour-service applications multiply. Flowserve leverages backward integration into metallurgical R&D to sustain premium positioning in high-temperature acid transfer. Sulzer anchors European demand through localized casting capabilities and aftermarket service density. KSB competes on modular platform architectures that cut lead times for standardized chemical process skids.
A chemical pump is a fluid-handling device engineered to transfer corrosive, abrasive, or hazardous liquids with wetted components typically constructed from stainless steel 316L, alloy 20, or fluoropolymer-lined castings, rated for temperatures spanning minus forty to four hundred degrees Celsius and pressures exceeding fifty bar in critical refinery duties. Centrifugal pumps dominate volume in bulk fluid transfer while magnetic drive technology captures margin in sealless leakage-prevention applications across pharmaceuticals and chlor-alkali processing. Diaphragm pumps lead in metering accuracy for water treatment chemical dosing where pulsation tolerance and stroke adjustability determine specification wins.
EPA effluent limitation guidelines and OSHA process safety management standards govern material selection and containment protocols in US chemical processing, while REACH and the EU F-Gas Regulation restrict certain seal elastomers and lubricant chemistries in European equipment. China's MEE enforces stricter volatile organic compound emission controls that favor sealless pump architectures in coastal chemical clusters. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these chemicals appear in conventional pump coatings and seal materials that face phasedown timelines.
Market Dynamics
Sealless magnetic drive architectures are compressing the addressable market for mechanical seal suppliers as EPA and MEE emission mandates harden containment requirements across coastal chemical clusters. This technology inflection is redistributing value capture toward specialized metallurgical foundries capable of super-duplex and Hastelloy precision castings.
Growth Catalysts
- REACH chemical compliance:European material specifications for wetted components are tightening, forcing upgrade cycles in legacy installations across Germany's Rhine-Ruhr chemical corridor.
- Water treatment utilities:German and US municipal procurement of corrosion-resistant pump systems is scaling as infrastructure replacement timelines compress.
- Fluoropolymer lining advances:Casting houses are extending temperature ratings for acid transfer duties, opening specification wins in chlor-alkali processing.
Market Restraints
- Nickel alloy supply concentration:Super-duplex and Hastelloy feedstock dependence on a limited German and Swedish specialty steel base creates input cost volatility.
- PFAS coating restrictions:Per- and polyfluoroalkyl substance phasedown timelines across multiple jurisdictions are eliminating conventional pump coating chemistries before qualified alternatives achieve scale.
- Sealless pump capex premium:Magnetic drive architectures carry first-cost penalties that compress adoption in budget-constrained municipal water treatment procurement.
Strategic Opportunities
- US Gulf Coast petrochemical corridor:Brownfield expansion and methane-to-chemicals investments are creating demand for high-temperature acid transfer pump skids.
- Modular platform architectures:Standardized chemical process skids with configurable metallurgy are compressing lead times and opening mid-market specification access.
- EU F-Gas Regulation:Restrictions on certain seal elastomers are creating specification windows for fluoropolymer-lined alternatives in refrigeration and chemical processing.
Industry Challenges
- Metallurgical R&D talent scarcity:Foundry engineering expertise in super-duplex solidification modeling and corrosion-fatigue testing is concentrating at a handful of European institutions.
- Multi-jurisdiction PFAS compliance:Divergent phasedown timelines across EPA state implementation plans, REACH restrictions, and China's MEE standards are fragmenting material qualification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Pump Market |
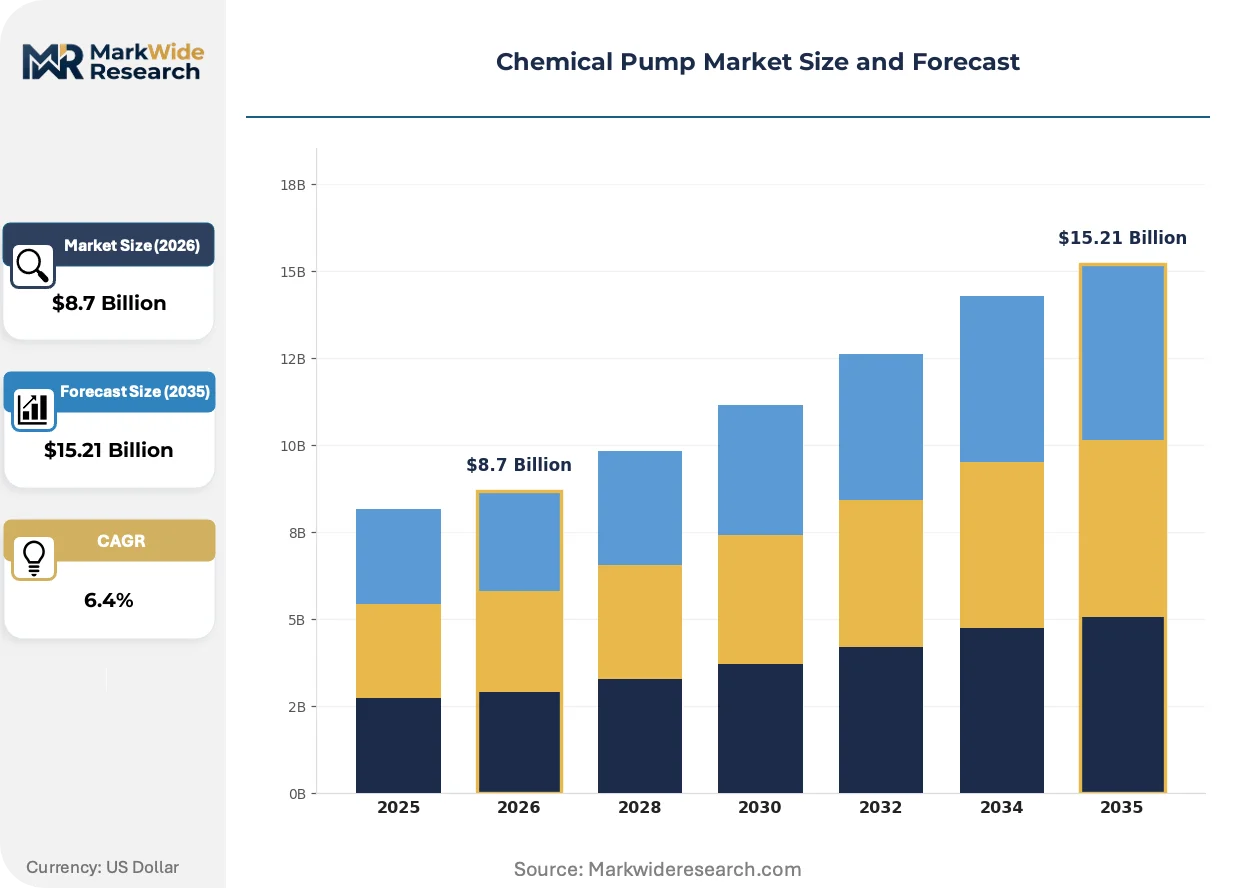
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Centrifugal Pumps, Gear Pumps, Peristaltic Pumps End User: Manufacturing, Oil & Gas, Water Treatment, Pharmaceuticals Installation: Stationary, Portable, Compact, Integrated Technology: Electric, Pneumatic, Hydraulic, Magnetic Drive |
| Companies Covered | Flowserve, Sulzer, Grundfos, IDEX Corporation, LEWA GmbH, Sundyne, ProMinent GmbH, KSB, ITT Goulds Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Pump Market Emerging Trajectories
Digital condition monitoring and predictive maintenance platforms are penetrating chemical pump installations, shifting value capture from hardware margins toward recurring service revenues. This instrumentation layer is restructuring buyer-supplier relationships across process industries.
Magnetic drive sealless technology is consolidating its position in hazardous fluid containment applications. Chlor-alkali processors and pharmaceutical manufacturers are specifying magnetic drive architectures as standard for new installations. This consolidation is compressing the installed base of conventional sealed pumps and redistributing aftermarket service revenues toward specialized sealless repair facilities.
EPA effluent limitation guidelines are tightening material selection protocols for US chemical processing facilities. The guidelines are mandating documented containment integrity for corrosive fluid transfer equipment. Refinery and specialty chemical operators are responding by pre-qualifying sealless architectures in capital project specifications.
Aftermarket service unbundling is fragmenting traditional pump supplier relationships. End-users are separating spare parts procurement, field service, and predictive maintenance analytics across specialized vendors. This unbundling is most visible in Germany's water treatment sector, where municipal procurement frameworks favor multi-vendor service disaggregation.
Chemical Pump Market Segmentation
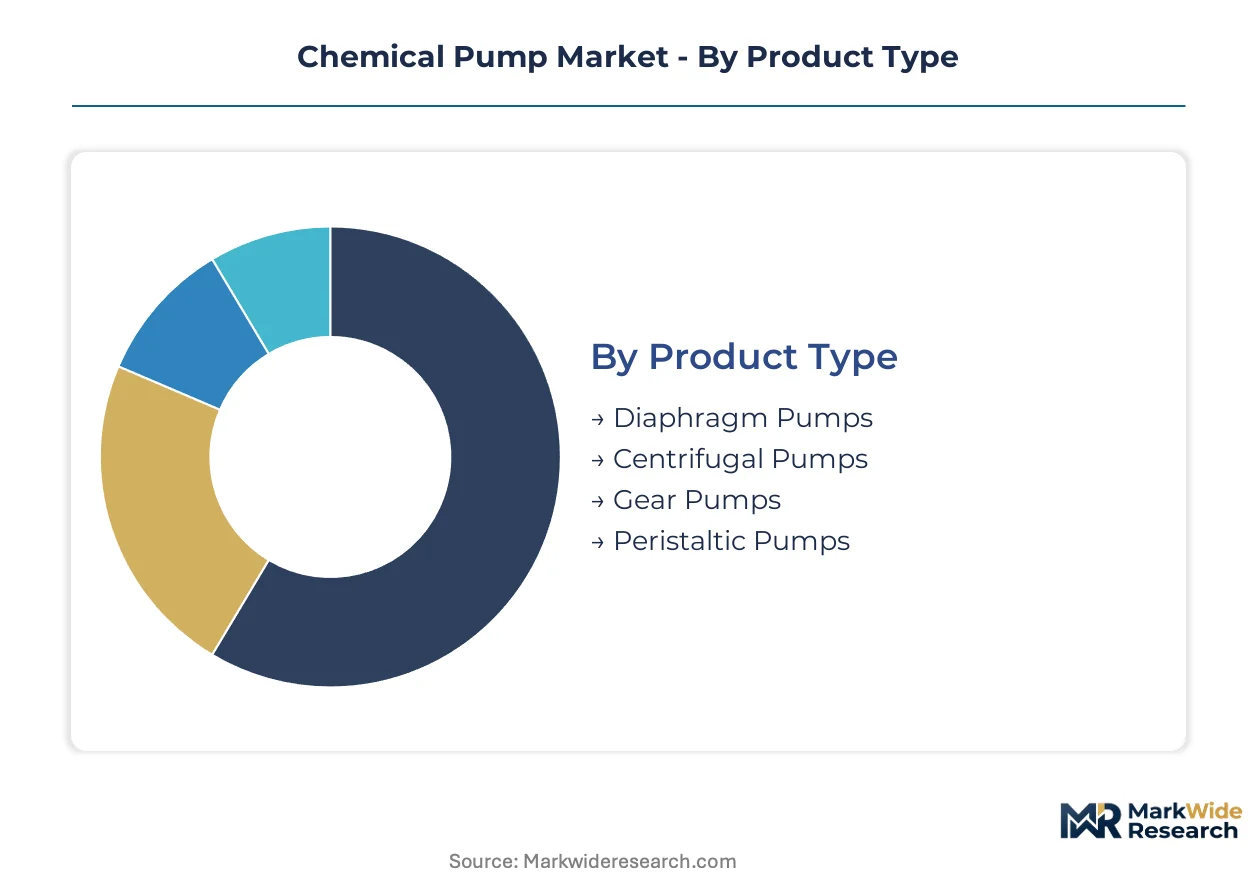
Chemical pump specification decisions cascade from fluid properties and duty severity into distinct product architectures. Segment boundaries reflect trade-offs between containment integrity, energy efficiency, and capital deployment flexibility across process industries.
Product Type:
Standalone pump units dominate bulk fluid transfer, while embedded configurations integrate into packaged process skids with shared controls and containment systems.
- Centrifugal Pumps:Impeller-driven designs handle high-volume, low-viscosity chemical transfers with stainless steel or alloy casings rated for continuous duty. Demand concentrates in US Gulf Coast petrochemical complexes where sour-service specifications mandate super-duplex metallurgy for acid handling.
- Diaphragm Pumps:Positive-displacement mechanisms deliver precise metering with zero leakage paths through elastomer or PTFE diaphragm isolation. Water treatment utilities in Germany specify these for chlorine and polymer dosing where stroke adjustability matches variable flow requirements.
- Gear Pumps:Intermeshing rotors provide steady, pulseless flow for viscous chemical feedstocks and polymer melts.
- Peristaltic Pumps:Hose compression designs eliminate wetted seals entirely, suiting abrasive slurries and shear-sensitive biological media.
Volume placements concentrate in Centrifugal Pumps; the faster expansion belongs to Diaphragm Pumps.
End User:
Capital intensity and regulatory exposure create divergent procurement patterns across customer categories.
- Oil & Gas:Upstream and downstream operators specify API-compliant pumps for hydrocarbon transfer, produced water reinjection, and refinery acid service. China's coastal chemical clusters drive replacement demand as MEE emission controls harden containment requirements for volatile organic compounds.
- Water Treatment:Municipal and industrial facilities deploy corrosion-resistant architectures for chemical disinfection, pH adjustment, and coagulant dosing. Procurement in Germany's Rhine-Ruhr corridor accelerates as infrastructure replacement timelines compress and REACH compliance forces material upgrades.
- Pharmaceuticals:cGMP manufacturing demands sealless magnetic drive systems with surface finish specifications down to Ra 0.4 micrometers for sterile processing.
- Manufacturing:General industrial chemical transfer spans plating baths, coolant systems, and cleaning chemical circulation with moderate specification intensity.
Revenue concentration sits with Oil & Gas; Pharmaceuticals exhibits the steepest expansion trajectory.
Installation:
Physical configuration determines maintenance accessibility, footprint constraints, and integration depth with surrounding process equipment.
- Stationary:Fixed-base installations anchor permanent process lines with dedicated piping, electrical, and containment infrastructure. US chemical processors favor these for continuous refinery duties where unplanned shutdowns carry substantial economic penalties.
- Portable:Skid-mounted or trolley-based units enable rapid redeployment across batch operations and temporary processing campaigns.
- Compact:Reduced-footprint designs squeeze into modular process skids and containerized treatment systems where space premiums dominate.
- Integrated:Pump-motor-control packages ship as pre-tested assemblies with unified documentation and single-source accountability.
Deployment frequency peaks with Stationary configurations; Compact formats are gaining share fastest in modular system builds.
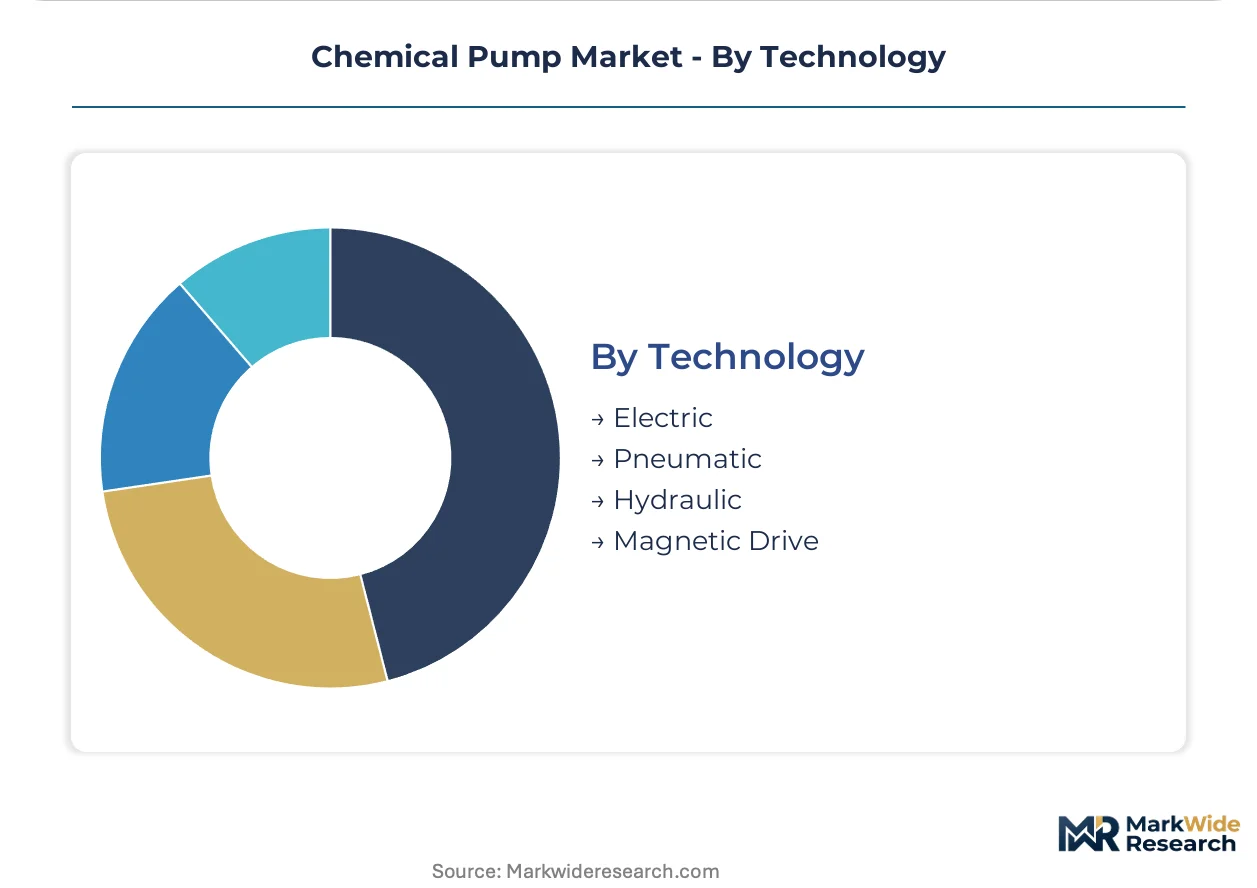
Technology:
Power transmission architecture governs efficiency, controllability, and leakage risk profiles across chemical handling duties.
- Magnetic Drive:Sealless torque transmission through containment shells eliminates mechanical seal wear and emissions. Chlor-alkali processors in China's coastal zones specify these as standard after MEE volatile organic compound rules tightened.
- Electric:Variable-frequency drive compatibility delivers precise flow control with efficiency ratings exceeding ninety percent in optimal duty points.
- Pneumatic:Compressed-air operation suits explosion-risk environments and remote locations without reliable electrical infrastructure.
- Hydraulic:Fluid power transmission delivers high torque density for viscous fluids and high-pressure injection duties.
Installed base dominance rests with Electric drives; Magnetic Drive architectures are climbing the fastest on emission mandate enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty steel foundries anchor metallurgical supply for super-duplex pump housings serving sour-service applications worldwide. This raw-material concentration shapes procurement patterns across downstream chemical processing clusters.
United States
EPA effluent limitation guidelines are tightening containment protocols for corrosive fluid transfer equipment in refinery and specialty chemical operations. The US Gulf Coast petrochemical corridor is driving brownfield expansion demand for high-temperature acid transfer pump skids. Municipal water treatment utilities are scaling corrosion-resistant system procurement as infrastructure replacement timelines compress.
Germany
Rhine-Ruhr chemical corridor operators are upgrading legacy installations as REACH compliance forces material specification changes for wetted components. The country's specialty steel base supplies super-duplex and Hastelloy feedstock to precision casting houses serving global pump manufacturers. Localized aftermarket service density anchors European demand through rapid response capabilities.
China
MEE volatile organic compound emission controls are hardening containment requirements across coastal chemical processing zones. Chlor-alkali processors in these clusters are specifying sealless magnetic drive architectures as standard for new installations. Yangtze River Delta and Pearl River Delta concentrations dominate procurement volume for hazardous fluid handling equipment.
India
Central Pollution Control Board mandates are accelerating adoption of leak-proof pump technologies in chemical manufacturing zones. Gujarat and Maharashtra industrial corridors are expanding chlor-alkali and pharmaceutical processing capacity requiring corrosion-resistant fluid handling systems. Domestic foundry capabilities in alloy steel castings are scaling to reduce import dependence for critical pump components.
Saudi Arabia
SABIC-led petrochemical expansion in the Eastern Province is creating demand for API-compliant pump systems in hydrocarbon transfer and acid service duties. The country's industrial diversification programs are attracting downstream chemical investments requiring high-integrity fluid containment. Local content requirements are incentivizing joint ventures for pump assembly and service operations.
Chemical Pump Market Vendor Landscape
Global majors compete with regional champions across metallurgical specialization and aftermarket service density. The vendor base stratifies into three tiers: integrated pump-metallurgy houses with captive foundry operations, modular platform specialists compressing lead times for standardized skids, and regional fabricators serving replacement parts demand. Dominant competitive moves include backward integration into super-duplex casting capabilities and geographic expansion through localized service partnerships.
Within the integrated metallurgy tier, Flowserve exemplifies premium positioning through in-house R&D control over high-temperature acid transfer materials. Sulzer anchors European demand through regional casting capabilities and dense aftermarket networks. KSB occupies a position in modular platform architectures that cut procurement cycles for standardized chemical process equipment. These three represent distinct strategic archetypes rather than direct substitutability.
| Leading Market Players |
|---|
| Flowserve |
| Sulzer |
| Grundfos |
| IDEX Corporation |
| LEWA GmbH |
| Sundyne |
| ProMinent GmbH |
| KSB |
| ITT Goulds Pumps |
| Others |
Supply Flow & Price Mechanics
Nickel alloy feedstock costs cascade through three distinct pricing tiers as super-duplex and Hastelloy casting premiums separate integrated foundry operators from assembly-only fabricators. German and Swedish specialty steel mills anchor upstream pricing power, while downstream buyers in water treatment and petrochemical procurement face divergent total-cost-of-ownership calculations based on metallurgical sourcing transparency.
Pricing Analysis
Warranty and aftermarket service bundling separates premium pump suppliers from unbundled competitors in municipal procurement frameworks. Three-tier pricing structure across premium, standard, and economy levels reflects metallurgical grade differentiation, with super-duplex housings commanding substantial premiums over 316L stainless configurations. Cost compression in standard-tier centrifugal pumps is intensifying because foundry capacity expansion in India is eroding legacy European cost structures. Municipal water treatment utilities exhibit the highest price sensitivity due to budget-constrained capital cycles, while pharmaceutical manufacturers show the least sensitivity given cGMP compliance requirements.
Supply Chain Analysis
Dual-sourcing mandates from major petrochemical operators in the US Gulf Coast and Germany's Rhine-Ruhr corridor are fragmenting foundry relationships across multiple qualified suppliers. Supply concentrates in Germany, Sweden, and India for specialty steel castings, with downstream assembly scaling in China and the United States. Raw material dependencies center on nickel, chromium, and molybdenum alloys subject to commodity exchange volatility. Single-source vulnerability persists for super-duplex solidification modeling expertise concentrated at a handful of European technical institutions. Distribution runs through OEM direct sales for large project orders and specialized distributors for replacement parts and aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where REACH chemical restrictions and EPA effluent standards erect formidable barrier-to-entry moats for players with pre-qualified material certifications.
For Market Incumbents: Cement metallurgical R&D control through captive super-duplex casting capabilities or exclusive foundry partnerships, insulating against commodity-grade entrants from low-cost manufacturing bases. Deepen aftermarket service density in Germany's water treatment corridor where municipal procurement fragmentation rewards localized response capabilities. Magnetic drive sealless technology displacement of conventional sealed pumps represents the primary substitution threat requiring pre-emptive portfolio repositioning.
For New Entrants and Emerging Players: Enter via modular platform architectures for standardized chemical process skids where lead time compression opens specification access without full metallurgical integration. Target India's Central Pollution Control Board enforcement zones where domestic foundry scaling reduces import dependence and creates local partnership opportunities. Chlor-alkali processing in China's coastal clusters offers the most penetrable application segment given MEE emission mandate urgency and magnetic drive standardization trends.
For Investors and Strategic Acquirers: EPA state implementation plan adoption timelines for PFAS restrictions are the leading indicator that coating chemistry transitions will consolidate supplier tiers around compliant players. Long-term viability favors integrated pump-metallurgy houses with backward casting control and dense European service networks. Acquisition targets should display super-duplex corrosion-fatigue testing capabilities and established REACH documentation protocols. Divergence in multi-jurisdiction PFAS phasedown schedules would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Casting | Captive super-duplex supply secures margin control against nickel alloy volatility. |
| Modular Platform Standardization | Configurable metallurgy cuts lead times for chemical process skid procurement cycles. |
| Sealless Magnetic Drive Expansion | EPA and MEE emission mandates are hardening containment specification preferences. |
| Localized Aftermarket Service Density | Rhine-Ruhr municipal procurement fragmentation rewards rapid-response maintenance networks. |
| PFAS-Compliant Coating Transition | REACH and EPA phasedown timelines eliminate conventional chemistries before alternatives scale. |
Methodological Framework
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone for volume and value estimation, supplemented by technical documentation from EPA and ECHA regulatory repositories. Primary interviews with plant engineers at chlor-alkali processors, procurement leads at water treatment utilities, aftermarket service heads at pump distributors, and metallurgical R&D directors at specialty foundries validated segmentation assumptions and growth driver weightings. Bottom-up unit economics and top-down macroeconomic indicators were triangulated to anchor forecast plausibility.
Historical trendline analysis across installed base replacement cycles and capital project pipelines established baseline growth trajectories over the projection horizon. Segmentation modeling incorporated product architecture, end-use industry, installation configuration, and power transmission technology dimensions. CAGRs were derived from regression analysis against industrial production indices and regulatory enforcement timelines. Forecast inputs included nickel alloy price volatility bands and municipal infrastructure spending authorization patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt PFAS restriction acceleration or nickel supply disruption scenarios. Projections reflect assumptions regarding REACH implementation consistency and MEE enforcement continuity across China's coastal chemical clusters. Deviation in specialty steel foundry capacity expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Membrane Pump Market