
 Global High Pressure Pumps Market | 2026-2036
Global High Pressure Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Pressure Pumps Market Analysis
China is rewriting capacity dynamics in high-pressure pump manufacturing as domestic foundries and precision machining clusters scale output for export markets. Sulzer Ltd. leverages its Swiss engineering heritage to sustain premium positioning in abrasive slurry applications. Kamat GmbH & Co. KG anchors German demand through specialized plunger pump systems serving industrial cleaning and waterjet cutting. Cat Pumps dominates niche markets with triplex positive displacement designs that control aftermarket parts revenue.
High pressure pumps are mechanical devices engineered to generate discharge pressures exceeding 40 bar, utilizing positive displacement or centrifugal force principles to move liquids against substantial resistance in industrial process loops. Positive displacement configurations, particularly reciprocating and diaphragm variants, command margin pools where leak-tight operation proves critical for chemical injection and hazardous fluid transfer. Centrifugal designs lead volume in water treatment and power generation cooling circuits where continuous duty cycles and lower maintenance intensity offset higher initial capital outlay. Oil and gas end users increasingly specify portable installation formats for offshore platform maintenance, while stationary configurations retain share in permanent refining and mining infrastructure.
The US EPA enforces effluent limitation guidelines that compel water treatment operators to upgrade to higher-pressure membrane feed systems, tightening pump material and sealing specifications. EU REACH compliance and CE marking requirements restrict certain elastomer compounds in wetted components, redirecting sourcing toward perfluoroelastomer and advanced ceramic alternatives. India's BIS certification mandates pressure vessel alignment for imported pumping equipment, creating procedural friction for non-domestic suppliers. Stakeholders must monitor how carbon border adjustment mechanisms and evolving efficiency standards reshape total cost of ownership calculations across procurement cycles.
Market Dynamics
EU F-Gas Regulation enforcement is compressing refrigerant containment standards across industrial cooling applications, forcing OEMs to abandon traditional seal designs in favor of diaphragm architectures that eliminate fugitive emissions from high-pressure process loops.
Growth Catalysts
- Desalination infrastructure buildout:Water treatment utilities in India and China are scaling membrane feed system procurement to address freshwater scarcity, with BIS certification aligning pressure vessel specifications to accelerate domestic manufacturing absorption.
- REACH compliance migration:ECHA restrictions on elastomer compounds in wetted pump components are redirecting material sourcing toward perfluoroalkoxy and advanced ceramic alternatives, opening specification windows for seal-less architectures.
- Offshore platform maintenance formats:Oil and gas operators in the US Gulf Coast petrochemical corridor are specifying portable high-pressure pump configurations for hydrostatic testing, displacing fixed-installation capital commitments with rental and service-based access models.
Market Restraints
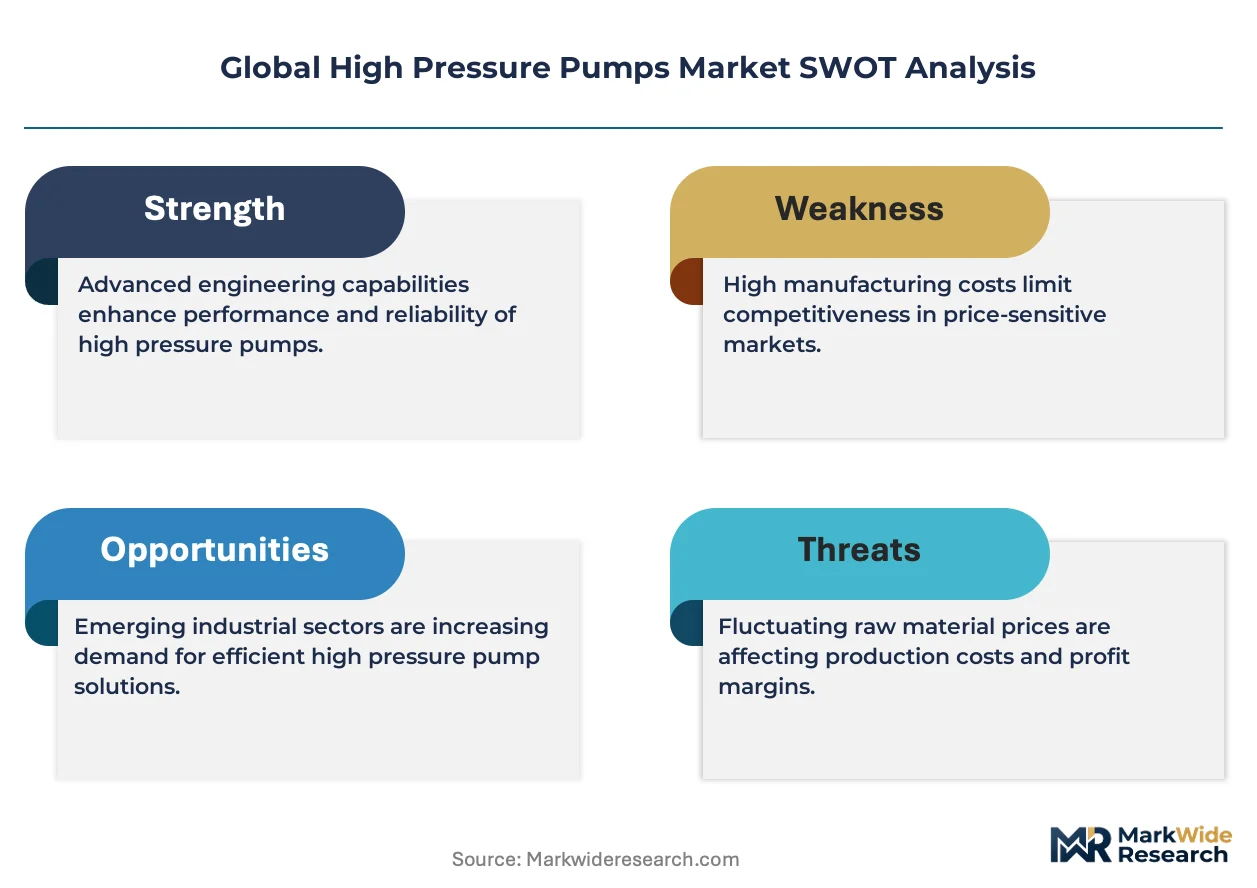
- Specialized alloy input volatility:Duplex stainless steel and superalloy pricing fluctuations for plunger and diaphragm pump components compress margin predictability for precision-machined pressure vessels.
- Foundry concentration risk:Precision casting capacity for high-pressure pump housings concentrates in select Chinese manufacturing clusters, exposing procurement timelines to regional logistics disruptions.
- Centrifugal technology substitution:Continuous-duty water treatment and power generation cooling applications favor lower-maintenance centrifugal designs over positive displacement alternatives, capping addressable volume in process-critical segments.
Strategic Opportunities
- Carbon border adjustment positioning:EU CBAM implementation creates first-mover advantage for pump manufacturers with documented lifecycle emissions data and low-carbon foundry sourcing.
- Waterjet cutting system integration:Industrial cleaning and precision machining applications are converging high-pressure plunger pumps with abrasive delivery systems, expanding specification scope beyond standalone pump sales.
- Wastewater reuse mandates:US EPA effluent limitation guidelines are compelling municipal operators to upgrade membrane bioreactor feed pressures, tightening material specifications that favor premium diaphragm pump suppliers.
Industry Challenges
- Precision machining talent scarcity:Multi-axis CNC programming and superalloy finishing expertise for high-pressure sealing surfaces remains concentrated among aging specialist workforces in Germany and Switzerland.
- CE marking timeline compression:EU machinery directive conformity assessment for seal-less pump designs requires extended third-party validation cycles that delay product launch windows.
- Legacy system integration friction:Retrofitting diaphragm pump architectures into existing chemical injection skids demands custom manifold fabrication and control system recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Pressure Pumps Market |
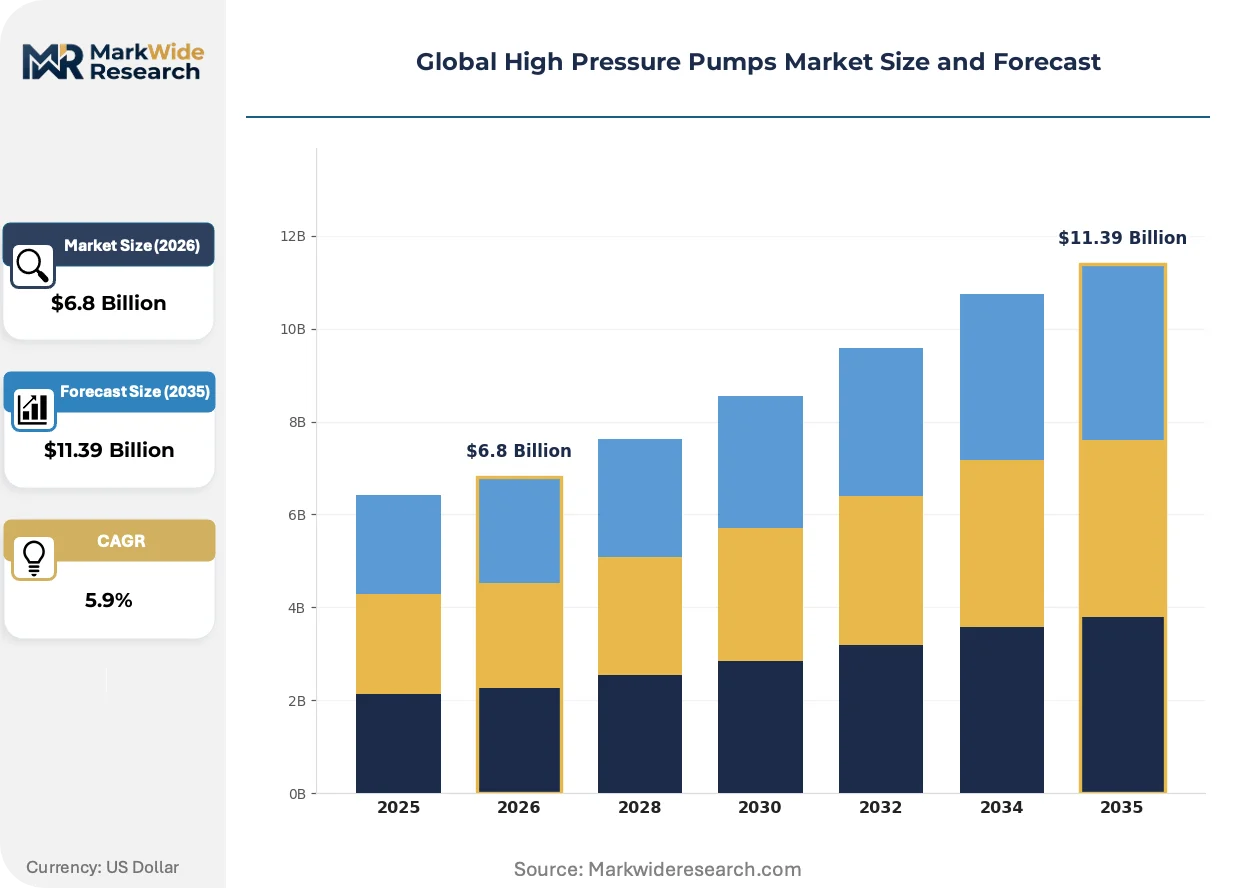
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Centrifugal, Diaphragm, Reciprocating End User: Oil & Gas, Water Treatment, Mining, Power Generation Installation: Onshore, Offshore, Portable, Stationary Application: Fluid Transfer, Chemical Injection, Hydrostatic Testing, Cleaning |
| Companies Covered | Grundfos Holding A/S, Sulzer Ltd., Andritz AG, Danfoss A/S, GEA Group, The Weir Group PLC, Cat Pumps, Kamat GmbH & Co. KG, Hammelmann GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Pressure Pumps Market Emerging Trajectories
Digital twin architectures are virtualizing pump performance validation, compressing physical prototyping cycles while enabling predictive maintenance monetization. Three developments are restructuring competitive positioning.
Sensor-embedded diaphragm pump systems are virtualizing real-time condition monitoring for seal-less chemical injection applications. Offshore platform operators in the North Sea are deploying these architectures to eliminate manual inspection cycles. The technology is virtualizing traditional aftermarket parts revenue into subscription-based performance guarantees.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant pump containment redesigns across industrial cooling OEM supply chains. ECHA documentation requirements for fluorinated gas equipment are extending procurement qualification timelines. European HVAC and process cooling segments are responding by consolidating supplier panels around certified seal-less pump specialists.
Service unbundling is fragmenting traditional pump procurement into performance-based access agreements. Water treatment operators in California and Texas are separating capital equipment ownership from maintenance liability through rental and outcome-guarantee structures. This model is most visible in desalination pre-treatment applications where membrane fouling risk shifts to equipment providers.
Global High Pressure Pumps Market Segmentation
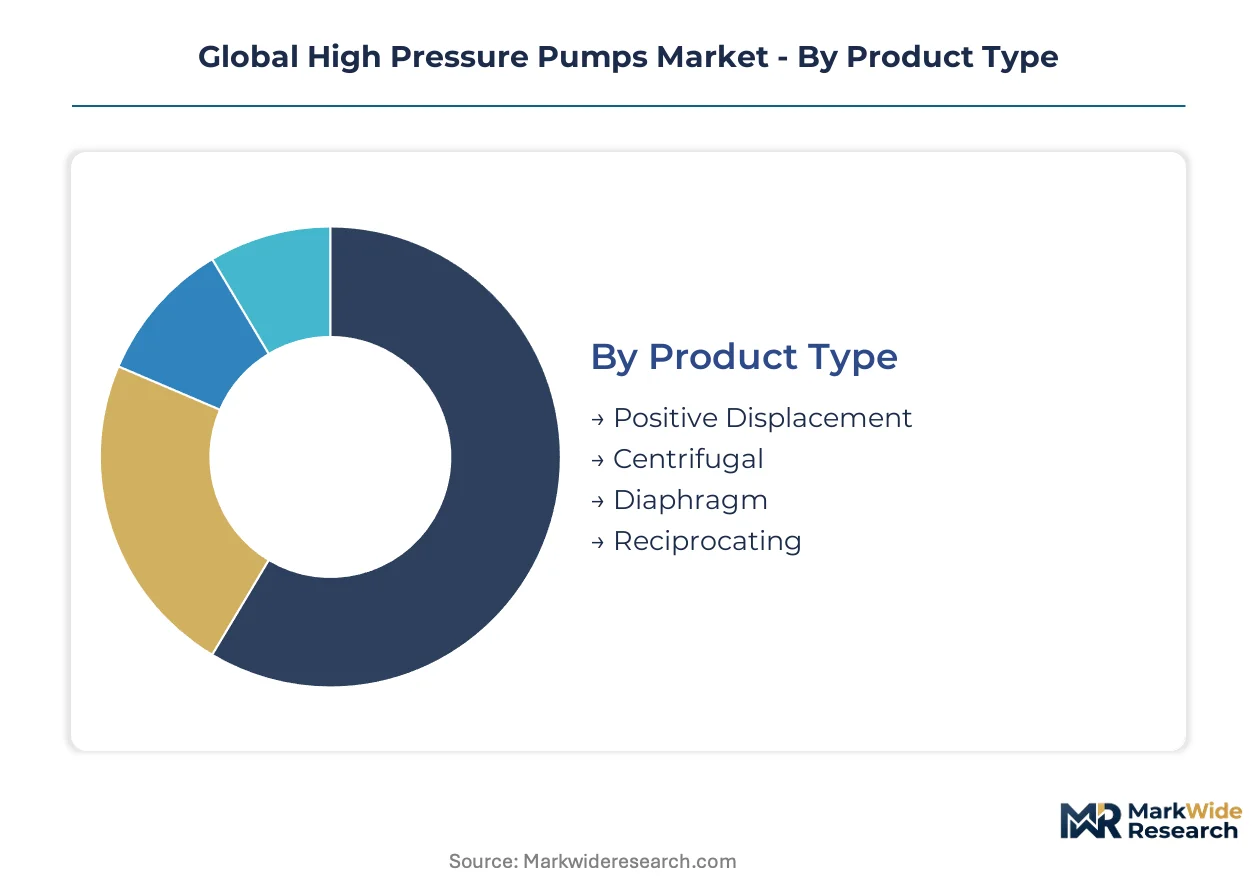
High-pressure pump procurement patterns diverge sharply across operating environments, pressure specifications, and maintenance intensity requirements. Segmentation reveals how technology selection maps to capital deployment cycles and regulatory exposure in process industries.
Product Type:
Positive displacement architectures dominate chemical injection and hazardous fluid transfer where leak-tight integrity commands specification priority; centrifugal designs capture continuous-duty water treatment and power generation cooling circuits where maintenance minimization outweighs first-cost premiums.
- Positive Displacement:Reciprocating and rotary mechanisms compress fixed fluid volumes against system resistance, achieving pressure ratios exceeding 1000 bar in plunger configurations. Oil & gas operators in the US Gulf Coast petrochemical corridor specify these for chemical injection skids where seal integrity failure carries environmental liability exposure.
- Centrifugal:Rotodynamic impellers convert kinetic energy to pressure head through velocity transformation, sustaining continuous duty cycles with lower parts replacement frequency. Water treatment utilities in India and China deploy these for membrane feed systems where capital efficiency and energy recovery integration prove decisive.
- Diaphragm:Flexible membrane isolation eliminates seal wear paths, satisfying EU F-Gas Regulation containment mandates for refrigerant and process gas applications.
- Reciprocating:Plunger and piston variants deliver precise flow control for hydrostatic testing and waterjet cutting where pressure accuracy determines output quality.
Established volume favors centrifugal designs; emerging adoption favors diaphragm architectures.
End User:
Capital intensity and regulatory stringency vary dramatically across downstream sectors, fragmenting specification authority between procurement engineering and environmental compliance functions.
- Oil & Gas:Exploration, production, and refining operations demand portable configurations for offshore platform maintenance and permanent installations for pipeline hydrostatic testing. US EPA effluent guidelines tighten material specifications for produced water reinjection pumps.
- Water Treatment:Desalination pre-treatment, membrane bioreactor feed, and wastewater reuse applications concentrate procurement in coastal utilities facing freshwater scarcity. BIS certification in India and GB standards in China localize supply chain requirements.
- Mining:Slurry transport and process water recovery systems specify abrasive-resistant metallurgy for extended wear life in remote installations.
- Power Generation:Cooling tower circulation and boiler feed applications favor centrifugal designs with energy recovery integration for combined-cycle efficiency.
Mature replacement cycles dominate power generation; steepest expansion trajectory concentrates in water treatment infrastructure buildout.
Installation:
Asset ownership models are fragmenting between capital-intensive permanent infrastructure and service-based access formats that shift maintenance liability to equipment providers.
- Onshore:Fixed-site refining, chemical processing, and municipal water facilities specify stationary configurations with integrated control systems for automated process loop integration.
- Offshore:Platform maintenance and subsea intervention demand compact, corrosion-resistant packages with rapid deployment capability for weather-window-constrained operations.
- Portable:Rental and service-based access models displace ownership in hydrostatic testing and industrial cleaning where utilization rates vary seasonally.
- Stationary:Permanent mining and refining infrastructure anchors multi-decade procurement relationships with aftermarket parts revenue concentration.
Stationary configurations retain margin stability; portable formats are gaining share fastest in service-unbundled procurement.
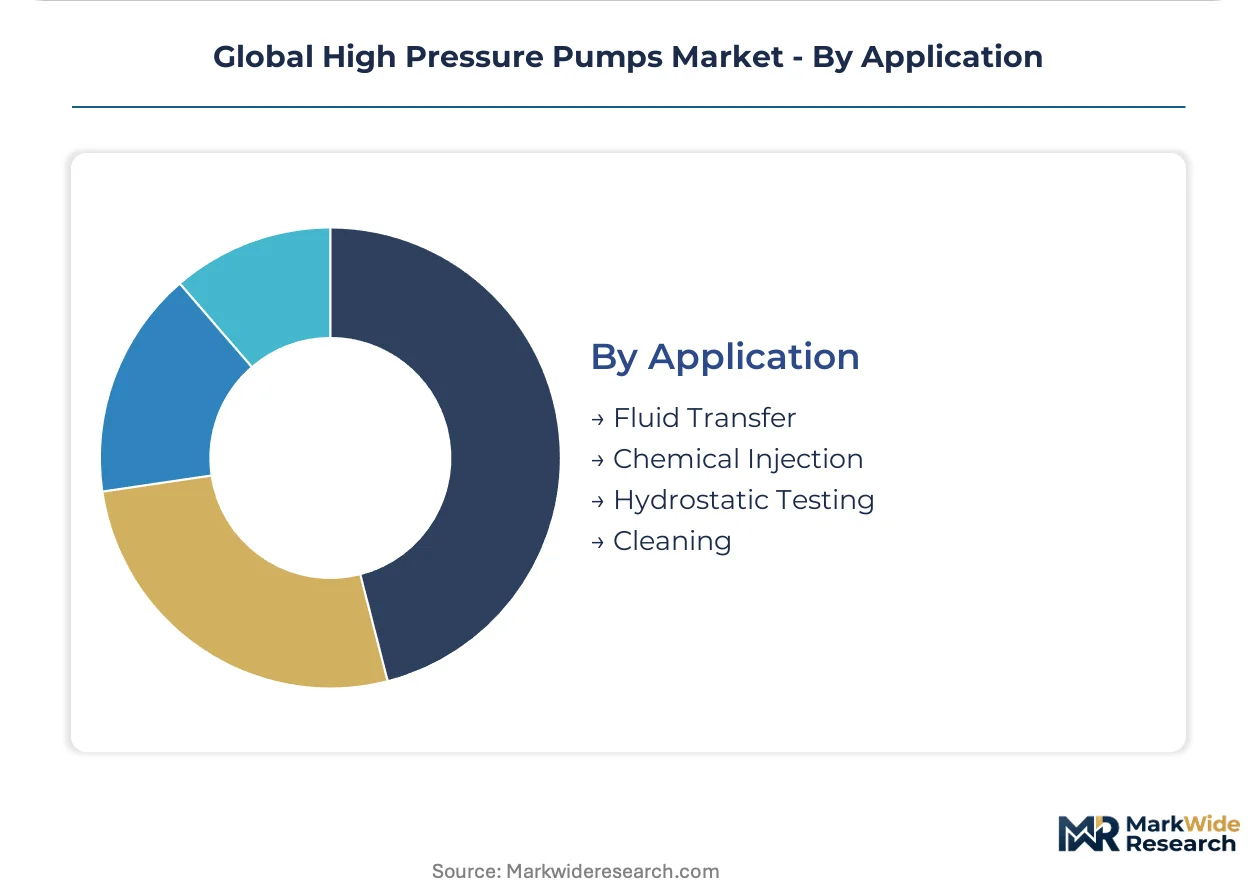
Application:
Pressure specification and fluid compatibility requirements determine material selection and sealing architecture across process-critical and utility-scale deployments.
- Fluid Transfer:Continuous circulation of process liquids and slurries in refining and mining operations specifies abrasion-resistant metallurgy and variable frequency drive integration.
- Chemical Injection:Precise additive metering for corrosion inhibition and flow assurance demands seal-less diaphragm or packed plunger designs with pulsation dampening.
- Hydrostatic Testing:Pipeline and pressure vessel integrity verification requires portable positive displacement units with pressure holding accuracy and data logging compliance.
- Cleaning:Industrial surface preparation and waterjet cutting converge high-pressure plunger pumps with abrasive delivery systems for precision machining applications.
Fluid transfer commands installed base volume; chemical injection specification intensity is climbing the fastest under tightening containment regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent limitation guidelines anchor North American demand, while EU F-Gas Regulation phase-downs redirect European procurement toward seal-less architectures. BIS certification and GB standards reshape supply chain localization across Asia-Pacific manufacturing clusters.
United States
Gulf Coast petrochemical operators specify portable configurations for offshore platform hydrostatic testing and chemical injection skids. EPA enforcement tightens material specifications for produced water reinjection pumps. Houston anchors procurement concentration for abrasive slurry applications serving refining and mining corridors.
Germany
Industrial cleaning and waterjet cutting applications sustain specialized plunger pump demand from precision machining clusters. ECHA REACH compliance redirects elastomer sourcing toward perfluoroalkoxy alternatives. Baden-Württemberg and North Rhine-Westphalia concentrate engineering talent for multi-axis CNC finishing of superalloy sealing surfaces.
China
Domestic foundries and precision machining clusters scale membrane feed system output for desalination and wastewater reuse infrastructure. GB standards and MIIT dual carbon goals accelerate efficiency mandates for power generation cooling circuits. Yangtze River Delta manufacturing bases absorb BIS-aligned pressure vessel specifications for export markets.
India
Water treatment utilities scale procurement for coastal desalination and municipal membrane bioreactor installations. BIS certification mandates pressure vessel alignment for imported pumping equipment, creating procedural friction for non-domestic suppliers. Gujarat and Maharashtra industrial corridors localize casting capacity for high-pressure pump housings.
Switzerland
Swiss engineering heritage sustains premium positioning in abrasive slurry and process-critical applications. CE marking requirements under EU machinery directives extend conformity assessment timelines for seal-less designs. Precision machining expertise concentrates around aging specialist workforces serving global OEM supply chains.
Global High Pressure Pumps Market Vendor Landscape
European engineering heritage specialists and Asian scale manufacturers split the market along specification intensity and cost efficiency vectors. The vendor base concentrates around three strategic archetypes: precision-engineered premium specialists, integrated industrial conglomerates, and focused niche displacement experts. Consolidation pressures favor M&A activity among mid-tier fabricators seeking geographic expansion, while technology licensing agreements accelerate seal-less architecture penetration across refrigerant and chemical process applications.
Among European precision engineering groups, Sulzer Ltd. and Kamat GmbH & Co. KG exemplify heritage-tier positioning through specialized plunger and diaphragm system expertise. Cat Pumps occupies a position within the focused displacement segment, anchoring aftermarket revenue concentration through triplex positive displacement designs. Grundfos Holding A/S and Danfoss A/S represent integrated conglomerate archetypes with broad industrial fluid handling portfolios spanning multiple pressure specifications and end-use verticals.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Sulzer Ltd. |
| Andritz AG |
| Danfoss A/S |
| GEA Group |
| The Weir Group PLC |
| Cat Pumps |
| Kamat GmbH & Co. KG |
| Hammelmann GmbH |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese precision machining clusters is compressing margin capture for mid-tier pump fabricators while simultaneously enabling aggressive export pricing that reshapes procurement negotiations across water treatment utilities in India and Southeast Asia. This utilization dynamic forces European heritage manufacturers toward premium diaphragm architectures where seal-less technology commands specification loyalty despite higher first-cost outlay.
Pricing Analysis
Geographic price spreads between Swiss-engineered premium units and Chinese-manufactured standard configurations exceed three-to-one multiples across desalination membrane feed applications. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in economy-tier centrifugal pumps is intensifying because Yangtze River Delta foundries are absorbing alloy input volatility through volume scale. Municipal water treatment operators in India demonstrate highest price sensitivity, while offshore oil and gas contractors prioritize leak-tight integrity over capital expenditure minimization.
Supply Chain Analysis
Upstream duplex stainless steel and superalloy feedstock sourcing draws from German specialty steel mills, Chinese integrated producers, and Japanese precision metallurgy suppliers. High-pressure pump housing castings hinge on foundry capacity concentrated in China's Jiangsu and Zhejiang provinces, with secondary precision finishing anchored in Baden-Württemberg machining clusters. Single-source vulnerability persists for superalloy plunger components serving abrasive slurry applications. Distribution runs through OEM-direct contracting for large infrastructure projects and rental-service intermediaries for portable hydrostatic testing formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global High Pressure Pumps Market sits in early-cycle expansion as EU F-Gas Regulation phase-downs force refrigerant containment redesigns across industrial cooling OEM supply chains, opening specification windows for seal-less architectures that displace legacy packed pump installations.
For Market Incumbents: Build switching-cost moats through sensor-embedded diaphragm systems that virtualize aftermarket revenue into subscription-based performance guarantees. Deepen backward integration into superalloy finishing capacity in Switzerland and Germany to defend margin position against Chinese scale competitors. CE marking timeline compression for seal-less designs represents a regulatory threat that favors early certification investment. For New Entrants and Emerging Players: Establish a beachhead in portable hydrostatic testing rentals serving US Gulf Coast petrochemical maintenance cycles where utilization-based access models displace capital ownership. Waterjet cutting system integration offers the most penetrable white-space target, converging plunger pumps with abrasive delivery architectures beyond standalone pump sales. Pursue outcome-guarantee contracting that shifts membrane fouling liability to equipment providers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across diaphragm pump sub-segments as digital twin architectures compress physical prototyping cycles. Long-term viability over the coming decade favors precision-engineered specialists with documented lifecycle emissions data for EU CBAM positioning. Acquisition target archetype: mid-tier German or Swiss fabricators with superalloy machining expertise and aging founder transition dynamics. The signal to watch is carbon border adjustment mechanism implementation timelines that reward first-mover low-carbon sourcing documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Seal-Less Architecture Certification | CE marking investment captures EU F-Gas Regulation-driven specification shifts ahead of competitor compliance timelines. |
| Digital Twin Integration | Virtualized performance validation compresses R&D cycles while enabling predictive maintenance subscription monetization. |
| Low-Carbon Foundry Sourcing | Documented lifecycle emissions data secures first-mover advantage under EU CBAM implementation for export markets. |
| Waterjet System Convergence | Plunger pump integration with abrasive delivery expands addressable scope beyond standalone equipment sales. |
| Service Unbundling Partnerships | Rental and outcome-guarantee structures align with California and Texas municipal procurement preference shifts. |
Methodological Framework
Operator-level perspectives from maintenance directors at water treatment utilities, procurement leads at oil and gas operators, plant engineers in petrochemical corridors, and aftermarket service heads at pump OEMs anchored the qualitative base. These primary insights combined with secondary validation from customs and trade data, SEC 10-K filings, ECHA REACH documentation, and BIS certification registries. Bottom-up volume modeling across pressure specifications and installation formats triangulated against top-down industry spend analysis.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic, baseline, and constrained demand pathways reflecting varying desalination infrastructure buildout paces and refrigerant regulation enforcement intensity. Segmentation dimensions modeled include product type, end-use vertical, installation format, and regional regulatory cluster. CAGRs derived from historical shipment data and capacity absorption rates incorporated alloy input cost trajectories and efficiency standard evolution as industry-specific forecast inputs.
Stress conditions across superalloy price volatility, foundry logistics disruption, and EU machinery directive timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure spending continuity and regulatory enforcement intensity. Cross-checking against EIA industrial energy consumption benchmarks and IEA water sector investment tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Pump Over Tanks Market