
 Vertical Immersion Pumps Market | 2026-2036
Vertical Immersion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Immersion Pumps Market Outlook
Multi-source procurement for critical pump assemblies is expanding as plant operators reduce dependency on single OEM service networks. KSB leverages its European manufacturing footprint to sustain aftermarket parts availability across chemical corridors. Flowserve competes through vertical integration into specialty metallurgy, controlling alloy supply for sulfuric acid service. EBARA Corporation anchors its position in Asian energy infrastructure, dominating nuclear coolant and thermal power applications.
A vertical immersion pump is a centrifugal or positive-displacement unit with its motor and hydraulic end fully submerged in the pumped fluid, typically constructed from stainless steel, duplex alloys, or fluoropolymer-lined housings to achieve seal-less operation at depths exceeding 10 meters. Its primary purpose is to transfer corrosive, abrasive, or high-temperature liquids without shaft seals exposed to atmosphere, eliminating leakage paths in hazardous fluid handling. Submersible configurations lead the product landscape due to their proven reliability in deep sump drainage and raw water intake, while magnetic drive types capture expanding margin pools as chemical processors adopt zero-emission mandates. Water treatment applications represent the largest volume outlet, though oil and gas retrofit activity is accelerating fastest as offshore platforms replace legacy vertical turbine installations with compact immersion units.
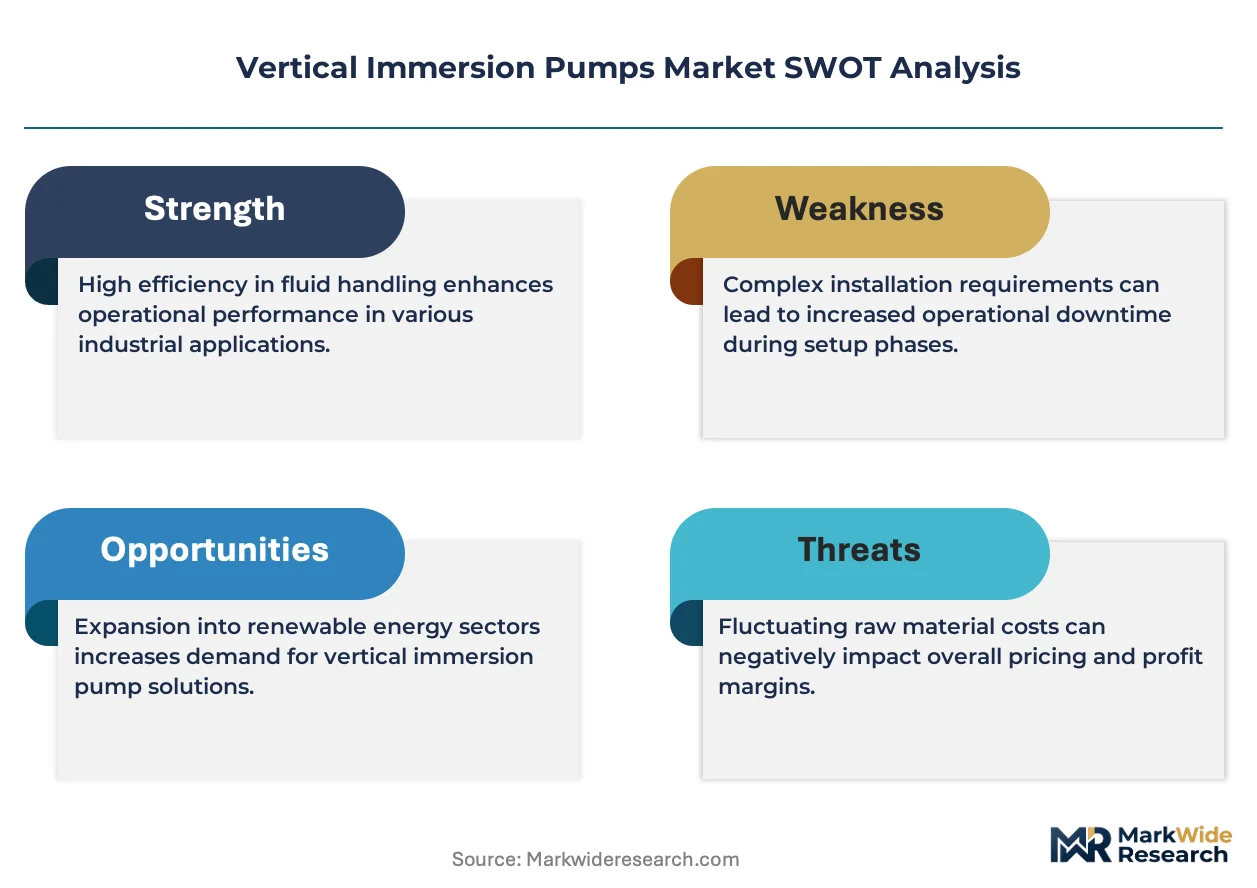
The EPA enforces Clean Water Act discharge standards that shape municipal procurement specifications for wastewater immersion systems, while OSHA's Process Safety Management rules mandate seal-less pump architectures in highly hazardous chemical service. REACH compliance in Europe restricts certain elastomer and coating chemistries, redirecting material selection toward perfluoroalkoxy and advanced ceramic options. Stakeholders must monitor evolving alloy cost volatility and regional carbon border adjustments that will reshape total cost of ownership calculations for cross-border pump sourcing.
Market Dynamics
Chemical processors are consolidating pump specifications around seal-less magnetic drive architectures as the EU F-Gas Regulation tightens emissions accountability for industrial rotating equipment. This regulatory compression is forcing alloy selection toward higher-grade materials while reshaping competitive positioning around captive metallurgy capabilities.
Growth Catalysts
- REACH Compliance Migration:European chemical processors are retiring elastomer-sealed pumps ahead of restricted substance deadlines. This is accelerating specification of perfluoroalkoxy-lined immersion systems in German and Dutch refining corridors.
- Offshore Platform Retrofit Cycles:North Sea and Gulf of Mexico operators are replacing legacy vertical turbine installations with compact immersion units. The shift eliminates atmospheric shaft seals in hazardous zone classifications.
- Nuclear Coolant Infrastructure:Asian energy utilities are expanding sealed circulation systems for pressurized water reactor maintenance. Japanese and South Korean reactor fleets require zero-leakage coolant handling for primary loop service.
Market Restraints
- Super-Duplex Alloy Volatility:Nickel and molybdenum price swings compress margin predictability for sulfuric acid service pumps. Foundry capacity concentrates in Scandinavian and Austrian supplier networks.
- Extended Certification Timelines:ATEX and IECEx testing protocols for explosive atmosphere pumps now exceed fourteen months. This delays revenue recognition for customized magnetic drive configurations.
- Substitution by Air-Operated Diaphragm Pumps:Low-pressure chemical transfer applications below five bar are migrating to pneumatic alternatives. AODD pumps avoid motor submersion complexity in intermittent duty cycles.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing Expansion:CDSCO-compliant sterile processing facilities require seal-less pumps for active pharmaceutical ingredient synthesis. Domestic production incentives under the PLI scheme attract captive pump assembly investments.
- Hydrogen Economy Electrolyte Handling:PEM and alkaline electrolyzer plants need corrosion-resistant circulation for potassium hydroxide and deionized water loops. This application remains underpenetrated by established immersion pump portfolios.
- Carbon Border Adjustment Positioning:EU CBAM implementation favors regional manufacturing footprints with documented alloy provenance. German and Italian producers can leverage captive foundry emissions data for tender advantage.
Industry Challenges
- Specialized Welding Certification Scarcity:ASME IX-qualified orbital welders for super-duplex pump casings command premium labor rates. Training pipelines have not kept pace with demand from nuclear and chemical sectors.
- Legacy DCS Integration Complexity:Brownfield chemical plants operate proprietary control architectures from the 1990s. New smart pump monitoring systems require costly protocol translation gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Immersion Pumps Market |
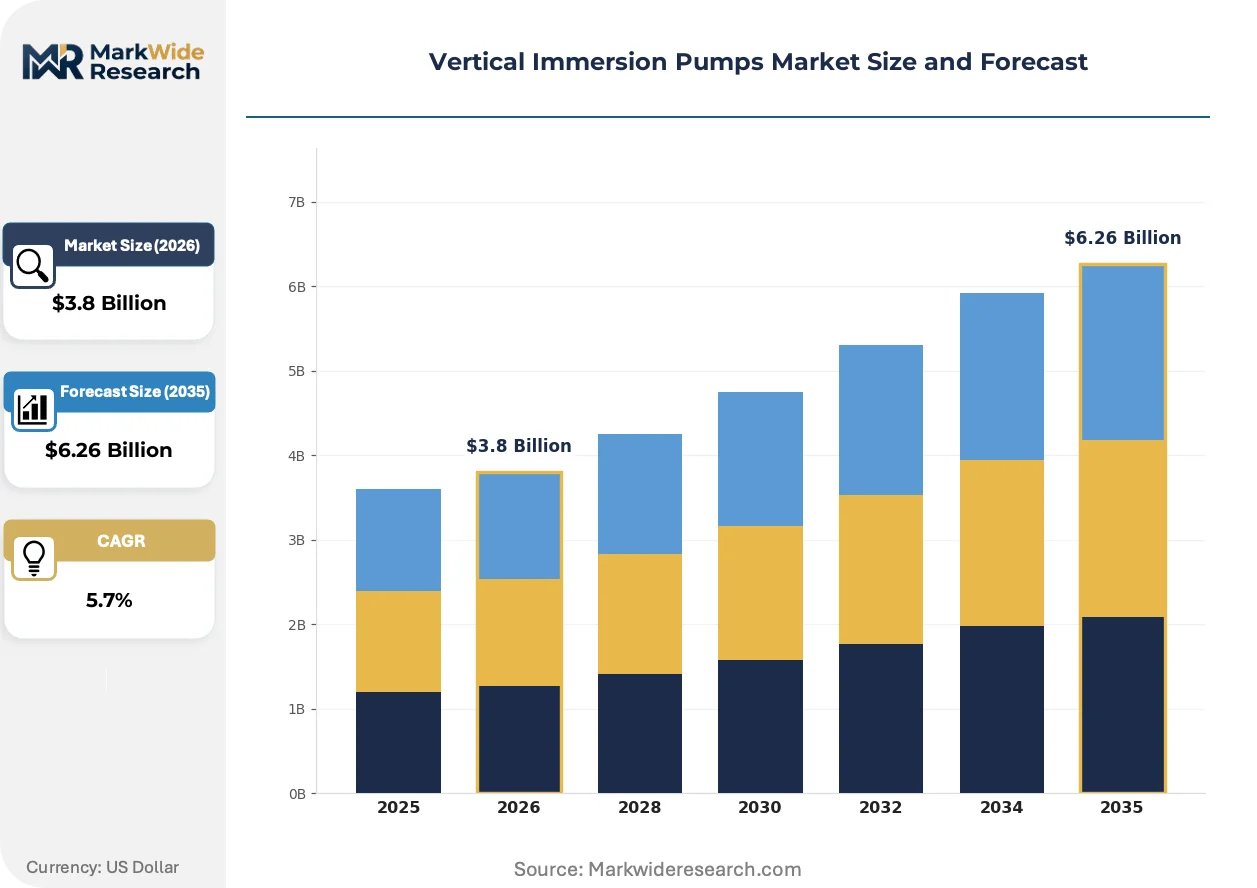
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Venturi, Magnetic Drive, Diaphragm Application: Water Treatment, Chemical Processing, Oil & Gas, Agriculture End User: Mining, Manufacturing, Energy, Municipal Installation: Fixed, Portable, Modular, Customized |
| Companies Covered | Ruhrpumpen Group, KSB, Gusher Pumps, Sulzer, Flowserve, EBARA Corporation, Weir Group, ITT Inc., Lutz-JESCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Immersion Pumps Market Strategic Shifts
Equipment architectures are fragmenting into standardized sub-assemblies that accelerate field reconfiguration and reduce spare parts proliferation. This modular decomposition is compressing lead times while enabling regional customization without full redesign cycles.
Cartridge seal replacement systems are modularizing wet-end maintenance for chemical service pumps. BASF and Dow facilities in Antwerp and Ludwigshafen are specifying cartridge-compatible immersion units to reduce confined-space entry during turnaround events. The approach is compressing mean-time-to-repair from days to hours in hazardous fluid applications.
The EPA's Clean Water Act enforcement is tightening municipal procurement specifications for wastewater immersion systems. Discharge standard violations now trigger consent decrees that mandate seal-less architectures in publicly owned treatment works. California and Texas utilities are prioritizing magnetic drive configurations in raw sewage lift station retrofits.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts. Large chemical processors in the US Gulf Coast are directly engaging third-party pump rebuild shops for wet-end overhauls. This bypasses factory service networks and compresses pricing power for original equipment suppliers in the Houston Ship Channel corridor.
Vertical Immersion Pumps Market Segmentation
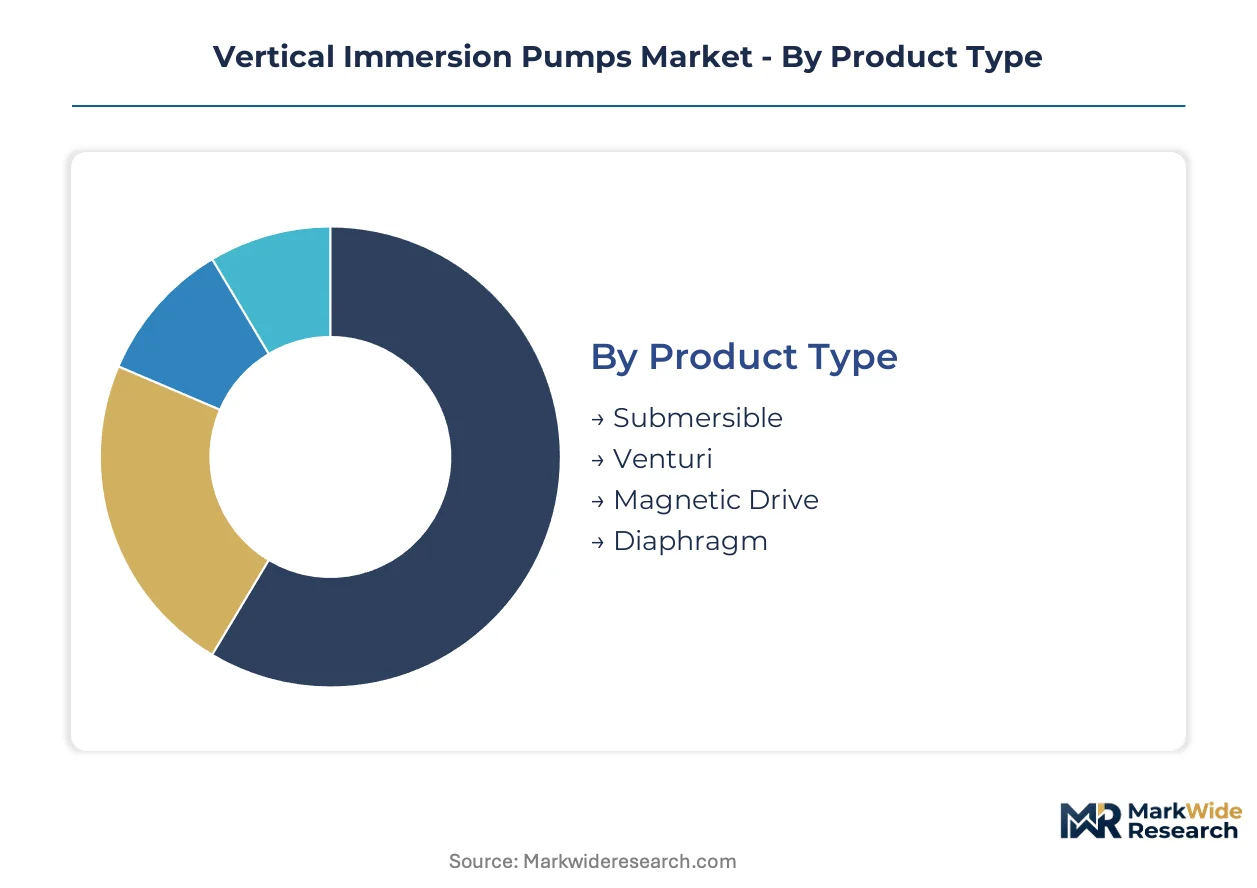
Immersion pump procurement splits sharply between high-volume standardized units for water infrastructure and engineered-to-order systems for hazardous chemical service. Specification committees in chemical processing and nuclear energy prioritize seal-less architectures, while municipal buyers optimize for lifecycle cost in corrosive wastewater environments.
Product Type:
Submersible configurations dominate unit shipments, yet magnetic drive systems capture disproportionate margin pools through zero-emission compliance premiums.
- Submersible:These units submerge motor and hydraulic end in a single sealed housing, typically constructed from cast iron or 316 stainless steel for raw water intake and sump drainage. German automotive supplier networks and Dutch municipal water authorities specify these for coolant circulation and flood control, driven by proven reliability in continuous-duty deep sump applications.
- Magnetic Drive:Seal-less architectures transmit torque through containment shells, eliminating atmospheric leakage paths in hazardous fluid handling. EU F-Gas Regulation enforcement is accelerating specification of these systems in Antwerp and Ludwigshafen chemical corridors, where emissions accountability now extends to rotating equipment.
- Venturi:Jet-assisted priming configurations handle entrained gas and intermittent suction lift in mining dewatering operations.
- Diaphragm:Positive-displacement alternatives serve low-flow, high-pressure chemical metering in pharmaceutical synthesis.
Today's leader: Submersible. Tomorrow's challenger: Magnetic Drive.
Application:
Water treatment absorbs the highest unit volumes, though chemical processing commands the steepest price premiums per kilowatt of hydraulic power.
- Water Treatment:Municipal sewage lift stations and raw water intake structures specify corrosion-resistant immersion units for continuous submergence in chlorinated or saline environments. EPA Clean Water Act consent decrees are mandating seal-less retrofits in California and Texas publicly owned treatment works.
- Chemical Processing:Aggressive fluid handling in sulfuric acid and caustic soda service requires super-duplex or fluoropolymer-lined wet ends. REACH compliance deadlines are forcing German and Dutch processors to retire elastomer-sealed pumps ahead of restricted substance prohibitions.
- Oil & Gas:Offshore platform retrofit cycles favor compact immersion units over legacy vertical turbine installations in North Sea and Gulf of Mexico hazardous zone classifications.
- Agriculture:Irrigation drainage and livestock wastewater handling prioritize cast iron economy configurations for intermittent seasonal duty.
Water treatment anchors current procurement volumes. Chemical processing offers the fastest margin expansion trajectory.
End User:
Mining operators and energy utilities diverge in their technical priorities, with the former emphasizing abrasion resistance and the latter demanding zero-leakage nuclear coolant handling.
- Energy:Pressurized water reactor maintenance requires sealed circulation systems for primary loop service in Japanese and South Korean reactor fleets. These specifications tolerate no atmospheric shaft seals in radioactive coolant environments.
- Mining:Pit dewatering and slurry transfer applications subject pumps to abrasive silica and pyrite particulate. Australian iron ore and Chilean copper operations specify hardened impeller materials for extended wear life in continuous-duty extraction.
- Manufacturing:Automotive paint circulation and metal finishing lines demand stainless steel wetted parts for chemical compatibility.
- Municipal:Publicly owned treatment works optimize for mean-time-between-failures in raw sewage lift station service.
Energy sector specifications set the highest technical barriers. Mining procurement scales the largest unit volumes.
Installation:
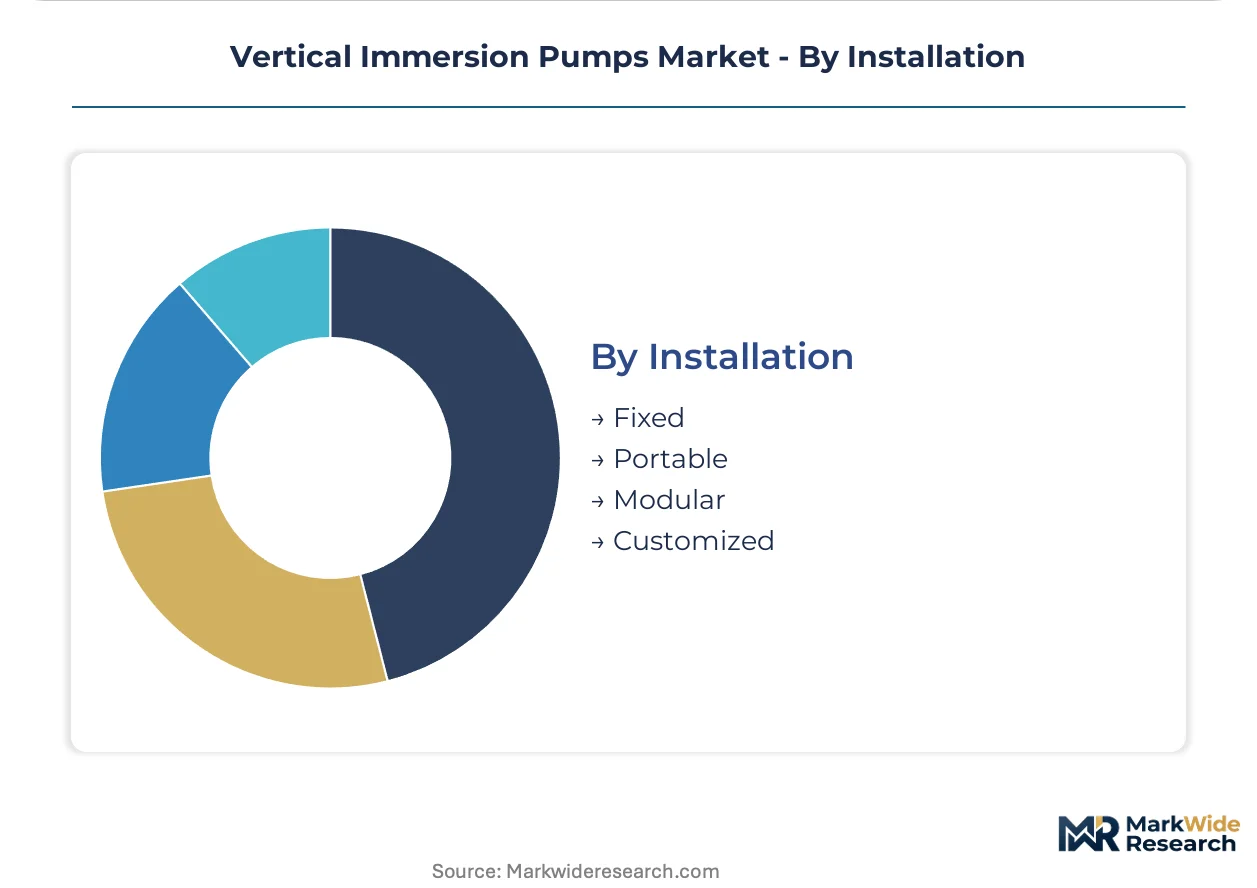
Fixed permanent mounting still dominates capital project specifications, though modular field-reconfigurable systems are compressing spare parts proliferation in multi-site operator fleets.
- Fixed:Permanent concrete pad or sump-mounted installations serve baseline production capacity in chemical plants and water treatment facilities. These configurations minimize vibration transmission and simplify foundation loading calculations for large-capacity units.
- Modular:Standardized sub-assemblies enable rapid wet-end reconfiguration without full pump replacement. BASF and Dow facilities specify cartridge-compatible immersion units to reduce confined-space entry during turnaround events.
- Portable:Temporary dewatering and emergency flood response applications favor trailer-mounted or skid-based deployment.
- Customized:Engineered-to-order configurations address extreme depth, temperature, or metallurgical requirements in specialty chemical and nuclear service.
Fixed installations retain procurement dominance. Modular architectures are expanding most quickly in chemical sector retrofit activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters anchor procurement intensity for corrosion-resistant immersion systems, with automotive supplier networks and chemical processing corridors driving specification of seal-less magnetic drive architectures across multiple regulatory jurisdictions.
Germany
Automotive coolant circulation and chemical processing plants dominate demand for super-duplex alloy pumps in the Rhine-Ruhr and Ludwigshafen corridors. The EU F-Gas Regulation tightens emissions accountability for industrial rotating equipment, accelerating magnetic drive adoption. BASF facilities in Ludwigshafen specify cartridge-compatible immersion units to reduce confined-space maintenance.
United States
EPA Clean Water Act consent decrees mandate seal-less retrofits in California and Texas municipal sewage lift stations. Offshore platform operators in the Gulf of Mexico replace legacy vertical turbine installations with compact immersion units for hazardous zone classifications. Houston Ship Channel chemical processors engage third-party rebuild shops for wet-end overhauls.
Japan
Pressurized water reactor maintenance drives zero-leakage coolant handling specifications for primary loop service. METI oversees nuclear safety standards that tolerate no atmospheric shaft seals in radioactive environments. EBARA Corporation anchors supply relationships with domestic reactor fleets requiring sealed circulation systems.
India
Pharmaceutical manufacturing expansion under the PLI scheme attracts captive pump assembly investments for CDSCO-compliant sterile processing. Domestic production incentives redirect procurement toward local fabrication for active pharmaceutical ingredient synthesis. Gujarat and Maharashtra industrial corridors concentrate sterile processing facility development.
South Korea
Nuclear coolant infrastructure expansion requires sealed circulation systems for pressurized water reactor maintenance. MFDS-equivalent nuclear safety protocols mirror Japanese zero-leakage specifications. Energy utilities in the southeastern industrial belt specify magnetic drive architectures for primary loop service.
Vertical Immersion Pumps Market Competitive Environment
Global majors compete with regional champions across metallurgical capabilities and aftermarket service density. The vendor base stratifies into three tiers: integrated alloy producers commanding sulfuric acid service premiums, submersible specialists dominating water infrastructure volumes, and magnetic drive innovators capturing chemical sector compliance premiums. Consolidation pressures concentrate around captive foundry emissions data and fourteen-month ATEX certification timelines.
Among European manufacturing anchors, KSB leverages its continental footprint to sustain aftermarket parts availability across chemical corridors. Flowserve exemplifies the integrated alloy tier through upstream control over specialty metallurgy supply. EBARA Corporation occupies a position within Asian energy infrastructure, with its name signaling Japanese origin and nuclear coolant application concentration. These three represent distinct competitive archetypes: regional service density, backward integration into materials, and sector-specific technical positioning.
| Leading Market Players |
|---|
| Ruhrpumpen Group |
| KSB |
| Gusher Pumps |
| Sulzer |
| Flowserve |
| EBARA Corporation |
| Weir Group |
| ITT Inc. |
| Lutz-JESCO |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation enforcement gates qualified supply for sealed magnetic drive configurations and premium-tier pricing access for corrosion-resistant immersion systems in chemical processing corridors. Alloy provenance documentation and ATEX certification timelines compress margin predictability for sulfuric acid service pumps while rewarding regional manufacturing footprints with captive foundry emissions data.
Pricing Analysis
Input-cost pass-through from nickel and molybdenum volatility shapes three-tier pricing structure across premium, standard, and economy levels in super-duplex alloy pumps. Price differentiation rests on certification grade and geographic delivery cost, with ATEX/IECEx-certified magnetic drive units commanding substantial premiums over submersible baselines. Cost compression in standard-tier cast iron configurations is intensifying because municipal water authorities optimize for lifecycle cost over initial procurement. Chemical processors in German refining corridors exhibit least price sensitivity due to zero-emission mandate compliance deadlines, while agricultural irrigation buyers drive hardest bargain negotiations.
Supply Chain Analysis
Super-duplex alloy supply rests on Scandinavian and Austrian foundry networks, with specialty metallurgy capacity concentrating in Germany, Japan, and the United States for nuclear-grade certification. Raw material dependencies center on nickel, molybdenum, and chromium feedstock from mining operations in Indonesia and South Africa. Supply chain risk hinges on single-source vulnerability in orbital welding certification for ASME IX-qualified super-duplex pump casings. Distribution runs through OEM-direct channels for engineered-to-order chemical service units, while standardized submersible configurations flow through regional distributor networks serving municipal water infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification committees in chemical processing and nuclear energy are consolidating procurement around seal-less magnetic drive architectures with zero-leakage guarantees.
For Market Incumbents: Cement aftermarket service density in chemical corridors to offset unbundling pressures from third-party rebuild shops in the Houston Ship Channel. Deepen captive metallurgy capabilities to defend margin position against nickel price volatility in sulfuric acid service. Prioritize cartridge-compatible wet-end architectures that compress mean-time-to-repair for BASF and Dow turnaround schedules. For New Entrants and Emerging Players: Hydrogen economy electrolyte handling represents a technology-first wedge with underpenetrated demand for potassium hydroxide circulation in PEM and alkaline electrolyzer plants. Target Indian pharmaceutical manufacturing expansion under PLI scheme incentives for CDSCO-compliant sterile processing facilities. Pursue joint development agreements with domestic fabricators in Gujarat and Maharashtra industrial corridors to bypass fourteen-month ATEX certification barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with dense aftermarket parts networks because maintenance contract unbundling fragments traditional OEM pricing power. Target mid-cap magnetic drive innovators with captive containment shell manufacturing and documented EU CBAM alloy provenance. Watch hydrogen infrastructure deployment rates as inflection indicator for electrolyte handling pump demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Metallurgy | Flowserve's upstream control over alloy supply secures sulfuric acid service margins against nickel volatility. |
| Cartridge Seal Modularization | BASF and Dow specifications for cartridge-compatible units reduce confined-space entry during turnaround events. |
| Regional Manufacturing Footprint Expansion | German and Italian producers leverage captive foundry emissions data for EU CBAM tender advantage. |
| Third-Party Service Network Partnership | Houston Ship Channel chemical processors bypass OEM maintenance contracts through direct rebuild shop engagement. |
| Hydrogen Electrolyte Handling Portfolio Development | PEM and alkaline electrolyzer plants need corrosion-resistant circulation for potassium hydroxide and deionized water loops. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and aftermarket service heads, secondary validation through customs data and SEC filings, technical specification review — were reconciled across bottom-up and top-down triangulation. Stakeholder consultations included maintenance directors at chemical processing facilities, OEM procurement teams in automotive supplier networks, nuclear coolant system engineers at Asian energy utilities, and distribution channel partners serving municipal water authorities. Secondary sources comprised trade association reports from chemical industry federations, EPA enforcement action databases, EU regulatory filing repositories, and foundry capacity surveys from specialty metallurgy associations.
Historical shipment patterns were cross-referenced against panel input from specification committees to model demand trajectories across the projection horizon. Segmentation dimensions included product architecture, application severity, end-user technical requirements, and installation permanence. CAGRs were derived from regression analysis of alloy cost pass-through elasticity and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated nuclear reactor maintenance cycle timing and offshore platform retrofit commitment schedules.
The model holds under stable nickel-molybdenum price corridors and fourteen-month ATEX certification timelines; deviation in alloy volatility spikes or regulatory acceleration would shift procurement patterns toward air-operated diaphragm substitutes. Forecasts reflect documented assumptions on REACH compliance migration pace and F-Gas Regulation enforcement intensity. A small set of named triggers — EU CBAM implementation scope, hydrogen infrastructure deployment rates, and specialized welding certification pipeline expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Automatic Tank Cleaning Systems Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
India Industrial Pump Market