
 Hydro Turbines Market | 2026-2036
Hydro Turbines Market Size, Share, and Industry Trends Forecast 2026-2036
Hydro Turbines Market Intelligence
Demand from private developers for smaller-scale hydropower projects is consolidating market share away from traditional large utility-scale installations. This shift favors modular and standardized turbine designs. ANDRITZ AG leverages its expertise in both new builds and refurbishment projects to capture diverse revenue streams. Voith GmbH & Co. KGaA sustains its position through advanced digital solutions for turbine optimization, while General Electric Company competes on the strength of its global service network.
A hydro turbine is a rotary machine designed to convert the kinetic and potential energy of moving water into mechanical power. These devices feature a runner or a series of blades that rotate as water passes through, with designs optimized for specific head and flow conditions. Francis and Kaplan turbines dominate the market for low-to-medium head applications, while Pelton turbines are specified for high-head sites. Hydropower plants remain the principal application, with run-of-river installations gaining traction due to lower environmental impact.
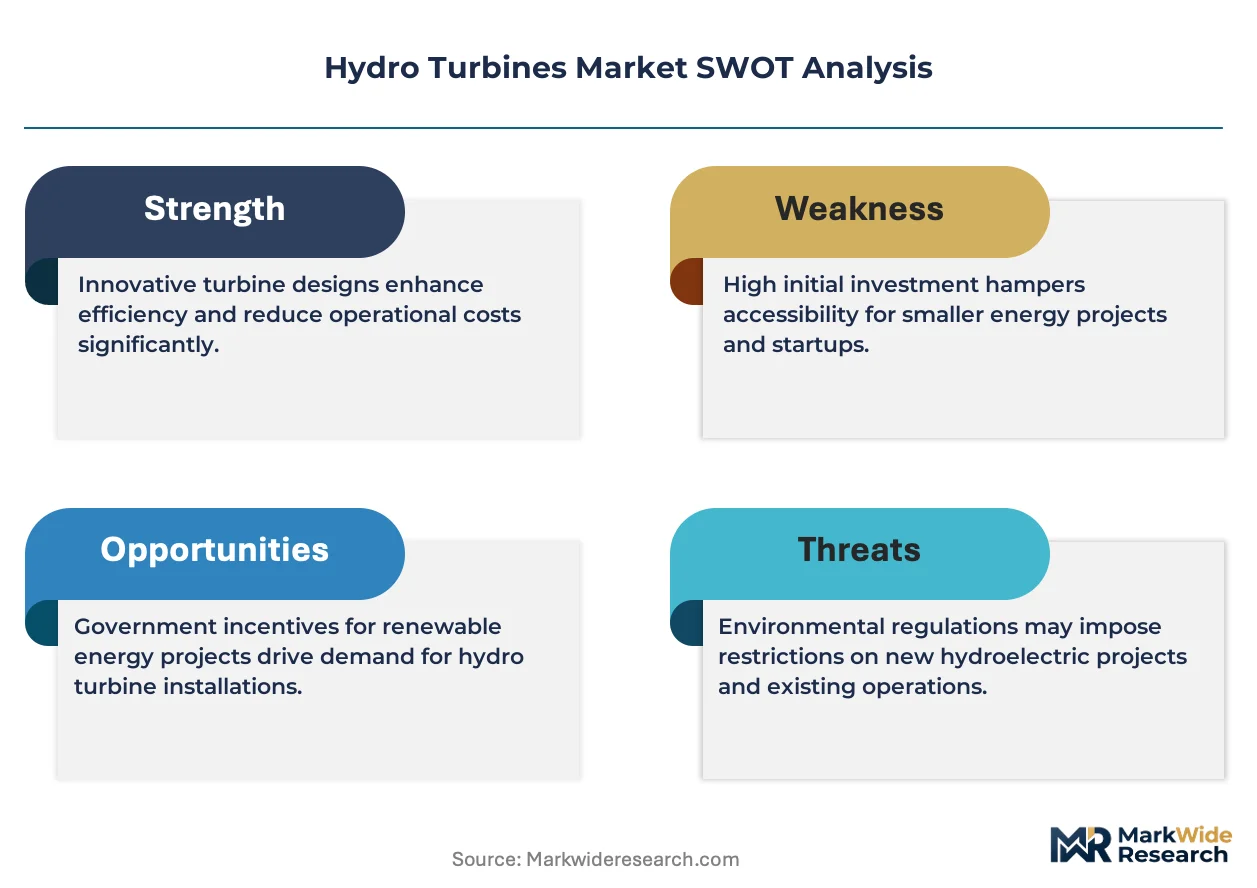
Regulatory frameworks from bodies like China's Ministry of Ecology and Environment (MEE) and the U.S. Environmental Protection Agency (EPA) govern environmental impact assessments for new projects. The EU Green Deal and similar renewable energy portfolio standards in various nations directly mandate or incentivize hydropower capacity additions, shaping investment cycles. Stakeholders must now decide how to balance investment between developing new small-scale hydro resources and upgrading the aging fleet of large-scale turbines for improved efficiency and grid stability.
Market Dynamics
The central tension in the hydro turbines market is the strategic allocation of capital between modernizing an extensive, aging global fleet of large-scale dams and developing new, smaller-scale, decentralized hydropower resources. This dynamic forces stakeholders to weigh the efficiency gains from refurbishment against the faster deployment and lower environmental impact of new run-of-river projects.
Growth Catalysts
- EU Green Deal:This framework provides direct incentives and mandates for expanding renewable energy capacity, creating a stable, long-term demand signal for both new hydro projects and the modernization of existing European plants.
- China's Energy Security Goals:National policies in China prioritizing energy independence and decarbonization under its dual carbon goals are driving sustained investment in large-scale hydropower projects, securing a significant volume of turbine orders.
- Run-of-River Installations:A preference for hydropower projects with minimal water impoundment and reduced ecological disruption is boosting the development of run-of-river sites, expanding the market for specialized low-head turbines like Kaplan models.
Market Restraints
- High Capital Costs:The substantial upfront investment required for civil engineering works, dam construction, and the installation of large-scale turbines remains a primary barrier to entry, particularly for private developers and in emerging economies.
- Regulatory Delays:Protracted environmental impact assessment and permitting processes, governed by bodies like the U.S. Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE), can extend project timelines by years.
- Site Constraints:The availability of economically and environmentally viable sites for new large-scale hydropower projects is diminishing, while public and political opposition to large dam construction has intensified globally.
Strategic Opportunities
- Untapped Hydropower Potential:Regions such as Southeast Asia, particularly along the Mekong River basin, and parts of Latin America possess significant undeveloped hydropower resources, offering greenfield expansion opportunities for turbine manufacturers.
- Digitalization of Assets:The integration of IoT sensors, predictive analytics, and digital twin models presents a major opportunity to sell high-margin digital services for turbine optimization, predictive maintenance, and operational efficiency.
- Hybrid Power Projects:Pairing hydropower facilities with other energy sources, such as floating solar panels on reservoirs or co-located battery energy storage systems, creates new applications for turbines in providing grid stability and ancillary services.
Industry Challenges
- Specialized Workforce Shortages:The industry faces a critical shortage of skilled engineers and technicians who possess expertise in both the mechanical aspects of aging turbines and the sophisticated digital control systems of modern units.
- Supply Chain Bottlenecks:The manufacturing of large turbine components like runners and wicket gates is concentrated among a few suppliers, leading to long lead times and vulnerability to logistical disruptions that can delay entire projects.
- Legacy System Integration:Refurbishment projects frequently encounter significant technical challenges and cost overruns when attempting to integrate new, digitally-controlled turbines with outdated electrical and mechanical infrastructure at existing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydro Turbines Market |
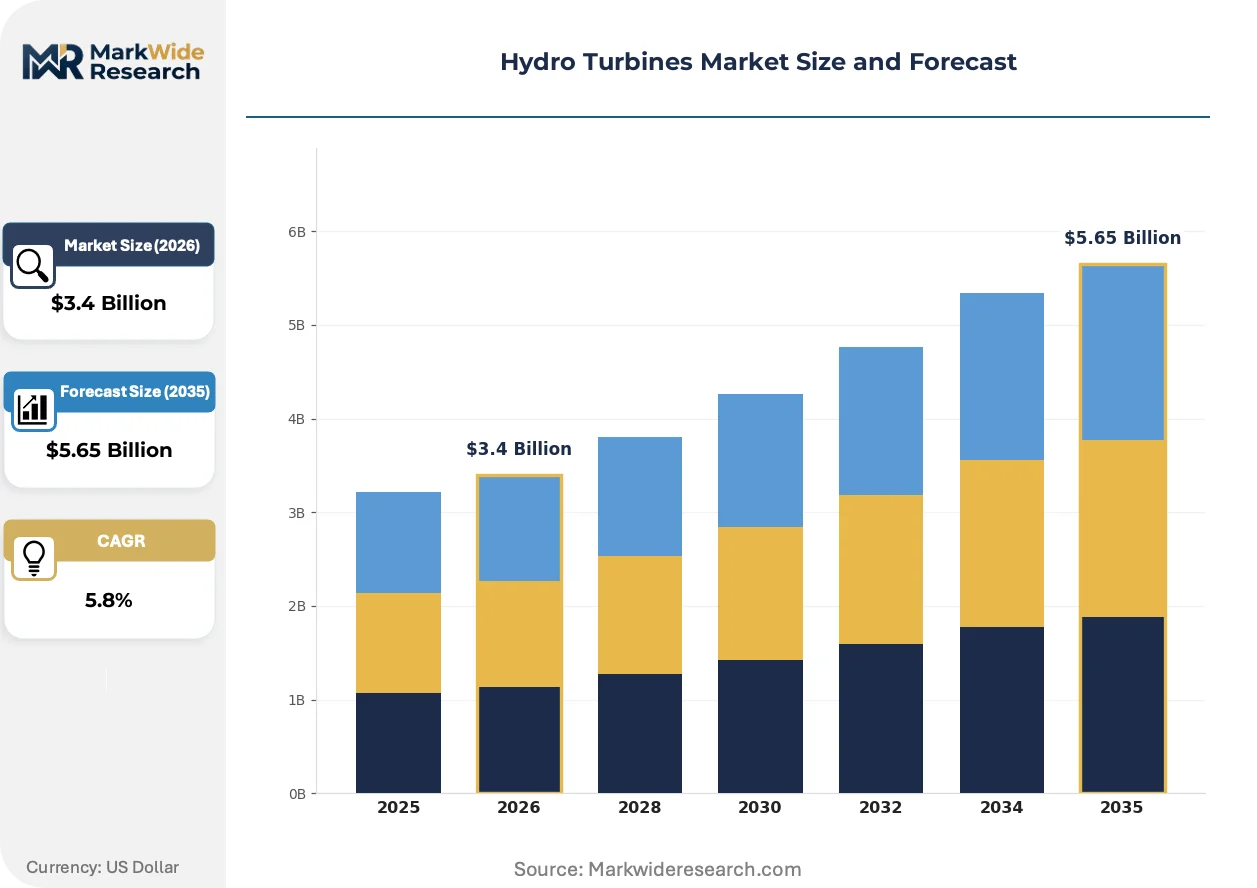
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Impulse Turbines, Francis Turbines, Kaplan Turbines, Pelton Turbines Application: Hydropower Plants, Irrigation Systems, Water Supply, Flood Control End User: Utilities, Government Agencies, Private Developers, Industrial Users Installation: Onshore, Floating, Underground, Run-of-River |
| Companies Covered | ANDRITZ AG, General Electric Company, Voith GmbH & Co. KGaA, Dongfang Electric Corporation, Toshiba Energy Systems & Solutions Corporation, Siemens AG, Harbin Electric Corporation, Bharat Heavy Electricals Limited, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydro Turbines Market Strategic Shifts & Innovations
Digitalization and modularity are fundamentally altering the design and operational philosophy of hydro turbines. The market is shifting focus from raw power generation toward providing flexible, grid-stabilizing assets, a change reflected in both new product development and the modernization of existing fleets.
Advanced digital twin technology creates a virtual, real-time replica of a physical turbine and its operating environment. Plant operators and asset managers are adopting this technology to simulate various operating scenarios and predict component wear without physical intervention. This technology is integrating sensor data with physics-based models, enabling highly accurate predictive maintenance and performance optimization that extends asset life.
Policies like the U.S. Inflation Reduction Act (IRA) are creating powerful financial incentives for the modernization of existing hydropower facilities. The act's investment and production tax credits directly reduce the cost of upgrading turbines, accelerating refurbishment cycles across the North American hydro fleet. Owners of aging plants are most affected, now finding it financially viable to invest in higher-efficiency runners and digitally-enabled governors.
Demand for ancillary grid services is reshaping turbine procurement criteria. Grid operators are increasingly contracting for hydropower's capacity to provide rapid frequency response and voltage support, rather than just bulk energy. This shift disrupts traditional energy-centric bidding and favors turbines with enhanced operational flexibility, a trend most visible in grids with high renewable penetration like those in Germany and Australia.
Hydro Turbines Market Segmentation
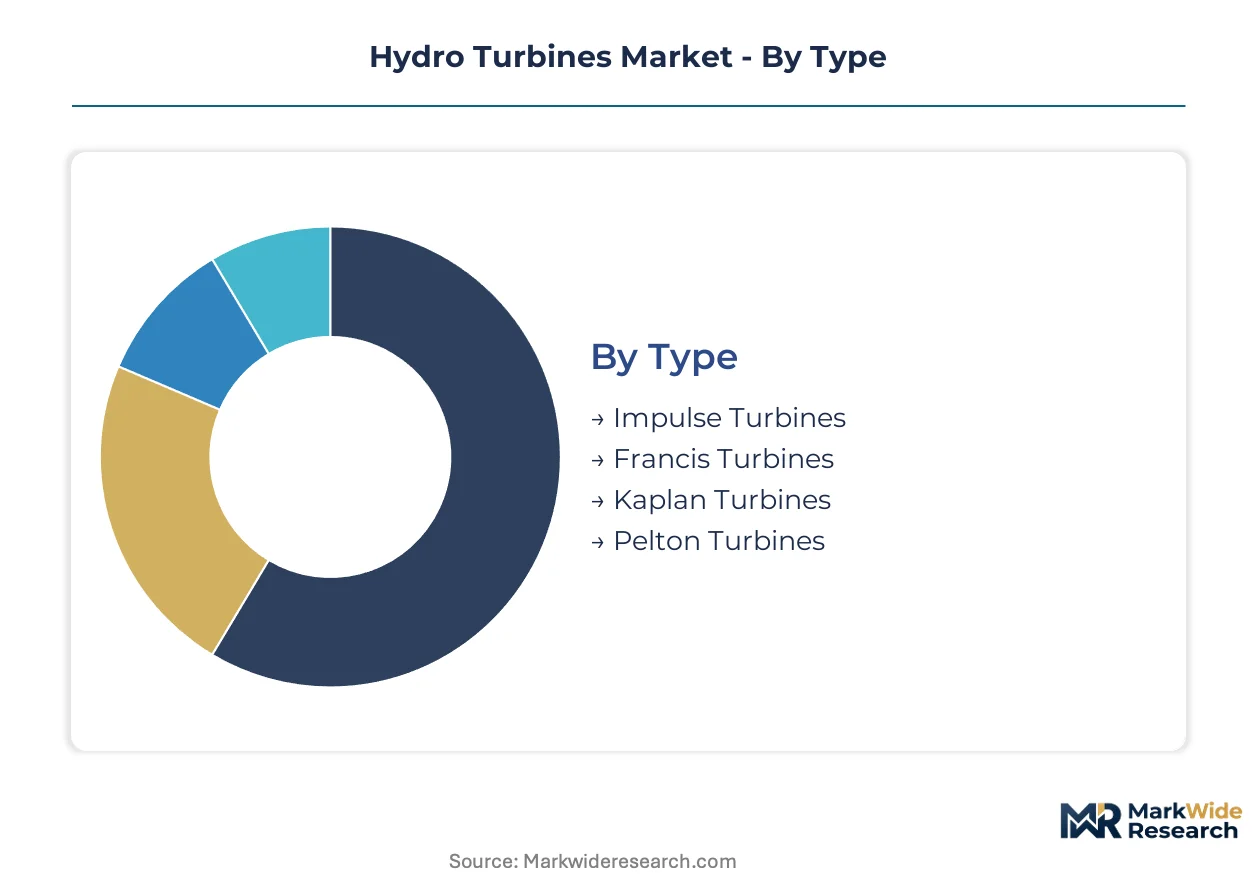
The hydro turbines market exhibits diverse segmentation across critical dimensions, reflecting varied operational requirements and strategic investment priorities. Understanding these categories is essential for stakeholders to identify specific growth vectors and tailor technology deployments. Each segment addresses unique aspects of water energy conversion and infrastructure development.
Type:
The type of hydro turbine dictates specific engineering standards and regulatory approvals, with Francis and Kaplan designs necessitating stringent certifications for grid integration.
- Francis Turbines:These reaction turbines, with spiral casings and fixed blades, are highly efficient for medium-head and medium-flow applications. Demand is robust in China for large-scale dam construction.
- Kaplan Turbines:Featuring adjustable propeller-like blades, Kaplan turbines excel in low-head, high-flow environments, offering flexibility. Modernization projects in Europe specify them for efficiency gains.
- Impulse Turbines:These convert water's kinetic energy from a high-velocity jet, employed in high-head, low-flow scenarios, particularly in mountainous regions.
- Pelton Turbines:Designed for very high head applications, Pelton wheels direct water through nozzles to strike bucket-shaped runners for mechanical power.
Francis Turbines sit at the top of the volume ranking, with Kaplan Turbines climbing the fastest.
Application:
The specific application of hydro turbines influences project capital expenditure and operational costs, with large-scale hydropower plants representing substantial initial investments.
- Hydropower Plants:These installations are primary for hydro turbines, converting water flow into electricity for grid supply. Demand in Southeast Asia offers significant greenfield expansion.
- Irrigation Systems:Turbines integrated into irrigation networks provide decentralized power for pumping and local electricity, particularly in agricultural regions. Private developers target these smaller-scale projects.
- Water Supply:Turbines generate power within municipal water supply pipelines, recovering energy from pressure reduction for local grid contribution.
- Flood Control:Turbines incorporated into flood control dams generate power while managing water levels and mitigating flood risks.
Hydropower Plants continue to command the largest share, while decentralized energy applications like irrigation are expanding their footprint.
End User:
The end-user profile determines procurement patterns and service requirements; utilities prioritize grid stability, while private developers focus on project ROI.
- Utilities:Traditional power generation companies represent a foundational demand segment, investing in large-scale hydropower plants and refurbishment projects for grid stability.
- Private Developers:This segment includes independent power producers, increasingly focusing on smaller, modular hydropower projects and run-of-river installations, seeking financial incentives.
- Government Agencies:National and regional government bodies invest in hydro turbines for public infrastructure projects and multi-purpose water management.
- Industrial Users:Industries with significant water resources utilize smaller hydro turbines for captive power generation, prioritizing reliability and energy savings.
Utilities remain a core segment for large-scale projects, but private developers are expanding their presence in the decentralized hydro market.
Installation:
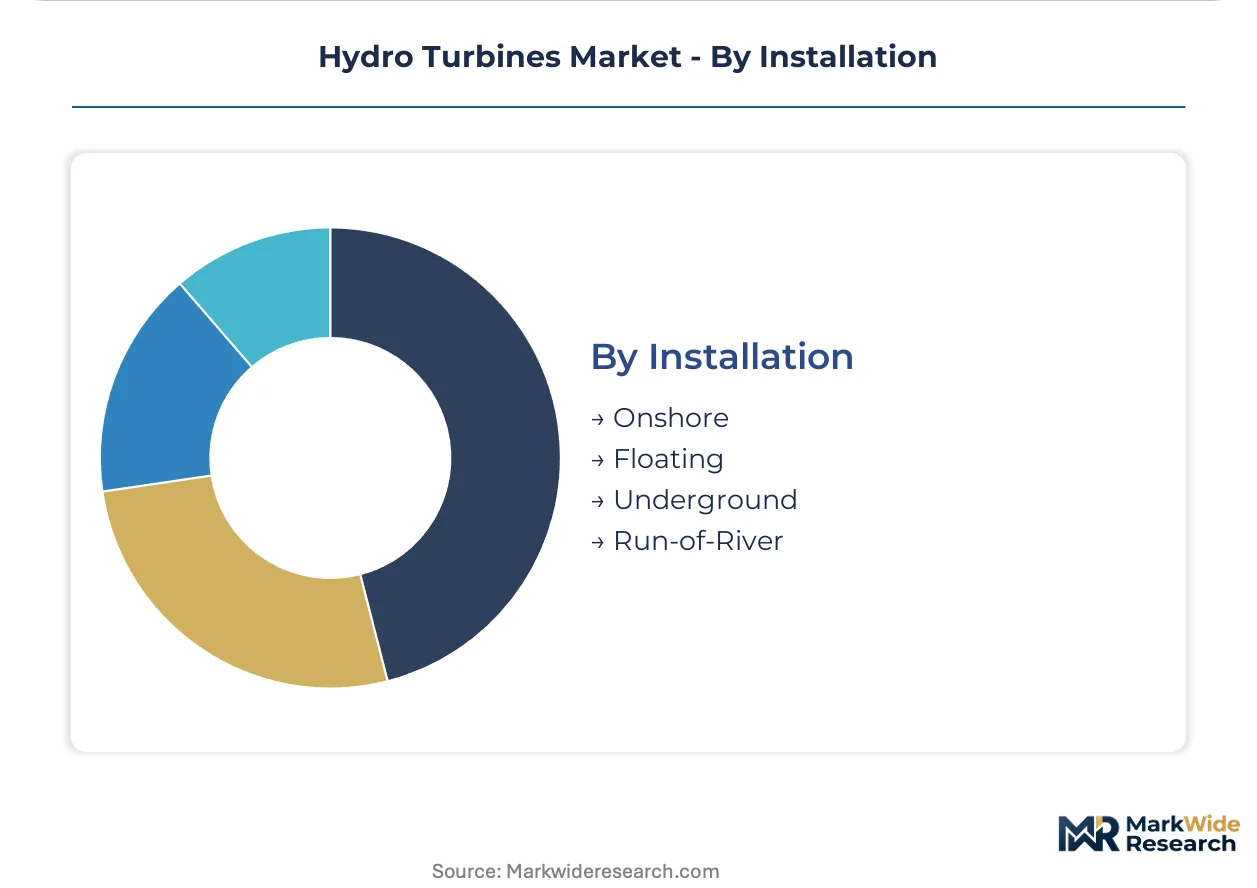
Installation type influences specialized civil engineering and manufacturing capabilities, with configurations like underground or floating turbines demanding concentrated expertise.
- Onshore:This traditional installation method involves turbines housed within or adjacent to dams and reservoirs, requiring extensive civil works. Sites face diminishing viability and scrutiny.
- Run-of-River:These installations divert river flow through a turbine, minimizing environmental impact and reservoir creation. They gain traction due to lower ecological disruption.
- Floating:Floating hydro turbine installations are emerging for tidal or river currents, designed to be less intrusive and offer flexible deployment.
- Underground:Turbines installed in underground powerhouses offer advantages in land use and protection, common in large-scale pumped-hydro storage schemes.
Run-of-river installations are increasingly favored for reduced environmental footprint and accelerated deployment compared to conventional onshore projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive hydropower development anchors global demand for hydro turbines. Modernization efforts in established markets and greenfield projects in emerging economies are driving regional investment. Diverse regulatory frameworks and energy security goals shape procurement patterns across continents.
China
China's robust demand for Francis turbines stems from national energy security goals and extensive large-scale dam construction. The Ministry of Ecology and Environment (MEE) stringently regulates environmental impact assessments for new projects across the nation. Sichuan Province and Yunnan Province are central to the country's extensive hydropower development and turbine deployment.
Germany
Germany's market benefits from the EU Green Deal, which incentivizes renewable energy infrastructure and plant modernization. The country's energy transition policies prioritize grid stability and efficiency upgrades for existing hydropower facilities. Bavaria and Baden-Württemberg lead in modernizing Kaplan turbines for low-head applications and grid support.
United States
The United States sees demand driven by the modernization of aging hydropower facilities. The Inflation Reduction Act (IRA) provides significant financial incentives for upgrading existing turbines. The Pacific Northwest and the Tennessee Valley Authority region are actively investing in higher-efficiency runners and digital controls.
Vietnam
Vietnam presents significant untapped hydropower potential, especially within its extensive river basins. The government actively promotes hydropower capacity additions to meet the nation's growing energy needs. The Mekong River basin region is a key focus for greenfield expansion and new turbine installations.
Brazil
Brazil's market is shaped by the need for grid stability and energy supply in a large country. National energy policies encourage investment in both large-scale and smaller hydro projects. The Paraná River basin and Amazon region are crucial for new project development and existing plant maintenance.
Hydro Turbines Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers seek to capture revenue from both new installations and the extensive refurbishment projects. The market structure includes established global engineering conglomerates, specialized digital solution providers, and regional manufacturers. Strategic partnerships, continuous technology innovation, and geographic expansion are prevalent competitive moves. Companies are actively balancing investment in large-scale utility projects with the growing demand for smaller, decentralized hydropower resources.
Global engineering conglomerates like ANDRITZ AG and Voith GmbH & Co. KGaA represent a significant portion of the market, leveraging their extensive expertise in both new builds and advanced digital solutions for turbine optimization. These entities often provide comprehensive offerings spanning design, manufacturing, installation, and long-term service contracts across diverse geographies. Dongfang Electric Corporation, a China-based heavy equipment manufacturer, exemplifies the strength of national champions in securing large-scale domestic projects and driving volume. These players collectively anchor the market's technological and service capabilities.
| Leading Market Players |
|---|
| ANDRITZ AG |
| General Electric Company |
| Voith GmbH & Co. KGaA |
| Dongfang Electric Corporation |
| Toshiba Energy Systems & Solutions Corporation |
| Siemens AG |
| Harbin Electric Corporation |
| Bharat Heavy Electricals Limited |
| Mitsubishi Heavy Industries |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's direct incentives for expanding renewable energy capacity are forcing manufacturers to prioritize standardized, modular turbine designs, which influences pricing structures across the market.
Pricing Analysis
Rising input costs for specialized steel alloys and advanced control systems are frequently passed through in project-based turbine contracts. The dominant pricing model is project-based, reflecting extensive customization and long-term installation agreements. Price differentiation stems from turbine efficiency ratings and the level of integrated digital solutions for optimization. Pricing softness affects standardized, lower-margin components, particularly due to competition from Asian manufacturers. Utilities, focused on long-term grid stability, exhibit lower price sensitivity than private developers seeking faster project ROI.
Supply Chain Analysis
Stringent certifications for grid integration, particularly for Francis and Kaplan designs, act as a significant gating factor within the supply chain. Turbine component manufacturing concentrates heavily in China, Germany, and Japan. Key dependencies include specialized steel for runners, copper for generators, and high-performance control electronics. Single-source vulnerability for large-scale castings represents a structural risk, while distribution runs primarily through direct sales to utilities and EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hydro Turbines Market presents a geographic-arbitrage opportunity, as development costs for new large-scale projects in Southeast Asia remain significantly lower than extensive modernization efforts in mature European markets.
For Market Incumbents:
Anticipate continued demand for advanced digital solutions and refurbishment services, especially as aging infrastructure faces increased regulatory scrutiny. Bolster capabilities in digital twin technology and predictive maintenance to counter the threat of specialized software providers. Diversify revenue streams by investing in modular, standardized designs for smaller-scale projects. Leverage existing global service networks as a key lever to maintain market share against regional competitors.
For New Entrants and Emerging Players:
Digital platforms offering remote monitoring and optimization services represent a viable channel route for market entry. Target underpenetrated decentralized energy applications like irrigation systems in emerging economies. Focus on developing highly efficient, standardized Kaplan turbines for run-of-river installations, which offer faster deployment and lower environmental impact. A go-to-market angle could involve offering integrated financing solutions alongside modular turbine packages.
For Investors and Strategic Acquirers:
Asymmetric upside sits with technology-focused firms specializing in digital controls and advanced materials for turbine efficiency upgrades. The long-term viability of hydropower remains strong, driven by grid stability needs and renewable energy mandates. Seek acquisition targets with proven expertise in both new modular designs and complex refurbishment projects. A signal to watch is the acceleration of grid modernization programs requiring flexible hydropower assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Twin Platforms | Enhances asset life and operational efficiency for existing hydropower facilities through predictive analytics. |
| Expand Modular Turbine Production | Addresses the growing demand for smaller, decentralized run-of-river installations with reduced environmental impact. |
| Form Hybrid Power Partnerships | Integrates hydropower with solar or storage to provide flexible grid services and enhance energy reliability. |
| Develop Advanced Materials for Runners | Improves turbine efficiency and durability, extending operational lifespan in challenging water conditions. |
| Strengthen Global Service Networks | Ensures comprehensive after-sales support and maintenance, crucial for long-term utility-scale asset performance. |
Research Approach
Direct dialogue with utility planning officers, independent power producers, EPC contractors, and turbine design engineers provided crucial qualitative grounding. This primary research was validated through extensive secondary data from MEE reports, EPA filings, IEA reports, and national energy policy documents. A bottom-up and top-down triangulation approach ensured comprehensive market sizing and validation.
The quantitative model estimated market volume and value outputs across the analysis window, segmented by turbine type, application, end-user, and installation method. Compound annual growth rates were derived from historical trends and projected future demand drivers. Forecast inputs included planned hydropower capacity additions and the rate of aging fleet modernization.
The model assumes a particular technology adoption path; alternative pathways for modular turbine designs or advanced digital integration would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and economic growth within key regional markets. A model refresh is warranted upon material change in national energy security goals or major policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market