
 Progressing Cavity Pump Market | 2026-2036
Progressing Cavity Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Progressing Cavity Pump Market Intelligence
API 676 qualification for positive displacement pumps in upstream hydrocarbon service is collapsing the competitive field to a handful of certified manufacturers. NETZSCH leverages its German engineering base and captive elastomer compounding to dominate high-temperature and chemically resistant configurations. SEEPEX sustains a broad application portfolio across wastewater and food processing, where its modular stator-rotor architecture reduces inventory complexity for municipal buyers. NOV anchors its position through upstream oilfield integration, supplying progressing cavity pumps as part of integrated artificial lift packages.
A progressing cavity pump moves fluid through a helical rotor turning eccentrically within an elastomer-lined stator, creating sealed cavities that progress from suction to discharge at rates typically spanning single-digit to thousands of gallons per minute. Its primary purpose is handling viscous, abrasive, or shear-sensitive fluids across industries where centrifugal alternatives lose efficiency or damage product integrity. Heavy-duty pumps capture the dominant share of value in oil and gas extraction, where abrasive produced water and polymer-laden crude demand hardened rotor coatings and specialized stator elastomers. Electric drive systems are gaining fastest in water treatment and food processing applications, as facilities retrofit from pneumatic and hydraulic alternatives to meet site energy targets and reduce maintenance headcount.
The EPA enforces effluent limitations guidelines that mandate reliable solids handling in municipal wastewater facilities, directly shaping pump specification and replacement timetables. In Europe, the Ecodesign Directive and REACH compliance requirements constrain elastomer chemistry and motor efficiency classes, filtering out suppliers lacking in-house testing and certification capabilities. China's GB standards for mechanical equipment and energy labeling add a parallel compliance layer for manufacturers serving its domestic industrial base. Stakeholders must monitor how tightening efficiency thresholds and material disclosure rules redistribute margin pools between integrated compounders and assembly-only competitors.
Market Dynamics
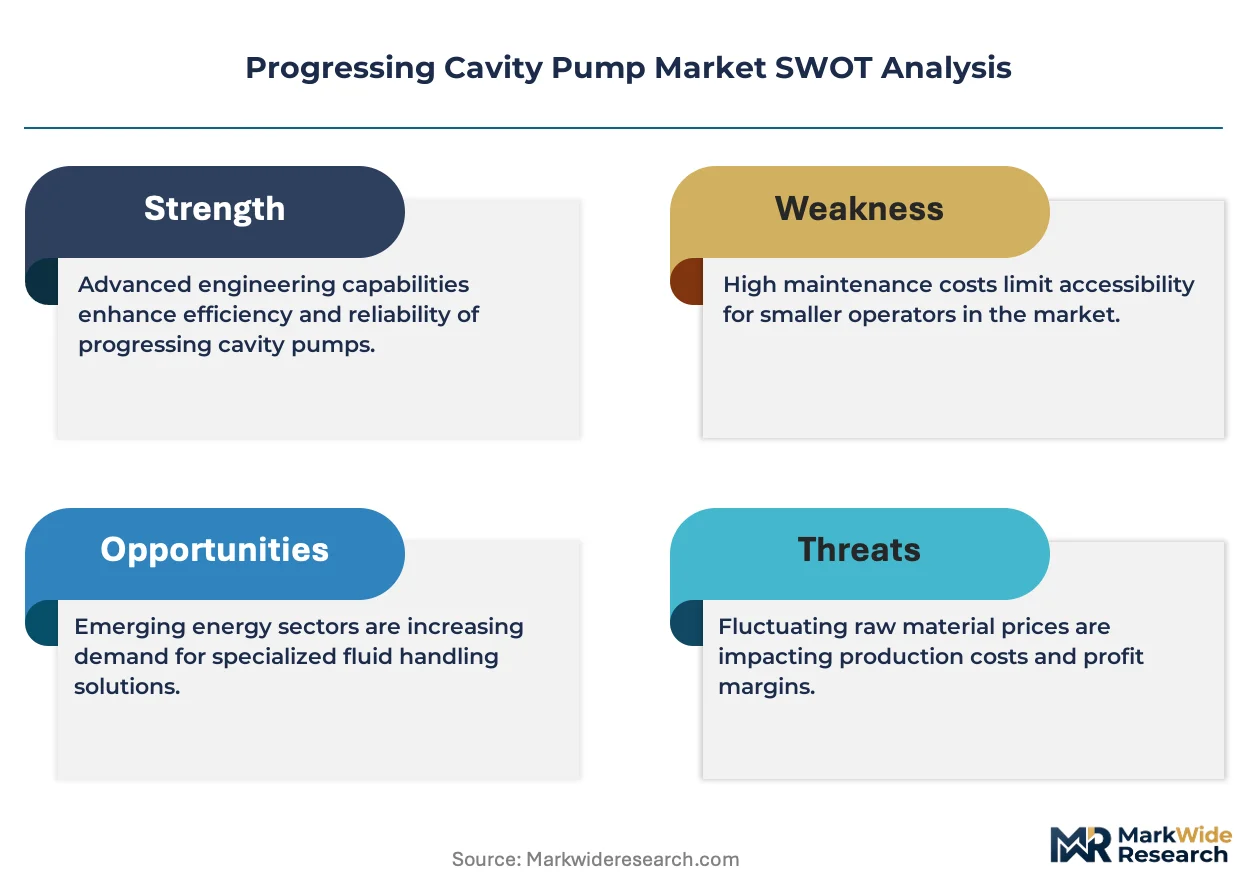
The progressing cavity pump market is bifurcating between integrated manufacturers with captive elastomer compounding capabilities and assembly-only competitors facing margin compression from tightening material disclosure rules and efficiency mandates.
Growth Catalysts
- EPA Effluent Guidelines:US municipal wastewater facilities face mandated solids-handling reliability standards that accelerate replacement timetables and favor pumps with proven abrasion resistance.
- Electric Drive Retrofits:Germany's wastewater utilities are systematically replacing pneumatic and hydraulic systems to meet site energy targets and reduce maintenance headcount.
- Shanghai Petrochemical Cluster:China's chemical processing corridor around Shanghai drives replacement cycles as aging installations reach end-of-service intervals.
Market Restraints
- Specialized Elastomer Supply:High-temperature and chemically resistant stator linings depend on concentrated specialty polymer suppliers, creating input cost volatility and qualification bottlenecks.
- API 676 Certification Barrier:Upstream hydrocarbon service requires third-party qualification that filters out manufacturers lacking in-house testing infrastructure.
- Centrifugal Pump Substitution:Low-viscosity applications in water treatment increasingly adopt multi-stage centrifugal alternatives where progressing cavity efficiency advantages diminish.
Strategic Opportunities
- Food Processing Modularity:Modular stator-rotor architectures reduce inventory complexity for municipal and industrial buyers managing diverse fluid profiles.
- EU Ecodesign Directive:Motor efficiency class mandates create procurement preference for integrated electric-drive packages over retrofit motor-adapted units.
- India Industrial Corridor:Chemical and pharmaceutical manufacturing expansion in Gujarat and Maharashtra presents underpenetrated demand for shear-sensitive fluid handling.
Industry Challenges
- Elastomer Formulation Expertise:REACH compliance and material disclosure requirements demand chemists capable of reformulating compounds without performance degradation.
- Legacy System Integration:Brownfield installations require customized adapter kits and control system interfaces that extend commissioning timelines and erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Progressing Cavity Pump Market |
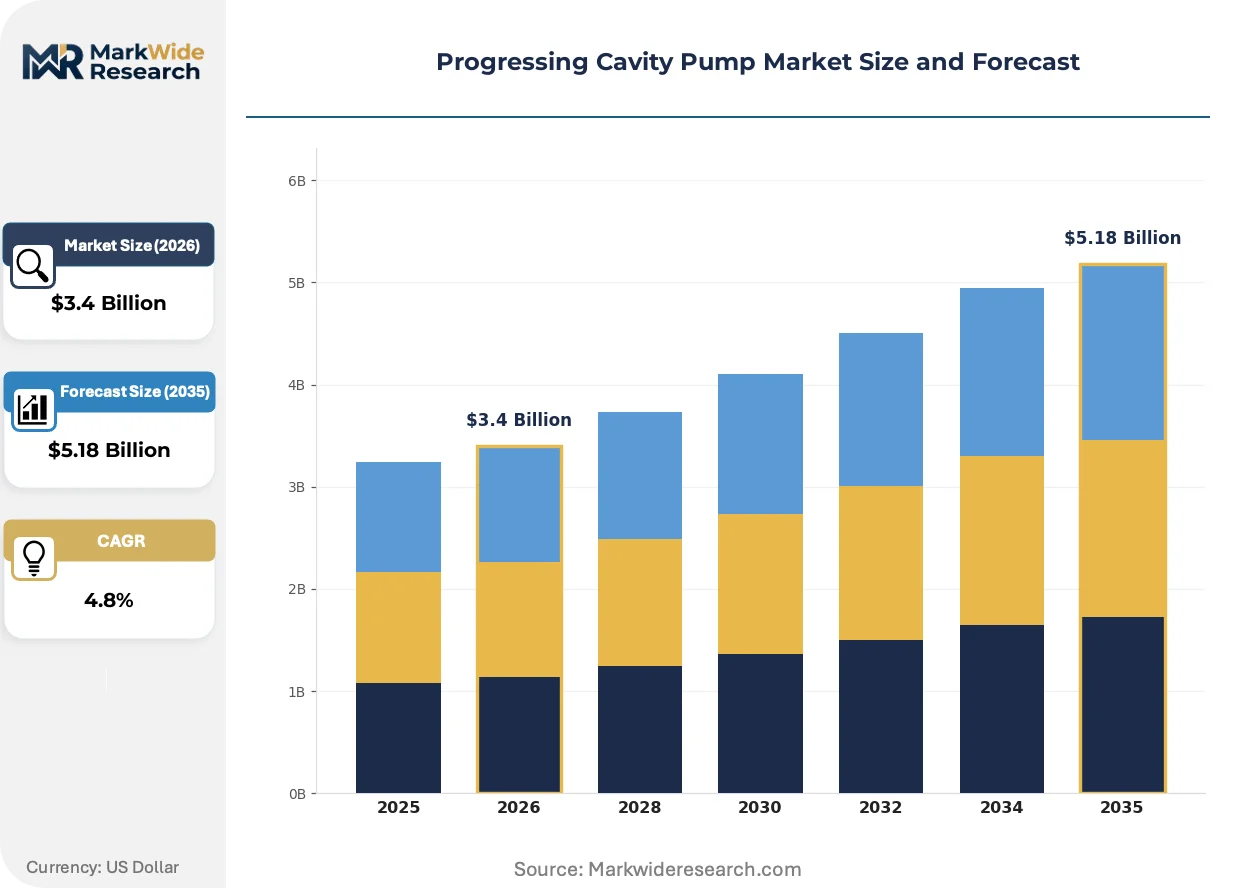
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pumps, Compact Pumps, Heavy-Duty Pumps, High-Temperature Pumps Application: Oil & Gas, Water Treatment, Food Processing, Chemicals End User: Industrial, Municipal, Commercial, Agricultural Technology: Mechanical Drive, Hydraulic Drive, Electric Drive, Pneumatic Drive |
| Companies Covered | NETZSCH, SEEPEX, NOV, CIRCOR International, SLB, Sulzer, Xylem, PCM, Roto Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Progressing Cavity Pump Market Strategic Shifts & Innovations
Hardened rotor coatings and smart monitoring systems are compressing maintenance intervals and enabling condition-based service models that alter traditional aftermarket revenue structures.
Ceramic and tungsten carbide rotor coatings are displacing traditional chrome plating in abrasive service applications. Oilfield operators in North Dakota's Bakken formation have adopted these surfaces for produced water handling. The technology is displacing conventional hardening methods by extending run life threefold in high-sand environments.
REACH authorization procedures for specialty elastomers are constraining stator material options available to European manufacturers. ECHA's candidate list expansion forces compounders to reformulate nitrile and hydrogenated nitrile variants. German pump producers are responding by accelerating in-house polymer synthesis capabilities to maintain formulation control.
Integrated pump-motor-drive packages with embedded vibration and temperature sensors are replacing standalone mechanical units in water treatment facilities. Buyers in California's Central Valley irrigation districts now specify predictive maintenance interfaces as standard. Municipal procurement in the Netherlands favors these configurations for remote monitoring of distributed lift stations.
Progressing Cavity Pump Market Segmentation
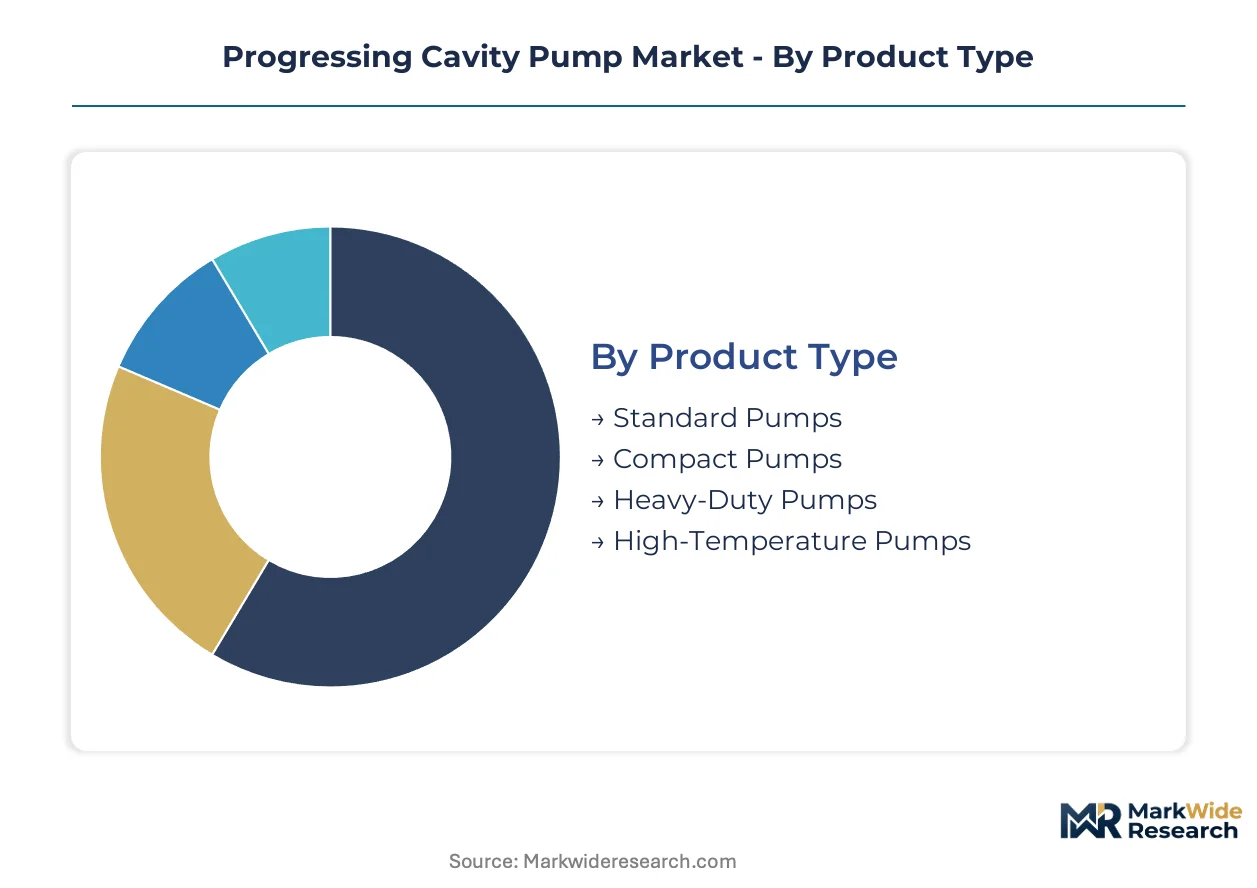
Progressing cavity pump specifications diverge sharply across duty cycles and fluid characteristics, with regulatory mandates in Germany, the United States, and China filtering procurement toward certified configurations. Segmentation reveals where elastomer chemistry, drive efficiency, and abrasion resistance concentrate margin capture.
Product Type:
EPA effluent guidelines and EU Ecodesign Directive thresholds differentiate procurement by duty severity and thermal envelope, with certified configurations commanding specification preference in regulated jurisdictions.
- Standard Pumps:General-purpose configurations handle viscous fluids in municipal water treatment and light industrial transfer. Demand concentrates in Germany's wastewater retrofit programs, where Ecodesign motor efficiency classes favor integrated electric-drive packages over pneumatic alternatives.
- Heavy-Duty Pumps:Hardened rotor coatings and specialized stator elastomers withstand abrasive produced water and polymer-laden crude. Oilfield operators in North Dakota's Bakken formation specify these for high-sand environments, with ceramic and tungsten carbide surfaces extending run life threefold.
- Compact Pumps:Space-constrained installations in food processing and pharmaceutical skids favor reduced footprint designs.
- High-Temperature Pumps:Hydrogenated nitrile and fluorocarbon stator formulations service thermal oil transfer and chemical processing above 150°C.
Established volume favors Heavy-Duty Pumps; emerging adoption favors Compact Pumps.
Application:
Fluid abrasiveness and shear sensitivity determine technology selection, with API 676 certification collapsing competitive fields in hydrocarbon service while food-grade requirements reshape material specifications elsewhere.
- Oil & Gas:Upstream artificial lift and produced water disposal demand API-qualified positive displacement pumps. NETZSCH and NOV dominate through captive elastomer compounding and integrated lift packages. REACH authorization constraints on specialty polymers force compounders to reformulate nitrile variants without performance degradation.
- Water Treatment:Municipal facilities in California's Central Valley irrigation districts specify predictive maintenance interfaces as standard. EPA effluent limitations mandate reliable solids handling, accelerating replacement timetables for abrasion-resistant configurations.
- Food Processing:Modular stator-rotor architectures reduce inventory complexity for facilities managing diverse fluid profiles.
- Chemicals:Shear-sensitive polymer and slurry handling in Shanghai's petrochemical corridor drives replacement cycles as aging installations reach end-of-service intervals.
Revenue concentration tilts toward Oil & Gas; specification momentum is climbing the fastest in Water Treatment.
End User:
Capital intensity and maintenance capability separate procurement patterns, with integrated electric-drive packages penetrating facilities seeking energy target compliance and headcount reduction.
- Industrial:Petrochemical and chemical processing clusters around Shanghai and in Gujarat, India, drive demand for high-temperature and chemically resistant configurations. Brownfield installations require customized adapter kits that extend commissioning timelines.
- Municipal:Germany's wastewater utilities systematically replace pneumatic and hydraulic systems to meet site energy targets. The Netherlands favors pump-motor-drive packages with embedded sensors for remote monitoring of distributed lift stations.
- Commercial:Building services and district heating applications favor compact electric-drive units.
- Agricultural:Irrigation and manure handling in California's Central Valley specify predictive maintenance capabilities for dispersed operations.
Industrial buyers dominate absolute volume; Municipal procurement is expanding most quickly through Ecodesign-driven retrofit programs.
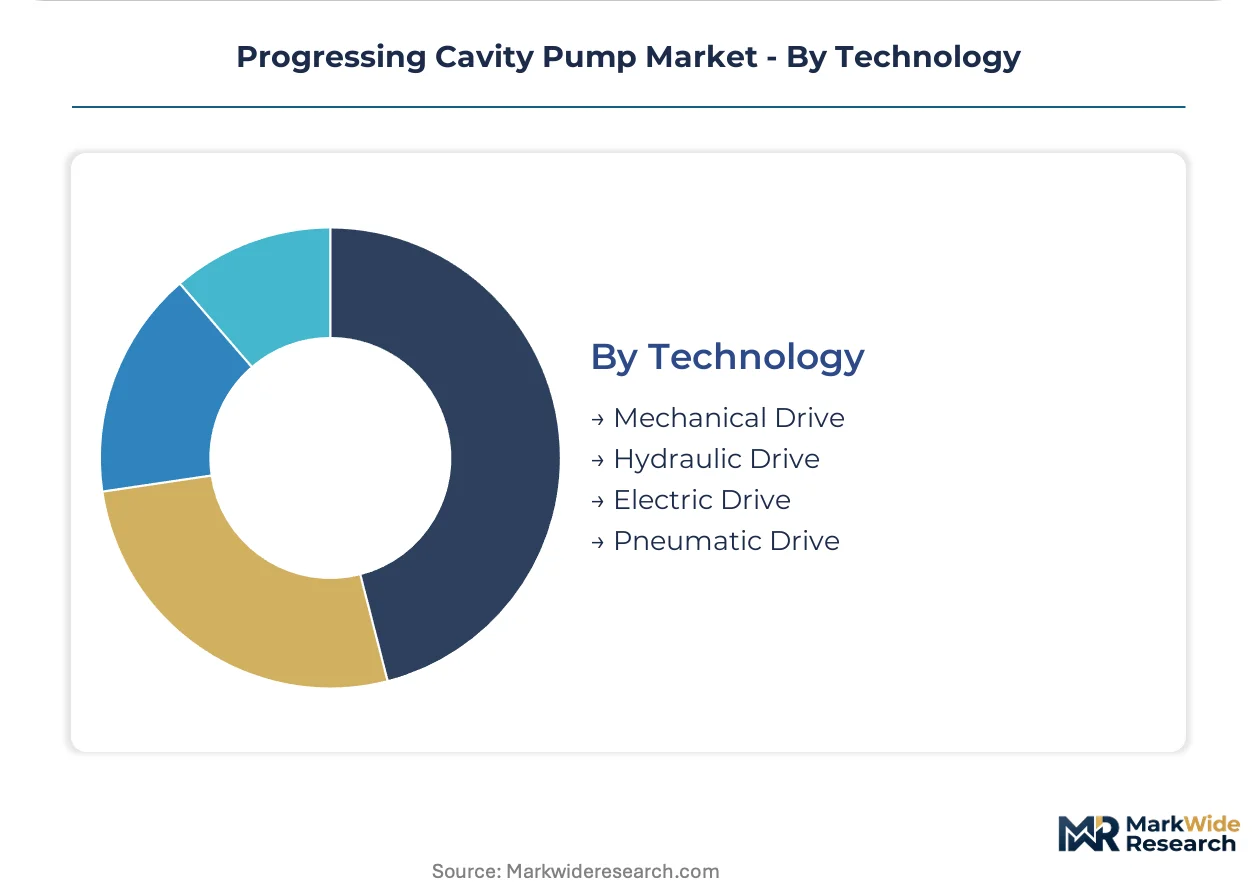
Technology:
Drive mechanism selection reflects energy efficiency mandates and maintenance headcount constraints, with electric systems displacing pneumatic and hydraulic alternatives in regulated environments.
- Electric Drive:Integrated pump-motor packages with embedded vibration and temperature sensors enable condition-based maintenance. Germany's wastewater sector and California's irrigation districts specify these configurations to meet energy targets and reduce field service requirements.
- Mechanical Drive:Direct-coupled and belt-driven systems persist in legacy installations and cost-sensitive applications where efficiency thresholds are less stringent.
- Hydraulic Drive:High-torque applications in oilfield service maintain limited deployment where variable speed control justifies fluid power complexity.
- Pneumatic Drive:Explosion-proof requirements in chemical processing sustain niche demand, though electric alternatives with ATEX certification are gaining specification share.
Mechanical Drive retains installed base dominance; Electric Drive is gaining share fastest through efficiency mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent guidelines and the EU Ecodesign Directive are redistributing procurement toward certified configurations across Germany, the United States, and China. Municipal retrofit programs and petrochemical cluster replacement cycles concentrate demand in specific industrial corridors.
United States
Municipal wastewater facilities face EPA-mandated solids-handling reliability standards that accelerate replacement timetables. The Bakken formation in North Dakota drives demand for hardened rotor coatings in produced water applications. California's Central Valley irrigation districts specify predictive maintenance interfaces as procurement standard.
Germany
Wastewater utilities systematically replace pneumatic systems with electric-drive configurations to meet site energy targets. The Ecodesign Directive constrains motor efficiency classes and REACH compliance filters elastomer chemistry options. Industrial demand concentrates in North Rhine-Westphalia's chemical processing corridor.
China
GB standards for mechanical equipment and energy labeling add parallel compliance layers for domestic manufacturers. The petrochemical cluster around Shanghai drives replacement cycles as aging installations reach end-of-service intervals. Yangtze River Delta chemical processors specify high-temperature configurations.
India
Chemical and pharmaceutical manufacturing expansion in Gujarat and Maharashtra presents demand for shear-sensitive fluid handling. The country's national industrial equipment regulator enforces mechanical safety standards that shape import qualification. Brownfield installations in these states require customized adapter kits.
Netherlands
Municipal procurement favors pump-motor-drive packages with embedded sensors for remote monitoring of distributed lift stations. The country's water management authority mandates reliability standards for flood control infrastructure. Port of Rotterdam chemical terminals specify corrosion-resistant configurations.
Progressing Cavity Pump Market Key Industry Players
Player mix skews toward integrated manufacturers with captive elastomer compounding capabilities and assembly-only competitors facing margin compression. The field collapses into two tiers: API-certified specialists serving upstream hydrocarbon service and modular architects addressing wastewater and food processing. Dominant competitive moves include backward integration into polymer synthesis and geographic expansion through distribution partnerships.
Within the integrated specialist tier, NETZSCH leverages German engineering heritage to occupy positions in high-temperature and chemically resistant configurations. SEEPEX exemplifies modular architecture approaches that reduce inventory complexity for municipal buyers. NOV anchors upstream positioning through artificial lift package integration. These three represent distinct archetypes: compounder-integrated engineering, application-modular systems, and oilfield-integrated solutions.
| Leading Market Players |
|---|
| NETZSCH |
| SEEPEX |
| NOV |
| CIRCOR International |
| SLB |
| Sulzer |
| Xylem |
| PCM |
| Roto Pumps |
| Others |
Cost & Logistics Intelligence
Specialty elastomer compounding scale in Germany and Japan establishes minimum efficient scale thresholds that filter out regional assemblers and compress margin pools for non-integrated competitors. API 676 certification infrastructure and REACH-compliant polymer synthesis capabilities concentrate pricing power among compounder-integrated manufacturers, while electric-drive retrofit demand in German wastewater utilities and California irrigation districts reshapes procurement toward bundled pump-motor packages with embedded sensor diagnostics.
Pricing Analysis
Certification level creates the primary spread between API 676-qualified upstream configurations and general-purpose wastewater units. Three-tier pricing structure across premium certified, standard industrial, and economy municipal levels reflects elastomer chemistry sophistication and motor efficiency class bundling. Cost compression in economy tiers intensifies because REACH authorization constraints on hydrogenated nitrile variants force reformulation investments that non-integrated assemblers cannot absorb. Municipal procurement teams in Germany and the Netherlands exhibit highest price sensitivity due to Ecodesign-driven retrofit budget cycles, while oilfield operators in North Dakota's Bakken formation prioritize run-life economics over unit cost.
Supply Chain Analysis
Germany and Japan anchor specialty elastomer compounding for high-temperature stator formulations, while China concentrates on standard nitrile variants and electric motor assembly. Raw material flows draw from concentrated hydrogenated nitrile rubber suppliers, tungsten carbide coating feedstock providers, and rare-earth magnet processors for integrated drive packages. Single-source vulnerability in REACH-authorized specialty polymer grades creates qualification bottlenecks that extend lead times for European manufacturers. Distribution runs through OEM-direct channels for oilfield artificial lift packages and regional fluid-handling distributors for municipal wastewater retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as electric-drive retrofit mandates and REACH compliance requirements splinter demand across certification tiers, creating defendable niches for compounder-integrated specialists and modular architects alike.
For Market Incumbents: Fortify captive elastomer synthesis capabilities to maintain formulation control as ECHA candidate list expansion accelerates. Secure API 676 recertification ahead of upstream hydrocarbon demand cycles. Defend against centrifugal pump substitution in low-viscosity water treatment by embedding predictive maintenance interfaces as standard configuration. For New Entrants and Emerging Players: CE marking fast-track for electric-drive wastewater configurations opens procurement access in German municipal retrofit programs. Target India's Gujarat pharmaceutical corridor for shear-sensitive fluid handling where brownfield adapter kit customization creates service revenue anchoring. Pursue distribution partnerships with European fluid-handling specialists rather than direct OEM competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounder-integrated mid-cap specialists with demonstrated REACH compliance infrastructure. Long-term viability hinges on backward integration depth rather than assembly scale. Watch for inflection in ECHA authorization timelines for hydrogenated nitrile variants as signal for margin redistribution between integrated and non-integrated tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | REACH compliance and formulation control separate margin tiers in European supply. |
| API 676 Recertification Investment | Upstream hydrocarbon qualification collapses competitive field to certified manufacturers. |
| Predictive Maintenance Interface Development | California irrigation districts and Dutch municipalities now specify embedded sensor diagnostics. |
| Electric-Drive Package Bundling | German Ecodesign mandates favor integrated pump-motor configurations over retrofits. |
| Regional Distribution Partnership Expansion | India's Gujarat corridor and Shanghai petrochemical cluster demand localized service presence. |
Research Approach
A standing panel of maintenance directors at German wastewater utilities, plant engineers in Shanghai's petrochemical corridor, aftermarket service heads at oilfield artificial lift operators, and OEM procurement teams provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA effluent guideline filings, ECHA REACH authorization databases, SEC 10-K disclosures from listed pump manufacturers, and German engineering association technical bulletins. Bottom-up unit economics triangulated against top-down market sizing across product type, application, and technology segmentation dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled progression rates by duty severity, thermal envelope, drive mechanism, and end-user capital intensity. CAGRs derived from replacement cycle analysis in regulated jurisdictions and capacity expansion patterns in China's Yangtze River Delta. Industry-specific inputs included REACH authorization timeline assumptions and Ecodesign motor efficiency class adoption curves.
Underlying assumptions cover regulatory enforcement continuity, specialty polymer supply stability, and electric-drive retrofit funding availability, with deviation risk concentrated in ECHA candidate list expansion timing and upstream hydrocarbon capital allocation cycles. Recalibration cycles align with material shifts in REACH authorization procedures and EPA effluent guideline revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Mud Pumps Market