
 Drum Pump Market | 2026-2036
Drum Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Pump Market Analysis
REACH chemical handling mandates in Europe and EPA fugitive emission rules in the United States are decoupling drum pump procurement from pure cost metrics toward sealed-system specifications. Graco Inc. leverages its fluid handling engineering heritage to dominate high-viscosity chemical transfer applications. Lutz Pumpen GmbH anchors European demand through German-manufactured stainless steel immersion pumps with ATEX certification. PSG Dover Inc. competes across multiple industrial verticals through its diversified pump platform architecture.
A drum pump is a portable fluid transfer device designed to evacuate liquids from barrels, drums, and intermediate bulk containers, typically featuring immersion tube lengths of 27 to 47 inches and flow rates spanning 5 to 70 gallons per minute depending on motor configuration. Electric drum pumps lead product type demand in continuous-duty chemical processing environments where operator fatigue from manual actuation creates throughput bottlenecks. Stainless steel material configurations command premium positioning in pharmaceutical end-user segments where surface finish standards and clean-in-place compatibility govern procurement specifications. Food and beverage application demand is accelerating as processors replace fixed piping with flexible transfer equipment to accommodate SKU proliferation and allergen segregation protocols.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate closed-loop liquid transfer in chemical manufacturing, directly shaping drum pump sealing technology requirements. OSHA workplace exposure limits for volatile organic compounds further drive demand for vapor-recovery pump configurations in solvent-handling operations. Stakeholders must monitor evolving per- and polyfluoroalkyl substances restrictions across state-level regulatory frameworks, as material compatibility certifications for fluoropolymer pump components face prospective revision that could alter supplier qualification timelines and retrofit obligations.
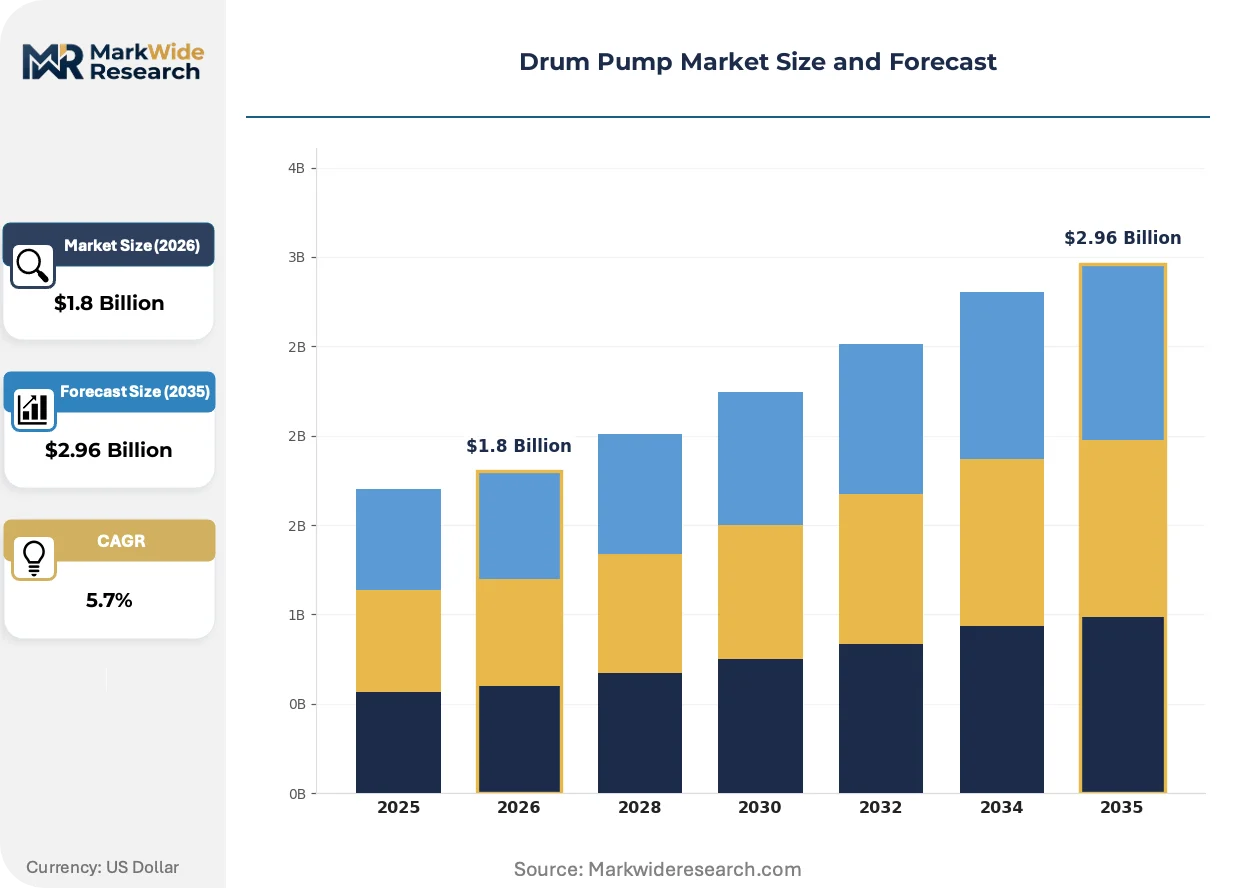
Market Dynamics
REACH and EPA emissions mandates are decoupling drum pump procurement from pure cost metrics toward sealed-transfer specifications, forcing chemical processors to retire legacy open-system equipment ahead of regulatory deadlines.
Growth Catalysts
- REACH chemical handling mandates:European chemical processors must deploy closed-loop transfer systems to eliminate fugitive emissions, creating immediate replacement demand for sealed drum pump configurations.
- Electric motor technology:Continuous-duty manufacturing environments in East Asian chemical corridors are abandoning manual actuation to resolve operator fatigue bottlenecks and throughput constraints.
- Food allergen segregation protocols:North American food processors are replacing fixed piping with flexible transfer equipment to accommodate SKU proliferation and prevent cross-contamination incidents.
Market Restraints
- Stainless steel input volatility:Pharmaceutical-grade surface finish requirements depend on austenitic steel grades whose nickel content exposes manufacturers to London Metal Exchange price swings.
- German supply concentration:ATEX-certified immersion pump production clusters disproportionately in Baden-Württemberg, creating single-source vulnerability for European chemical processors.
- Peristaltic substitution threat:Hose pump technology is capturing low-viscosity chemical transfer applications previously served by centrifugal drum pumps in batch processing environments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO inspection intensity and export compliance requirements are driving domestic adoption of clean-in-place compatible pump systems.
- US state-level PFAS restrictions:California and Maine regulations targeting fluoropolymer components are creating retrofit obligations that favor suppliers with rapid material certification capabilities.
- Digital inventory integration:Industrial distributors are embedding pump specification data into vendor-managed inventory platforms, compressing specification-to-delivery cycles for maintenance procurement.
Industry Challenges
- ATEX certification timelines:Notified body queue congestion in Germany extends explosion-proof pump qualification cycles, delaying product launches for manufacturers targeting European chemical facilities.
- Legacy system integration friction:Sealed-transfer retrofits require mechanical interface adaptation with existing drum handling equipment, complicating deployment in brownfield processing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Pump Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Pneumatic, Vacuum Material: Plastic, Stainless Steel, Polypropylene, Aluminum Application: Chemical Transfer, Diesel Dispensing, Food and Beverage, Paint Supply End User: Industrial, Agricultural, Pharmaceutical, Automotive |
| Companies Covered | Flux, Tapflo AB, Graco Inc., Gorman-Rupp Company, Yamada America, Inc., Lutz Pumpen GmbH, PSG Dover Inc., Standard Pump, Finish Thompson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Pump Market Emerging Trajectories
Sealed-system engineering and smart monitoring capabilities are converging to redefine equipment specification criteria, with chemical processors now prioritizing emission containment and predictive maintenance over baseline flow performance.
Brushless DC motor technology is overtaking traditional AC induction designs in portable drum pump applications. Pharmaceutical cleanrooms and semiconductor chemical handling facilities are specifying electronically commutated drives for their variable speed precision and reduced spark risk. This motor architecture is overtaking legacy pneumatic alternatives in solvent transfer operations where compressed air infrastructure is absent.
EPA National Emission Standards for Hazardous Air Pollutants now mandate closed-loop liquid transfer in US chemical manufacturing, directly shaping sealing technology roadmaps. Mechanical seal manufacturers are accelerating perfluoroelastomer compatibility testing to meet vapor-recovery pump specifications. Batch chemical producers in Texas and Louisiana are responding by consolidating supplier qualifications around vendors with pre-validated emission containment packages.
Vendor-managed inventory contracts are displacing spot procurement for maintenance, repair, and operations categories. Industrial distributors are capturing drum pump specification authority previously held by plant engineering departments through integrated e-procurement platforms. This shift is most visible in German automotive chemical supply chains, where Just-in-Sequence delivery requirements favor suppliers with real-time inventory visibility systems.
Drum Pump Market Segmentation
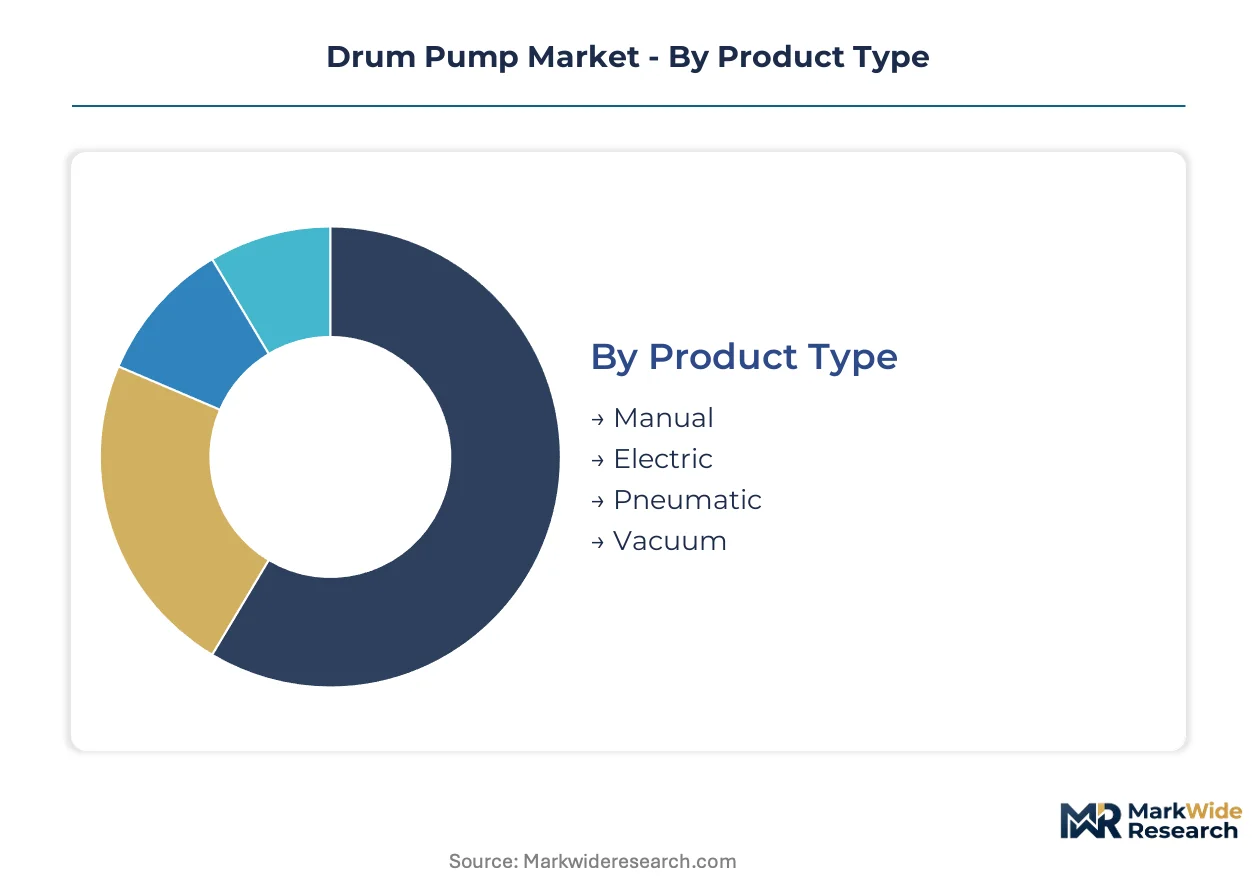
Drum pump procurement patterns diverge sharply across operating environments, with regulatory pressure and fluid compatibility requirements fragmenting specification criteria. Manufacturers must align product architectures to distinct duty cycles, chemical resistance profiles, and cleanliness standards rather than pursuing universal designs.
Product Type:
Supply concentration for motor and actuator components clusters around specialized industrial drive manufacturers in Germany and Japan, shaping regional availability and service networks for finished pump assemblies.
- Manual:Hand-cranked rotary or lever-actuated mechanisms deliver 5-15 gallons per minute for intermittent transfer of low-viscosity fluids. Demand concentrates in agricultural cooperatives across the US Midwest and French wine regions where electrical infrastructure is unreliable and batch volumes remain modest.
- Electric:AC induction or brushless DC motors power continuous-duty evacuation at 20-70 gallons per minute. East Asian chemical manufacturing corridors in China's Yangtze River Delta and South Korea's Ulsan petrochemical complex are standardizing on sealed electric configurations to satisfy EPA and REACH emission containment mandates.
- Pneumatic:Compressed-air-driven diaphragm or piston pumps operate in explosion-risk zones without electrical ignition sources. ATEX-certified pneumatic units dominate solvent handling in German chemical parks and Texas Gulf Coast refineries.
- Vacuum:Ejector-based systems generate suction through venturi effect for viscous or shear-sensitive fluid recovery. Niche deployment in pharmaceutical cleanrooms and semiconductor chemical handling facilities where product integrity overrides throughput priorities.
Electric configurations absorb the bulk of installed capacity in continuous manufacturing; manual systems are expanding most quickly in emerging agricultural markets with constrained capital budgets.
Material:
Raw material sourcing geography and surface finish certification requirements create tiered procurement economics that separate pharmaceutical-grade from industrial-grade supply streams.
- Plastic:Injection-molded polypropylene or PVDF housings resist acids and alkalis at sub-60°C operating temperatures. Cost-sensitive chemical processors in India's Gujarat chemical belt specify plastic immersion tubes for sulfuric acid and caustic soda transfer where metallic corrosion would accelerate replacement cycles.
- Stainless Steel:AISI 316L austenitic grades with Ra 0.8 surface finishes enable clean-in-place sterilization protocols. Pharmaceutical manufacturers in Switzerland's Basel region and North Carolina's Research Triangle demand electropolished stainless configurations to satisfy FDA and EMA aseptic processing guidelines.
- Polypropylene:Reinforced thermoplastic construction balances chemical resistance with weight reduction for portable field applications. Wastewater treatment operators in Australia's mining regions favor polypropylene for hydrochloric acid dosing where equipment mobility matters.
- Aluminum:Die-cast alloy housings with anodized surfaces serve lightweight diesel and lubricant dispensing in automotive service bays. German automotive supplier parks specify aluminum-bodied pumps for Just-in-Sequence fluid delivery to assembly lines.
Stainless steel commands the premium tier on specification sheets; plastic variants are gaining share fastest in price-pressured emerging market installations.
Application:
End-use fluid properties—viscosity, volatility, particulate load, and toxicity—dictate pump architecture selection more than any other dimension, creating application-specific supplier relationships.
- Chemical Transfer:Sealed-system designs with mechanical seals or magnetic drives prevent fugitive emissions of chlorinated solvents and aromatic hydrocarbons. Louisiana and Texas chemical processors facing EPA National Emission Standards enforcement are retiring open-transfer equipment for vapor-recovery configurations.
- Diesel Dispensing:Explosion-proof electric or manual rotary pumps with grounding provisions handle petroleum distillates in mining and construction fleets. Australian and Canadian remote resource extraction sites specify diesel transfer pumps with integrated flow meters for fuel accountability.
- Food and Beverage:FDA-compliant materials and sanitary quick-disconnect fittings support allergen segregation and cleanability. North American dairy processors and European craft brewers are replacing fixed piping with flexible transfer equipment to accommodate SKU proliferation.
- Paint Supply:Precision gear or diaphragm pumps deliver shear-sensitive coatings without pigment degradation. Automotive OEM paint shops in Stuttgart and Detroit specify stainless steel pumps with variable speed control for robotic application systems.
Chemical transfer applications anchor supplier revenue; food and beverage installations are climbing the fastest as allergen management protocols proliferate.
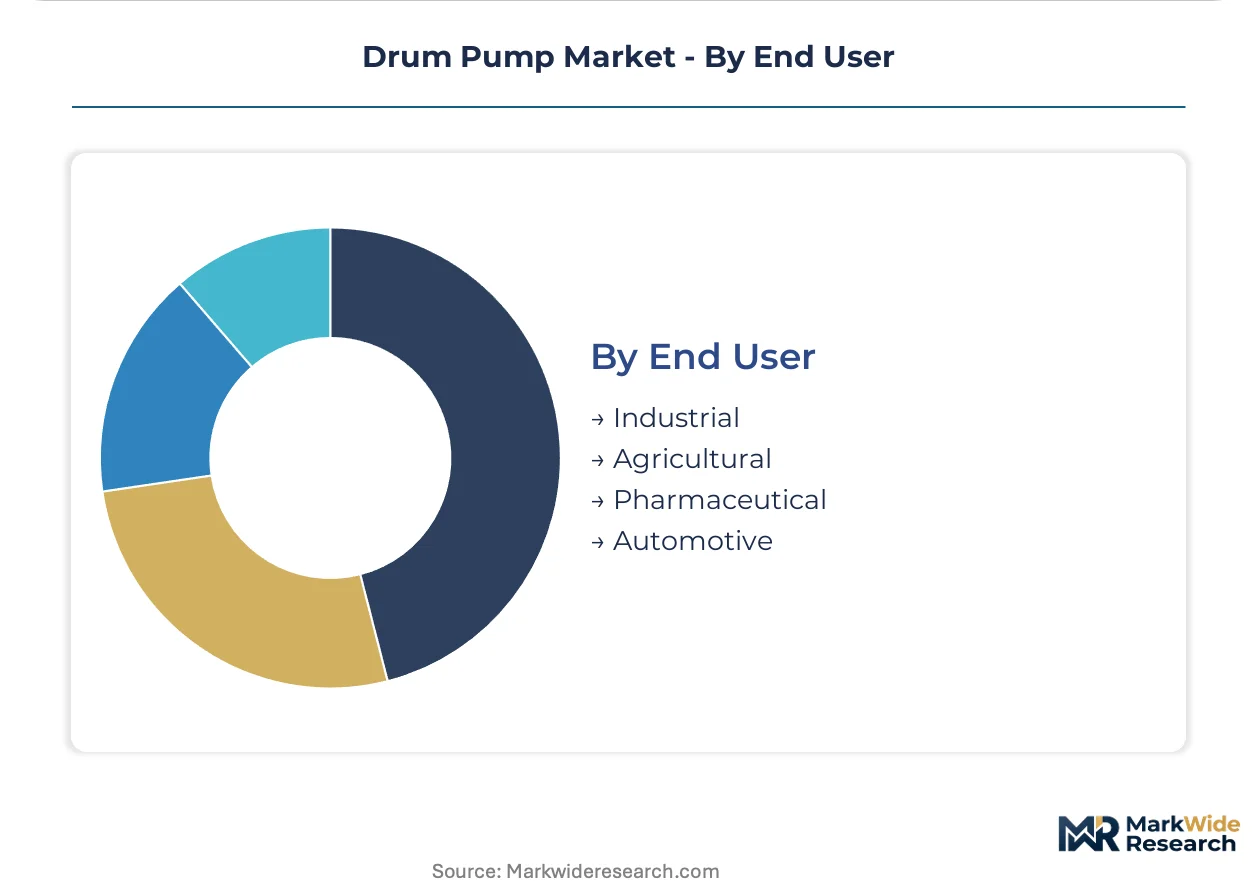
End User:
Customer scale and compliance burden stratify the market, with multinational pharmaceutical and automotive manufacturers driving specification standards that cascade to smaller operators.
- Industrial:Chemical, petrochemical, and general manufacturing facilities operating 24/7 duty cycles demand redundant pump configurations with predictive maintenance integration. German automotive chemical supply chains are embedding pump specification data into vendor-managed inventory platforms.
- Agricultural:Crop protection chemical handling and fuel transfer for mechanized operations require portable, corrosion-resistant equipment. Brazilian soybean producers and Ukrainian grain cooperatives prioritize manual and small electric pumps for seasonal application windows.
- Pharmaceutical:Aseptic processing and active pharmaceutical ingredient manufacturing impose surface finish, material certification, and documentation requirements. CDSCO-inspected facilities in India's Hyderabad-Visakhapatnam corridor are adopting clean-in-place compatible systems for export compliance.
- Automotive:Assembly line fluid delivery and aftermarket service operations specify quick-change pumps for multi-fluid flexibility. Mexican automotive supplier parks serving US OEMs are consolidating procurement around suppliers with IATF 16949 quality certification.
Industrial end users represent the largest installed base; pharmaceutical applications are expanding most steeply as biologics manufacturing capacity multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's chemical parks anchor European drum pump specification standards, with Stuttgart automotive suppliers driving Just-in-Sequence fluid delivery requirements that cascade across supplier networks.
United States
Louisiana and Texas chemical processors face EPA National Emission Standards enforcement for hazardous air pollutants. The mandate for closed-loop liquid transfer is retiring open-system equipment ahead of regulatory deadlines. Houston-Galveston refineries are consolidating procurement around vapor-recovery pump configurations.
Germany
REACH chemical handling mandates require sealed-transfer systems to eliminate fugitive emissions in European chemical processing. ATEX certification from German Notified Bodies governs explosion-proof equipment qualification. Ludwigshafen's chemical complex and Frankfurt's pharmaceutical corridor are standardizing on stainless steel immersion pumps with electropolished finishes.
China
Yangtze River Delta manufacturing corridors are abandoning manual drum pumps for electric configurations to resolve operator fatigue in continuous-duty environments. China's Ministry of Ecology and Environment enforces volatile organic compound emission controls. Shanghai and Ningbo petrochemical zones are embedding predictive maintenance capabilities into sealed-system procurement specifications.
India
Hyderabad-Visakhapatnam pharmaceutical manufacturing is adopting clean-in-place compatible pump systems to satisfy CDSCO inspection intensity and export compliance requirements. India's Bureau of Indian Standards governs equipment certification timelines. Gujarat's chemical belt specifies plastic immersion tubes for corrosive acid transfer where cost pressures dominate procurement decisions.
Japan
Osaka-Kobe industrial corridors specify brushless DC motor configurations for semiconductor chemical handling facilities requiring spark-risk reduction. Japan's Ministry of Economy, Trade and Industry promotes manufacturing efficiency standards. Tokyo Bay pharmaceutical cleanrooms are prioritizing variable speed precision over baseline flow performance in equipment selection.
Drum Pump Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with fluid handling heritage. Market concentration remains moderate, with regional specialists capturing premium niches through certification authority. Three archetypes dominate: diversified pump platform operators, German-engineered precision specialists, and Japanese motor-drive integrators. Capacity expansion in East Asian manufacturing corridors and strategic partnerships for digital inventory integration represent the dominant competitive moves.
Within the diversified platform tier, Graco Inc. and PSG Dover Inc. exemplify multi-vertical coverage strategies. Lutz Pumpen GmbH anchors German-engineered precision positioning through its Baden-Württemberg manufacturing base. Tapflo AB and Yamada America, Inc. occupy positions within pneumatic and diaphragm pump specializations. Flux represents European fluid handling heritage, while Gorman-Rupp Company and Standard Pump sit within North American industrial distribution networks. Finish Thompson exemplifies material-specialist positioning for corrosive chemical applications.
| Leading Market Players |
|---|
| Flux |
| Tapflo AB |
| Graco Inc. |
| Gorman-Rupp Company |
| Yamada America, Inc. |
| Lutz Pumpen GmbH |
| PSG Dover Inc. |
| Standard Pump |
| Finish Thompson |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ATEX-validated sealed systems and commodity open-transfer equipment manifests in both pricing premiums and supply chain qualification burdens. Pharmaceutical processors in Basel and North Carolina absorb 40-60% cost premiums for electropolished stainless configurations, while German automotive chemical supply chains embed specification authority into vendor-managed inventory platforms that compress procurement cycles.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for continuous-duty electric configurations in East Asian chemical corridors. Pricing stratifies across ATEX-certified premium tiers, standard industrial grades, and economy manual alternatives, with nickel-content volatility in austenitic steel grades forcing dynamic adjustment clauses in pharmaceutical supply agreements. Cost compression in plastic immersion tubes intensifies as Indian and Chinese processors prioritize acid-transfer durability over surface finish precision. Agricultural cooperatives exhibit highest price sensitivity, while semiconductor cleanrooms demonstrate near-zero elasticity for spark-risk-compliant brushless DC systems.
Supply Chain Analysis
Dual-sourcing mandates from Texas and Louisiana chemical processors require qualified backup suppliers for vapor-recovery pump configurations, extending ATEX certification timelines. Manufacturing gravity centers on Germany, Japan, and China, with Baden-Württemberg housing disproportionate concentration of explosion-proof immersion pump production. Raw material dependencies span nickel-bearing austenitic steels, perfluoroelastomer seal compounds, and brushless DC motor drives. Single-source vulnerability in German Notified Body certification queues creates regulatory chokepoint risk. Distribution runs through industrial distributor networks capturing specification authority from plant engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATEX certification queue congestion at German Notified Bodies constrains qualified supplier capacity, propping pricing power for pre-certified incumbents while extending lead times for new market entrants.
For Market Incumbents: Anticipate peristaltic substitution threats in low-viscosity batch processing by accelerating magnetic drive development for shear-sensitive applications. Secure backward integration into perfluoroelastomer seal manufacturing to hedge fluoropolymer regulatory exposure from California and Maine PFAS restrictions. Channel control through vendor-managed inventory platform partnerships defends specification authority against distributor consolidation. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian pharmaceutical manufacturing invites clean-in-place compatible plastic pump development for CDSCO-inspected facilities prioritizing export compliance over European surface finish standards. Target Gujarat chemical belt cost-sensitive acid-transfer applications with reinforced polypropylene configurations. Go-to-market leverage rests on rapid material certification capabilities for state-level fluoropolymer retrofit obligations. For Investors and Strategic Acquirers: Re-rating potential sits with Japanese brushless DC motor integrators given semiconductor chemical handling demand and spark-risk regulatory tightening. Long-term viability favors specialists with dual certification authority across ATEX and FDA/EMA quality tiers. Monitor California Air Resources Board PFAS rulemaking timelines as inflection indicator for fluoropolymer component retrofit cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ATEX Certification Pre-Validation | German Notified Body queue congestion rewards early qualification investment with specification lock-in at Louisiana refineries. |
| Vendor-Managed Inventory Integration | Real-time inventory visibility captures specification authority from plant engineering in Stuttgart automotive supply chains. |
| Perfluoroelastomer Material Certification | Rapid compliance capabilities exploit California and Maine fluoropolymer retrofit obligations before competitors qualify alternatives. |
| Brushless DC Motor Platform Expansion | Electronically commutated drives displace pneumatic alternatives in solvent transfer where compressed air infrastructure is absent. |
| Clean-in-Place Compatible System Development | CDSCO inspection intensity in Hyderabad-Visakhapatnam corridor drives domestic adoption for export-compliant pharmaceutical manufacturing. |
Methodological Framework
Document review covered SEC 10-K filings from fluid handling conglomerates, ECHA REACH compliance databases, and EPA National Emission Standards enforcement records, complemented by interviews with plant engineers at Texas Gulf Coast refineries, procurement leads at German automotive chemical suppliers, and aftermarket service heads at industrial distributors. Secondary validation drew from customs trade data, ATEX certification registries, and pharmaceutical equipment qualification guidelines. Bottom-up installation base estimates triangulated against top-down chemical processing capacity expansion projections.
Segment-level outputs across the analysis window reflect modeled interactions between motor configuration, material grade, and end-use regulatory burden. The framework incorporated product type, application viscosity class, cleanliness standard, and regional emissions enforcement intensity as core dimensions. CAGRs were derived from regression against chemical processing capacity additions, pharmaceutical manufacturing investment flows, and food allergen protocol adoption curves.
Inputs from EPA enforcement databases and ECHA registration timelines were available through the study window; gaps in real-time ATEX certification queue data introduce uncertainty bands around supplier qualification timeline assumptions. Deviation in German Notified Body resource allocation or state-level PFAS rulemaking acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Dry Vacuum Pumps Market