
 Vertical Inline Pumps Market | 2026-2036
Vertical Inline Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Inline Pumps Market Analytics
The gap between premium smart-pumping systems and commodity electric inline units is expanding across municipal and industrial procurement channels. Flowserve leverages its aftermarket service network to anchor long-term contracts with North American water utilities. Pentair competes on energy-efficient motor designs that meet escalating efficiency thresholds for commercial HVAC retrofits.
Vertical inline pumps are close-coupled centrifugal devices where the pump impeller mounts directly on the motor shaft, eliminating baseplate requirements and reducing footprint to one-third of frame-mounted alternatives; they operate at rotational speeds between 1,450 and 2,900 RPM with discharge diameters from 32 mm to 300 mm, serving primarily in building services, water transfer, and pressurized distribution loops. Centrifugal designs dominate installed base volumes across water supply and wastewater management applications, while smart pumping technology with embedded variable frequency drives captures disproportionate margin pools in industrial facilities pursuing demand-responsive flow control. HVAC applications sustain steady replacement cycles in mature urban markets, whereas agriculture irrigation segments show faster technology uptake where electricity tariffs incentivize load-shifting pump operation.
EPA Clean Water Act standards and ISO 5198 test protocols shape minimum hydraulic efficiency and material specifications for products sold into US municipal systems; China's GB/T 5657 national standards and MEE water quality regulations impose comparable performance floors for domestic manufacturers and imported equipment. Stakeholders must monitor how fragmented national efficiency regimes affect cross-border product platform strategies and certification costs.
Market Dynamics
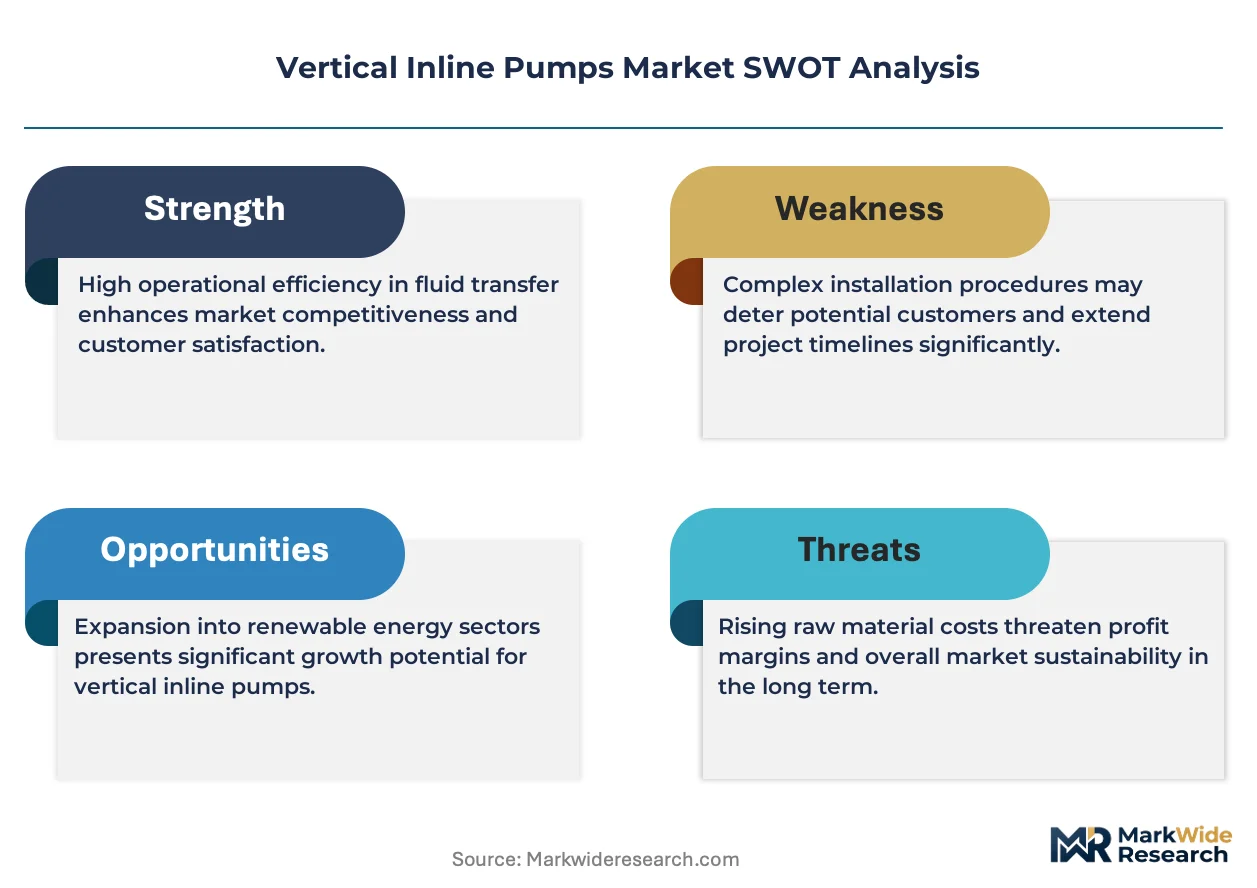
The divergence between premium smart-pumping architectures and commodity inline units is compressing mid-tier supplier margins while rewarding vertically integrated manufacturers with captive motor and control production.
Growth Catalysts
- EPA efficiency mandates:US municipal water utilities face replacement deadlines for aging infrastructure, accelerating procurement of variable frequency drive-equipped systems that meet Clean Water Act performance floors.
- China rural-urban distribution expansion:Provincial water conservancy bureaus are deploying high-pressure inline pumps across inter-basin transfer projects connecting agricultural hinterlands to coastal manufacturing zones.
- Embedded IoT diagnostics:Predictive maintenance algorithms integrated into pump motor controllers are reducing unplanned downtime for industrial process cooling loops.
Market Restraints
- Copper and rare earth magnet volatility:Permanent magnet motor costs fluctuate with neodymium supply from concentrated Chinese refining operations, squeezing OEM margin predictability.
- ISO 5198 certification timelines:Third-party hydraulic testing protocols add six-to-nine month lead times for new product introductions into North American municipal channels.
- Frame-mounted pump substitution:Large-capacity HVAC retrofits above 75 kW sometimes favor baseplate-mounted split-case designs with lower first-cost despite footprint disadvantages.
Strategic Opportunities
- India AMRUT 2.0 urban water missions:Smart metering integration with pressurized distribution networks creates demand for digitally native inline pump skids in secondary cities.
- EU F-Gas Regulation phase-down:Refrigerant transition in commercial cooling systems is elevating pump efficiency requirements for low-global-warming-potential chiller retrofits.
- Agricultural load-shifting incentives:Time-of-use electricity tariffs in Australia's Murray-Darling Basin are driving variable-speed pump adoption for precision irrigation scheduling.
Industry Challenges
- Cross-platform firmware integration:Building automation system protocols from Siemens, Honeywell, and Johnson Controls require custom gateway development for seamless pump control integration.
- Skilled commissioning technician scarcity:Proper alignment of close-coupled motor-pump assemblies demands specialized vibration analysis expertise that utilities struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Inline Pumps Market |
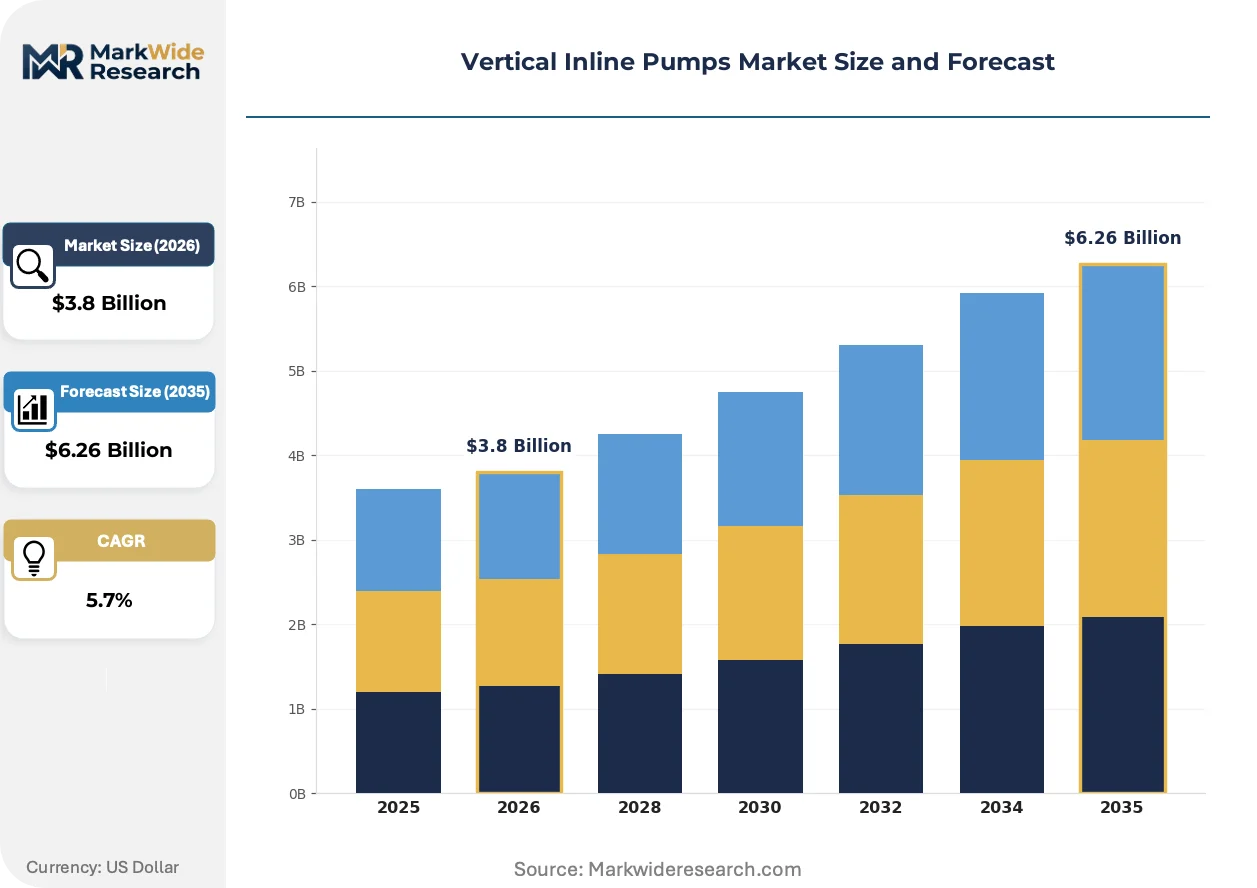
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Submersible, Positive Displacement, Diaphragm Application: Water Supply, Wastewater Management, Agriculture Irrigation, HVAC End User: Municipalities, Industrial Facilities, Residential, Agricultural Technology: Smart Pumping, Variable Frequency Drives, Electric, Thermal |
| Companies Covered | Flowserve, Pentair, Xylem, Wilo, Ebara, Sulzer, KSB, Ruhrpumpen, Grundfos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Inline Pumps Market Evolving Landscape
Digital twin technology and edge-computing architectures are redefining how pump performance is monitored, optimized, and monetized across asset-heavy industries.
Permanent magnet synchronous motors with integrated variable frequency drives are electrifying efficiency benchmarks in the 1.5-22 kW power range. Data center cooling operators in Singapore and Frankfurt are specifying these configurations for demand-responsive flow modulation. The technology is electrifying traditional induction motor supply chains by collapsing separate component procurement into single-source integrated units.
China's MEE water quality regulations and GB/T 5657 efficiency standards are tightening discharge head and power consumption thresholds for equipment sold into domestic municipal networks. Domestic manufacturers must retest legacy platforms against revised hydraulic performance curves. Imported equipment faces extended conformity assessment periods, favoring joint-venture production within Chinese free-trade zones.
Performance-based service contracts are displacing traditional break-fix maintenance arrangements in North American industrial water treatment facilities. End-users now specify guaranteed availability metrics rather than equipment ownership, transferring operational risk to OEM service organizations. This restructuring is most advanced in Texas and California chemical processing clusters where water scarcity elevates pump reliability to strategic priority status.
Vertical Inline Pumps Market Segmentation
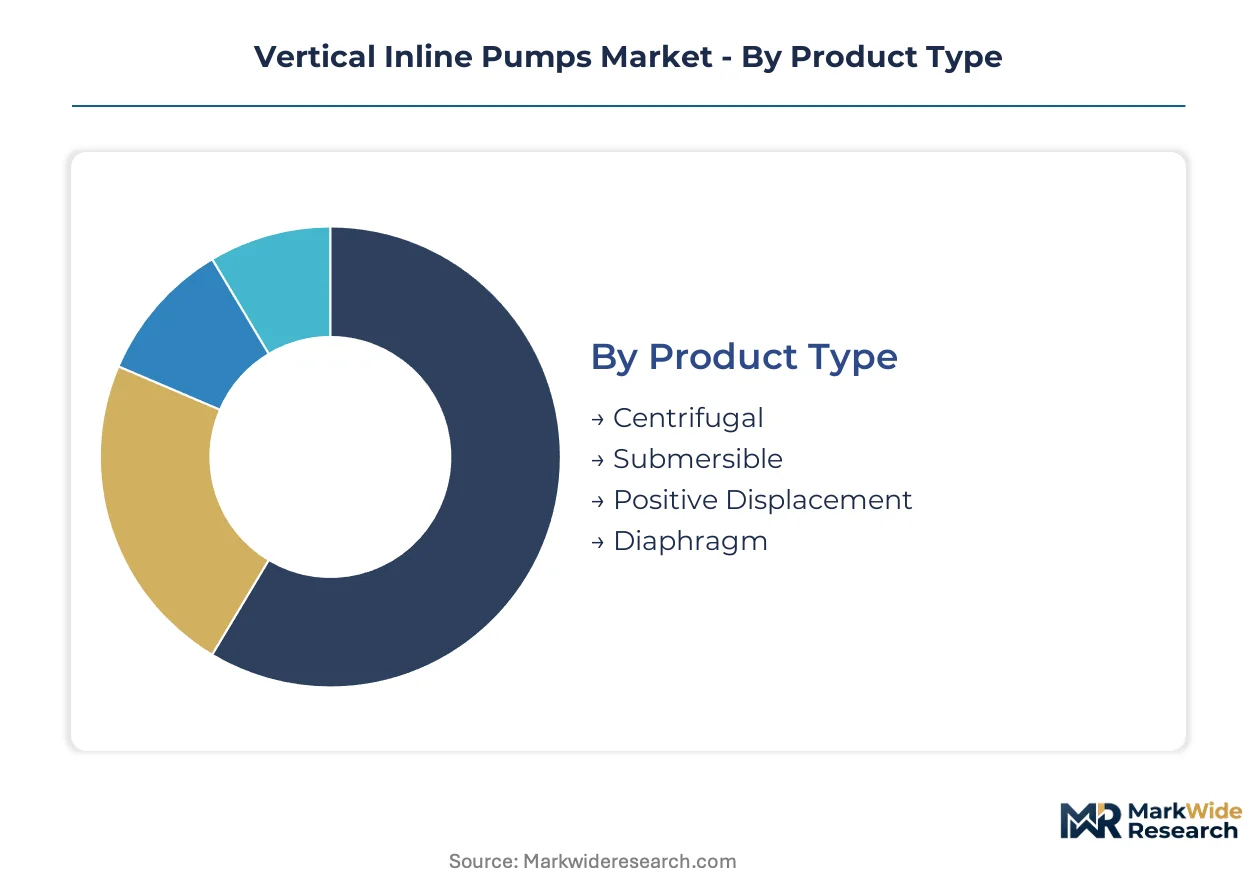
Vertical inline pump procurement decisions hinge on hydraulic duty, control sophistication, and lifecycle cost calculations rather than upfront capital alone. Buyers weigh energy recovery potential against maintenance accessibility across markedly different operating environments.
Product Type:
Impeller geometry and sealing architecture determine which configurations withstand specific fluid characteristics and pressure regimes.
- Centrifugal:Radial and mixed-flow impeller designs dominate high-volume water transfer applications with discharge heads between 10 and 150 meters. Municipal water utilities in Texas and California specify these for distribution network booster stations where EPA efficiency mandates drive variable-speed retrofits.
- Submersible:Hermetically sealed motor-pump units operate fully immersed in source water or process fluids, eliminating suction lift limitations. Deep-well extraction projects in India's Gujarat and Rajasthan states deploy these for groundwater withdrawal where bore depths exceed 200 meters.
- Positive Displacement:Rotary gear and progressing cavity mechanisms handle viscous fluids and precise metering duties in chemical processing.
- Diaphragm:Air-operated and mechanical designs isolate pumped media from drive components for abrasive slurry handling.
Volume sits with Centrifugal; growth tilts toward Submersible.
Application:
Operating context dictates materials selection, duty cycles, and redundancy requirements across installed bases.
- Water Supply:Potable water distribution demands NSF-certified materials and continuous-duty motors rated for 20-year service intervals. China's provincial water conservancy bureaus are expanding inter-basin transfer capacities connecting agricultural hinterlands to coastal manufacturing zones.
- HVAC:Chilled water and condenser circuits require compact footprints for mechanical room retrofits where space constraints eliminate frame-mounted alternatives. Commercial building operators in Singapore and Frankfurt specify integrated variable frequency drive packages for demand-responsive thermal load management.
- Wastewater Management:Abrasion-resistant impellers and volutes handle solids-laden effluent in municipal treatment plants.
- Agriculture Irrigation:Seasonal operation patterns favor pumps with rapid startup characteristics and tolerance for voltage fluctuation.
Water Supply commands installed base volume; HVAC exhibits steepest expansion trajectory.
End User:
Procurement sophistication varies sharply between centralized utility buyers and fragmented agricultural operators.
- Municipalities:Public-sector procurement cycles emphasize lifecycle cost analysis and guaranteed efficiency performance under ISO 5198 test protocols. US water utilities face replacement deadlines for infrastructure installed during mid-20th century expansion programs.
- Industrial Facilities:Process cooling and boiler feed applications prioritize uptime assurance through predictive maintenance contracts. Texas and California chemical processing clusters specify availability guarantees rather than equipment ownership, transferring operational risk to OEM service organizations.
- Residential:Multi-building pressure boosting systems serve high-rise developments with intermittent demand profiles.
- Agricultural:Price-sensitive buyers respond to time-of-use electricity tariffs with load-shifting pump scheduling.
Municipalities anchor procurement volume; Industrial Facilities show fastest technology refresh rates.
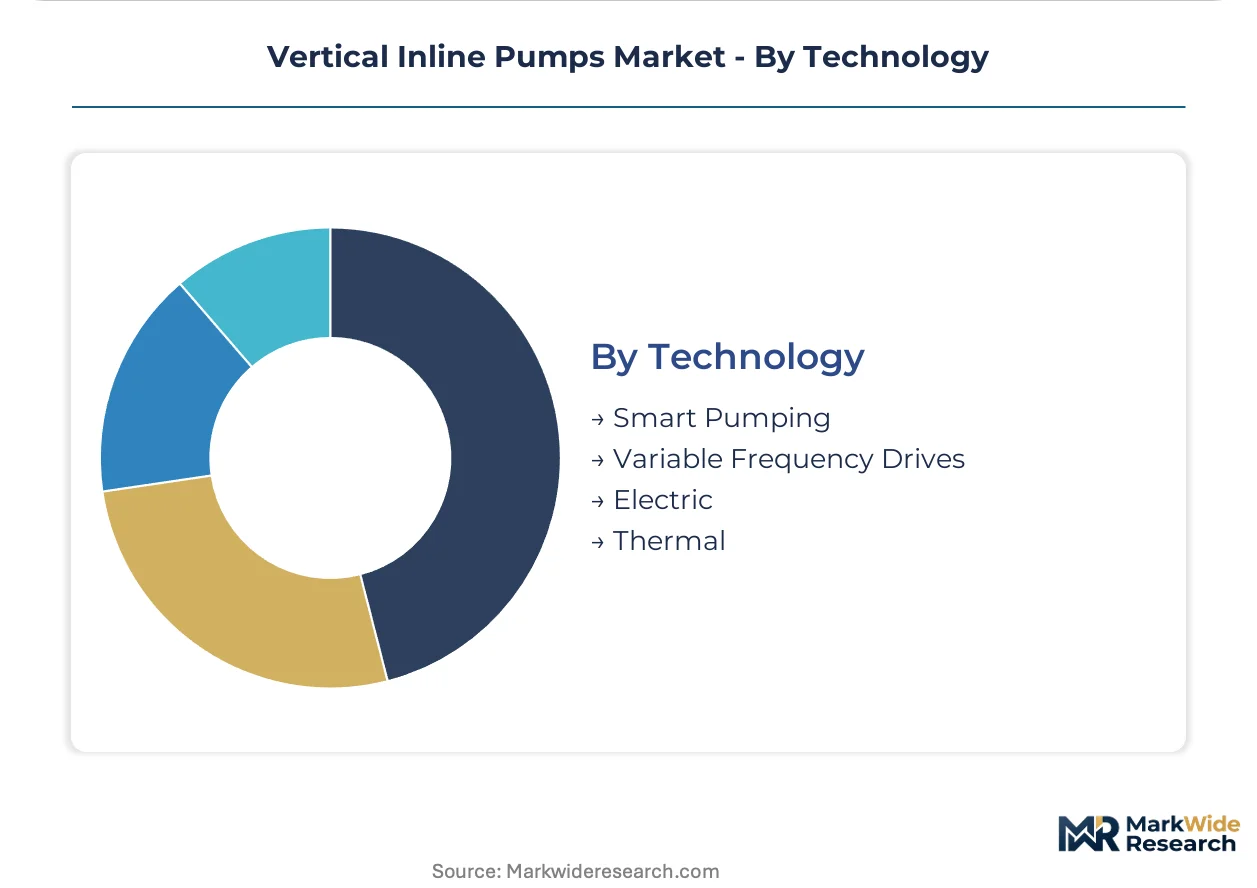
Technology:
Motor and control integration levels separate commodity hardware from premium system architectures.
- Smart Pumping:Embedded sensors and edge-computing controllers enable predictive maintenance algorithms that reduce unplanned downtime. Data center cooling operators specify these configurations for demand-responsive flow modulation in Singapore and Frankfurt facilities.
- Variable Frequency Drives:Separate inverter units retrofitted to existing motors capture efficiency gains without full pump replacement. Australia's Murray-Darling Basin irrigation districts adopt these for precision scheduling under time-of-use tariff structures.
- Electric:Standard induction motor drives serve cost-sensitive applications with steady-state flow requirements.
- Thermal:Specialized designs handle high-temperature heat transfer fluids in industrial process applications.
Electric technology holds volume dominance; Smart Pumping climbs fastest as building automation integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta anchors the densest concentration of vertical inline pump manufacturing and municipal procurement activity worldwide. Provincial water conservancy bureaus across China are expanding inter-basin transfer capacities connecting agricultural hinterlands to coastal manufacturing zones. This infrastructure buildout is reshaping competitive positioning across Asia-Pacific supply chains.
United States
Texas and California chemical processing clusters specify availability guarantees rather than equipment ownership, transferring operational risk to OEM service organizations. EPA Clean Water Act standards and ISO 5198 test protocols shape minimum hydraulic efficiency requirements for municipal systems. Houston's petrochemical corridor drives demand for smart pumping configurations in process cooling loops.
China
Provincial water conservancy bureaus are deploying high-pressure inline pumps across inter-basin transfer projects connecting agricultural hinterlands to coastal manufacturing zones. MEE water quality regulations and GB/T 5657 efficiency standards tighten discharge head and power consumption thresholds for domestic equipment. The Pearl River Delta manufacturing belt concentrates production capacity for export-oriented pump assemblies.
Germany
Frankfurt's data center cooling operators specify integrated variable frequency drive packages for demand-responsive thermal load management. EU F-Gas Regulation phase-down elevates pump efficiency requirements for low-global-warming-potential chiller retrofits. The Rhine-Main metropolitan region serves as the primary specification hub for European HVAC retrofit projects.
India
Smart metering integration with pressurized distribution networks creates demand for digitally native inline pump skids in secondary cities under AMRUT 2.0 urban water missions. BIS efficiency standards and state-level electricity regulatory commissions impose performance floors on municipal procurement. Gujarat's groundwater extraction projects deploy submersible configurations where bore depths exceed 200 meters.
Australia
Time-of-use electricity tariffs in the Murray-Darling Basin are driving variable-speed pump adoption for precision irrigation scheduling. The country's national water regulator imposes efficiency disclosure requirements on agricultural equipment imports. Queensland's sugar cane processing districts concentrate seasonal demand for rapid-startup pump configurations.
Vertical Inline Pumps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with smart-pumping architectures commanding disproportionate returns. The vendor base stratifies into three tiers: vertically integrated multinationals with captive motor production, specialized pump fabricators sourcing controls externally, and regional assemblers competing on first-cost. Dominant competitive moves include strategic partnerships with building automation providers and geographic expansion through joint-venture production in Chinese free-trade zones.
Within the integrated-systems tier, Flowserve leverages its aftermarket service network to anchor long-term contracts with North American water utilities. Pentair competes on energy-efficient motor designs that meet escalating efficiency thresholds for commercial HVAC retrofits. Xylem occupies a position exemplifying the digital-native archetype, with embedded IoT diagnostics reducing unplanned downtime for industrial process cooling loops.
| Leading Market Players |
|---|
| Flowserve |
| Pentair |
| Xylem |
| Wilo |
| Ebara |
| Sulzer |
| KSB |
| Ruhrpumpen |
| Grundfos |
| Others |
Value Network & Pricing Analysis
Neodymium magnet costs cascade from Chinese refining operations through permanent magnet synchronous motor production, compressing margins for OEMs lacking captive rare earth supply while amplifying pricing power for vertically integrated manufacturers serving EPA-mandated municipal retrofits.
Pricing Analysis
Availability-based contracting anchors value capture for premium smart-pumping configurations, with Texas and California chemical processors paying for guaranteed uptime rather than equipment ownership. Three-tier pricing structure across premium smart-pumping, standard VFD-equipped, and economy induction motor tiers reflects certification grade differentiation under ISO 5198 and GB/T 5657 protocols. Cost compression in the economy tier intensifies as Chinese domestic manufacturers expand inter-basin transfer project participation. Agricultural buyers in Australia's Murray-Darling Basin exhibit highest price sensitivity, while data center operators in Singapore and Frankfurt prioritize efficiency performance over capital outlay.
Supply Chain Analysis
Container freight rate volatility from Shanghai to Rotterdam and Long Beach directly impacts landed costs for European and North American project deliveries, forcing OEMs to regionalize assembly footprints. Manufacturing gravity centers on China's Yangtze River Delta, Germany's Rhine-Main region, and India's Gujarat industrial corridor. Permanent magnet motors draw from neodymium processing concentrated in Chinese Inner Mongolia and Jiangxi provinces, while copper winding supply hinges on Chilean and Peruvian mining output. Single-source vulnerability in rare earth refining exposes margin predictability to export quota shifts. Distribution runs through authorized distributor networks for municipal procurement, direct OEM engagement for industrial facilities, and agricultural equipment dealers for irrigation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-pumping technology convergence is compressing mid-tier supplier viability, with ISO 5198 certification timelines and firmware integration complexity forcing consolidation among non-integrated fabricators.
For Market Incumbents: Deploy predictive maintenance service contracts to lock in municipal utility relationships before EPA replacement deadlines peak. Backward integration into permanent magnet motor production defends margin structures against neodymium cost volatility. Capture building automation system certification partnerships with Siemens, Honeywell, and Johnson Controls to erect switching costs for industrial facility customers.
For New Entrants and Emerging Players: Capture secondary city water infrastructure under India's AMRUT 2.0 missions where smart metering integration creates specification openings for digitally native pump skids. Target Australia's Murray-Darling Basin irrigation districts with load-shifting variable-speed configurations under time-of-use tariff structures. Lead with commissioning technician training programs to overcome skilled labor scarcity that incumbents struggle to address.
For Investors and Strategic Acquirers: Joint-venture announcements in Chinese free-trade zones are the leading indicator that export market access is being secured for premium smart-pumping architectures. Five-to-ten year viability favors OEMs with captive motor production and installed base service density. Monitor EPA enforcement patterns on Clean Water Act efficiency mandates as the signal for North American replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture in Chinese Free-Trade Zone | Accelerates GB/T 5657 conformity assessment for imported smart-pumping equipment. |
| Permanent Magnet Motor Integration | Captures efficiency gains in 1.5-22 kW range for data center cooling specifications. |
| Predictive Maintenance Platform Launch | Transfers operational risk from Texas chemical processors to OEM service organizations. |
| Building Automation System Certification | Enables seamless pump control integration with Siemens, Honeywell, and Johnson Controls protocols. |
| Commissioning Technician Training Program | Addresses skilled labor scarcity that constrains close-coupled assembly deployment. |
Research Methodology
Trade association publications, customs import records, and equipment registration databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary fieldwork encompassed interviews with municipal water utility procurement directors, chemical plant maintenance managers, HVAC retrofit contractors, and agricultural irrigation cooperative technical officers. Bottom-up triangulation across product-level shipment data and top-down validation against national infrastructure expenditure reports ensured cross-verified volume estimates.
Historical trendline analysis of municipal capital expenditure patterns and industrial facility energy efficiency investment cycles established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, application, end-user procurement sophistication, and technology integration depth dimensions. CAGRs were derived from regression analysis of replacement cycle timing, regulatory mandate phase-in schedules, and electricity tariff structure evolution. Forecast inputs included EPA enforcement intensity projections and China's MEE water quality regulation revision timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export policy shifts and building automation protocol standardization battles. Forecasts reflect documented assumptions regarding infrastructure funding continuity and regulatory enforcement cadence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Air Compressor Controller Market