
 Global Heavy Duty Pumps Market | 2026-2036
Global Heavy Duty Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heavy Duty Pumps Market Intelligence
A scarcity of technicians skilled in IIoT integration and predictive maintenance analytics is bifurcating the competitive landscape. The Weir Group PLC leverages its deep domain expertise in mining applications to offer integrated solutions. Meanwhile, Xylem Inc. differentiates through its portfolio of smart water technologies and digital services. Grundfos Holding A/S sustains its market position through extensive R&D in energy-efficient pump systems.
Heavy duty pumps are engineered systems designed for continuous operation under high-pressure, high-volume, or abrasive fluid conditions. These pumps often feature robust materials like cast iron or stainless steel and are built to handle slurries, corrosive chemicals, or large solids without failure. Centrifugal pumps dominate the product landscape due to their versatility, while submersible pumps are critical for dewatering in mining and construction. The oil & gas and mining end-user segments represent the largest sources of revenue, driven by fluid transfer and wastewater treatment applications.
Product design and market access are governed by a complex web of industrial standards and safety regulations. Compliance with API standards is non-negotiable in the oil & gas sector, while the EU's ATEX directives dictate pump specifications for hazardous environments. ISO 9906 standards for rotodynamic pump performance testing provide a baseline for quality assurance across geographies. Vendor selection will increasingly hinge on the ability to demonstrate total cost of ownership savings and compliance with evolving energy efficiency mandates.
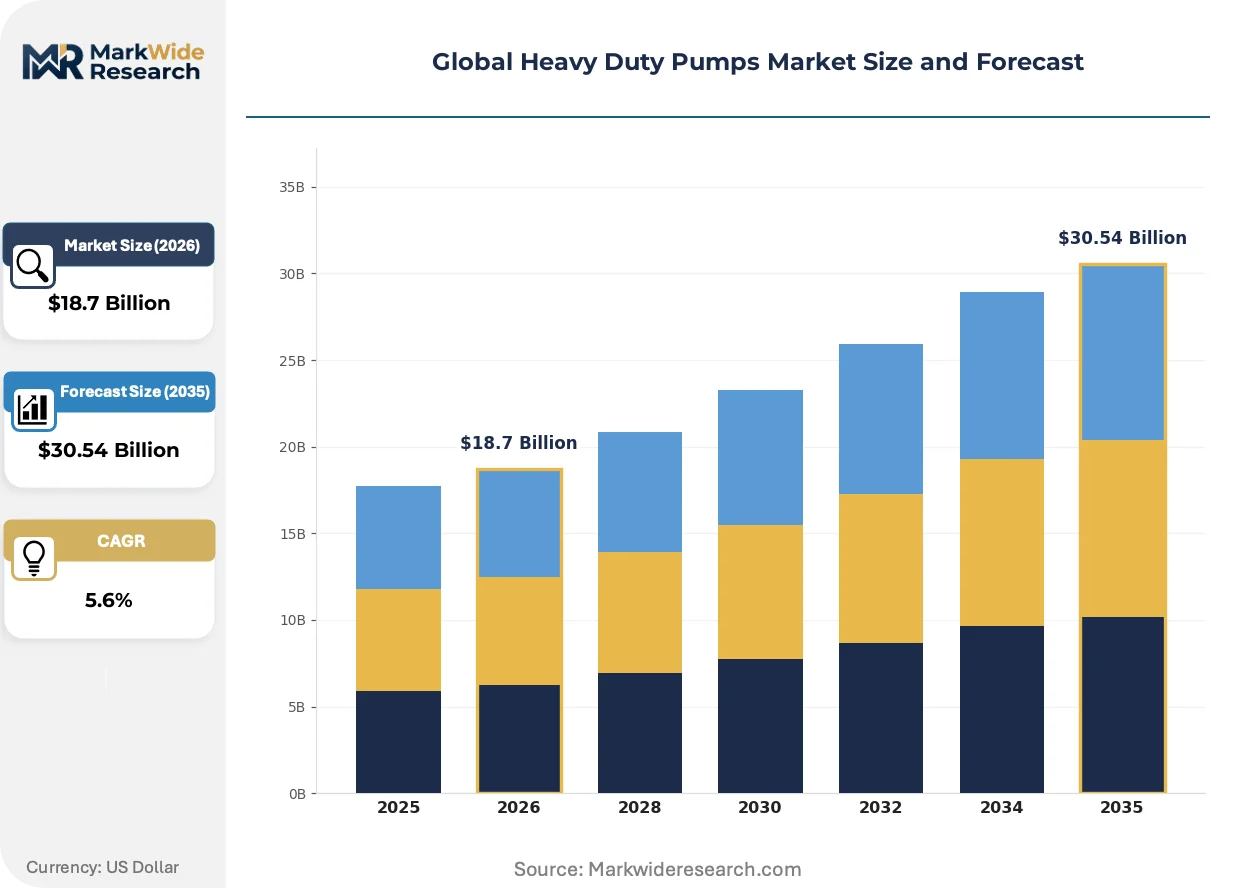
Market Dynamics
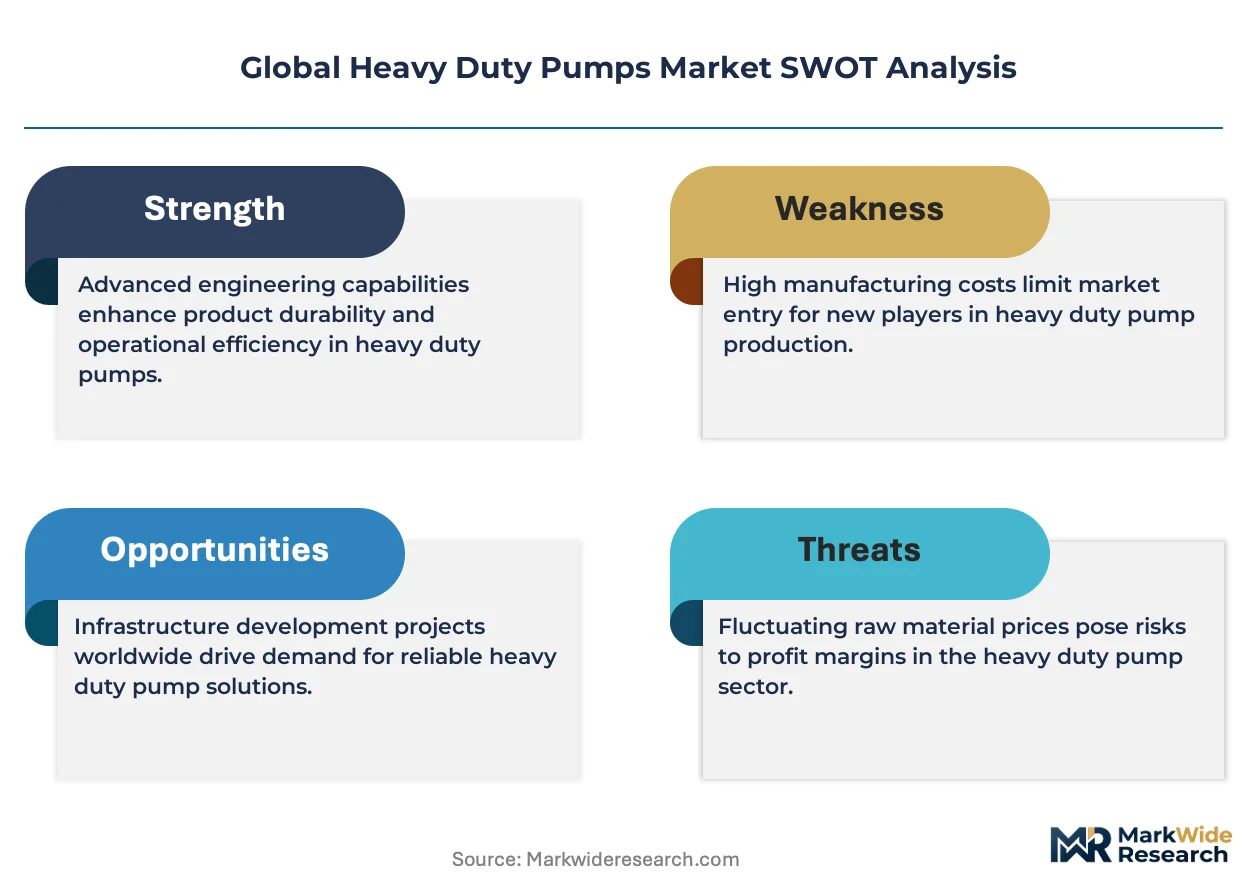
The market's trajectory is fundamentally shaped by the dual pressures of intensified resource extraction and tightening environmental regulations. This creates a demand for pumps that are not only durable enough for abrasive materials in mining and oil and gas, but also highly efficient and compliant with evolving wastewater discharge and emissions standards.
Growth Catalysts
- Wastewater Regulation:Stricter mandates, including the EU's Industrial Emissions Directive and EPA standards in the United States, compel industrial operators to invest in advanced pumps for compliant water treatment and effluent handling systems.
- Mining Sector Expansion:Sustained investment in mineral extraction, particularly in resource-rich nations like Australia and Chile, drives consistent demand for robust dewatering and slurry transport pumps capable of continuous operation in harsh environments.
- Material Science Advances:The development of superior corrosion-resistant alloys and composite materials enables the production of pumps with longer operational lifespans in aggressive chemical processing and desalination applications, expanding their utility.
Market Restraints
- Input Cost Volatility:The price of essential raw materials, such as nickel, chromium, and molybdenum used in high-grade stainless steel and specialty alloys, is subject to significant market fluctuations, complicating cost structures and margin stability.
- High Energy Consumption:Many legacy heavy duty pump installations are inherently energy-intensive, creating a structural conflict with corporate and national energy efficiency goals, which can delay large-scale replacement cycles due to high initial costs.
- Specialized Casting Supply:The global supply of foundries capable of producing the large, high-integrity castings required for the largest pump casings and impellers is highly concentrated, creating potential supply chain bottlenecks and long lead times.
Strategic Opportunities
- Emerging Energy Applications:The build-out of infrastructure for carbon capture, utilization, and storage (CCUS) and green hydrogen production presents a significant opportunity for specialized, high-pressure pumps designed for CO2 and fluid hydrogen transport.
- Digital Service Models:Integrating IIoT sensors for predictive maintenance allows manufacturers to offer outcome-based contracts and pump-as-a-service models, creating recurring revenue streams that are less dependent on capital equipment sales cycles.
- Water Scarcity Initiatives:Government-backed projects focused on large-scale water recycling and desalination, especially in the Middle East and North Africa, open new geographic markets for high-capacity, corrosion-resistant pump systems.
Industry Challenges
- Skilled Technician Shortage:A deficit of technicians with dual expertise in mechanical pump engineering and digital IIoT integration hinders the effective deployment and servicing of smart pump systems, limiting the realization of their full value.
- Legacy System Integration:Connecting new, intelligent pump systems with older, existing plant control infrastructures like distributed control systems (DCS) often requires extensive and costly custom engineering work, slowing adoption.
- Hazardous Environment Certification:Obtaining and maintaining certifications for explosive atmospheres, such as ATEX in Europe and its North American equivalents, is a time-consuming and expensive process that can act as a barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heavy Duty Pumps Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.54 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Diaphragm Pumps, Gear Pumps End User: Mining, Construction, Oil & Gas, Water Utilities Application: Wastewater Treatment, Fluid Transfer, Chemical Handling, Fire Protection Technology: Electric, Hydraulic, Pneumatic, Mechanical |
| Companies Covered | Grundfos Holding A/S, The Weir Group PLC, Flowserve Corporation, Ebara Corporation, Xylem Inc., Sulzer Ltd., ITT Inc., Ingersoll Rand Inc., KSB SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heavy Duty Pumps Market Strategic Shifts & Innovations
A fundamental transition from evaluating pumps as standalone mechanical assets to viewing them as integrated, data-rich systems is underway. This shift prioritizes operational intelligence, energy efficiency, and total cost of ownership over simple hydraulic performance, forcing innovation in both product design and service delivery.
Onboard sensor packages, which integrate vibration, temperature, and flow sensors, deliver real-time operational data directly from the pump. The chemical processing and oil and gas sectors are adopting these instrumented systems to enhance asset monitoring in critical process applications. This integration of micro-electro-mechanical systems (MEMS) into the pump assembly is miniaturizing the external diagnostic equipment, consolidating monitoring functions into the core asset itself.
The European Union's Ecodesign Directive imposes progressively stricter minimum efficiency requirements for both water pumps and their associated electric motors. This regulation forces manufacturers to engineer products with advanced hydraulic designs and to promote the use of variable speed drives (VSDs). The industrial wastewater treatment segment is particularly impacted, as operators must retrofit or replace entire pump installations to achieve compliance.
End-user evaluation criteria, especially in capital-intensive sectors like power generation and mining, are evolving beyond initial purchase price. A focus on total cost of ownership (TCO) that quantifies energy consumption, maintenance requirements, and expected operational lifespan is becoming standard. This behavioral change is most apparent in North America and Europe, where high energy costs and stringent reliability standards influence procurement decisions.
Global Heavy Duty Pumps Market Segmentation
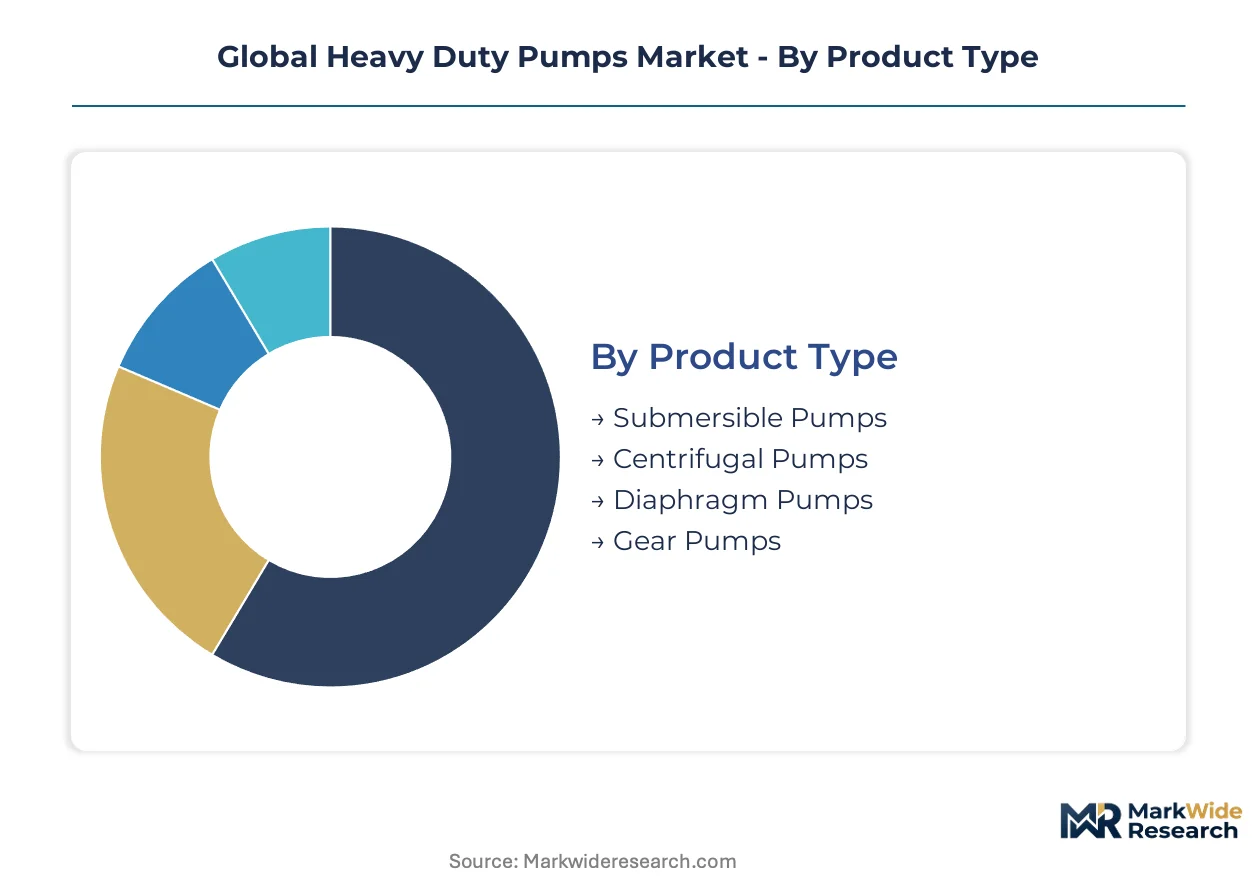
The heavy duty pumps market segmentation provides a granular understanding of the diverse product offerings and their specialized applications across various industrial sectors. This detailed breakdown highlights how design specifications and operational characteristics align with specific end-user requirements and regulatory compliance standards.
Product Type:
Product type differentiation in heavy duty pumps is often dictated by specific industrial standards and environmental safety regulations governing their design and operational parameters.
- Centrifugal Pumps:Centrifugal pumps utilize a rotating impeller to move fluid through a volute casing, converting rotational energy into kinetic energy. Their versatility and high flow rates make them foundational in global fluid transfer operations, particularly in industrial water supply and processing plants.
- Submersible Pumps:Submersible pumps feature a hermetically sealed motor directly coupled to the pump body, allowing for full immersion in the fluid being pumped. Demand is critical in mining dewatering and construction site drainage across resource-rich regions like Australia and Chile.
- Diaphragm Pumps:Diaphragm pumps use a reciprocating diaphragm to displace fluid, suitable for abrasive slurries and corrosive chemicals in chemical processing.
- Gear Pumps:Gear pumps employ meshing gears to transfer viscous fluids with high precision, commonly found in lubrication systems and chemical dosing.
Established volume favors Centrifugal Pumps; emerging adoption favors Diaphragm Pumps for specialized chemical handling.
End User:
End-user segments define specific operational demands and procurement criteria for heavy duty pump systems.
- Mining:Mining operations require robust pumps for dewatering, slurry transport, and tailings management, enduring highly abrasive and corrosive conditions. Sustained investment in mineral extraction, particularly in Australia and Chile, drives significant demand for these durable systems.
- Oil & Gas:The oil & gas sector utilizes heavy duty pumps for drilling fluid circulation, crude oil transfer, and wastewater injection, often under extreme pressure and temperature. Compliance with API standards is non-negotiable for these critical applications in the North Sea and the Permian Basin.
- Construction:Construction sites deploy heavy duty pumps for dewatering excavations, concrete pumping, and general fluid transfer, requiring portable and reliable solutions.
- Water Utilities:Water utilities rely on these pumps for municipal water supply, wastewater collection, and treatment, emphasizing energy efficiency and long operational lifespans.
The mining sector holds significant revenue share, while water utilities are gaining share fastest due to infrastructure upgrades.
Application:
Specific applications dictate the hydraulic performance and material specifications required for heavy duty pump installations.
- Wastewater Treatment:Wastewater treatment applications demand pumps capable of handling corrosive effluents and solids, often under continuous operation. Stricter mandates, such as the EU's Industrial Emissions Directive, compel operators to invest in advanced, compliant pumping systems.
- Fluid Transfer:Fluid transfer encompasses a broad range of operations moving liquids, slurries, or gases across industrial processes and infrastructure networks. This application forms the backbone of many mining and oil & gas operations, requiring high-volume and high-pressure capabilities.
- Chemical Handling:Chemical handling applications require pumps made from specialized corrosion-resistant alloys for safe and precise movement of hazardous substances.
- Fire Protection:Fire protection systems utilize heavy duty pumps to provide reliable high-pressure water flow for sprinklers and hydrants in commercial and industrial buildings.
Wastewater treatment applications are driving demand for highly efficient and compliant pump solutions.
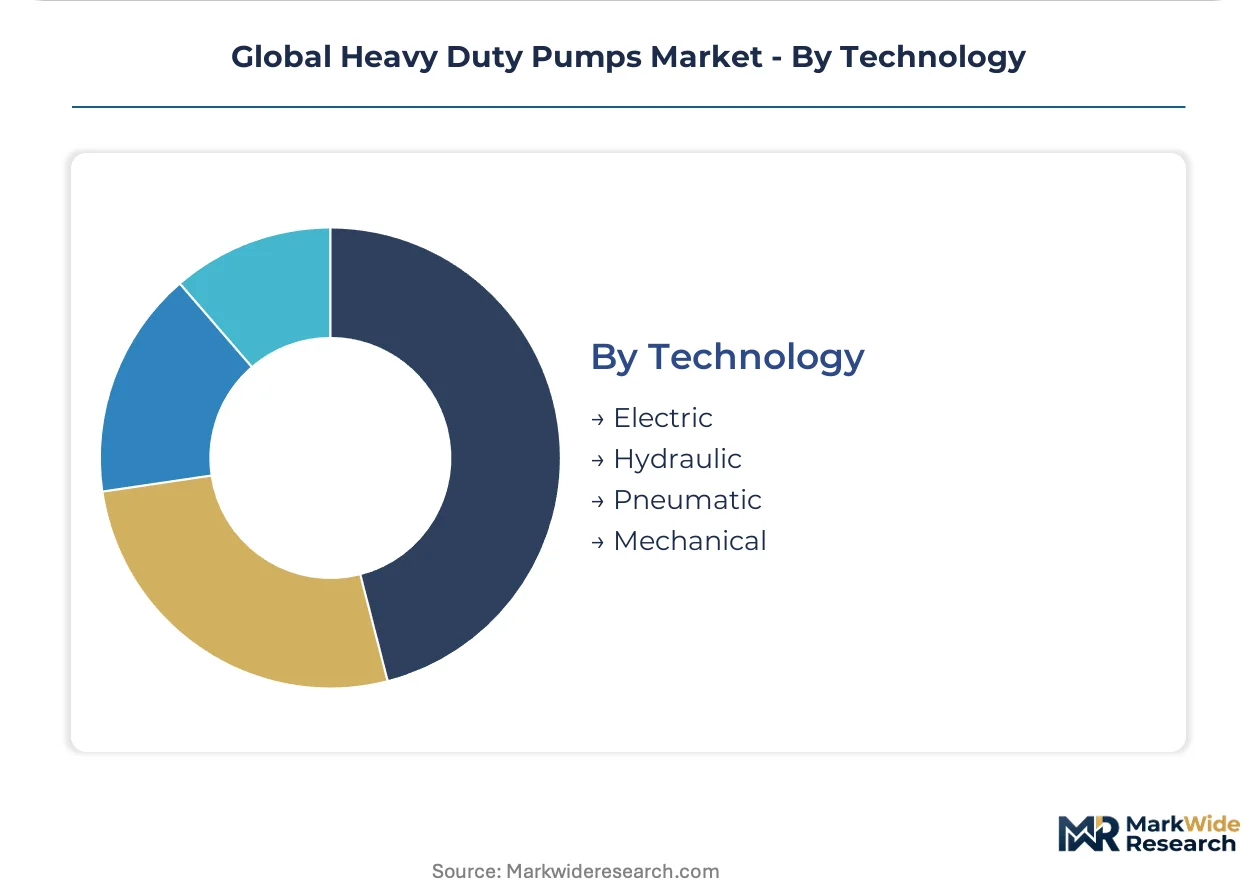
Technology:
Technological advancements influence pump efficiency, control, and suitability for diverse operational environments.
- Electric:Electric pumps are powered by electric motors, offering precise control and integration with variable speed drives for energy efficiency. The European Union's Ecodesign Directive is forcing manufacturers to optimize electric pump systems for minimum efficiency requirements.
- Hydraulic:Hydraulic pumps convert mechanical energy into hydraulic energy, generating high pressure and force for heavy lifting and robust power transmission. These systems are critical in construction equipment and offshore oil & gas platforms, where high power density is essential.
- Pneumatic:Pneumatic pumps operate using compressed air, providing intrinsically safe solutions for hazardous or explosive environments where electrical ignition is a concern.
- Mechanical:Mechanical pumps rely on direct mechanical power input, often through internal combustion engines, for applications requiring independence from electrical grids like remote mining sites.
Electric pump technologies are experiencing significant innovation driven by energy efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global demand for heavy duty pumps exhibits distinct regional consumption patterns, driven by varying industrial priorities. Some geographies prioritize robust solutions for mineral extraction, while others focus on stringent wastewater compliance or the build-out of new energy infrastructure. This diverse consumption mix shapes regional market dynamics and investment priorities for advanced fluid handling systems.
United States
The United States market for heavy duty pumps is driven by infrastructure upgrades in water utilities and sustained activity in the Permian Basin's oil and gas sector. EPA standards for wastewater discharge compel industrial operators to invest in compliant pumping solutions. Major manufacturing clusters in the Midwest and Gulf Coast regions continue to adopt advanced pump systems for process efficiency.
Germany
Germany's heavy duty pump demand is shaped by its advanced manufacturing sector and stringent environmental regulations. The EU's Ecodesign Directive mandates high energy efficiency for pump systems, pushing innovation. Industrial hubs like North Rhine-Westphalia and Bavaria are key centers for both pump manufacturing and high-tech industrial applications.
Australia
Australia represents a significant market for heavy duty pumps, primarily due to its extensive mining operations, particularly for iron ore and coal. The country's environmental protection regulations, such as those governing mine dewatering, require robust and efficient pump systems. Western Australia's Pilbara region and Queensland's Bowen Basin are major demand centers for slurry and dewatering pumps.
Chile
Chile's market for heavy duty pumps is dominated by its copper mining industry, which requires specialized pumps for slurry transport and high-volume dewatering. Strict national environmental guidelines for water management in arid regions influence pump selection. The Antofagasta and Tarapacá regions, home to large copper mines, drive consistent demand for durable fluid handling equipment.
Saudi Arabia
Saudi Arabia's market is propelled by significant investments in its oil and gas sector and large-scale desalination projects. Government initiatives for water security and industrial expansion necessitate high-capacity, corrosion-resistant pump systems. Industrial cities such as Jubail and Yanbu are major end-users for heavy duty pumps in chemical processing and water infrastructure.
Global Heavy Duty Pumps Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the heavy duty pumps market. These market participants often differentiate through deep domain expertise, advanced technological portfolios, or a focus on specific end-user applications. Dominant competitive moves include strategic partnerships for IIoT integration and continuous investment in research and development for energy-efficient solutions.
Integrated solution providers such as The Weir Group PLC and Xylem Inc. exemplify this tiered structure, offering comprehensive product lines and digital services. Grundfos Holding A/S also occupies a significant position, anchoring its market presence through extensive R&D in energy-efficient pump systems. These companies represent different strategic archetypes, from mining-focused expertise to smart water technology leadership, shaping the competitive dynamics across global regions.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| The Weir Group PLC |
| Flowserve Corporation |
| Ebara Corporation |
| Xylem Inc. |
| Sulzer Ltd. |
| ITT Inc. |
| Ingersoll Rand Inc. |
| KSB SE & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Superior corrosion-resistant alloys are reshaping the heavy duty pump market by concentrating specialized material production in fewer geographies. This dynamic enables premium pricing based on extended operational lifespans and reduced maintenance.
Pricing Analysis
Project-based contracts often define heavy duty pump pricing, especially for large infrastructure or mining developments. Price differentiation stems from adherence to API standards and the level of customization for abrasive or corrosive applications. Pricing softness reflects high energy consumption of legacy systems and the need for significant initial investment. Capital-intensive sectors like mining prioritize total cost of ownership, making them less sensitive to upfront costs than smaller construction projects.
Supply Chain Analysis
Port congestion and rising container costs impact the inbound flow of specialized raw materials for heavy duty pumps. Supply concentrates in countries with advanced metallurgy like Germany and Japan, alongside China for specialized castings. The market relies on high-grade stainless steel and specialty alloys, creating single-source vulnerability for large, high-integrity components. Distribution runs through direct sales channels for major projects and specialized industrial distributors for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy duty pumps market is positioned for early-cycle expansion, driven by the increasing penetration of IIoT integration and predictive maintenance solutions. This shift elevates operational intelligence and total cost of ownership as primary evaluation criteria.
For Market Incumbents: Compound deep domain expertise in mining applications with strategic partnerships for IIoT integration to counter emerging digital service providers. Invest in R&D for advanced hydraulic designs and energy-efficient systems to meet EU Ecodesign Directive mandates. Leverage existing channel control and API/ATEX certification investments to maintain market share against new entrants. Address the skilled technician shortage by internal training programs focused on IIoT analytics.
For New Entrants and Emerging Players: Digital service model gaps present an opportunity for new entrants to offer outcome-based contracts and pump-as-a-service solutions. Target specialized, high-pressure pumps for emerging energy applications like carbon capture and green hydrogen production. Focus on industrial wastewater treatment, where operators require compliant, efficient solutions. Penetrate markets like the Middle East with advanced desalination pump systems.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-forward specialists with deep application expertise. Long-term viability is strong, anchored by persistent demand from resource extraction and tightening environmental regulations over the next 5-10 years. Target vertically integrated mid-cap companies demonstrating strong IIoT integration and predictive maintenance offerings. Watch for increasing enterprise adoption of outcome-based contracts as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Energy-Efficient Systems | Addresses EU Ecodesign Directive, reducing operational costs for industrial wastewater treatment. |
| IIoT Integration Partnerships | Enhances predictive maintenance capabilities, creating new recurring revenue streams for manufacturers. |
| Specialized Material Development | Extends pump lifespan in abrasive mining conditions, improving total cost of ownership. |
| Geographic Expansion into MENA | Captures demand from large-scale desalination projects in water-scarce regions. |
| Digital Service Model Rollout | Shifts revenue from capital equipment sales to outcome-based contracts for end-users. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with plant engineers, procurement leads, maintenance directors, and R&D specialists. This primary research was triangulated with extensive secondary validation from industry association reports, government environmental agency data, and company annual filings. A bottom-up and top-down approach ensured comprehensive market sizing and segment validation.
The forecasting horizon spans the analysis window, utilizing a robust analytical framework to project market evolution. Segmentation dimensions modeled include Product Type, End User, Application, Technology, and regional economic development. Compound Annual Growth Rates were derived from historical data analysis and projected future trends. Key industry-specific inputs included raw material price trends and industrial investment cycles.
Forecasts assume regulatory continuity in key regimes like the EU Ecodesign Directive and US EPA standards; material policy shifts would require re-modeling. Geopolitical instability or unforeseen technological disruptions represent significant risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Latin America Hydraulic Filtration Market
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Droplet Separator Market