
 Industrial Gas Turbine Sales Market | 2026-2036
Industrial Gas Turbine Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gas Turbine Sales Market Insights
The aftermarket service channel is fragmenting as OEMs and independent providers compete for long-term maintenance contracts. GE Vernova leverages its digital monitoring platform to lock in predictive service agreements across installed fleets. Siemens Energy anchors European demand through its hydrogen-ready turbine roadmap. Mitsubishi Power competes on high-temperature alloy expertise for advanced-class units.
Industrial gas turbine sales involve the commercial transfer of combustion turbines rated typically from one megawatt to over four hundred megawatts, employing axial compressors, annular combustors, and multi-stage turbines to convert fuel energy into rotational mechanical power for electricity generation or mechanical drive. Heavy duty turbines dominate baseload power plant deployments due to their durability and scale economics, while aeroderivative units lead in oil and gas applications where rapid startup and mobility matter. Combined cycle technology captures the fastest expansion as operators prioritize efficiency gains from waste heat recovery systems.
The EPA enforces nitrogen oxides limits under the Clean Air Act, compelling turbine manufacturers to deploy dry low-emission combustors or face permitting restrictions. The EU F-Gas Regulation and REACH framework restrict fluorinated greenhouse gases and hazardous substances in turbine cooling and sealing systems, raising compliance costs for suppliers accessing European projects. Stakeholders must monitor hydrogen blending mandates and carbon border adjustments as these mechanisms reshape turbine specification requirements and geographic sourcing decisions.
Market Dynamics
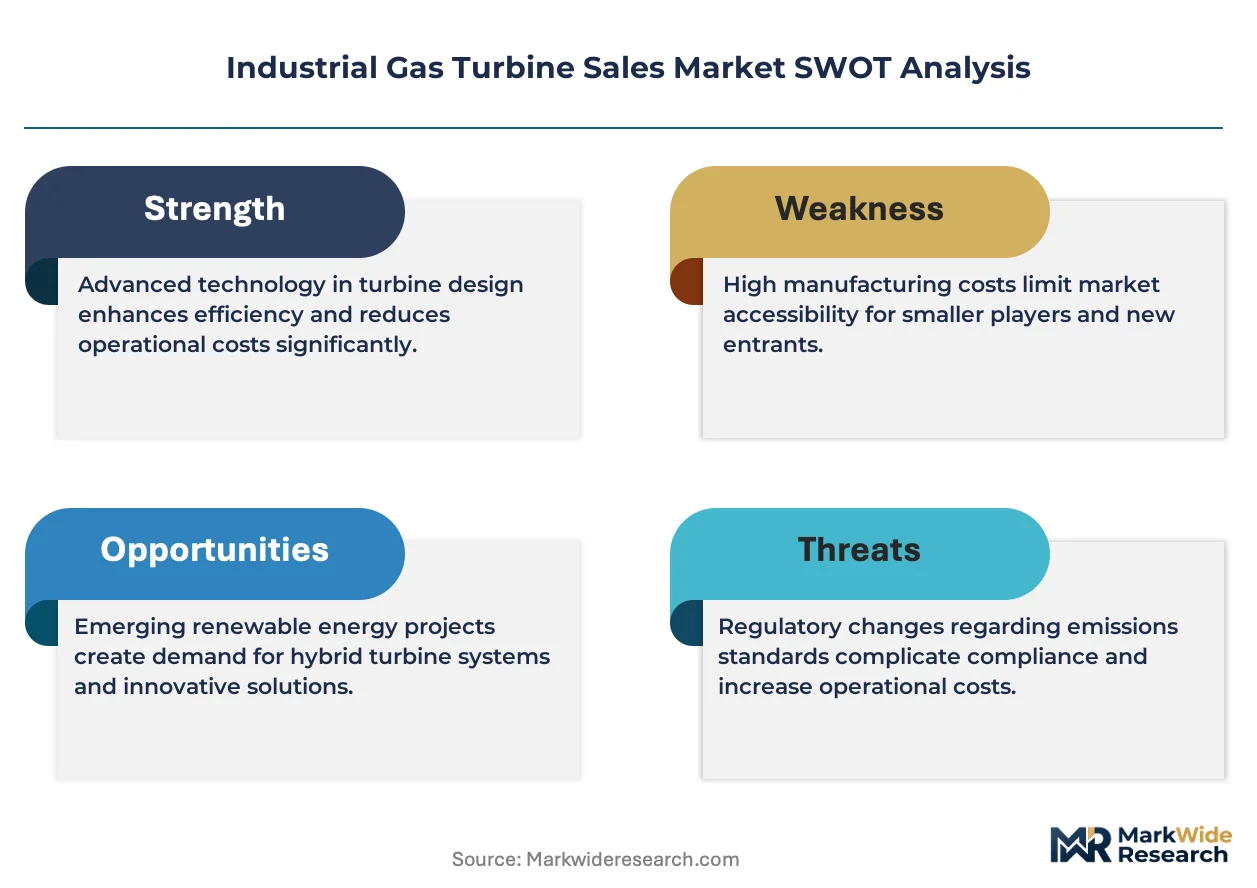
The industrial gas turbine market is undergoing a fundamental reconfiguration as hydrogen blending mandates force original equipment manufacturers to redesign combustion architectures. These specifications are reshaping procurement criteria across power generation utilities and oil and gas operators.
Growth Catalysts
- EPA Clean Air Act enforcement:Nitrogen oxides limits under Title I compel utilities to replace aging coal-fired baseload capacity with combined-cycle gas turbine installations. Permitting restrictions on legacy fossil assets accelerate retirement timelines.
- Saudi Arabia combined-cycle expansion:The kingdom's utility procurement program targets substantial efficiency gains through waste heat recovery systems. State-backed power developers anchor regional demand for heavy-duty frame units.
- Dry low-emission combustor technology:Advanced premixed combustion systems enable sub-25 ppm NOx operation without water injection. This hardware satisfies stringent air quality standards in urbanized deployment zones.
Market Restraints
- Specialized alloy supply concentration:Single-source dependence for directionally solidified turbine blades creates vulnerability in high-temperature component supply chains. Foundry capacity constraints in select supplier geographies extend lead times.
- Hydrogen infrastructure gap:Pipeline distribution networks and storage facilities for fuel-grade hydrogen remain underdeveloped in most industrial clusters. Turbine readiness exceeds fuel availability.
- EU F-Gas Regulation compliance costs:Restrictions on fluorinated greenhouse gases in sealing and cooling systems force material substitutions. Reformulation expenses compress margins for European project bids.
Strategic Opportunities
- India grid stabilization demand:Rapid renewable energy integration creates need for fast-ramping aeroderivative units. Grid operators seek turbines capable of sub-ten-minute startup to balance solar and wind intermittency.
- Carbon border adjustment mechanisms:EU CBAM incentivizes low-carbon power generation equipment procurement. Export-oriented industrial facilities prioritize turbines with verified lifecycle emissions profiles.
- Digital twin convergence with predictive maintenance:Physics-based modeling integrated with sensor analytics enables condition-based overhaul scheduling. This fusion reduces unplanned outage frequency for fleet operators.
Industry Challenges
- Combustion engineering talent scarcity:Specialized expertise in flame dynamics and fuel flexibility remains concentrated among retiring workforce cohorts. Universities produce insufficient graduates with relevant thermofluids training.
- Extended type certification timelines:Novel hydrogen-capable turbine variants require multi-year validation protocols with aviation-derived safety regulators. Test facility bottlenecks delay commercial entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gas Turbine Sales Market |
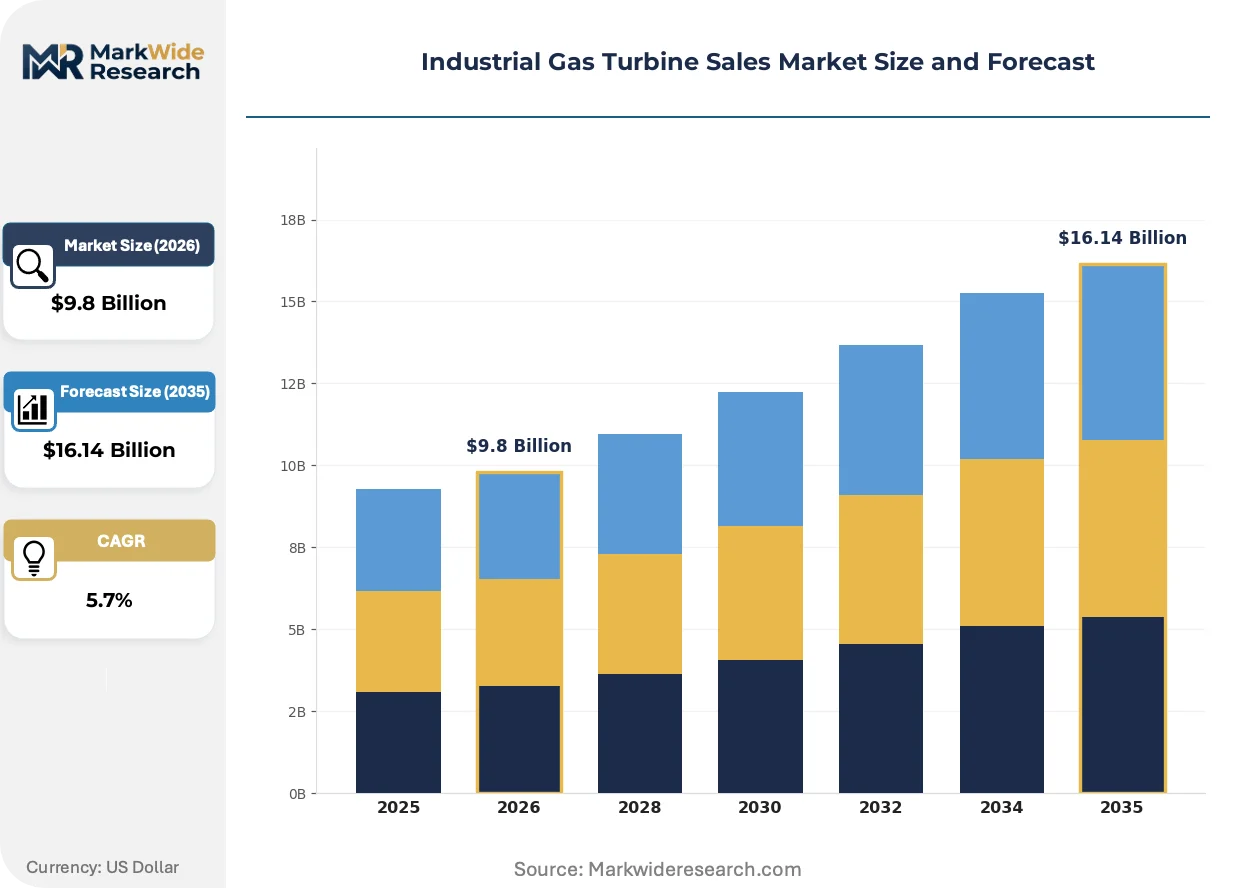
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Duty, Aeroderivative, Baseline, Package End User: Power Generation, Oil & Gas, Marine, Aerospace Technology: Combined Cycle, Simple Cycle, Cogeneration, Hybrid Installation: Onshore, Offshore, Containerized, Fixed Site |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Power, Ansaldo Energia, Solar Turbines, Kawasaki Heavy Industries, Doosan Enerbility, Bharat Heavy Electricals, MAN Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gas Turbine Sales Market Trends and Innovations
Combustion system architectures are converging with hydrogen fuel pathways and digital monitoring platforms. These parallel developments are compressing traditional equipment lifecycles while opening new service revenue streams.
Annular combustor designs with staged fuel injection are hybridizing natural gas and hydrogen combustion within single hardware configurations. Power utilities in Germany and the Netherlands are piloting these systems at 30% hydrogen volume fractions. The technology is hybridizing procurement specifications, forcing suppliers to guarantee fuel flexibility across blended operating envelopes rather than optimize for single-fuel performance.
REACH framework amendments are restricting chromium-based coatings in hot gas path components. European turbine operators face accelerated replacement schedules for legacy blade and vane inventories. The regulation most affects mid-life fleet upgrades, where operators must choose between coating stripping and component replacement.
Long-term service agreements are fragmenting into modular, performance-guaranteed contracts. Independent maintenance providers in Texas and Alberta are capturing rotor overhaul work previously captive to original equipment manufacturers. This unbundling is most pronounced in oil and gas mechanical drive applications, where operators prioritize uptime guarantees over brand-aligned service relationships.
Industrial Gas Turbine Sales Market Segmentation
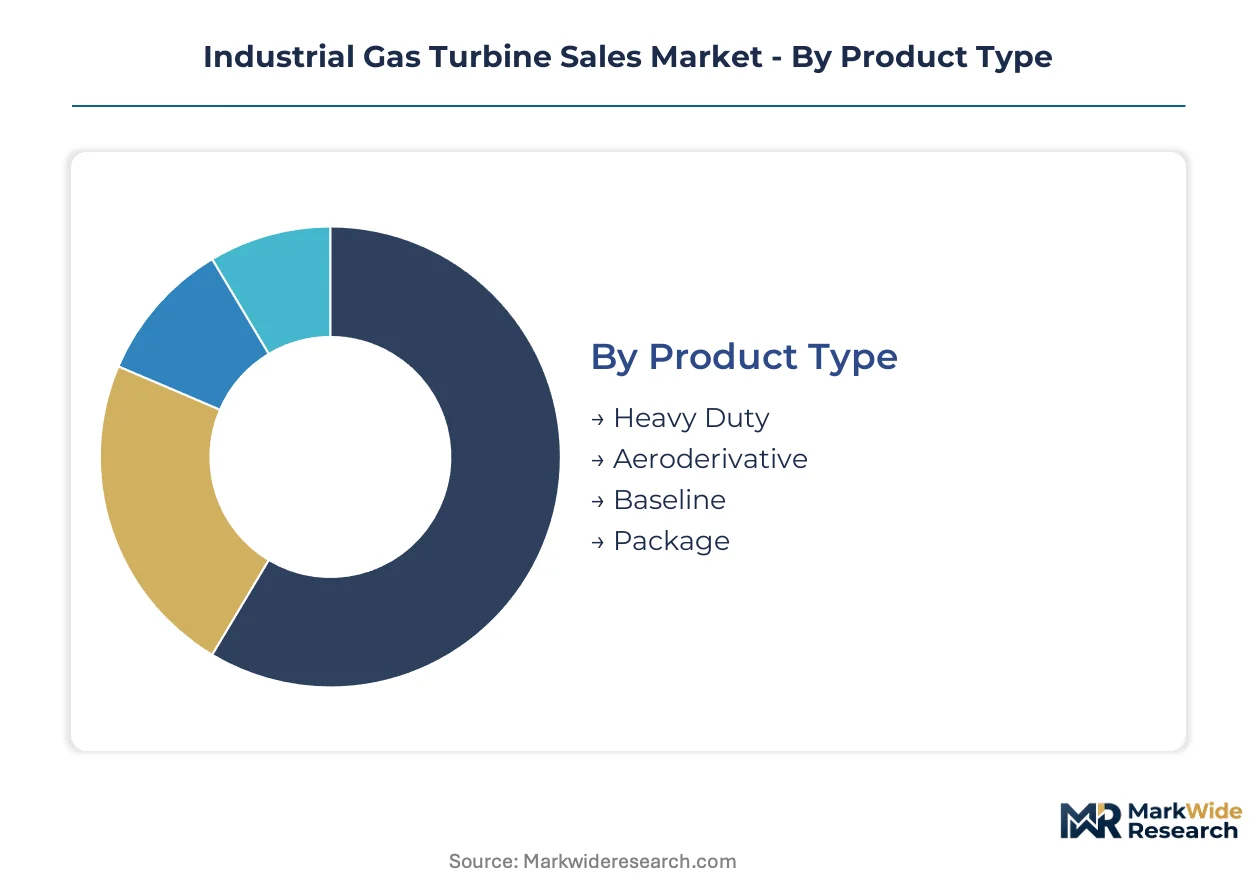
Industrial gas turbine procurement patterns diverge sharply across product architectures and deployment contexts. Equipment specifications, maintenance cycles, and fuel flexibility requirements create distinct commercial segments with uneven replacement velocities and margin structures.
Product Type:
Heavy duty units operate on decade-long replacement cycles, while aeroderivative fleets turn over faster due to higher utilization intensity in mechanical drive applications.
- Heavy Duty:These frame turbines employ annular combustors and multi-stage axial compressors rated above 100 megawatts for baseload power generation. Saudi Arabia's state-backed developers anchor procurement for combined-cycle plants requiring 25-year operational lifespans. The segment commands premium pricing for efficiency guarantees above 60% in combined-cycle configuration.
- Aeroderivative:Aviation-derivative turbines leverage lightweight turbine disks and rapid-start thermal profiles for oil and gas mechanical drive. Permian Basin operators in Texas prioritize sub-ten-minute startup capability to capture spot electricity pricing volatility. The hardware sacrifices peak efficiency for operational flexibility and transportability.
- Baseline:Entry-level turbines serve captive industrial power needs with standardized combustion architectures and limited fuel flexibility.
- Package:Pre-integrated turbine-generator sets reduce field installation timelines for remote deployment zones with constrained construction labor.
Heavy duty turbines dominate installed base. Aeroderivative units are where expansion concentrates.
End User:
Power generation utilities concentrate procurement volume, while oil and gas operators prioritize uptime-guaranteed service contracts over capital efficiency.
- Power Generation:Electric utilities deploy combined-cycle configurations to replace retiring coal capacity under EPA Clean Air Act enforcement. Chinese provincial grid operators anchor regional procurement for 400-megawatt-class frame units with hydrogen blending readiness.
- Oil & Gas:Upstream and midstream operators specify aeroderivative turbines for gas compression and mechanical drive. North Sea platform operators demand offshore-certified packages with redundant fuel systems.
- Marine:Naval and commercial vessel propulsion requires compact turbine footprints with shock-resistant mounting configurations.
- Aerospace:Ground-based test facilities and auxiliary power units represent niche demand with specialized certification requirements.
Power generation commands capital deployment scale. Oil and gas generates the densest service contract attach rates.
Technology:
Combined cycle systems extract margin through waste heat recovery, while simple cycle installations prioritize capital discipline in peaking applications.
- Combined Cycle:Heat recovery steam generators capture exhaust thermal energy to drive secondary turbine stages. German utilities pilot 30% hydrogen blending in these configurations to satisfy EU carbon border adjustment exposure.
- Simple Cycle:Single-shaft turbines optimize for minimal capital outlay and rapid deployment in grid stabilization roles. Indian grid operators specify these for renewable balancing duty with sub-ten-minute ramp rates.
- Cogeneration:Combined heat and power configurations serve industrial clusters with simultaneous steam and electricity demand.
- Hybrid:Battery-turbine integrated systems buffer renewable intermittency with synthetic inertia services.
Combined cycle dominates new-build efficiency specifications. Simple cycle is climbing the fastest in renewable-balancing deployments.
Installation:
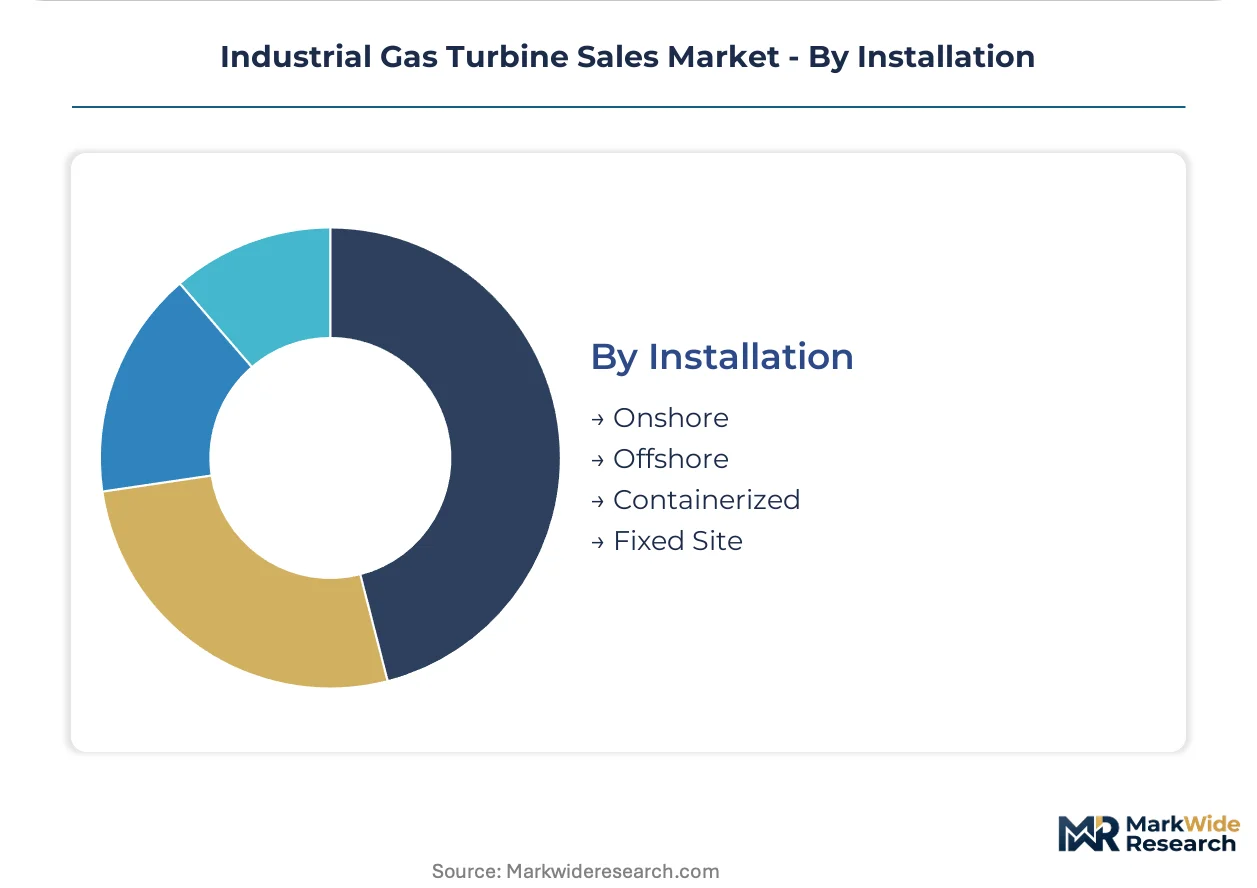
Onshore deployments concentrate manufacturing scale, while offshore and containerized formats command specialized engineering premiums.
- Onshore:Fixed foundation installations at utility-scale power plants anchor procurement volume with standardized civil works and grid interconnection protocols. Chinese and Saudi Arabian project pipelines concentrate demand for heavy-duty frame units in this configuration.
- Offshore:Platform-mounted turbines require marine-grade corrosion protection and compact modular packaging. North Sea and Gulf of Mexico developments specify these for space-constrained production facilities.
- Containerized:Skid-mounted turbine packages enable rapid redeployment across dispersed oil field locations.
- Fixed Site:Permanent industrial installations with dedicated fuel supply infrastructure serve captive power needs.
Onshore installations dominate unit volume. Offshore formats capture the steepest expansion trajectory in remote hydrocarbon development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for hydrogen-ready turbines command wider spreads in Germany than in Saudi Arabia, where state procurement compresses vendor margins through volume concentration. This asymmetry shapes divergent competitive strategies across procurement markets.
United States
EPA Clean Air Act enforcement accelerates combined-cycle deployments to replace retiring coal baseload in the Ohio River Valley and Texas. FERC interconnection queue reforms aim to compress permitting timelines for utility-scale gas plants. The Permian Basin anchors aeroderivative demand from oilfield operators seeking rapid-start flexibility.
Germany
EU F-Gas Regulation compliance costs and hydrogen blending mandates reshape turbine specifications for RWE and Uniper fleet renewals. The EU Green Deal carbon border adjustment mechanism incentivizes low-carbon equipment procurement. The Ruhr industrial cluster pilots 30% hydrogen volume combustion in combined-cycle configurations.
China
Provincial grid operators in Guangdong and Jiangsu procure 400-megawatt-class frame units with hydrogen readiness for coastal power corridors. MEE emissions standards tighten NOx limits in the Yangtze River Delta manufacturing belt. The Pearl River Delta concentrates domestic turbine assembly capacity with state-backed technology transfer programs.
Saudi Arabia
State-backed power developers anchor regional demand for heavy-duty frame units through the kingdom's combined-cycle expansion program. The national renewable energy initiative integrates gas turbines for grid stabilization alongside solar capacity. The Eastern Province industrial cities concentrate petrochemical-driven mechanical drive applications.
India
Rapid renewable integration in Gujarat and Rajasthan creates demand for fast-ramping aeroderivative units to balance solar intermittency. CEA grid codes mandate sub-ten-minute startup capability for new gas capacity. The Mumbai-Pune industrial corridor deploys cogeneration turbines for captive power in manufacturing clusters.
Industrial Gas Turbine Sales Market Competitive Landscape
Integrated energy conglomerates and specialized turbine OEMs split the market along technology depth versus portfolio breadth lines. The vendor base concentrates around three strategic archetypes: full-lifecycle service integrators, high-temperature materials specialists, and regional fabrication champions. Dominant competitive moves include hydrogen combustion technology licensing and predictive maintenance platform unbundling.
Among the full-lifecycle integrators, GE Vernova, Siemens Energy, and Mitsubishi Power occupy distinct competitive positions. GE Vernova exemplifies the digital service lock-in archetype through its monitoring platform deployments. Siemens Energy anchors European positioning through hydrogen-ready technology roadmaps. Mitsubishi Power represents the high-temperature alloy specialization vector for advanced-class frame units.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Power |
| Ansaldo Energia |
| Solar Turbines |
| Kawasaki Heavy Industries |
| Doosan Enerbility |
| Bharat Heavy Electricals |
| MAN Energy Solutions |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity in precision casting for directionally solidified turbine blades compresses supplier margins while inflating configured-to-order premiums for heavy-duty frame units. This utilization squeeze forces OEMs to prioritize long-term service contract pricing over equipment margins, reshaping how procurement teams negotiate total cost of ownership.
Pricing Analysis
Configured-to-order premiums for hydrogen-ready combustion systems command spreads of 15-25% above standard natural gas configurations, reflecting engineering validation costs and fuel-flexibility guarantees. Price differentiation hinges on certification grade for EU F-Gas Regulation compliance and volume scale in Saudi state-backed procurement programs. Cost compression in baseline aeroderivative units is intensifying because independent maintenance providers are unbundling service revenues previously captive to OEMs. Oil and gas mechanical drive operators demonstrate lowest price sensitivity, prioritizing uptime guarantees over capital efficiency; Indian grid operators show highest sensitivity, optimizing for sub-ten-minute startup capability at minimal capital outlay.
Supply Chain Analysis
Upstream feedstock for high-temperature superalloys draws from nickel ore processing in Indonesia, cobalt refining in the Democratic Republic of Congo, and precision casting capacity in the United States and Japan. Directionally solidified turbine blades and thermal barrier coatings represent critical component dependencies with limited qualified suppliers. Single-source vulnerability in foundry capacity for advanced-class frame units creates extended lead time exposure during demand surges. Distribution runs through original equipment manufacturer direct sales for utility-scale projects and specialized EPC contractors for oil and gas mechanical drive deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against battery storage and renewable peaking technologies that threaten simple-cycle gas turbine economics in grid balancing roles. Incumbents must restructure commercial models before fuel-flexibility premiums erode.
For Market Incumbents: Insulate installed base revenues through predictive maintenance platform lock-in and hydrogen combustion technology licensing to regional fabricators. Anchor vertical integration into precision casting capacity to reduce single-source vulnerability for directionally solidified components. Prioritize certification investment for EU F-Gas Regulation compliance to defend European project access against emerging Asian competitors.
For New Entrants and Emerging Players: Build out aeroderivative aftermarket service capabilities in the Permian Basin and Alberta oil fields where independent providers are capturing rotor overhaul work from incumbents. Target India's fast-ramping grid stabilization segment where CEA mandates create procurement pull for sub-ten-minute startup hardware. Pursue joint venture structures with domestic fabricators in China and Saudi Arabia to bypass capital barriers in heavy-duty frame manufacturing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital service platform operators with predictive maintenance attach rates above 60% of installed base. Long-term viability favors acquisition targets with hydrogen-ready technology roadmaps and established utility relationships in combined-cycle expansion markets. Monitor EU carbon border adjustment implementation as the signal to watch for inflection in low-carbon equipment procurement premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Combustion Technology Licensing | Enables fuel-flexibility premiums in EU and Chinese procurement specifications. |
| Predictive Maintenance Platform Deployment | Locks in long-term service agreements across utility and oil and gas fleets. |
| Precision Casting Capacity Expansion | Reduces single-source vulnerability for directionally solidified turbine blades. |
| Aeroderivative Aftermarket Service Buildout | Captures unbundled rotor overhaul work in North American oil and gas basins. |
| EU F-Gas Regulation Compliance Certification | Secures project access as REACH amendments restrict chromium-based coatings. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads; and secondary validation through EIA capacity data, IEA power generation reports, FERC interconnection filings, and project development databases. Bottom-up unit economics for heavy-duty and aeroderivative segments were triangulated against top-down market sizing from equipment shipment tracking and regional procurement announcements.
Forecast inputs considered hydrogen blending mandate trajectories, EPA Clean Air Act enforcement timelines, and renewable integration rates across the analysis window. Segmentation dimensions modeled include product architecture, end-use application, technology configuration, and regional regulatory framework. CAGRs were derived from regression analysis of historical equipment shipments against announced project pipelines, with scenario weighting for carbon border adjustment implementation and foundry capacity expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery storage developers or hydrogen electrolyzer manufacturers would shift outcomes for simple-cycle peaking applications. Cross-checking against IEA power sector investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Submarine Power Cable Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Power Analyzers Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Thailand Power EPC Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Wind Turbine Equipment Market