
 Regenerative Turbine Pump Market | 2026-2036
Regenerative Turbine Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Turbine Pump Market Analysis
The EPA's Clean Water Act enforcement is restructuring capital planning across municipal and industrial water infrastructure. ITT leverages its vertical integration in precision casting to sustain price competitiveness in stainless steel pump configurations. Crane Pumps & Systems anchors its position through specialized distribution networks serving North American water treatment utilities. TEIKOKU Electric Mfg. Co dominates Asian manufacturing scale for multistage regenerative turbine designs.
A regenerative turbine pump employs a rotating impeller with multiple vanes that recirculate fluid through a toroidal channel, generating high heads at low flow rates with hydraulic efficiencies typically ranging from 40% to 65%. This mechanism serves boiler feed, pressure boosting, and condensate return applications where centrifugal pumps cannot achieve sufficient discharge pressure. Stainless steel material configurations command premium positioning due to corrosion resistance requirements in chemical processing and desalination environments, while cast iron variants occupy cost-sensitive HVAC and agricultural irrigation segments. Multistage architectures represent the fastest-growing product category as industrial users pursue higher pressure ratios without expanding footprint.
The EPA mandates NSF/ANSI 61 certification for potable water contact components, while the EU F-Gas Regulation pressures HVAC system designers toward leak-tight pump sealing technologies. ISO 5199 chemical pump standards govern international procurement specifications for oil and gas downstream applications. Stakeholders must monitor evolving PFAS remediation regulations, as emerging treatment protocols will redefine pump material compatibility requirements and open replacement demand across contaminated groundwater extraction systems.
Market Dynamics
Stainless steel regenerative turbine pumps are displacing cast iron configurations across high-pressure boiler feed systems as corrosion resistance requirements tighten under EPA effluent enforcement and desalination chemistry demands.
Growth Catalysts
- EPA Clean Water Act enforcement:Tightened industrial discharge standards are forcing facility upgrades across Texas and California petrochemical clusters, accelerating replacement cycles for corrosion-resistant pump configurations.
- Desalination chemistry requirements:High-salinity environments in Middle Eastern and Australian coastal projects are mandating duplex stainless steel impeller materials that withstand chloride attack.
- Multistage architecture adoption:Industrial users pursuing higher pressure ratios without footprint expansion are specifying stacked impeller designs for condensate return and pressure boosting duties.
Market Restraints
- Alloy cost volatility:Nickel and molybdenum price swings in stainless steel feedstock directly compress margin structures for precision-cast impeller manufacturers.
- Foundry concentration risk:Premium stainless steel casting capacity concentrates in German and Japanese supplier networks, creating vulnerability to regional energy cost spikes.
- Centrifugal pump substitution:Advancements in high-speed multistage centrifugal designs threaten regenerative turbine positioning in mid-pressure HVAC applications.
Strategic Opportunities
- PFAS remediation infrastructure:Emerging groundwater extraction protocols for contaminated sites in Michigan and North Carolina will open demand for chemically resistant pump materials.
- EU F-Gas Regulation compliance:Leak-tight sealing requirements for HVAC refrigerant systems create specification advantages for hermetic regenerative turbine configurations.
- Modular skidded systems:Packaged pump-and-control assemblies are expanding addressable market through reduced on-site installation complexity for municipal utilities.
Industry Challenges
- Precision casting skill scarcity:Toroidal channel machining and vane profile grinding require specialized metrology expertise that aging workforces in Midwest US manufacturing regions struggle to replenish.
- NSF/ANSI 61 certification timelines:Potable water contact component approvals stretch 18-24 months, delaying revenue recognition for municipal procurement bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Turbine Pump Market |
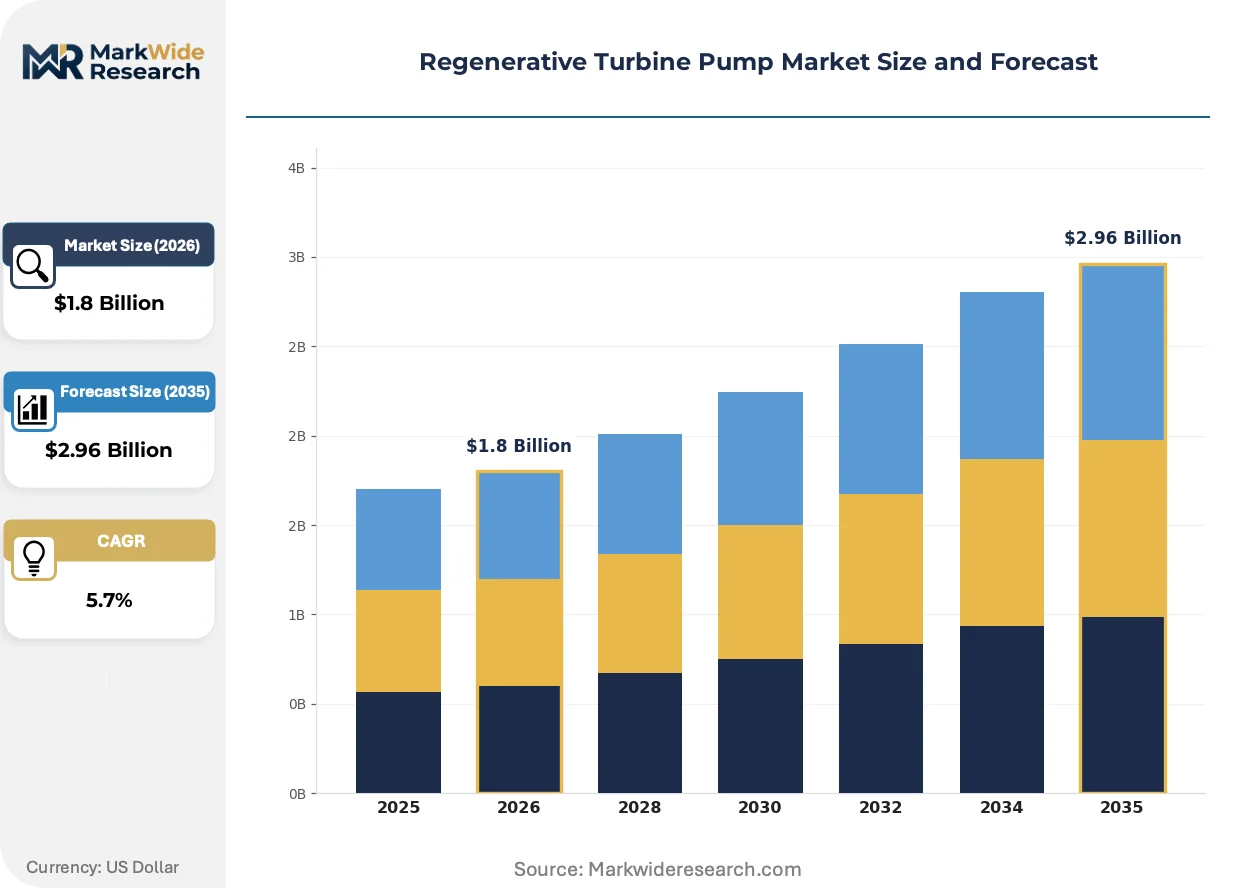
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Multistage, Single Stage Material: Stainless Steel, Cast Iron, Bronze, Plastic End User: Agriculture, Oil & Gas, Water Treatment, HVAC Application: Industrial Applications, Domestic Water Supply, Fire Protection, Irrigation |
| Companies Covered | ITT, Crane Pumps & Systems, TEIKOKU Electric Mfg. Co, Pentair, MTH Pumps, Xylem, Sulzer, Grundfos, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Turbine Pump Market Emerging Trajectories
Digital monitoring integration and materials science advances are compressing maintenance intervals while expanding duty envelopes for regenerative turbine architectures previously limited by mechanical seal life and cavitation thresholds.
Ceramic-coated stainless steel impellers are expanding into chemical processing and brine handling applications where abrasive particulate erosion previously limited service life. Dow Chemical and BASF downstream facilities in Louisiana and Texas are piloting these configurations for hydrochloric acid transfer duties. The technology is expanding into specification sheets for ISO 5199 chemical pump procurement categories.
The EU F-Gas Regulation is mandating hermetic pump sealing for HVAC refrigerant systems to prevent fluorinated gas leakage. This regulatory pressure is restructuring European supplier portfolios toward leak-tight regenerative turbine configurations. German and Italian HVAC OEMs are accelerating qualification programs for magnetic drive and canned motor variants.
Condition-based maintenance contracts are displacing time-based service agreements among North American water treatment utilities. Xylem and Grundfos service divisions are unbundling predictive analytics from hardware sales. Texas and California municipal procurement departments are piloting outcome-based contracts linking pump availability to payment terms.
Regenerative Turbine Pump Market Segmentation
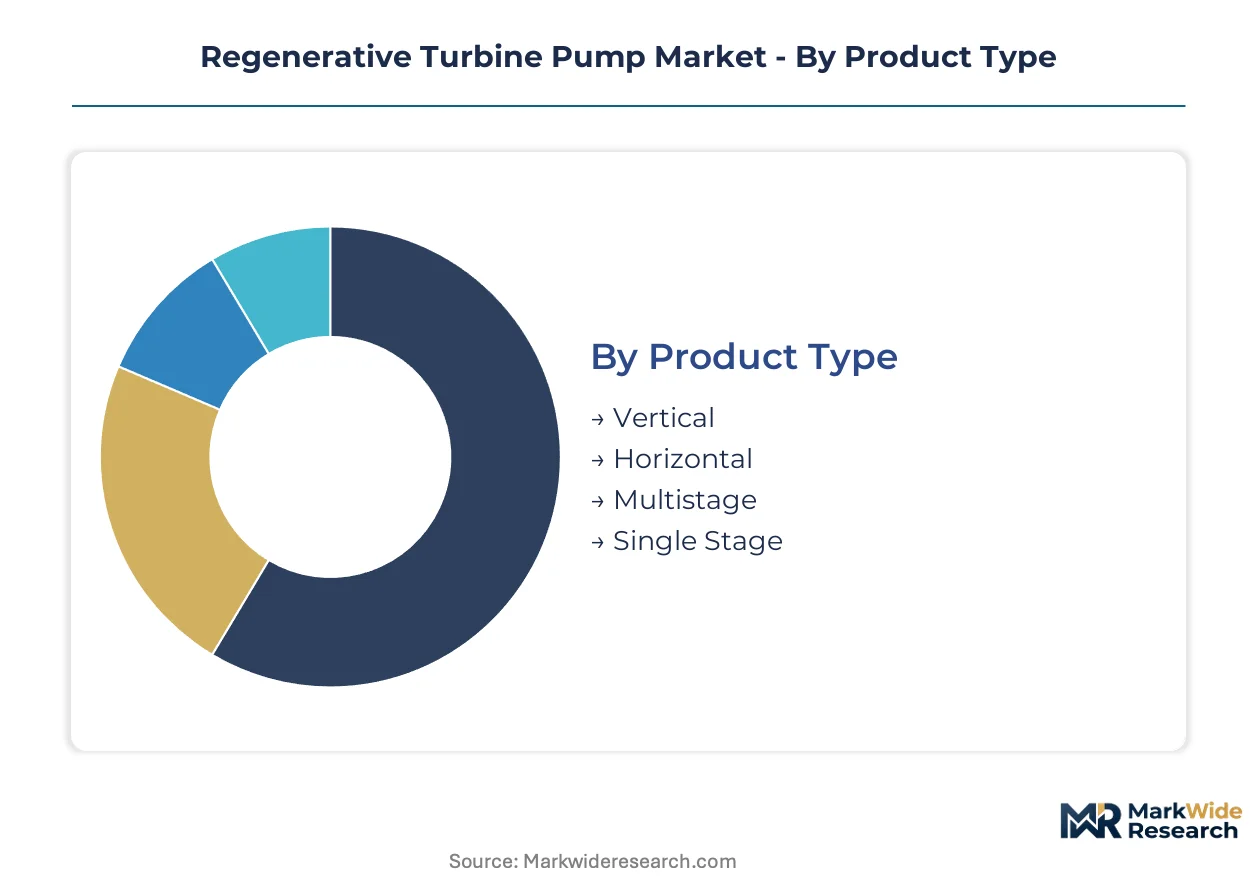
Regenerative turbine pump procurement hinges on pressure ratio requirements, fluid chemistry, and installation footprint constraints. Buyers trade initial capital outlay against corrosion resistance and multistage capability when specifying configurations for boiler feed and desalination duties.
Product Type:
Installation geometry and pressure staging requirements drive specification decisions across municipal, industrial, and commercial procurement channels.
- Vertical:Space-constrained installations in Texas and California petrochemical facilities favor vertical configurations that minimize footprint while accommodating high-head boiler feed requirements. EPA effluent enforcement accelerates replacement cycles in these clusters.
- Multistage:Stacked impeller architectures achieve pressure ratios exceeding single-stage limits without footprint expansion. Industrial users in desalination and condensate return applications specify these for high-pressure duties where centrifugal pumps fall short.
- Horizontal:Split-case horizontal designs simplify maintenance access for large-flow agricultural and HVAC installations.
- Single Stage:Compact single-impeller units serve low-pressure domestic water supply and light commercial pressure boosting.
Volume sits with Horizontal configurations; growth tilts toward Multistage.
Material:
Fluid chemistry and regulatory compliance tiers separate premium specifications from cost-sensitive procurement.
- Stainless Steel:Duplex and austenitic grades withstand chloride attack in Middle Eastern desalination projects and high-salinity Australian coastal installations. EPA Clean Water Act enforcement mandates these for industrial effluent handling in US petrochemical corridors.
- Cast Iron:Gray and ductile iron variants occupy price-sensitive HVAC and agricultural irrigation segments where corrosion exposure remains limited.
- Bronze:Naval bronze impellers serve marine and brackish water applications requiring galvanic compatibility.
- Plastic:Reinforced thermoplastic housings handle aggressive chemical transfer in specialty processing environments.
Cast Iron captures baseline volume; Stainless Steel climbs the fastest on desalination and EPA-driven replacement demand.
End User:
Operational intensity and regulatory exposure differentiate procurement patterns across sectoral buyers.
- Water Treatment:Municipal utilities and industrial effluent facilities specify NSF/ANSI 61 certified configurations for potable contact and high-pressure boiler feed. Texas and California procurement departments drive replacement cycles under tightened discharge standards.
- Oil & Gas:Downstream refineries and petrochemical complexes demand ISO 5199 compliant chemical pump specifications for hydrocarbon processing and condensate return.
- HVAC:Commercial building systems prioritize leak-tight hermetic sealing under EU F-Gas Regulation pressure.
- Agriculture:Cost-optimized cast iron units serve irrigation and drainage in volume-driven procurement.
Water Treatment holds installed base dominance; Oil & Gas shows steepest expansion trajectory on petrochemical cluster upgrades.
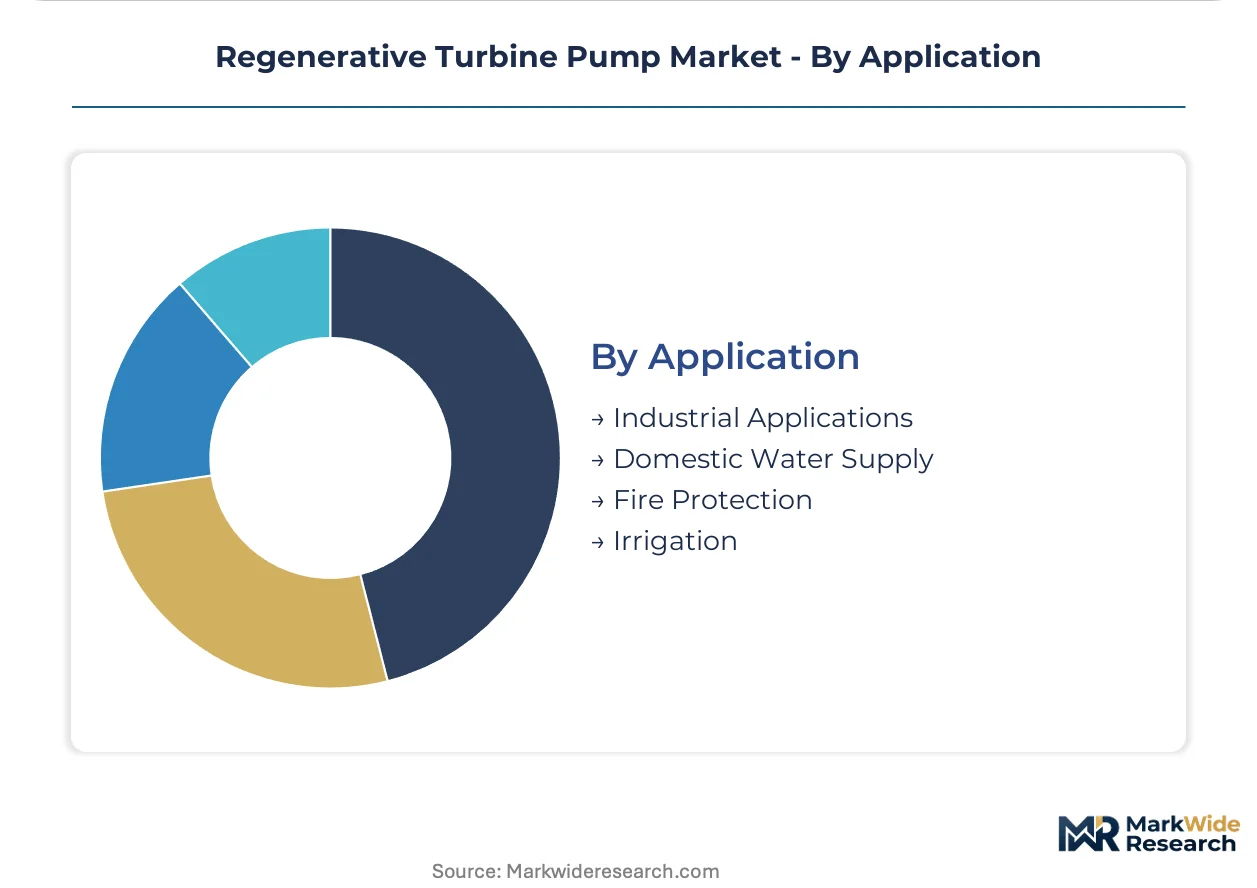
Application:
Duty cycle severity and safety criticality shape specification rigor across use cases.
- Industrial Applications:Continuous-duty boiler feed and chemical transfer operations mandate corrosion-resistant materials and precision-cast impeller geometries. Dow Chemical and BASF downstream facilities pilot ceramic-coated configurations for hydrochloric acid duties.
- Fire Protection:Listed configurations for high-pressure sprinkler systems require dedicated hydraulic performance certification.
- Domestic Water Supply:Pressure boosting for municipal distribution and building services emphasizes reliability and energy efficiency.
- Irrigation:Seasonal-duty pumps prioritize capital economy over extended service intervals.
Industrial Applications anchor revenue concentration; Fire Protection gains specification share on code compliance tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Saudi Arabia and China's coastal provinces are concentrating regenerative turbine pump demand through petrochemical cluster incentives and desalination infrastructure mandates.
United States
Texas and California petrochemical corridors drive replacement cycles under tightened EPA effluent standards. The Clean Water Act enforcement mandates NSF/ANSI 61 certified stainless steel configurations for high-pressure boiler feed systems. Houston-area refineries and Los Angeles basin desalination plants anchor procurement concentration.
Germany
Premium stainless steel casting capacity serves European chemical processing demand. The EU F-Gas Regulation pressures HVAC OEMs toward hermetic sealing qualifications. Ruhr Valley industrial clusters and Bavarian pump manufacturing districts sustain precision foundry networks.
China
Dual carbon goals accelerate boiler feed upgrades in coastal manufacturing zones. GB standards govern chemical pump specifications for downstream petrochemical facilities. Yangtze River Delta and Shandong Peninsula industrial clusters specify multistage architectures for condensate return duties.
Saudi Arabia
NEOM and Red Sea desalination megaprojects mandate duplex stainless steel for chloride resistance. The national water regulator enforces stringent material specifications for high-salinity environments. Eastern Province petrochemical cities and Jeddah coastal installations anchor procurement volume.
Japan
Metropolitan water utilities specify compact multistage designs for space-constrained pressure boosting. METI efficiency standards drive replacement of aging cast iron installations. Kanto and Kansai industrial corridors concentrate demand for precision-cast impeller configurations.
Regenerative Turbine Pump Market Vendor Landscape
German and Japanese producers anchor the premium casting tier; US and Chinese fabricators hold volume positions through standardized configurations. The vendor structure splits between consolidated multinationals with captive foundry capacity and specialized mid-tier players sourcing precision components. Three archetypes dominate: vertically integrated precision casters, hermetic sealing specialists, and modular skidded system packagers. Competitive moves concentrate on backward integration into stainless steel casting and geographic expansion through distribution partnerships.
Within the precision-casting tier, ITT and TEIKOKU Electric Mfg. Co occupy positions sustained by in-house impeller production capabilities. Crane Pumps & Systems represents the specialized distribution archetype serving North American water treatment procurement channels.
| Leading Market Players |
|---|
| ITT |
| Crane Pumps & Systems |
| TEIKOKU Electric Mfg. Co |
| Pentair |
| MTH Pumps |
| Xylem |
| Sulzer |
| Grundfos |
| Flowserve Corporation |
| Others |
Supply Flow & Price Mechanics
Stainless steel duplex grade certification separates premium procurement from commodity cast iron tenders, with this material bifurcation driving both 40-65% hydraulic efficiency premiums and captive foundry investments across German and Japanese supplier networks. EPA effluent mandates and NSF/ANSI 61 potable water certifications compress margin structures for precision-cast impeller manufacturers while rewarding backward integration into corrosion-resistant alloy production.
Pricing Analysis
Short lead-time premiums of 15-25% apply to NSF/ANSI 61 certified stainless steel configurations, while spot inventory of cast iron variants trades at contract discounts. Three-tier pricing structure across premium duplex grades, standard austenitic stainless, and economy cast iron segments reflects certification burden and raw material volatility. Nickel and molybdenum price swings compress margins in precision-cast impeller manufacturing. Municipal utilities in Texas and California exhibit lowest price sensitivity due to regulatory compliance deadlines; agricultural irrigation buyers in the Midwest drive hardest bargain on initial capital outlay.
Supply Chain Analysis
ISO 5199 and NSF/ANSI 61 qualification gates restrict supply base to German, Japanese, and select US foundries with precision casting capability. Duplex stainless steel feedstock draws from specialized alloy producers in Germany and Japan. Toroidal channel machining and vane profile grinding rest on aging metrology expertise concentrated in Ruhr Valley and Kansai industrial corridors. Single-source vulnerability concentrates in premium stainless steel casting capacity exposed to regional energy cost spikes. Distribution runs through specialized industrial pump distributors serving water treatment utilities and petrochemical OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The regenerative turbine pump market sits in a technology-transition phase as ceramic-coated impeller designs displace legacy configurations in hydrochloric acid and brine handling applications. This materials science shift restructures competitive positioning around coating qualification expertise rather than traditional casting scale.
For Market Incumbents: Extend hermetic sealing qualification programs to capture EU F-Gas Regulation-driven HVAC retrofit demand. Deepen backward integration into duplex stainless steel casting to defend margin position against nickel price volatility. Anchor channel control through outcome-based maintenance contracts linking pump availability to payment terms with Texas and California municipal utilities. For New Entrants and Emerging Players: Begin with modular skidded system packaging for PFAS remediation groundwater extraction sites in Michigan and North Carolina, where emerging treatment protocols outpace incumbent qualification timelines. Target desalination chemistry applications in Australian coastal projects as the most penetrable premium segment. Pursue magnetic drive and canned motor variant partnerships with German HVAC OEMs as primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with hermetic sealing specialists given EU F-Gas Regulation compliance deadlines accelerating specification shifts. Long-term viability favors captive foundry operators with ISO 5199 and NSF/ANSI 61 certification infrastructure across the 5-10 year projection horizon. Target acquisition archetype: mid-tier precision casters with toroidal channel machining expertise. Watch ceramic coating pilot results at Dow Chemical and BASF Louisiana facilities as inflection indicator for materials substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Duplex Stainless Steel Casting | Captive supply of corrosion-resistant impeller materials defends margins against nickel volatility in German and Japanese supplier networks. |
| Hermetic Sealing Qualification Program | EU F-Gas Regulation compliance creates specification lock-in for HVAC refrigerant system OEMs in German and Italian markets. |
| Ceramic Coating Technology Pilot | Dow Chemical and BASF downstream trials for hydrochloric acid transfer expand duty envelopes beyond traditional cavitation limits. |
| Modular Skidded System Packaging | Reduced on-site installation complexity opens municipal utility procurement channels previously dominated by full-service incumbents. |
| Outcome-Based Maintenance Contract | Texas and California water treatment pilots linking pump availability to payment terms unbundle predictive analytics from hardware sales. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this regenerative turbine pump market assessment. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and water treatment utility maintenance directors combined with EPA enforcement databases, ISO certification registries, and desalination project announcements. Bottom-up unit economics triangulated against top-down sectoral spending patterns across petrochemical, municipal water, and HVAC end-use segments.
Data-stream reconciliation across shipment volumes, installed base estimates, and replacement cycle analytics shaped the projection framework. Segmentation dimensions modeled include material grade tier, staging architecture, end-use industry, and regional regulatory cluster. CAGRs derived from regression analysis of historical replacement cycles against enforcement intensity and desalination capacity additions. Forecast inputs incorporated nickel price volatility assumptions and PFAS remediation infrastructure deployment timelines.
Underlying measurement precision varies by segment; stainless steel multistage configurations carry tighter precision than cast iron agricultural units due to concentrated supplier disclosure. Forecasts reflect assumptions around EPA enforcement continuity, EU F-Gas Regulation implementation pace, and ceramic coating technology adoption curves. A model refresh is warranted upon material change in nickel alloy pricing or PFAS remediation protocol finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Metering Pump Market