
 Hypertrophic and Keloid Scar Treatment Market | 2026-2036
Hypertrophic and Keloid Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hypertrophic and Keloid Scar Treatment Market Intelligence
Hospital procurement departments are losing relative influence as dermatology clinics is bifurcating demand toward outpatient laser and cryotherapy protocols. Smith & Nephew leverages its wound care infrastructure to dominate silicone gel distribution across acute care networks. Merz Pharmaceuticals anchors European prescription access through its botulinum toxin and pharmaceutical portfolio. Lumenis competes on laser platform breadth, sustaining installed-base loyalty with multi-modality systems.
Hypertrophic and keloid scar treatment encompasses pharmaceutical, device-based, and procedural interventions designed to modulate collagen deposition and reduce fibroproliferative tissue elevation. Silicone gel sheeting operates through occlusion and hydration mechanisms, typically requiring twelve to twenty-four hours of daily contact over two to four months to achieve clinically meaningful flattening. Laser therapy leads in revenue intensity due to capital equipment bundling and recurring consumable revenue, while combination approaches spanning topical agents with cryotherapy represent the fastest-growing treatment method as clinicians seek to reduce recurrence rates. Topical formulations remain the most mature segment, with margin pools shifting toward specialty clinics that can command cash-pay aesthetic premiums.
FDA 510(k) pathways and EU MDR technical documentation requirements are elevating clinical evidence burdens for laser and radiation devices, slowing market access for new entrants. Health Canada and the Therapeutic Goods Administration in Australia are harmonizing with these standards, creating a consolidated regulatory front across major developed markets. Stakeholders must monitor reimbursement coding splits between medically necessary scar revision and cosmetic indications, as these distinctions determine addressable patient volumes and pricing authority across every major geography.
Market Dynamics
Combination therapy protocols are restructuring competitive positioning across the scar treatment landscape. Dermatology clinics now capture disproportionate procedure volume as outpatient laser and cryotherapy bundling reduces hospital dependency.
Growth Catalysts
- FDA 510(k) pathway harmonization:Streamlined device clearances for laser platforms accelerate clinic adoption cycles. The pathway reduces time-to-market for fractional CO2 and pulsed-dye systems.
- Silicone gel sheeting hydration mechanisms:Twelve-to-twenty-four-hour daily occlusion protocols deliver measurable flattening outcomes. Patient compliance tools embedded in mobile applications improve adherence rates.
- South Korea reimbursement expansion:National health insurance now covers cryotherapy protocols for hypertrophic scarring. Seoul-based dermatology chains are scaling multi-modality service lines.
Market Restraints
- EU MDR technical documentation burdens:Active scar devices face reclassification with elevated clinical evidence requirements. Small device manufacturers lack resources for post-market surveillance systems.
- Laser platform capital intensity:Multi-modality systems require six-figure equipment investments plus annual service contracts. Independent clinics defer purchases during credit tightening cycles.
- Recurrence rate limitations:Monotherapy approaches fail in thirty to fifty percent of keloid cases. Patients cycle through multiple interventions before achieving durable outcomes.
Strategic Opportunities
- Germany outpatient clinic networks:Private dermatology chains in Munich and Hamburg are consolidating procurement for combination therapy suites. Cash-pay aesthetic premiums exceed reimbursed medical rates by threefold.
- Botulinum toxin-pharma convergence:Adjunctive use of neurotoxins for tension reduction during scar maturation opens prescription pathways. Formulation stability improvements enable topical delivery mechanisms.
- Telehealth pre-screening protocols:Remote scar assessment tools filter patient flow into appropriate intervention tiers. United States-based platforms are licensing algorithms to Australian clinic networks.
Industry Challenges
- Laser technician certification timelines:Multi-modality platform operation requires twelve to eighteen months of supervised training. Clinic operators face wage inflation for credentialed specialists.
- Silicone gel supply concentration:Three contract manufacturers control seventy percent of medical-grade sheeting output. Lead times extend to twenty weeks during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypertrophic and Keloid Scar Treatment Market |
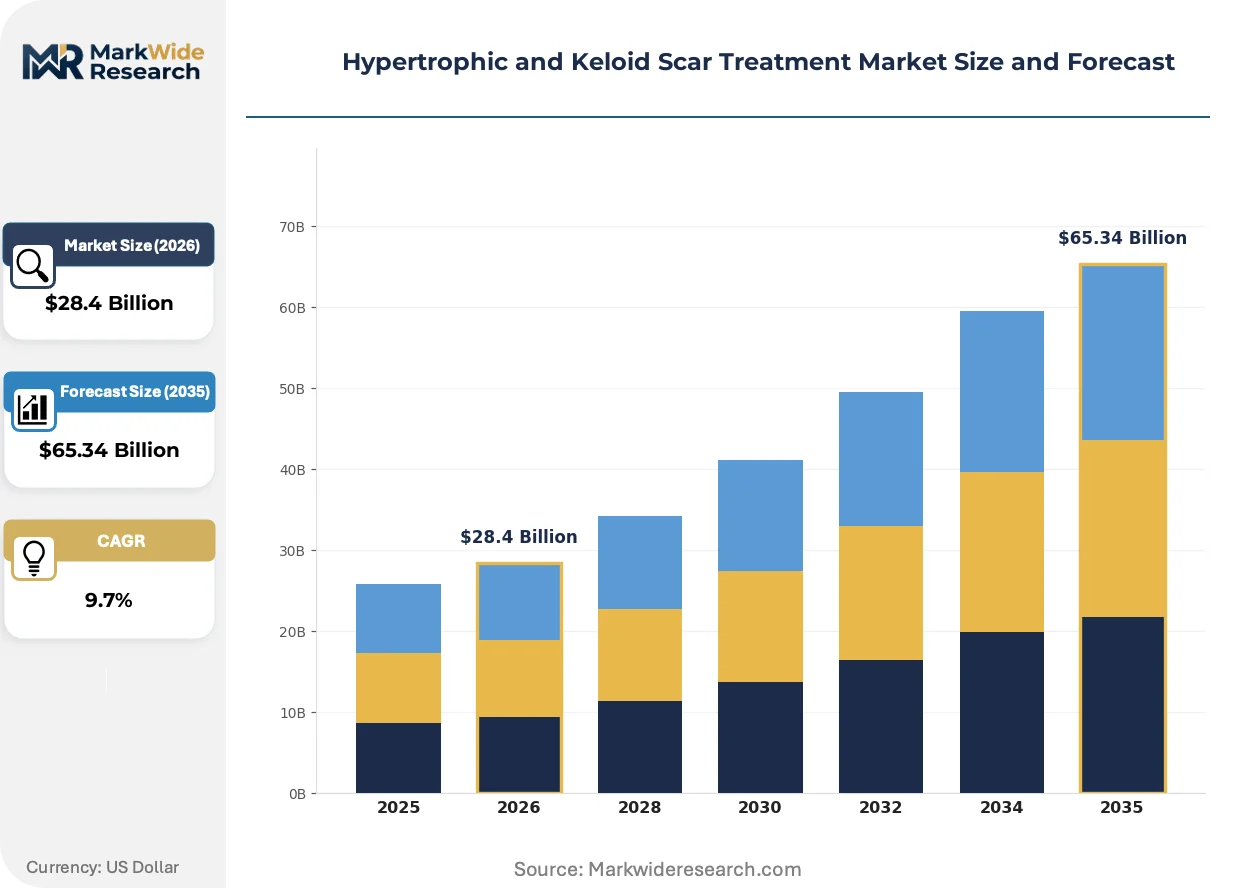
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $65.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gel, Steroid Injection, Cryotherapy, Laser Therapy Treatment Method: Topical, Surgical, Radiation, Combination End User: Hospitals, Dermatology Clinics, Homecare, Specialty Clinics Application: Cosmetic Procedures, Post-Surgical Care, Trauma Treatment, Burns Management |
| Companies Covered | Smith & Nephew, Merz Pharmaceuticals, Lumenis, Sonoma Pharmaceuticals, Cynosure, Mölnlycke Health Care, Alliance Pharma, Perrigo Company, Medytox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypertrophic and Keloid Scar Treatment Market Strategic Shifts & Innovations
Fractional laser technology is compressing treatment duration while elevating per-procedure economics. Device manufacturers are bundling energy-based platforms with proprietary topical delivery systems to lock in consumable revenue streams.
Fractional ablative lasers with tunable pulse durations are displacing traditional non-ablative protocols for mature scar revision. High-volume dermatology chains in Texas and California are retrofitting existing CO2 platforms with scanner upgrades rather than full replacement. The shift is compressing equipment refresh cycles from seven years to four while expanding addressable scar age ranges.
EU MDR reclassification of active scar devices under Class IIa and IIb rules is elevating post-market clinical follow-up obligations. Manufacturers must now submit periodic safety update reports with real-world evidence from European registries. German notified bodies are prioritizing technical documentation reviews for combination device-drug systems, delaying market access for hybrid laser-pharma platforms.
Patient acquisition is migrating from physician referral networks to direct-to-consumer digital channels. Instagram and TikTok content creators in Seoul and Los Angeles are driving consultation requests for scar revision procedures. Clinic operators in these cities now allocate forty percent of marketing spend to influencer partnerships and before-after content licensing rather than traditional medical directory placements.
Hypertrophic and Keloid Scar Treatment Market Segmentation
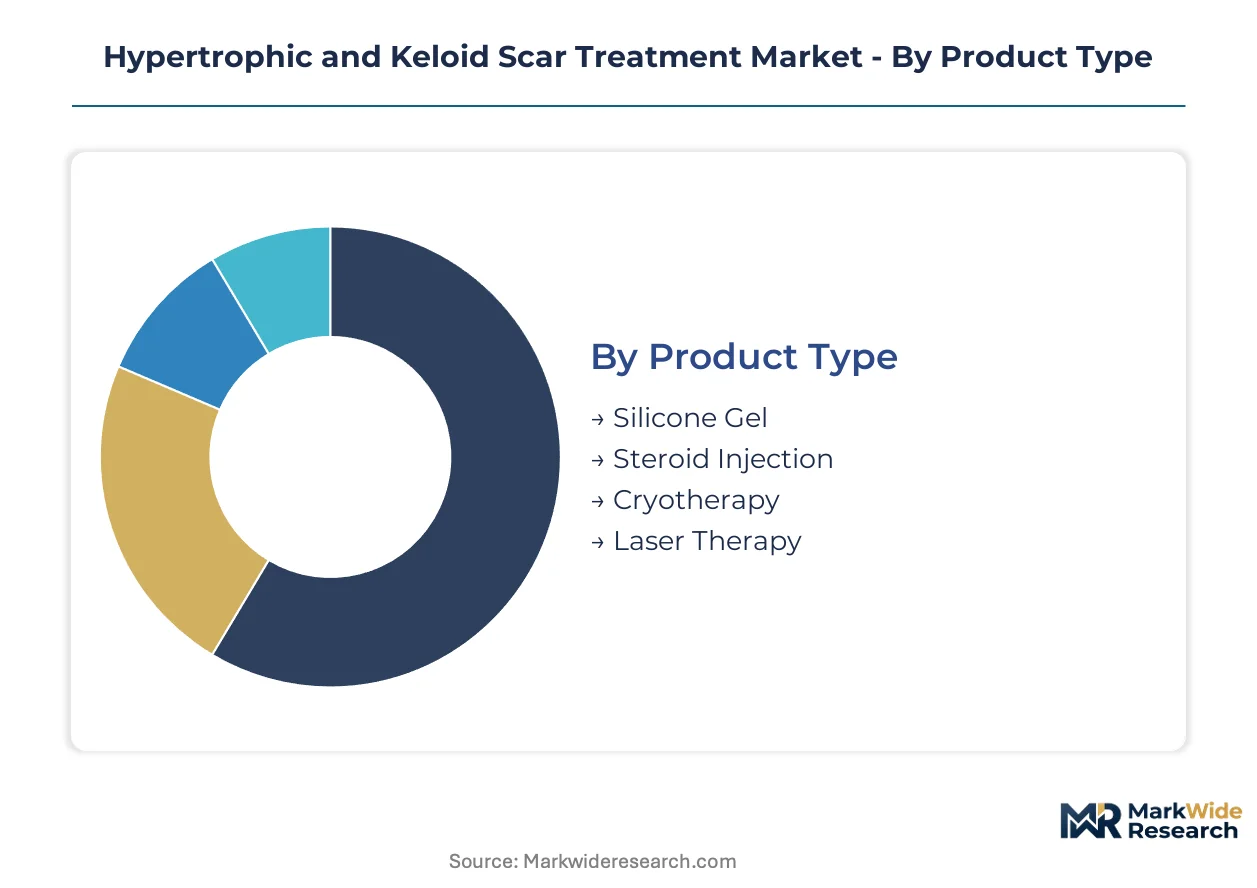
Scar treatment demand fragments across product modalities with distinct channel economics. Silicone gel flows through retail pharmacy and homecare channels, while laser and cryotherapy concentrate in outpatient clinic settings where bundling drives revenue per patient.
Product Type:
Channel mix varies sharply by intervention complexity, with prescription devices flowing through specialist clinics and self-administered products dominating retail pharmacy.
- Silicone Gel:Polymer-based occlusive sheeting and topical gels operate through hydration and pressure mechanisms. Demand concentrates in post-surgical homecare settings across Germany and the United States, where patient compliance tools embedded in mobile applications improve adherence rates.
- Laser Therapy:Fractional CO2 and pulsed-dye platforms deliver thermal injury to remodel collagen architecture. Dermatology chains in Seoul and Los Angeles capture disproportionate procedure volume as outpatient bundling reduces hospital dependency.
- Steroid Injection:Intralesional corticosteroids modulate inflammatory response in raised scar tissue. Triamcinolone formulations dominate hospital outpatient departments.
- Cryotherapy:Liquid nitrogen or nitrous oxide devices destroy fibroblastic tissue through freeze-thaw cycles. South Korean reimbursement expansion is accelerating clinic adoption.
Silicone gel dominates installed base. Laser therapy is where expansion concentrates.
Treatment Method:
Cost tier stratification separates premium device-based interventions from commodity topical approaches, with combination protocols commanding the highest per-patient economics.
- Combination:Sequential or concurrent application of multiple modalities reduces recurrence rates in refractory keloid cases. Texas and California dermatology chains are scaling multi-modality service lines fastest.
- Topical:Silicone-based gels, sheets, and onion extract formulations represent the most mature segment. Margin pools shift toward specialty clinics that can command cash-pay aesthetic premiums.
- Surgical:Excision with adjuvant therapy addresses large or function-impairing lesions. Hospital-based plastic surgery departments retain volume for complex reconstructions.
- Radiation:Post-surgical superficial radiotherapy prevents recurrence in high-risk keloid patients. EU MDR reclassification is elevating evidentiary requirements for device manufacturers.
Topical methods dominate installed base. Combination approaches are climbing the fastest.
End User:
Customer type fragmentation reflects divergent procurement authority, with hospital systems losing relative influence as independent dermatology clinics capture procedure volume.
- Dermatology Clinics:Outpatient laser and cryotherapy protocols reduce hospital dependency. Private chains in Munich and Hamburg consolidate procurement for combination therapy suites.
- Hospitals:Acute care networks retain complex surgical revision and burn reconstruction cases. Smith & Nephew leverages wound care infrastructure to dominate silicone gel distribution.
- Specialty Clinics:Aesthetic-focused practices command cash-pay premiums exceeding reimbursed medical rates. Instagram and TikTok content creators drive consultation requests in Seoul and Los Angeles.
- Homecare:Self-administered silicone sheeting and topical agents serve post-surgical maintenance protocols. Mobile application adherence tools expand addressable patient volumes.
Hospitals dominate installed base. Dermatology clinics are gaining share fastest.
Application:
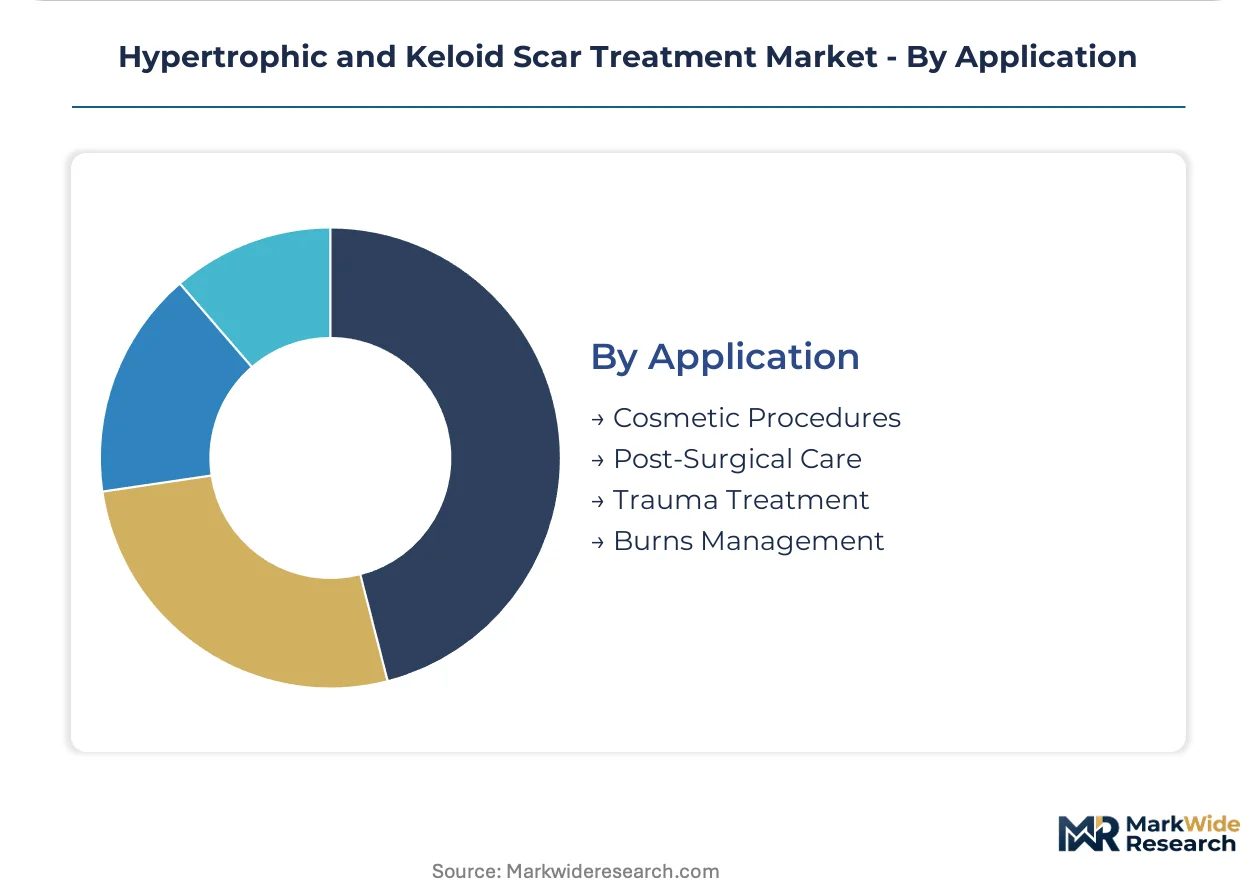
Volume concentration varies by etiology, with post-surgical prophylaxis representing the largest addressable population and cosmetic revision commanding premium pricing.
- Post-Surgical Care:Prophylactic intervention on incision sites prevents pathological scarring before maturation. Demand concentrates in cardiac and orthopedic surgery discharge protocols across the United States.
- Cosmetic Procedures:Aesthetic revision of visible scars commands cash-pay premiums exceeding reimbursed medical rates. Seoul-based clinic networks allocate forty percent of marketing spend to influencer partnerships.
- Trauma Treatment:Acute management of laceration and abrasion outcomes addresses functional and aesthetic concerns. Emergency department referral networks filter patients into appropriate intervention tiers.
- Burns Management:Contracture prevention and functional restoration require specialized multidisciplinary care. Hospital-based burn centers retain concentration for severe cases.
Post-surgical care dominates installed base. Cosmetic procedures represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatology clinics in the United States, Germany, and South Korea command disproportionate procedure volume as outpatient laser and cryotherapy protocols displace hospital-based care. FDA 510(k) pathway harmonization and EU MDR reclassification are tightening evidentiary standards across major developed markets.
United States
Post-surgical prophylaxis drives silicone gel demand through cardiac and orthopedic discharge protocols. FDA maintains streamlined 510(k) clearances for fractional CO2 and pulsed-dye laser platforms. Texas and California dermatology chains retrofit existing equipment with scanner upgrades rather than full replacement.
Germany
Private dermatology chains in Munich and Hamburg consolidate procurement for combination therapy suites. EU MDR technical documentation requirements elevate post-market surveillance obligations for active scar devices. Cash-pay aesthetic premiums in Bavaria exceed reimbursed medical rates by substantial margins.
South Korea
National health insurance now covers cryotherapy protocols for hypertrophic scarring. MFDS aligns device classification with EU MDR standards. Seoul-based clinic networks scale multi-modality service lines and allocate substantial marketing spend to influencer partnerships.
United Kingdom
Hospital outpatient departments retain volume for complex surgical revision cases. NICE guidance influences reimbursement thresholds for laser interventions. London aesthetic practices command premium positioning within the European scar treatment landscape.
Australia
TGA harmonizes with FDA and EU MDR standards for laser and radiation devices. Telehealth pre-screening protocols filter patient flow into appropriate intervention tiers. Sydney and Melbourne clinic networks license remote assessment algorithms from United States-based platforms.
Hypertrophic and Keloid Scar Treatment Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with wound care or aesthetic device foundations. Market structure exhibits moderate consolidation with tiered specialization across pharmaceutical, device, and topical segments. Strategic archetypes include wound care infrastructure deployers, laser platform bundlers, and prescription access anchors. Dominant competitive moves encompass multi-modality system integration and geographic expansion through clinic network partnerships.
Within the wound care infrastructure tier, Smith & Nephew leverages acute care distribution networks for silicone gel penetration. Merz Pharmaceuticals anchors European prescription pathways through its pharmaceutical portfolio concentration. Lumenis occupies a position exemplifying laser platform breadth with installed-base loyalty strategies. These three entities represent distinct competitive archetypes: acute care channel dominance, pharmaceutical access control, and device-technology bundling.
| Leading Market Players |
|---|
| Smith & Nephew |
| Merz Pharmaceuticals |
| Lumenis |
| Sonoma Pharmaceuticals |
| Cynosure |
| Mölnlycke Health Care |
| Alliance Pharma |
| Perrigo Company |
| Medytox |
| Others |
Cost & Logistics Intelligence
Fractional CO2 laser platforms displacing non-ablative systems simultaneously concentrate supply among three German and Israeli device manufacturers and widen pricing spreads between scanner-upgrade paths and full-platform replacements. This substitution dynamic reshapes procurement geography toward Seoul and Los Angeles clinic chains while compressing equipment refresh economics.
Pricing Analysis
Technology-generation pricing gaps separate mature CO2 platforms from pulsed-dye systems and emerging hybrid laser-pharma devices. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification tier and after-sales service bundling. Pricing pressure stems from credit tightening cycles deferring capital purchases among independent dermatology clinics. Hospital outpatient departments exhibit highest price sensitivity due to procurement committee oversight, while aesthetic-focused specialty clinics absorb premium positioning.
Supply Chain Analysis
Just-in-time inventory strategies dominate silicone gel sheeting procurement, though South Korean clinic networks maintain strategic stockpiles of cryotherapy consumables ahead of reimbursement expansion milestones. Medical-grade polymer supply concentrates in Germany, the United States, and China. Raw material dependencies include liquid nitrogen for cryotherapy, rare-earth elements for laser optics, and pharmaceutical-grade silicones. Single-source vulnerability runs through three contract manufacturers controlling medical-grade sheeting output. Distribution runs through acute care networks for silicone gel and direct manufacturer-to-clinic relationships for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hypertrophic and keloid scar treatment market sits in early-cycle recovery as EU MDR harmonization pressures clear marginal device manufacturers and consolidate procurement authority among scaled clinic networks.
For Market Incumbents: Secure installed-base loyalty through multi-modality platform bundling and scanner upgrade pathways that extend equipment lifecycles. Defend against emerging cryotherapy specialists by deepening backward integration into consumable supply. Prioritize certification investment for combination device-drug systems ahead of German notified body prioritization shifts. For New Entrants and Emerging Players: Telehealth pre-screening protocols represent the most penetrable service-layer gap as United States-based platforms license algorithms to Australian networks. Target homecare silicone gel adherence tools where mobile application integration remains underdeveloped. Pursue white-label partnerships with Seoul clinic chains seeking proprietary topical delivery systems. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors wound care infrastructure deployers with acute care channel control. Long-term viability over the next decade rests on regulatory navigation capabilities across FDA, EU MDR, and MFDS frameworks. Watch MFDS alignment announcements with EU MDR as the inflection signal for South Korean reimbursement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modality Platform Integration | Combines fractional CO2, pulsed-dye, and cryotherapy systems to lock in consumable revenue streams. |
| EU MDR Technical Documentation Investment | Positions manufacturers for Class IIa and IIb device reclassification ahead of German notified body reviews. |
| Clinic Network Partnership Expansion | Secures procurement consolidation benefits with Munich and Hamburg dermatology chains. |
| Telehealth Pre-Screening Development | Filters patient flow into appropriate intervention tiers for Texas and California dermatology chains. |
| Botulinum Toxin-Pharma Convergence | Opens prescription pathways through adjunctive neurotoxin use for tension reduction during scar maturation. |
Research Approach
The analysis maps silicone gel sheeting, laser therapy platforms, cryotherapy devices, and pharmaceutical interventions, each validated through dermatology clinic operators, hospital procurement managers, biomedical engineers, and GPO contracts administrators. Primary interviews with these stakeholders combined secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up patient-volume modeling and top-down revenue triangulation ensured cross-verification.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product modality, treatment method complexity tier, end-user procurement authority, and application etiology. CAGRs derived from procedure volume trajectories and per-patient revenue economics incorporate laser platform refresh cycle compression and cryotherapy reimbursement expansion as industry-specific inputs.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR Class IIa and IIb rules, and MFDS alignment standards; material policy shifts would require re-modeling. Specific risks include EU MDR documentation delays extending market access timelines and silicone gel supply concentration disrupting procurement. Revision becomes warranted when cryotherapy reimbursement coverage thresholds or laser technician certification timelines cross material inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market