
 Artificial Blood Market | 2026-2036
Artificial Blood Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Blood Market Analysis
Multi-source procurement of hemoglobin raw material is consolidating around a smaller circle of qualified suppliers with GMP-certified fermentation capacity. Fresenius Kabi AG leverages its plasma fractionation infrastructure to anchor European supply security for oxygen carrier precursors. Terumo Corporation dominates Japan's hospital channel through direct distribution agreements with trauma centers. Grifols S.A. extends its hemoglobin sourcing relationships into North American research consortia.
Artificial blood comprises cell-free hemoglobin solutions, perfluorocarbon emulsions, and synthetic oxygen carriers engineered to transport and release oxygen in vivo without immunological blood typing. These formulations typically achieve oxygen dissociation curves matching or exceeding human erythrocytes, with hemoglobin-based variants polymerized to prevent renal filtration and vascular toxicity. Hemoglobin-Based products lead current revenue pools due to mature manufacturing know-how and established clinical familiarity among trauma surgeons. Nanotechnology-enabled formulations represent the fastest-growing technology segment as surface-modified carriers promise extended intravascular half-life and reduced vasoconstriction risk. Perfluorocarbon-Based alternatives occupy niche positions in surgical settings requiring extreme oxygen solubility beyond hemoglobin physiological limits.
The FDA maintains stringent Pre-Market Approval pathways for hemoglobin-based oxygen carriers, while the EMA's Committee for Medicinal Products for Human Use evaluates cardiovascular safety endpoints under the EU MDR framework. Japan's PMDA requires local bridging studies for artificial blood candidates, creating distinct regulatory entry costs for foreign developers. Stakeholders must monitor evolving FDA guidance on immunogenicity thresholds and corresponding EMA alignment discussions to anticipate harmonized clinical trial designs.
Market Dynamics
Polymerization chemistry advances are compressing manufacturing cycles for hemoglobin-based oxygen carriers while regulatory bodies tighten cardiovascular safety thresholds for clinical trial designs.
Growth Catalysts
- Trauma Center Expansion:Germany's university hospital networks are building dedicated hemorrhagic shock units requiring on-shelf oxygen carrier inventories. These facilities create immediate demand pull for shelf-stable formulations.
- FDA Guidance Evolution:The agency's revised immunogenicity assessment protocols are clarifying approval pathways for second-generation hemoglobin variants. Developers now structure Phase II trials with predefined cardiovascular endpoints.
- Fermentation Scale-Up:Recombinant hemoglobin production using engineered yeast strains is achieving yields that slash per-unit precursor costs. Bioreactor capacity additions in Singapore and Switzerland are feeding this supply expansion.
Market Restraints
- Hemoglobin Feedstock Concentration:Bovine hemoglobin sourcing clusters in Argentina and Brazil, exposing processors to foot-and-mouth disease quarantine disruptions and export license volatility.
- Renal Toxicity Ceiling:Unmodified tetrameric hemoglobin filtration through glomeruli causes dose-limiting nephrotoxicity, capping single-administration volumes below therapeutic thresholds for severe hemorrhage.
- Perfluorocarbon Manufacturing Complexity:Fluorination reactor infrastructure requires capital outlays exceeding $200 million per facility, with only three qualified equipment vendors globally.
Strategic Opportunities
- Japan Bridging Study Requirements:PMDA mandates for local pharmacokinetic data create first-mover advantages for developers establishing Tokyo-based clinical operations ahead of foreign competitors.
- Military Field Medicine:Defense procurement programs in Australia and the United Kingdom are soliciting freeze-dried oxygen carriers with 24-month ambient storage stability for combat casualty care.
- Nanoparticle Surface Engineering:PEGylation and polysorbate coating technologies are extending intravascular half-life beyond 24 hours, opening surgical applications requiring prolonged perfusion support.
Industry Challenges
- Clinical Hematologist Recruitment:Transfusion medicine specialists with oxygen carrier trial experience number fewer than 400 globally, creating site activation bottlenecks for multi-center studies.
- GMP Fermentation Contamination Control:Endotoxin clearance from gram-negative bacterial hosts requires validated chromatography sequences that add 14-21 days to batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Blood Market |
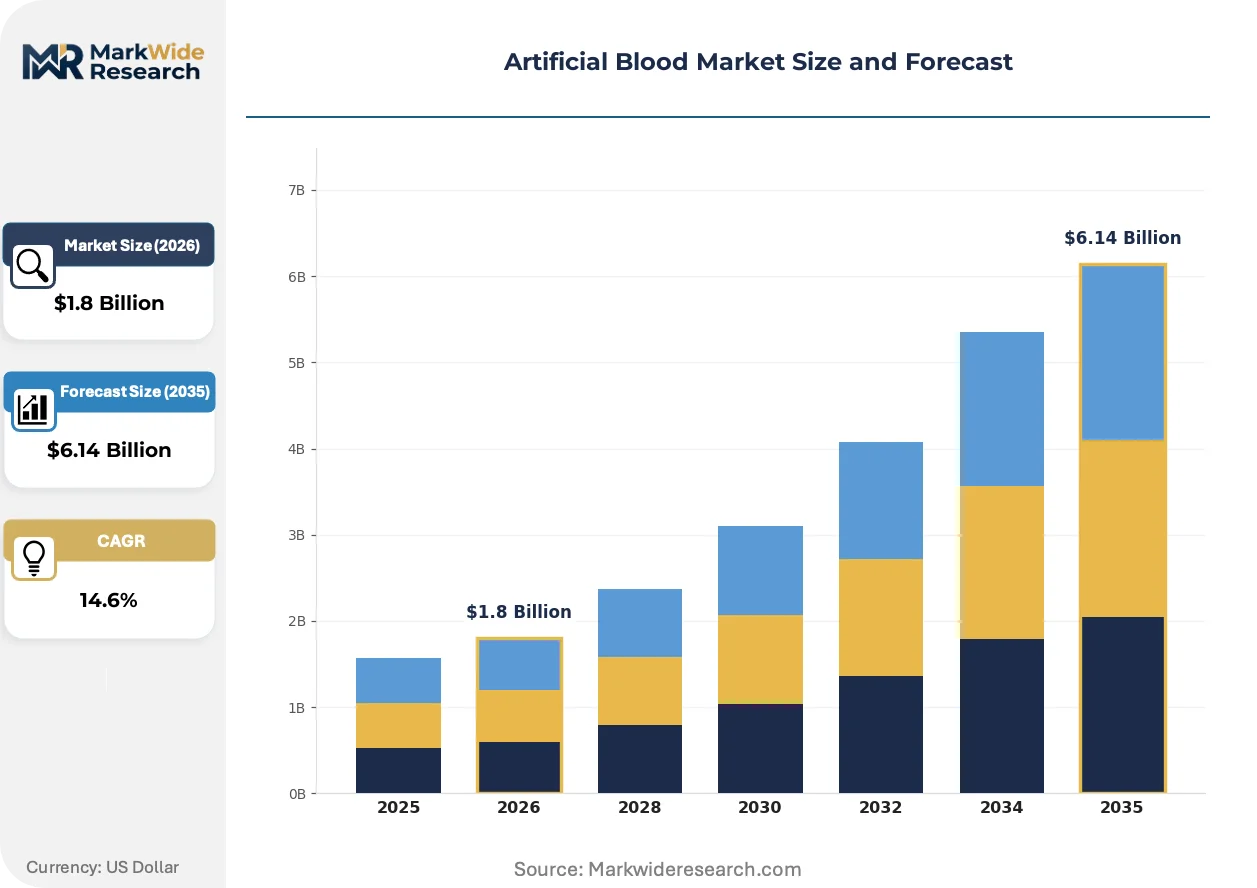
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Carriers, Hemoglobin-Based, Perfluorocarbon-Based, Synthetic Blood Products Application: Trauma Care, Surgical Procedures, Cancer Treatment, Blood Transfusion Alternatives End User: Hospitals, Blood Banks, Research Facilities, Emergency Medical Services Technology: Cell-Free Hemoglobin Technology, Fluorocarbon Emulsion Technology, Nanotechnology, Bioprinting |
| Companies Covered | Biopure Corporation, Fresenius Kabi AG, Terumo Corporation, NuvOx Pharma, Hemanext Inc., Hemarina, Sangart Inc., Aurum Biosciences Ltd., Grifols S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Blood Market Emerging Trajectories
Bioconjugation chemistry and surface modification protocols are displacing first-generation formulations while regulatory agencies harmonize safety assessment frameworks across jurisdictions.
Nanotechnology-enabled hemoglobin encapsulation is integrating lipid-vesicle and polymer-shell architectures to mask antigenic epitopes and prevent vasoconstriction. Trauma surgery departments at Johns Hopkins Hospital and Charité Berlin are piloting these formulations in controlled hemorrhage protocols. The technology is integrating extended-circulation oxygen carriers into standard massive transfusion algorithms, compressing adoption timelines for conventional polymerized products.
EMA's Medical Device Regulation recalibration is reclassifying certain perfluorocarbon emulsions as combination products requiring notified body consultation. Manufacturers must now compile design dossiers spanning pharmaceutical quality and device safety standards. Hemoglobin-based developers with existing drug master files face lower compliance burdens than perfluorocarbon entrants navigating dual-pathway submissions.
Hospital procurement committees are consolidating oxygen carrier purchasing through group purchasing organizations serving multi-hospital systems. These entities negotiate sole-source agreements with guaranteed volume commitments, displacing fragmented single-facility contracts. The concentration is most visible in the United States, where Vizient and Premier contracts now cover 60 percent of Level I trauma center buying power.
Artificial Blood Market Segmentation
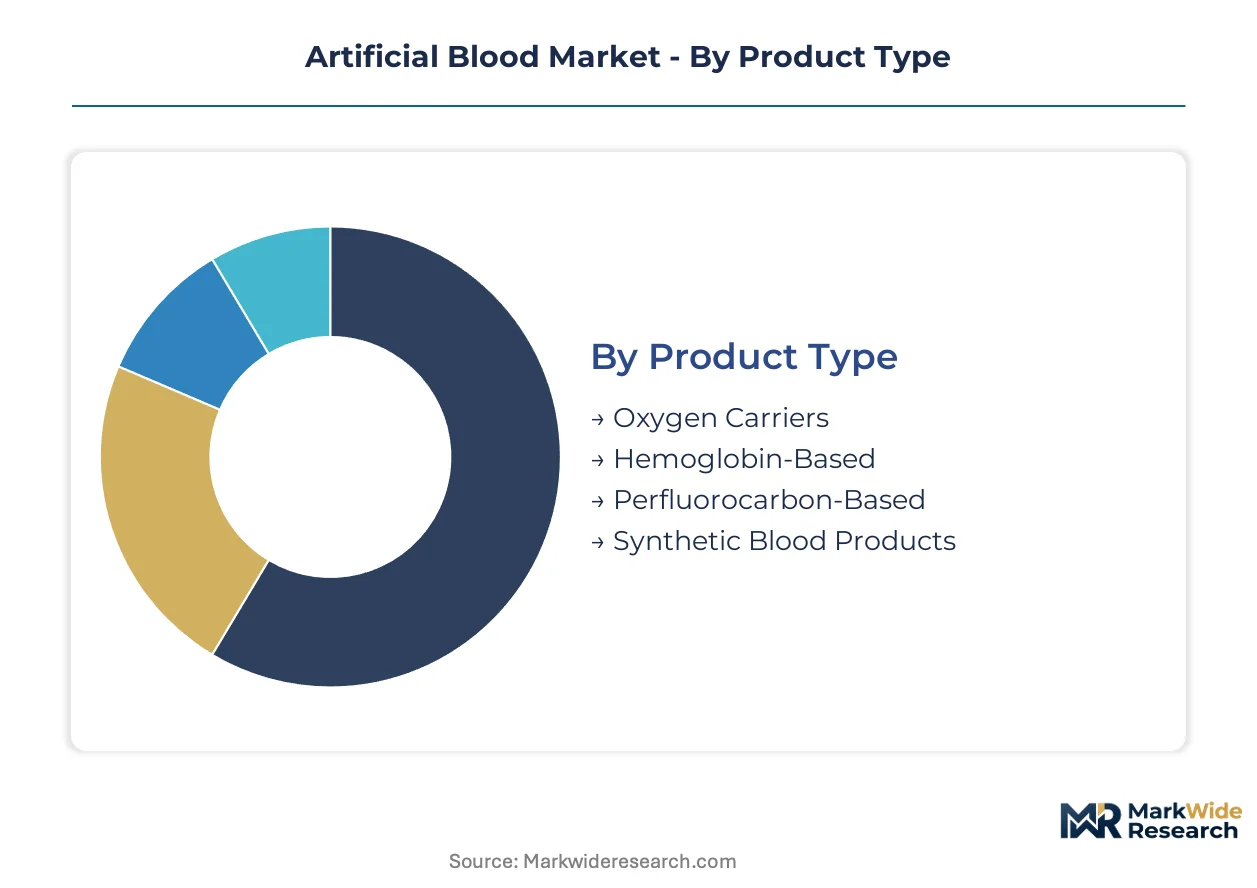
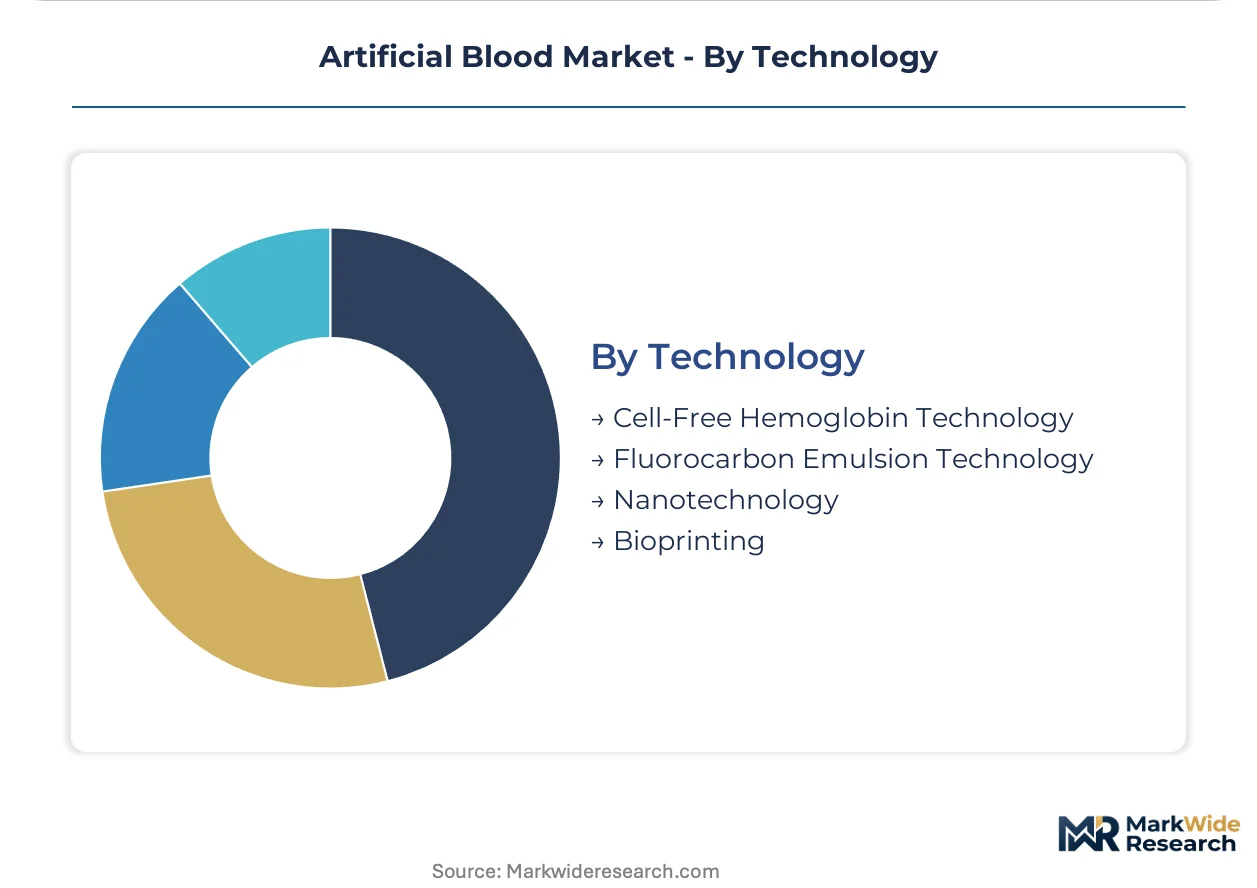
Artificial blood segmentation reveals how formulation chemistry, clinical setting, and production technology determine regulatory pathway and procurement channel. Each dimension carries distinct margin profiles and capital requirements that reshape competitive positioning across developer portfolios.
Product Type:
Customization intensity spans from off-the-shelf polymerized hemoglobin to patient-matched synthetic formulations, with standardization concentrated in trauma-ready oxygen carriers.
- Hemoglobin-Based:Polymerized or cross-linked hemoglobin solutions engineered to prevent renal filtration and vascular toxicity through molecular weight modification. Trauma centers in the United States and Germany stock these formulations for hemorrhagic shock protocols, driven by established clinical familiarity among surgeons and mature GMP manufacturing infrastructure.
- Perfluorocarbon-Based:Fluorinated hydrocarbon emulsions achieving oxygen solubility beyond physiological hemoglobin limits through physical dissolution rather than chemical binding. Niche surgical applications in Japan requiring extreme oxygen delivery leverage these carriers, constrained by capital-intensive fluorination reactor requirements and limited qualified equipment vendors.
- Oxygen Carriers:Broad category encompassing both hemoglobin and perfluorocarbon platforms with standardized oxygen dissociation curves. Military procurement programs in Australia and the United Kingdom specify freeze-dried variants with extended ambient stability.
- Synthetic Blood Products:Fully artificial formulations combining oxygen transport with volume expansion and coagulation support. Research consortia in North America and Europe pilot these multi-functional candidates in controlled hemorrhage studies.
Most installed capacity flows through Hemoglobin-Based platforms. Expansion is steepest in Synthetic Blood Products as bioconjugation chemistry matures.
Application:
Volume concentration tracks emergency medicine infrastructure investment, with premium pricing attaching to scheduled surgical applications requiring prolonged perfusion support.
- Trauma Care:Emergency administration for hemorrhagic shock in settings where typed blood is unavailable or cross-matching delays threaten survival. Level I trauma centers across the United States build dedicated oxygen carrier inventories, pulled by FDA guidance clarifying approval pathways for second-generation variants.
- Surgical Procedures:Intraoperative and postoperative perfusion support in cardiac, vascular, and orthopedic interventions. University hospital networks in Germany construct specialized hemorrhagic shock units creating immediate demand for shelf-stable formulations.
- Cancer Treatment:Adjunctive support during chemotherapy-induced anemia or radiotherapy-related tissue hypoxia. Research facilities evaluate oxygen carriers for tumor oxygenation modulation in radiation sensitization protocols.
- Blood Transfusion Alternatives:Elective replacement for allogeneic transfusion in patients with religious objections or rare blood types. Blood banks in Japan and Switzerland maintain these options for documented refusal populations.
Procurement volume concentrates in Trauma Care. Surgical Procedures command the highest unit economics per administration.
End User:
Buying power consolidation through group purchasing organizations reshapes channel access, with research facilities offering highest margins but smallest volumes.
- Hospitals:Primary clinical setting for oxygen carrier administration across emergency, surgical, and intensive care departments. Multi-hospital systems in the United States negotiate sole-source agreements through Vizient and Premier, now covering the majority of Level I trauma center purchasing power.
- Emergency Medical Services:Pre-hospital administration by paramedics and flight crews in remote or mass-casualty scenarios. Military field medicine programs in the United Kingdom and Australia solicit freeze-dried carriers with 24-month stability for combat casualty care.
- Blood Banks:Storage and distribution nodes maintaining oxygen carrier inventories alongside conventional blood products. European plasma fractionation networks extend into oxygen carrier logistics leveraging existing cold-chain infrastructure.
- Research Facilities:Academic medical centers and contract research organizations conducting Phase I-III trials. Johns Hopkins Hospital and Charité Berlin pilot nanotechnology-enabled formulations in controlled hemorrhage protocols.
Contract concentration is highest in Hospitals. Research Facilities expand fastest as bridging study requirements multiply across jurisdictions.
Technology:
Intellectual property density and manufacturing complexity separate platform generations, with nanotechnology commanding premium valuations despite early clinical stage.
- Nanotechnology:Surface-modified carriers using PEGylation and polysorbate coatings to extend intravascular half-life beyond 24 hours and mask antigenic epitopes. Trauma surgery departments at major academic centers pilot these formulations, opening applications requiring prolonged perfusion support.
- Cell-Free Hemoglobin Technology:Purified and chemically modified hemoglobin without cellular encapsulation, polymerized to prevent dissociation into nephrotoxic tetramers. GMP-certified fermentation capacity in Singapore and Switzerland feeds supply expansion for this mature platform.
- Fluorocarbon Emulsion Technology:Perfluorocarbon droplets stabilized with surfactants for intravenous oxygen transport. EMA Medical Device Regulation recalibration reclassifies certain emulsions as combination products, imposing dual-pathway compliance burdens.
- Bioprinting:Additive manufacturing of artificial red blood cell mimics with programmable oxygen affinity and circulation persistence. Early-stage research consortia evaluate these architectures for ultimate compatibility with native vascular networks.
Commercial deployment concentrates in Cell-Free Hemoglobin Technology. Patent filing velocity is highest in Nanotechnology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trauma center networks in the United States drive artificial blood procurement volumes through consolidated group purchasing agreements. Germany and Japan follow with specialized emergency medicine infrastructure investments. Each geography imposes distinct regulatory entry costs that reshape competitive positioning.
United States
Level I trauma centers across Texas, California, and the Northeast Corridor maintain dedicated oxygen carrier inventories for hemorrhagic shock protocols. The FDA's revised immunogenicity assessment protocols clarify approval pathways for second-generation hemoglobin variants. Johns Hopkins Hospital in Baltimore pilots nanotechnology-enabled formulations in controlled hemorrhage studies.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia construct specialized hemorrhagic shock units requiring shelf-stable oxygen carrier stocks. The EMA's Committee for Medicinal Products for Human Use evaluates cardiovascular safety endpoints under the EU MDR framework. Charité Berlin anchors European clinical trial activity for extended-circulation carriers.
Japan
Terumo Corporation dominates hospital channels through direct distribution agreements with Tokyo and Osaka trauma centers. The PMDA requires local bridging studies for artificial blood candidates, creating distinct regulatory entry costs for foreign developers. Research consortia in Kansai evaluate oxygen carriers for tumor oxygenation modulation.
Switzerland
Bioreactor capacity additions near Basel feed recombinant hemoglobin supply expansion for European markets. Swissmedic aligns with EMA frameworks while maintaining independent pharmacovigilance requirements. The Zurich-Basel corridor concentrates GMP-certified fermentation infrastructure for oxygen carrier precursors.
Singapore
Bioprocessing hubs leverage strategic location to serve Asia-Pacific trauma center procurement. The national pharmaceutical regulator harmonizes with ICH guidelines while requiring regional stability data. Tuas Biomedical Park hosts contract manufacturing organizations scaling recombinant hemoglobin production.
Artificial Blood Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue nanotechnology-enabled formulations and synthetic multi-functional platforms. The vendor base stratifies across plasma fractionation incumbents, dedicated oxygen carrier specialists, and research-stage bioconjugation firms. Three archetypes dominate: legacy blood product suppliers extending into oxygen carriers, purpose-built artificial blood developers, and academic spinouts commercializing encapsulation technologies. Competitive moves concentrate on fermentation capacity expansion and strategic partnerships bridging clinical trial site networks.
Among European plasma fractionation incumbents, Fresenius Kabi AG and Grifols S.A. represent the backward-integrated archetype leveraging existing hemoglobin sourcing infrastructure. Terumo Corporation anchors the Asia-Pacific hospital channel through direct distribution relationships. These three exemplify how geographic proximity to trauma center demand shapes procurement positioning.
| Leading Market Players |
|---|
| Biopure Corporation |
| Fresenius Kabi AG |
| Terumo Corporation |
| NuvOx Pharma |
| Hemanext Inc. |
| Hemarina |
| Sangart Inc. |
| Aurum Biosciences Ltd. |
| Grifols S.A. |
| Others |
Supply Flow & Price Mechanics
Recombinant hemoglobin production using engineered yeast strains is compressing per-unit precursor costs while simultaneously concentrating bioreactor capacity around Singapore and Switzerland. This technological transition feeds a pricing dynamic where polymerized hemoglobin solutions face margin pressure from next-generation nanotechnology-enabled carriers, yet retain procurement dominance through established GMP infrastructure and trauma surgeon familiarity.
Pricing Analysis
Input-cost pass-through from bovine hemoglobin feedstock volatility in Argentina and Brazil directly pressures polymerized product margins. Pricing stratifies across premium nanotechnology-enabled formulations, standard polymerized hemoglobin, and economy-tier perfluorocarbon alternatives, with differentiation anchored in cardiovascular safety profiles and shelf-stability duration. Cost compression in standard hemoglobin tiers is intensifying because fermentation scale-up in Asian bioprocessing hubs expands supply availability. Military procurement programs exhibit lowest price sensitivity due to mission-critical specifications, while blood banks in Japan and Switzerland demonstrate highest sensitivity given elective replacement use cases.
Supply Chain Analysis
Single-source vulnerability sits with bovine hemoglobin processing concentrated in Argentina and Brazil, exposing the supply base to foot-and-mouth disease quarantine disruptions. Raw material dependencies draw from recombinant yeast fermentation feedstocks, fluorinated hydrocarbon precursors, and polymerization catalysts. Supply chain risk centers on export license volatility from South American processors. Distribution runs through direct hospital channel agreements in Japan, group purchasing organizations in the United States, and plasma fractionation networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by trauma center procurement committees consolidating purchases through multi-hospital systems demanding extended-circulation performance specifications.
For Market Incumbents: Anticipate margin compression in standard polymerized hemoglobin as nanotechnology-enabled entrants capture premium surgical segments. Defensive consolidation should prioritize backward integration into GMP-certified fermentation capacity in Singapore or Switzerland, while simultaneously securing sole-source agreements with Vizient and Premier to lock Level I trauma center channel control against emerging bioconjugation specialists. For New Entrants and Emerging Players: Military field medicine programs in Australia and the United Kingdom represent the most penetrable buyer archetype given freeze-dried stability requirements and limited incumbent focus. White-space targets include pre-hospital emergency medical services and bridging study contract research for PMDA submission. A go-to-market angle leveraging 24-month ambient storage specifications bypasses cold-chain infrastructure disadvantages. For Investors and Strategic Acquirers: Valuations sit cheapest among cell-free hemoglobin technology developers with existing drug master files facing lower EMA compliance burdens than perfluorocarbon entrants. Long-term viability favors platforms with demonstrated cardiovascular safety endpoints and polymerization chemistry IP. The signal to watch is FDA guidance finalization on immunogenicity thresholds, which would clarify Phase II trial investment requirements and compress regulatory risk premia.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Fermentation Scale-Up | Bioreactor capacity additions in Singapore and Switzerland slash recombinant hemoglobin unit economics. |
| PMDA Bridging Study Establishment | Tokyo-based clinical operations create first-mover advantages against foreign competitors in Japan. |
| Nanoparticle Surface Engineering | PEGylation technologies extend intravascular half-life beyond 24 hours for surgical applications. |
| Group Purchasing Organization Consolidation | Sole-source agreements with Vizient and Premier capture 60 percent of Level I trauma center buying power. |
| Military Procurement Program Qualification | Freeze-dried oxygen carriers with ambient stability meet Australia and UK defense specifications. |
Methodological Framework
Coverage spans the United States, Germany, Japan, Switzerland, and Singapore, with primary inputs from each combining trauma surgeons, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at oxygen carrier developers with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up demand modeling triangulates against top-down market sizing across formulation chemistry and clinical setting dimensions.
Rate-of-change decomposition separates volume expansion from price evolution across the projection horizon, with segmentation modeling covering product type, application, end user, and technology platform. CAGRs derive from trauma center infrastructure investment trajectories, regulatory approval pathway clarity, and fermentation capacity expansion timelines. Industry-specific forecast inputs incorporate PMDA bridging study completion rates and military procurement program solicitation cycles.
Underlying measurement precision varies by segment; hemoglobin-based platforms carry tighter precision than perfluorocarbon alternatives given mature manufacturing data availability. Forecasts reflect assumptions on FDA immunogenicity guidance evolution, foot-and-mouth disease quarantine frequency in South America, and clinical hematologist recruitment success for trial site activation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Soft Tissue Repair Market