
 Australia Digital X-Ray Market | 2026-2036
Australia Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Digital X-Ray Market Outlook
Australia is fragmenting its digital X-ray procurement across state-based health networks rather than consolidating nationally. Fujifilm Holdings Corporation leverages its direct service infrastructure to sustain long-term contracts with Queensland Health. GE Healthcare anchors its position through bundled asset management agreements that span multiple hospital sites. Siemens Healthineers differentiates via AI-integrated imaging workflows that reduce radiologist reading times.
A digital X-ray system converts ionizing radiation into electronic signals for immediate image display, using flat panel detectors with spatial resolution typically exceeding 2.5 line pairs per millimeter and dynamic range above 16 bits to enable diagnostic visualization of bone, soft tissue, and contrast-enhanced organs. Fixed X-ray systems dominate capital budgets in major hospitals where throughput requirements justify permanent installation, while portable X-ray units capture the fastest expansion as aged care facilities and remote clinics prioritize point-of-care flexibility. Wireless detectors command premium positioning within the technology dimension due to elimination of tethered workflows that delay emergency department throughput.
TGA medical device registration mandates clinical evidence standards that filter lower-specification imports from Australian tenders, while Medicare Benefits Schedule updates directly determine reimbursement eligibility for digital diagnostic procedures and thus influence hospital upgrade cycles. State health department procurement frameworks layer additional compliance requirements onto vendor qualification processes. Stakeholders must monitor how Therapeutic Goods Administration digital health integration guidelines evolve to determine whether software-enabled diagnostics require separate conformity assessment pathways from hardware platforms.
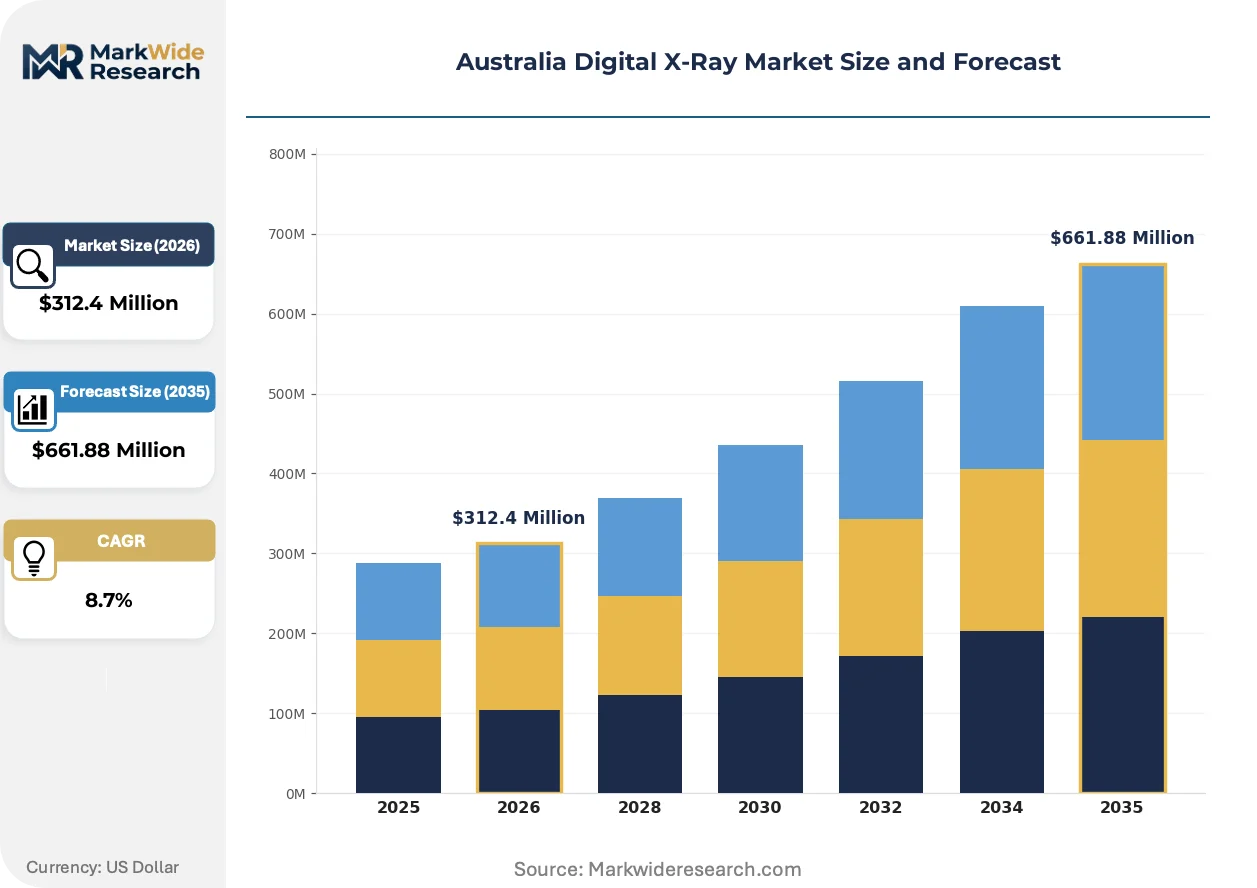
Market Dynamics
Hospital radiology departments across New South Wales and Victoria are accelerating replacement cycles as flat panel detector technology matures and TGA registration pathways clarify for software-enabled diagnostics. State-based procurement fragmentation creates divergent compliance timelines that vendors must navigate simultaneously.
Growth Catalysts
- Medicare Benefits Schedule updates:Reimbursement eligibility revisions for digital diagnostic procedures directly accelerate hospital capital expenditure programs in tertiary centers.
- Wireless detector adoption:Emergency departments in Queensland Health networks eliminate tethered workflows, compressing patient throughput times and justifying premium hardware procurement.
- Aged care facility expansion:Point-of-care flexibility requirements in remote clinics and residential aged care drive portable X-ray unit demand faster than fixed system replacement.
Market Restraints
- Flat panel detector supply concentration:Component sourcing relies on limited manufacturing geographies, exposing procurement timelines to semiconductor foundry capacity constraints.
- TGA clinical evidence standards:Registration mandates filter lower-specification imports from Australian tenders, extending vendor qualification periods for emerging manufacturers.
- Capital intensity of fixed installations:Permanent system deployment requires dedicated shielding infrastructure and HVAC modifications that strain regional hospital budgets.
Strategic Opportunities
- AI-integrated imaging workflows:Machine learning algorithms that reduce radiologist reading times create differentiation pathways for vendors with software development capabilities.
- Remote and rural clinic penetration:Western Australia and Northern Territory health networks present underpenetrated demand for mobile diagnostic units with satellite connectivity.
- State health department bundled agreements:Multi-site asset management contracts spanning hospital networks enable long-term service revenue capture and equipment lock-in.
Industry Challenges
- Radiologist workforce constraints:Specialized training pipelines for diagnostic imaging interpretation create bottlenecks that constrain throughput expansion regardless of hardware availability.
- Legacy analog system integration:Hybrid workflows during transition periods demand temporary interoperability solutions that complicate staff training and quality assurance protocols.
- Software-hardware conformity assessment divergence:TGA digital health integration guidelines remain unsettled on whether AI-enabled diagnostics require separate regulatory pathways from detector hardware platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Digital X-Ray Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed X-Ray Systems, Portable X-Ray Units, Computed Radiography Systems, Digital Fluoroscopy Systems End User: Hospitals, Diagnostic Imaging Centers, Outpatient Clinics, Research Laboratories Technology: Wireless Detectors, Flat Panel Detectors, Image Processing Software, Digital Sensors Application: Orthopedic, Dental Imaging, Cardiac Screening, Oncology |
| Companies Covered | Fujifilm Holdings Corporation, Shimadzu Corporation, GE Healthcare, Canon Medical Systems Corporation, Koninklijke Philips NV, Siemens Healthineers AG, Hologic Inc, Agfa Healthcare, Carestream Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Digital X-Ray Market Strategic Shifts
Cloud-native image archiving and artificial intelligence inference engines are restructuring how Australian health networks deploy diagnostic infrastructure. These shifts compress capital cycles and redistribute technical capabilities across the care continuum.
Advanced visualization software is virtualizing radiology workstation deployment across Australian hospital networks. Tertiary centers in Sydney and Melbourne adopt browser-based diagnostic interfaces that eliminate dedicated reading room hardware. This architecture is virtualizing capital allocation from physical equipment toward subscription-based software licensing.
TGA digital health integration guidelines are evolving to address software-enabled diagnostics as distinct regulated articles from detector hardware. Device sponsors must now demonstrate algorithm validation alongside traditional electromagnetic safety compliance. Radiology departments in Queensland and Victoria adjust procurement specifications to accommodate dual-pathway conformity assessments.
Consolidated state procurement frameworks are compressing vendor qualification timelines while fragmenting contract award decisions. Queensland Health and New South Wales Health operate independent tender processes with divergent technical weighting schemes. Equipment suppliers maintain parallel compliance documentation to preserve eligibility across jurisdictions without standardization.
Australia Digital X-Ray Market Segmentation
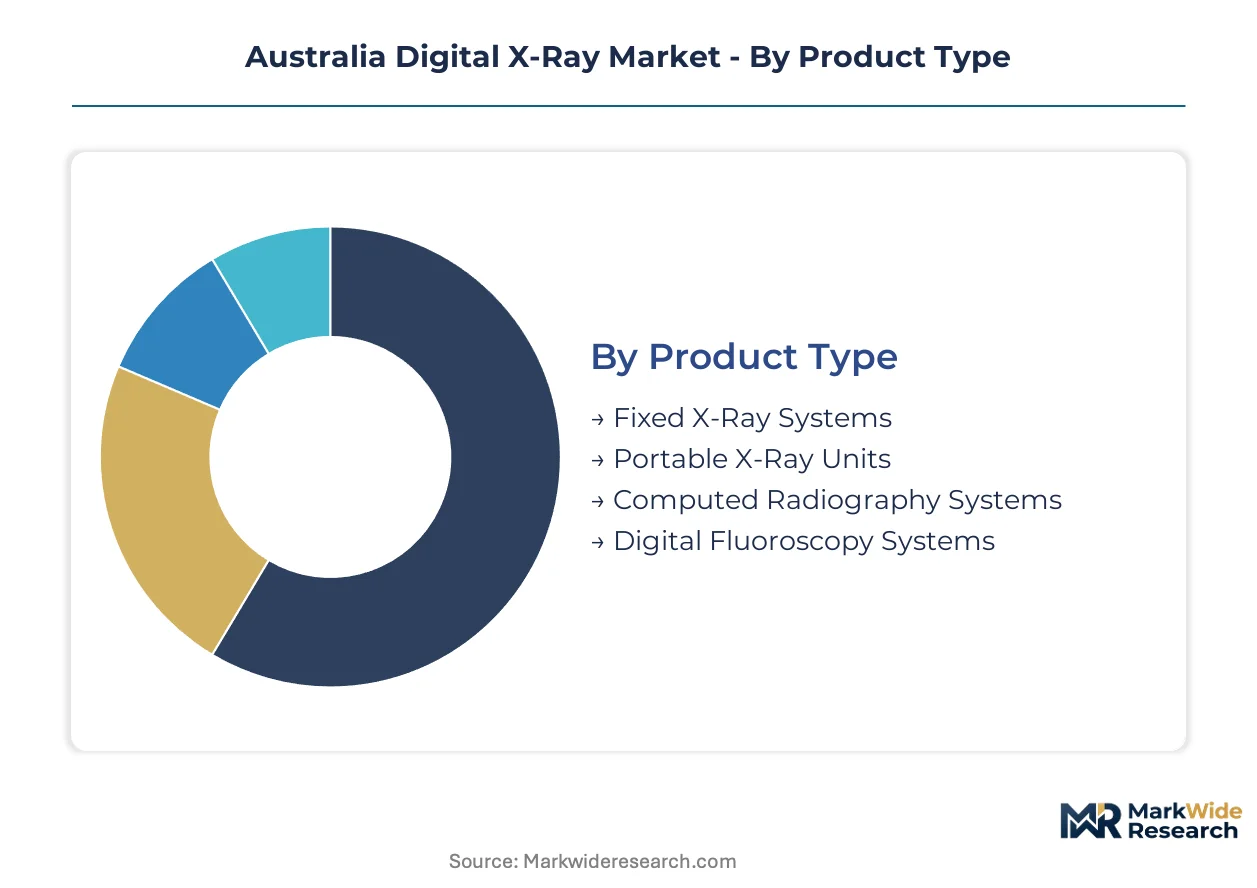
Segmentation reveals how procurement priorities diverge across Australian health networks. State-based tender frameworks and Medicare reimbursement schedules create distinct demand profiles that vendors must navigate simultaneously.
Product Type:
After-sales-service intensity varies sharply across installation types, with fixed systems demanding multi-year asset management contracts and portable units requiring rapid-response field support.
- Fixed X-Ray Systems:Permanent installations integrate flat panel detectors with dedicated shielding infrastructure and HVAC modifications. Major tertiary hospitals in New South Wales and Victoria anchor capital programs here, constrained by semiconductor foundry capacity for detector sourcing.
- Portable X-Ray Units:Battery-powered mobile systems enable point-of-care imaging at bedside or in remote settings. Aged care facilities and rural clinics in Queensland drive fastest expansion, prioritizing workflow flexibility over maximum resolution.
- Computed Radiography Systems:Cassette-based digital conversion technology serves budget-constrained regional hospitals transitioning from analog workflows.
- Digital Fluoroscopy Systems:Real-time moving image capture supports interventional procedures and contrast studies in cardiac and gastrointestinal applications.
By volume, Fixed X-Ray Systems leads. By growth pace, Portable X-Ray Units is ahead.
End User:
Customer type determines procurement authority structures, with state health departments controlling hospital tenders while private imaging centers negotiate directly with vendors.
- Hospitals:Public and private acute care facilities operate radiology departments with 24/7 throughput requirements. Radiology workforce constraints in Sydney and Melbourne limit expansion regardless of hardware availability.
- Diagnostic Imaging Centers:Standalone facilities compete on turnaround time and specialist radiologist access. Medicare Benefits Schedule reimbursement rates directly determine equipment upgrade cycles.
- Outpatient Clinics:Community-based settings handle lower-acuity referrals with constrained capital budgets and space limitations.
- Research Laboratories:Academic medical centers in Melbourne and Brisbane deploy preclinical imaging for trial protocols and device validation studies.
Hospitals dominate installed base. Diagnostic Imaging Centers show steepest expansion trajectory as private capital flows into outsourced radiology services.
Technology:
Component sourcing geography concentrates manufacturing risk, with flat panel detector supply chains exposed to semiconductor foundry bottlenecks.
- Wireless Detectors:Tether-free flat panel units eliminate cable management in emergency department workflows. Queensland Health networks justify premium procurement through compressed patient throughput times.
- Flat Panel Detectors:Direct conversion sensors using amorphous selenium or indirect scintillator layers achieve spatial resolution exceeding diagnostic thresholds. TGA registration mandates filter lower-specification imports from Australian tenders.
- Image Processing Software:Algorithm-enabled reconstruction and noise reduction tools face evolving conformity assessment pathways under TGA digital health integration guidelines.
- Digital Sensors:Charged-coupled device and complementary metal-oxide-semiconductor architectures serve cost-sensitive retrofit applications.
Flat Panel Detectors anchor revenue concentration. Wireless Detectors are gaining share fastest as emergency departments prioritize workflow velocity.
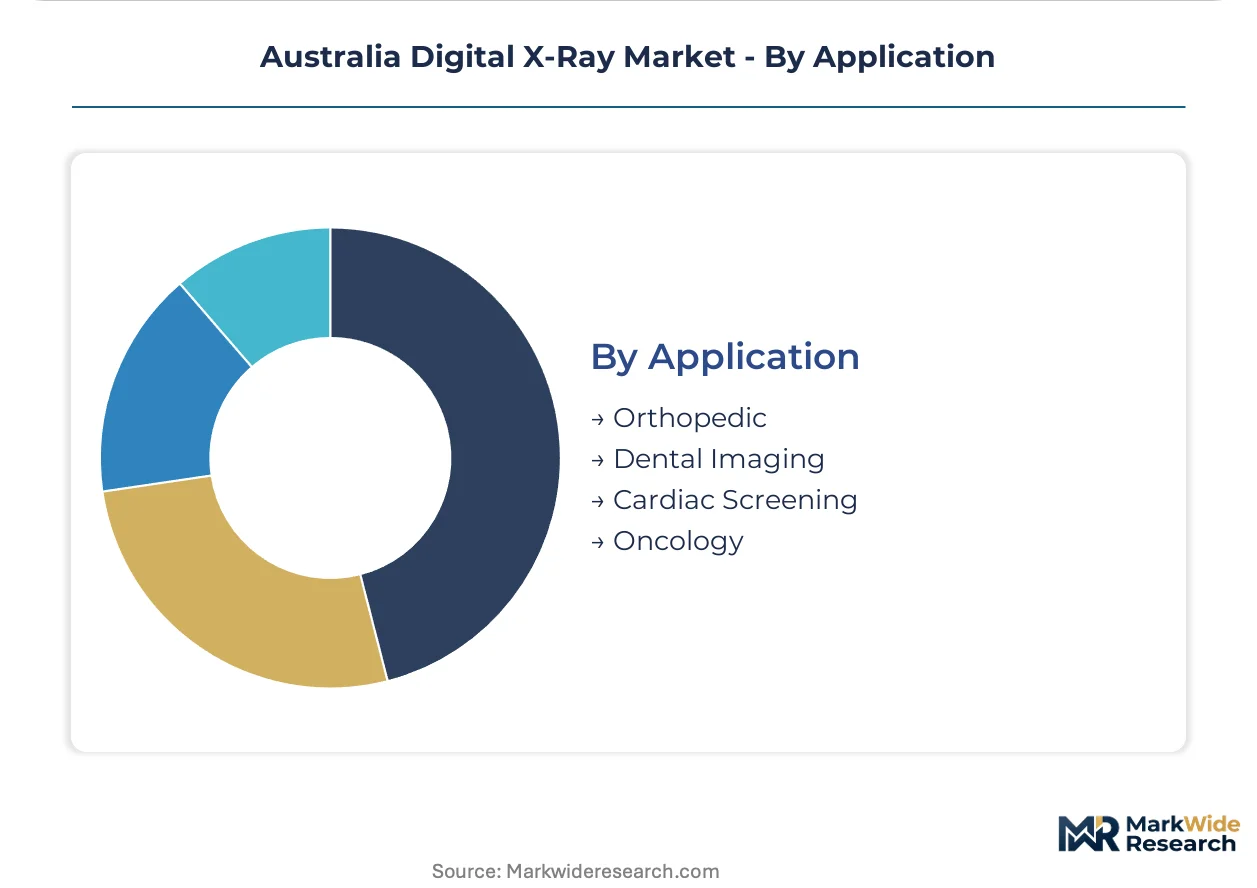
Application:
Clinical use case shapes specification requirements, with orthopedic and cardiac applications demanding distinct detector formats and software capabilities.
- Orthopedic:Extremity and spine imaging requires high spatial resolution for trabecular bone detail and metal artifact reduction for post-surgical assessment.
- Dental Imaging:Intraoral and panoramic systems serve private practice networks with distinct regulatory pathways from medical device registration.
- Cardiac Screening:Coronary angiography and stress testing protocols demand rapid frame rates and low-dose optimization algorithms.
- Oncology:Tumor staging and treatment response monitoring integrates with radiation therapy planning systems in comprehensive cancer centers.
Orthopedic applications lead procedure volume. Cardiac Screening climbs the fastest as population aging expands diagnostic surveillance protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State health networks across Australia deploy digital X-ray infrastructure with divergent procurement priorities. New South Wales and Victoria concentrate fixed-system capital expenditure in tertiary hospitals, while Queensland and Western Australia prioritize portable units for rural reach.
New South Wales
Tertiary hospitals in Sydney anchor the largest fixed-system procurement programs, driven by high-throughput radiology departments serving dense metropolitan populations. TGA device registration requirements filter tender eligibility, extending vendor qualification timelines. The Sydney Local Health District consolidates multi-site asset management agreements that span Royal Prince Alfred and Concord hospitals.
Victoria
Melbourne's major health networks accelerate replacement of legacy analog equipment with wireless detector systems. Medicare Benefits Schedule reimbursement revisions directly influence capital upgrade cycles at The Alfred and Austin Health. The Parkville biomedical precinct integrates digital imaging with research laboratory validation protocols.
Queensland
Queensland Health prioritizes portable X-ray units for aged care facilities and remote clinic networks across the state's vast geography. Wireless detector adoption eliminates tethered workflows in busy emergency departments at Royal Brisbane and Women's Hospital. State procurement frameworks operate independently from southern jurisdictions, creating parallel compliance documentation requirements.
Western Australia
Remote and rural health networks present underpenetrated demand for mobile diagnostic units with satellite connectivity requirements. The Pilbara and Kimberley regions drive point-of-care flexibility priorities over maximum resolution specifications. Perth's tertiary centers at Sir Charles Gairdner Hospital maintain fixed-system concentration while supporting outreach deployment models.
South Australia
Regional hospital budgets constrain permanent installation projects, favoring computed radiography transition systems over full digital fluoroscopy. The Flinders Medical Centre and Royal Adelaide Hospital anchor metropolitan capital programs. TGA clinical evidence standards extend registration periods for emerging manufacturers seeking South Australian Health tender eligibility.
Australia Digital X-Ray Market Competitive Environment
Capability concentration sits with diversified imaging conglomerates; scale advantage sits with established service infrastructure operators. The vendor base separates into three tiers: full-platform manufacturers with software integration capabilities, component specialists supplying detector subsystems, and regional distributors handling installation and maintenance contracts. Two strategic archetypes dominate competitive positioning—bundled asset management providers securing multi-year hospital contracts, and AI-enabled workflow specialists differentiating through radiologist productivity tools. M&A activity concentrates on software-enabled diagnostics capabilities, while geographic expansion targets Western Australia and Northern Territory health networks with mobile-first deployment models.
Among Japanese imaging conglomerates, Fujifilm Holdings Corporation and Shimadzu Corporation occupy positions emphasizing direct service infrastructure and long-term contract sustainability. GE Healthcare anchors the diversified manufacturer tier through multi-site asset management agreements spanning state health networks. Siemens Healthineers AG exemplifies the AI-integration archetype, with machine learning-enabled workflows reducing radiologist reading times in tertiary hospital deployments. These three companies represent distinct competitive vectors—service depth, scale bundling, and software differentiation—shaping procurement outcomes across Australian state health departments.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| GE Healthcare |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Siemens Healthineers AG |
| Hologic Inc |
| Agfa Healthcare |
| Carestream Health |
| Others |
Value Chain & Pricing Dynamics
Semiconductor foundry capacity constraints in East Asia determine both detector procurement premiums and the three-tier pricing structure across Australian health networks. TGA clinical evidence requirements amplify these cost pressures by filtering lower-specification imports and extending vendor qualification timelines.
Pricing Analysis
Queensland Health contracts command 15-20% premiums over South Australian regional tenders for equivalent wireless detector specifications. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated systems from conventional flat panel detectors and computed radiography retrofit units. Cost compression in the standard tier is intensifying because bundled asset management agreements consolidate procurement power within state health departments. Diagnostic imaging centers exhibit highest price sensitivity due to direct Medicare reimbursement exposure, while tertiary hospitals prioritize throughput metrics over unit economics.
Supply Chain Analysis
Amorphous selenium deposition and scintillator crystal growth feed from concentrated manufacturing bases in Japan, South Korea, and Germany. Flat panel detector assembly draws from semiconductor foundries in Taiwan and South Korea, with specialized readout integrated circuits sourced from US fabless designers. Single-source vulnerability around amorphous selenium substrates exposes procurement timelines to chemical precursor availability. Distribution runs through authorized service infrastructure operators that maintain TGA-registered device sponsor relationships across Australian state jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enabled diagnostic workflows and evolving TGA software-hardware conformity pathways are accelerating competitive disruption across Australian radiology procurement. Medicare Benefits Schedule revisions for digital procedures amplify capital cycle volatility.
For Market Incumbents: Pre-empt emerging entrant pressure by securing multi-site bundled agreements before Queensland Health and New South Wales Health consolidate independent tender frameworks. Deepen backward integration into detector subsystem servicing capabilities to capture recurring revenue streams. Invest in algorithm validation pipelines ahead of TGA digital health integration guideline finalization. For New Entrants and Emerging Players: Western Australia and Northern Territory rural health networks present the most penetrable geographic white-space for mobile diagnostic units with satellite connectivity requirements. Target aged care facility procurement outside state hospital radiology department frameworks. Pursue direct-to-facility sales models bypassing consolidated state tender processes. For Investors and Strategic Acquirers: TGA digital health integration guideline finalization reshapes the acquisition landscape by separating software-enabled diagnostic valuations from hardware platform multiples. Long-term viability centers on vendors with demonstrated algorithm validation capabilities and established state health department contract eligibility. Monitor Medicare Benefits Schedule update announcements as inflection indicators for capital expenditure cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Workflow Development | Machine learning algorithms reduce radiologist reading times at Royal Brisbane and Women's Hospital emergency departments. |
| Multi-Site Asset Management Agreement | Bundled contracts spanning Royal Prince Alfred and Concord hospitals lock in long-term service revenue capture. |
| Wireless Detector Premium Positioning | Tether-free flat panel units justify procurement premiums through compressed Queensland Health patient throughput times. |
| Remote Clinic Satellite Connectivity | Mobile diagnostic units with telemetry capabilities address Pilbara and Kimberley region point-of-care requirements. |
| TGA Software-Hardware Dual Pathway | Separate conformity assessments for AI-enabled diagnostics and detector platforms extend vendor qualification timelines. |
Study Parameters
Desk research of TGA device registration databases, Medicare Benefits Schedule historical revisions, and state health department tender documentation preceded structured interviews with hospital biomedical engineers, radiology department heads, GPO contracts managers, and medical device regulatory consultants. Primary fieldwork with Queensland Health and New South Wales Health procurement officers combined with secondary validation against hospital capital expenditure disclosures and detector manufacturer service infrastructure records. Bottom-up installation base estimates triangulated against top-down market size benchmarks derived from Medicare claims data patterns.
Assumptions held fixed across the modeling period include TGA medical device registration pathway stability and Medicare reimbursement eligibility for digital diagnostic procedures. Variables incorporated segmentation dimensions across product type, end user, technology, and application with geographic procurement framework overlays. CAGRs were derived from weighted average replacement cycle analysis and portable unit penetration trajectory modeling. Forecast inputs incorporated semiconductor foundry capacity utilization indicators and radiologist workforce pipeline projections.
Practitioners should monitor TGA digital health integration guideline evolution and Medicare Benefits Schedule update announcements for early signals of procurement cycle acceleration or delay. Forecasts reflect assumptions around state health department consolidation timelines and detector component supply chain normalization. Cross-checking against Australian Institute of Health and Welfare hospital activity statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Mammography Market
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Perfusion Radiology Market