
 Degenerative Disc Disease Treatment Market | 2026-2036
Degenerative Disc Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Degenerative Disc Disease Treatment Market Analysis
Polyetheretherketone is hardening its position against titanium in interbody fusion cages, reducing imaging artifacts and revision rates. Medtronic leverages integrated navigation systems to sustain premium positioning in cervical disc replacement. Stryker anchors its portfolio through proprietary 3D-printed porous titanium architectures that accelerate osseointegration.
Degenerative disc disease treatment encompasses surgical intervention, biologic therapy, and conservative management modalities targeting the breakdown of fibrocartilaginous spinal discs, with intervertebral disc height maintenance representing a critical functional parameter for preserving segmental biomechanics and neural decompression. The medication segment retains stable volume through oral NSAID and neuropathic pain protocols, though margin pools are migrating toward stem cell therapy as regulatory frameworks mature for autologous biologic delivery. Minimally invasive surgical approaches now compete directly with open discectomy across the lumbar segment, driven by reduced hospitalization duration and faster return-to-work profiles.
FDA 510(k) pathways and the EU Medical Device Regulation shape product commercialization timelines, with biologic classifications requiring additional clinical evidence packages that extend market access by eighteen to thirty-six months. The EU AI Act and HIPAA interoperability mandates in the United States are converging to demand predictive outcome analytics embedded within surgical planning platforms. Stakeholders must monitor reimbursement parity between motion-preserving devices and fusion constructs as value-based contracting expands across hospital purchasing consortia.
Market Dynamics
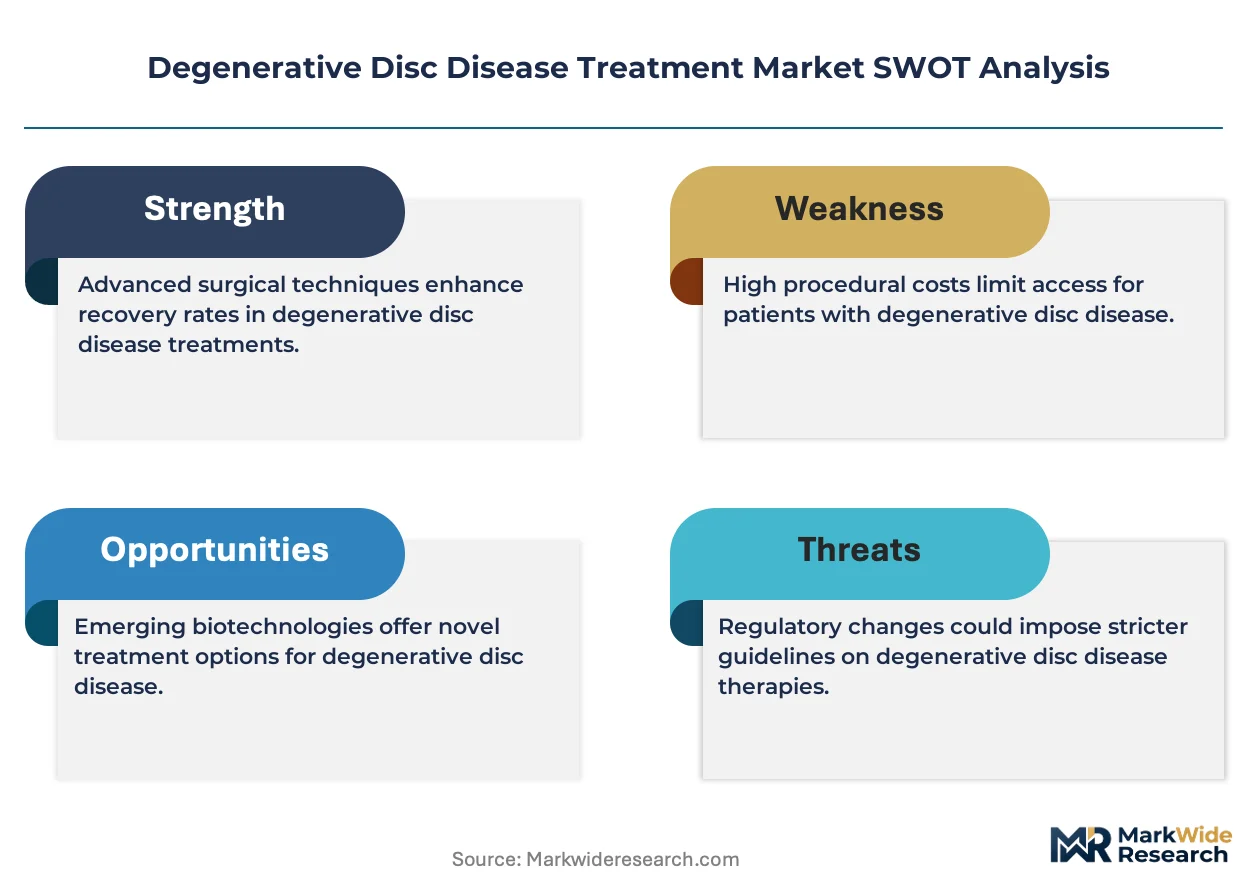
Hospital outpatient spine surgery expansion is compressing inpatient fusion volumes while biologic disc repair accelerates through shortened FDA clearance pathways, forcing device manufacturers to reconfigure revenue mix toward ambulatory-compatible platforms.
Growth Catalysts
- EU Medical Device Regulation harmonization:Streamlined conformity assessment for Class III spinal implants accelerates commercialization across Germany, France, and Italy.
- 3D-printed porous titanium:Osseointegration acceleration reduces revision rates and extends implant lifecycle economics for hospital systems.
- North American ASC expansion:Ambulatory surgery centers now capture lumbar discectomy volumes previously reserved for inpatient settings.
Market Restraints
- Biologics evidence requirements:Autologous stem cell therapies face eighteen-to-thirty-six-month clinical package extensions under FDA classification protocols.
- Titanium supply concentration:Medical-grade titanium sponge sourcing clusters in Chinese and Russian smelting operations create geopolitical exposure.
- Motion-preservation reimbursement parity gaps:Artificial disc replacement lacks procedural code equivalence with fusion constructs in US Medicare fee schedules.
Strategic Opportunities
- Underpenetrated Indian hospital segment:Corporate hospital chains in Mumbai and Delhi are installing navigation-enabled spine suites without vendor lock-in.
- EU AI Act surgical planning mandates:Predictive outcome analytics integration creates upgrade cycles for legacy navigation platforms.
- Biologic-cage hybrid convergence:Demineralized bone matrix combined with PEEK interbody devices opens premium pricing tiers.
Industry Challenges
- Interventional neuroradiologist scarcity:Minimally invasive lateral approaches require specialized training pipelines that academic medical centers cannot fill.
- HIPAA interoperability compliance:Surgical planning platforms must embed patient data exchange protocols that delay software release cycles.
- Legacy hospital IT integration:Navigation systems require PACS and EMR reconfiguration that extends sales-to-revenue timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Degenerative Disc Disease Treatment Market |
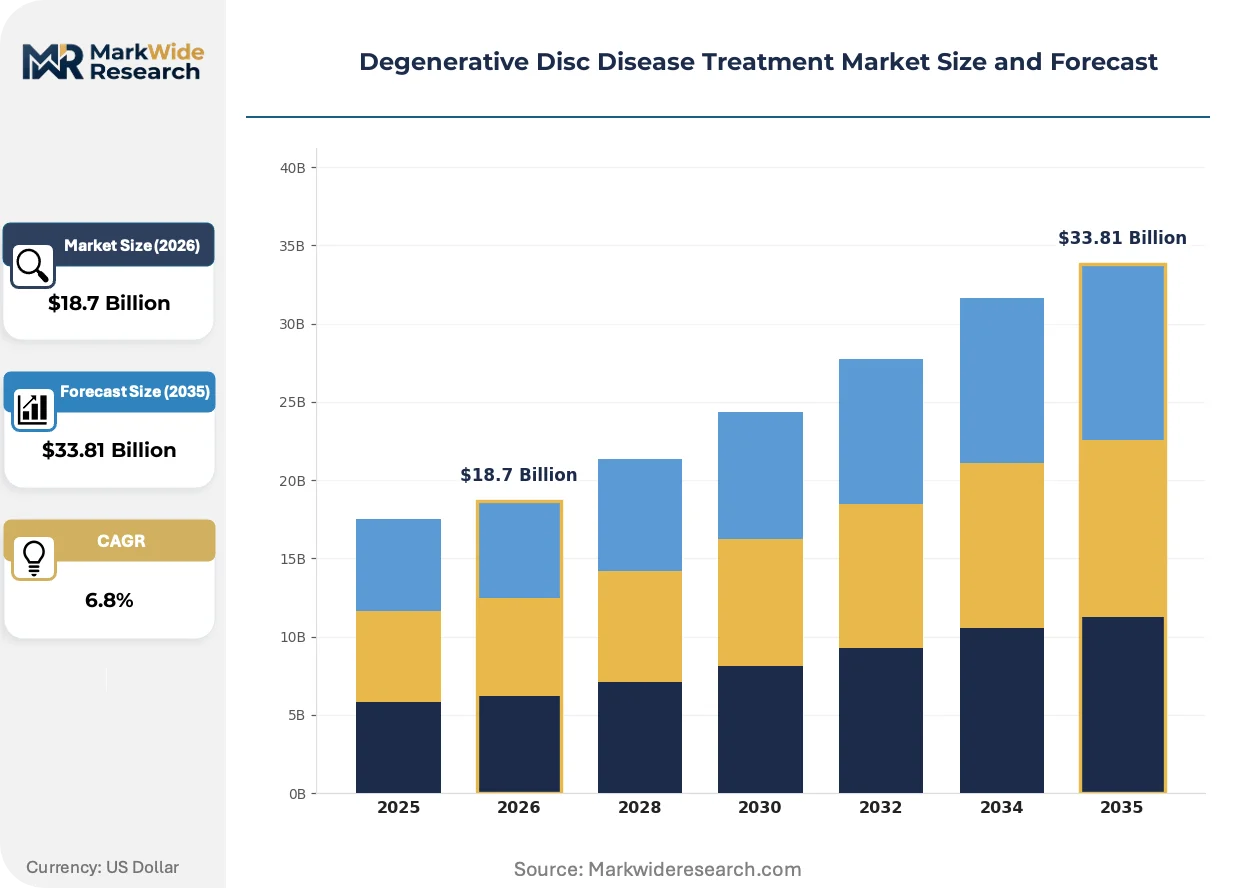
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Physical Therapy, Medication, Rehabilitation Technology: Laser Therapy, Stem Cell Therapy, Radiofrequency Ablation, Corticosteroid Injections End User: Orthopedic Clinics, Physiotherapy Centers, Hospitals, Rehab Facilities Treatment Method: Invasive, Minimally Invasive, Non-invasive, Complementary |
| Companies Covered | Medtronic, Johnson & Johnson Services, Stryker, Zimmer Biomet Holdings, Pfizer Inc., Novartis AG, Eli Lilly and Company, DiscGenics, Globus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Degenerative Disc Disease Treatment Market Emerging Trajectories
Navigation-integrated surgical platforms are displacing freehand techniques across cervical and lumbar segments, compressing the technical skill gap between high- and low-volume surgeons while elevating hardware-software bundling as the dominant commercial model.
Polyetheretherketone is consolidating its position in interbody fusion cages against titanium alternatives, reducing CT and MRI imaging artifacts that previously obscured fusion assessment. Hospital radiology departments now specify PEEK as standard to eliminate metal artifact reduction sequences. The technology is consolidating procurement specifications across integrated delivery networks that standardize implant formularies.
EU AI Act algorithmic transparency requirements are forcing surgical planning software vendors to document training data provenance and performance validation. CE marking renewals now require updated technical files demonstrating bias mitigation in predictive outcome models. European spine surgery platforms face eighteen-month recertification cycles that compress software update frequencies.
Hospital purchasing consortia are unbundling device procurement from service contracts, separating implant acquisition from navigation training and maintenance agreements. Value-based contracting pilots in US Medicare Advantage plans now tie cervical disc replacement reimbursement to ninety-day episode outcomes. This behavior concentrates in California and Texas health systems with capitated risk arrangements.
Degenerative Disc Disease Treatment Market Segmentation
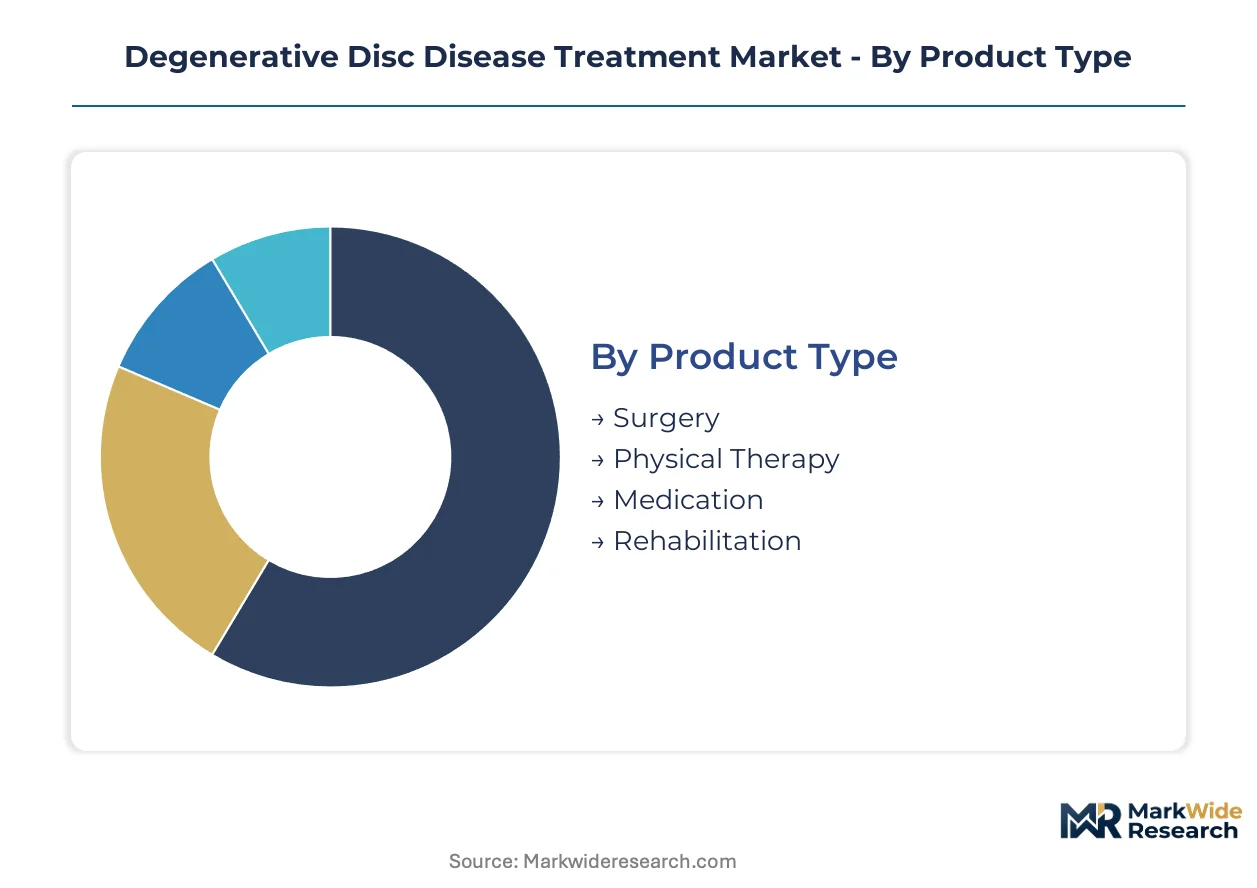
Segmentation in degenerative disc disease treatment reveals how reimbursement pathways and surgical site migration reshape commercial priorities. Each axis captures distinct purchasing behaviors, from hospital procurement of fusion hardware to outpatient clinic adoption of biologic protocols.
Product Type:
Technology specifications define clinical efficacy thresholds and reimbursement coding complexity across surgical and conservative modalities.
- Surgery:Spinal fusion, discectomy, and disc replacement procedures utilize titanium and PEEK interbody cages with integrated navigation. Demand concentrates in US hospital outpatient departments expanding ambulatory spine capacity.
- Medication:Oral NSAIDs, neuropathic pain agents, and muscle relaxants constitute first-line protocols. Prescription volumes stabilize in Germany and France while margin pools shift toward biologic alternatives under EMA frameworks.
- Physical Therapy:Structured exercise protocols and manual manipulation target functional restoration without surgical intervention.
- Rehabilitation:Postoperative recovery programs and chronic pain management integrate multidisciplinary care pathways.
Surgery leads on scale; Medication leads on momentum as biologics erode conventional pharmacology economics.
Technology:
Cost tier differentiation separates established reimbursable modalities from emerging self-pay biologics navigating regulatory evidence requirements.
- Stem Cell Therapy:Autologous and allogeneic biologic delivery targets disc regeneration through mesenchymal cell injection. FDA classification protocols extend clinical evidence timelines, compressing near-term commercialization velocity.
- Corticosteroid Injections:Epidural and facet joint steroid delivery provides intermediate-term pain relief with established CPT coding. Utilization concentrates in US ambulatory surgery centers seeking episode-based reimbursement efficiency.
- Laser Therapy:Percutaneous laser disc decompression offers tissue-sparing alternatives to open discectomy.
- Radiofrequency Ablation:Thermal denervation of medial branch nerves interrupts pain signaling for facet-mediated symptoms.
Corticosteroid Injections lead on scale; Stem Cell Therapy leads on momentum despite regulatory friction.
End User:
Customer type determines purchasing authority complexity, from centralized hospital value analysis committees to decentralized clinic decision-making.
- Hospitals:Integrated delivery networks command volume-based pricing leverage and standardize implant formularies across surgical service lines. North American systems prioritize navigation-enabled suites for outpatient migration.
- Orthopedic Clinics:Specialized spine practices drive adoption of motion-preservation devices and biologic adjuncts. German clinic chains in Munich and Hamburg install hybrid surgical platforms without vendor exclusivity.
- Physiotherapy Centers:Conservative management hubs deliver exercise-based protocols and electrophysical modalities.
- Rehab Facilities:Post-acute settings coordinate multidisciplinary recovery programs following surgical intervention.
Hospitals lead on scale; Orthopedic Clinics lead on momentum through specialized procedure concentration.
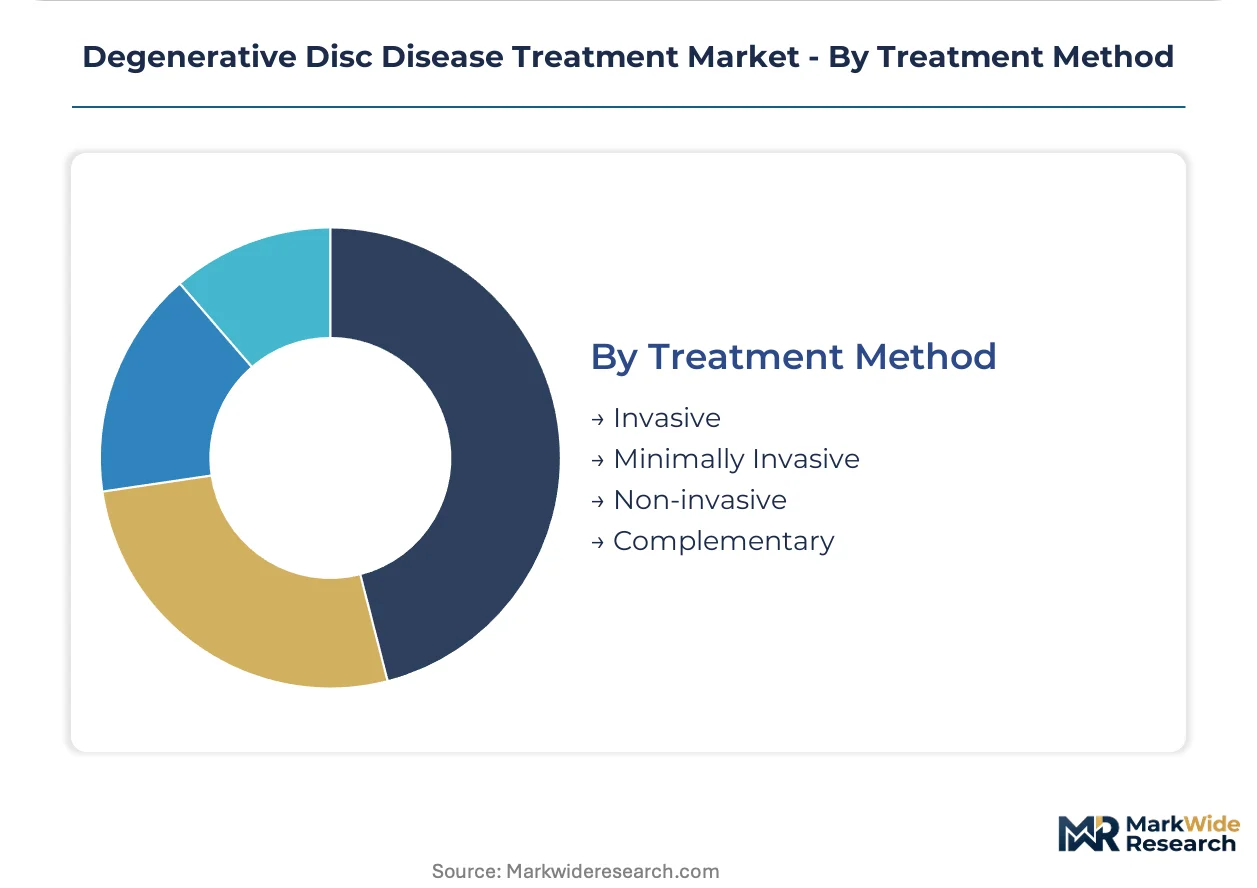
Treatment Method:
Volume distribution tracks site-of-care migration, with invasive procedures losing share to ambulatory-compatible alternatives.
- Minimally Invasive:Percutaneous and tubular approaches reduce tissue disruption and hospitalization duration. US Medicare Advantage plans in California and Texas pilot episode-based reimbursement tying payment to ninety-day outcomes.
- Invasive:Open discectomy, fusion, and disc replacement address advanced disc degeneration with established long-term efficacy data. Procedure volumes compress as outpatient alternatives capture lumbar segments.
- Non-invasive:Physical therapy, pharmacologic management, and lifestyle modification constitute first-line intervention.
- Complementary:Acupuncture, chiropractic manipulation, and mind-body techniques address patient preference for holistic approaches.
Invasive leads on scale; Minimally Invasive leads on momentum through site-of-care economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital systems anchor outpatient spine surgery migration across Europe, with Munich and Hamburg clinic chains installing navigation-enabled suites without vendor lock-in. FDA 510(k) pathways in the United States compress biologic disc repair timelines, while Japanese academic medical centers pioneer motion-preservation reimbursement pilots.
United States
California and Texas health systems drive Medicare Advantage episode-based contracting for cervical disc replacement, tying ninety-day outcomes to reimbursement. HIPAA interoperability mandates force surgical planning platforms to embed patient data exchange protocols. ASC expansion in Phoenix and Dallas captures lumbar discectomy volumes previously reserved for inpatient settings.
Germany
Corporate hospital chains in Munich, Hamburg, and Berlin standardize PEEK interbody cages across integrated delivery networks to eliminate metal artifact reduction sequences. EU Medical Device Regulation harmonization streamlines Class III spinal implant conformity assessment. The Bavarian medical technology cluster concentrates 3D-printed porous titanium manufacturing for osseointegration acceleration.
Japan
Tokyo and Osaka academic medical centers pilot motion-preservation reimbursement parity with fusion constructs under METI-guided health technology assessment frameworks. PMDA consultation pathways shorten biologic classification timelines for autologous stem cell therapies. The Kanto region concentrates navigation-integrated surgical platform adoption across high-volume spine centers.
China
Beijing-Tianjin-Hebei hospital systems expand minimally invasive lateral approach capacity despite interventional neuroradiologist scarcity. NMPA medical device registration reforms compress spinal implant approval timelines for domestic manufacturers. The Yangtze River Delta cluster in Shanghai drives procurement of biologic-cage hybrid devices combining demineralized bone matrix with PEEK interbody platforms.
India
Mumbai and Delhi corporate hospital chains install navigation-enabled spine suites without vendor exclusivity agreements, creating procurement leverage. CDSCO medical device rules tighten clinical evidence requirements for imported spinal implants. The Maharashtra medical device corridor concentrates domestic manufacturing of titanium interbody cages for cost-competitive regional supply.
Degenerative Disc Disease Treatment Market Vendor Landscape
Global majors compete with regional champions across navigation-integrated surgical platforms and biologic disc repair modalities. The vendor base organizes around three tiers: diversified medtech conglomerates with spine-dedicated divisions, mid-cap orthopedic specialists with motion-preservation focus, and emerging biologic therapy developers navigating FDA classification protocols. Dominant competitive moves include hardware-software bundling for surgical navigation systems and strategic partnerships between implant manufacturers and academic medical centers for clinical evidence generation.
Within the diversified medtech tier, Medtronic and Stryker occupy positions defined by integrated navigation ecosystems and proprietary 3D-printed porous titanium architectures respectively. Johnson & Johnson Services exemplifies the pharmaceutical-device hybrid archetype through its convergence of biologic therapy pipelines with surgical implant portfolios. Among mid-cap orthopedic specialists, Globus Medical represents the navigation-native challenger position, while Zimmer Biomet Holdings anchors the reconstructive spine segment with historical fusion hardware strength. DiscGenics sits within the emerging biologic therapy developer category, navigating eighteen-to-thirty-six-month clinical evidence timelines for autologous stem cell delivery platforms.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson Services |
| Stryker |
| Zimmer Biomet Holdings |
| Pfizer Inc. |
| Novartis AG |
| Eli Lilly and Company |
| DiscGenics |
| Globus Medical |
| Others |
Supply Flow & Price Mechanics
3D-printed porous titanium manufacturing consolidation simultaneously compresses per-unit production economics and concentrates supply leverage among Bavarian and Yangtze River Delta production clusters. This dual compression forces implant manufacturers to renegotiate volume commitments or absorb margin erosion.
Pricing Analysis
Medical-grade titanium sponge pass-through from Chinese and Russian smelting operations compresses margin buffers for interbody cage manufacturers. Three-tier pricing structure across premium navigation-integrated platforms, standard PEEK cages, and economy titanium constructs reflects FDA 510(k) clearance tier and hospital GPO volume scale. Pricing pressure stems from Medicare Advantage episode-based contracting in California and Texas. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with capitated risk arrangements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Russian medical-grade titanium sponge smelting operations that feed German and US forging facilities. Raw material dependencies include titanium sponge, polyetheretherketone resin, and demineralized bone matrix. Tariff exposure concentrates on implant-grade titanium imports under Section 301 provisions. Distribution runs through hospital purchasing consortia and GPO contracts that bundle navigation systems with disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The degenerative disc disease treatment market compounds steadily as aging demographics expand the addressable surgical population across OECD healthcare systems. Biologic disc repair maturation and ambulatory site-of-care migration sustain procedure volume growth.
For Market Incumbents: Deepen backward integration into 3D-printed porous titanium manufacturing to offset raw material concentration risk from Chinese and Russian smelters. Expand navigation-enabled outpatient platform deployment in Phoenix and Dallas ASC markets to capture lumbar discectomy volumes migrating from inpatient settings. Fortify GPO contract renewals before biologic-cage hybrid competitors achieve FDA 510(k) clearance.
For New Entrants and Emerging Players: Corporate hospital chains in Mumbai and Delhi represent the most penetrable buyer archetype, as these systems install navigation-enabled spine suites without vendor exclusivity agreements. Target motion-preservation device segments where Medicare reimbursement parity gaps still disadvantage established artificial disc replacement portfolios. Pursue CDSCO registration pathway for cost-competitive titanium interbody cages to serve Maharashtra manufacturing corridor demand.
For Investors and Strategic Acquirers: Valuations sit cheapest among emerging biologic therapy developers navigating eighteen-to-thirty-six-month FDA clinical evidence timelines. Long-term viability favors platforms with demonstrated osseointegration acceleration and ambulatory-compatible surgical workflows. Watch for EU AI Act recertification completion as inflection signal for surgical planning software upgrade cycle revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathway compression accelerates biologic-cage hybrid commercialization timelines. |
| CE Marking Pathway | EU MDR harmonization streamlines Class III spinal implant conformity assessment across Germany. |
| Hospital System Partnership | California and Texas Medicare Advantage pilots tie cervical disc replacement to episode outcomes. |
| Software Companion Development | EU AI Act mandates predictive outcome analytics integration for surgical planning platforms. |
| Reimbursement Strategy | Motion-preservation parity with fusion constructs unlocks Medicare fee schedule expansion. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation. Primary fieldwork triangulates against FDA 510(k) filings, EMA submission databases, hospital procurement records, and CMS Medicare claims data. Bottom-up procedure volume estimates reconcile with top-down implant manufacturer revenue disclosures.
Granularity-level modeling captures product type, technology tier, end-user channel, and treatment method invasiveness at country-level resolution across the projection horizon. CAGRs derive from procedure volume trajectories, reimbursement pathway evolution, and technology substitution elasticities. Forecast inputs incorporate navigation system adoption curves, biologic therapy regulatory clearance timelines, and ambulatory surgery center capacity expansion plans.
Underlying measurement precision varies by segment; surgical procedure volumes carry tighter precision than emerging stem cell therapy penetration estimates. Forecasts reflect assumptions on FDA classification protocol stability, EU MDR implementation consistency, and titanium supply chain continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Mesotherapy Guns Market