
 Mesotherapy Guns Market | 2026-2036
Mesotherapy Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Mesotherapy Guns Market Insights
The gap between premium automatic guns and basic manual injectors is expanding as clinical outcomes data splits the installed base. MI Medical Innovation leverages European CE marking to anchor its high-precision electroporation devices in regulated clinics. PERFECTLASER competes on manufacturing scale across Asian beauty salon channels. Foshan Nanhai Newface Beauty Instrument Technology Co., Ltd. dominates domestic supply through cost-optimized manual gun production.
Mesotherapy guns are spring-loaded or motorized injection systems that deliver active compounds into the mesodermal skin layer at depths between 0.5 mm and 4.0 mm, primarily for localized drug delivery and aesthetic tissue remodeling. Automatic guns with programmable depth and dosage controls command the highest unit margins in professional settings. Needle-free ultrasonic technology is capturing the fastest expansion in home-user segments where safety concerns limit penetration devices. Hair restoration applications sustain premium pricing through protocol complexity and repeat session requirements.
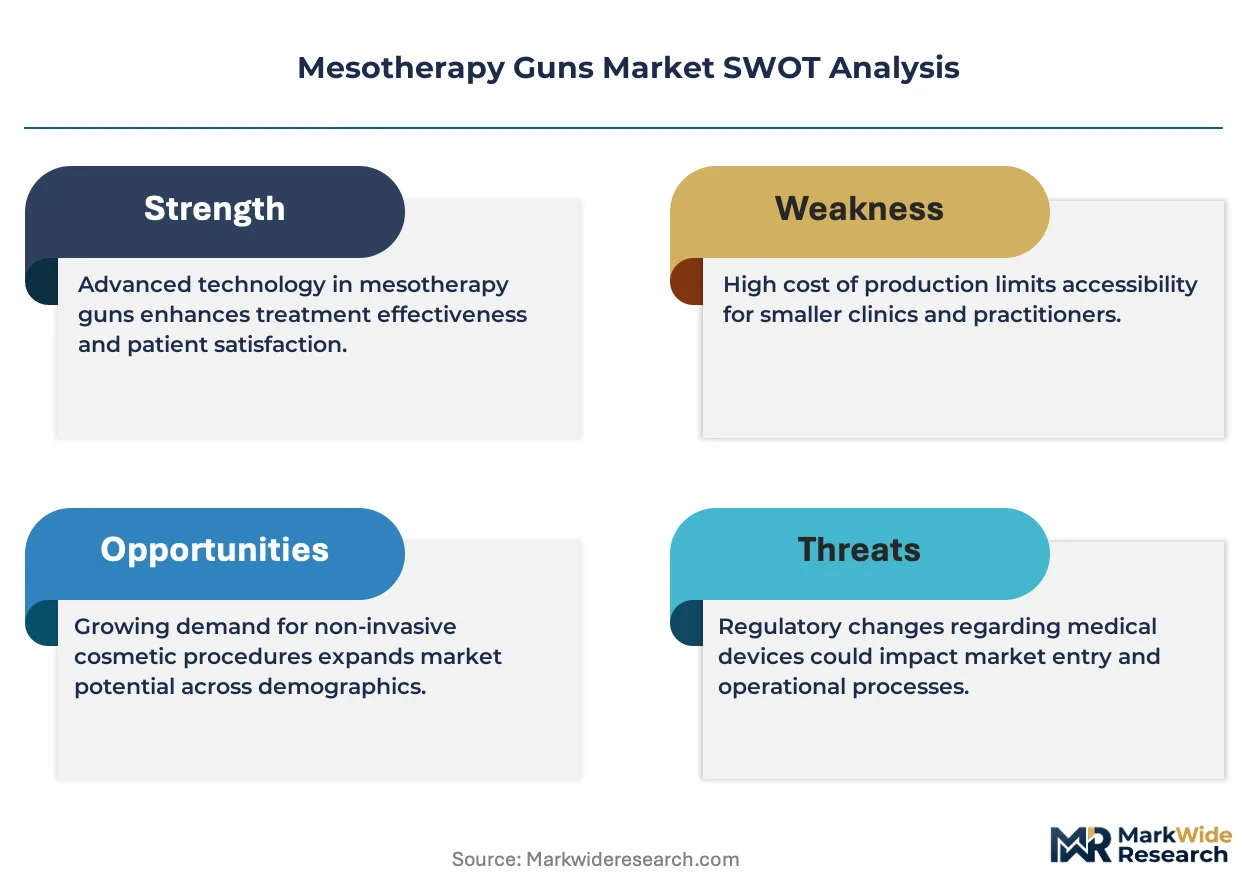
FDA Class II device regulations and the EU MDR framework impose clinical evidence thresholds that filter out uncertified manufacturers from OECD markets. China's NMPA and South Korea's MFDS maintain separate approval tracks that delay cross-border product launches by twelve to twenty-four months. Stakeholders must monitor divergence between regional efficacy standards and reimbursement eligibility for medical versus cosmetic indications.
Market Dynamics
The divergence between needle-free ultrasonic platforms and spring-loaded penetration devices is fragmenting clinical procurement standards across aesthetic medicine. This technology schism forces manufacturers to maintain dual R&D tracks while clinics recalibrate staff training protocols.
Growth Catalysts
- EU MDR framework:Stricter clinical evidence requirements for Class IIa devices are filtering out uncertified competitors and elevating pricing power for CE-marked manufacturers in regulated European markets.
- Hair restoration protocols:Complex multi-session treatment regimens for androgenetic alopecia sustain premium device utilization rates and recurring consumable revenue streams in trichology clinics.
- Gangnam medical district:Concentrated demand from Seoul's aesthetic corridor validates high-throughput automatic gun configurations and drives regional product development priorities.
Market Restraints
- Piezoelectric actuator costs:Precision motorization components for programmable depth control inflate bill-of-materials by 40-60% versus manual alternatives, compressing margins at mid-tier price points.
- Guangdong supply concentration:Domestic Chinese manufacturers cluster in Foshan's Nanhai district, creating single-source vulnerability for manual gun chassis and disposable needle cartridges.
- MFDS-NMPA regulatory divergence:Separate approval tracks between South Korea and China delay cross-border launches by twelve to twenty-four months, fragmenting product roadmaps.
Strategic Opportunities
- São Paulo aesthetic corridor:Brazil's ANVISA regulatory pathway offers faster market access than FDA or EU MDR for Class II devices, creating a beachhead for Latin American expansion.
- Home-use needle-free segments:Ultrasonic transdermal delivery systems bypass safety concerns that limit penetration devices in consumer channels, unlocking direct-to-patient revenue models.
- ISO 13485 certification arbitrage:Quality management system standardization enables qualified manufacturers to accelerate multi-jurisdictional registrations and reduce compliance overhead.
Industry Challenges
- Electroporation technician training:Needle-free platforms require distinct competency profiles from traditional mesotherapy practitioners, extending onboarding cycles and elevating labor costs.
- Legacy device compatibility:Clinics with installed bases of spring-loaded guns face capital write-down pressures when upgrading to motorized or ultrasonic systems, slowing replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesotherapy Guns Market |
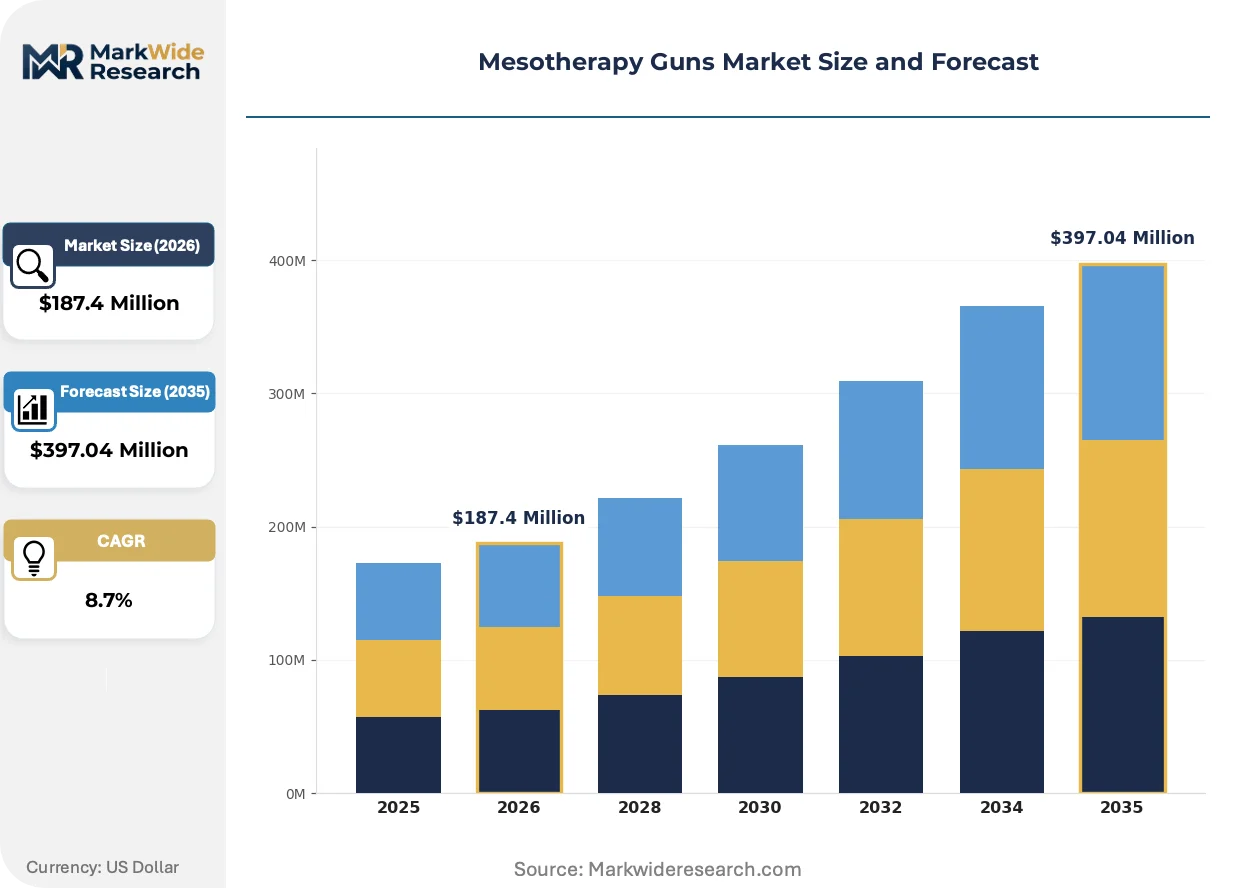
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Guns, Automatic Guns, Electroporation Devices, Injector Pens End User: Clinics, Hospitals, Home Users, Beauty Salons Application: Anti-Aging Treatments, Hair Restoration, Cellulite Reduction, Pain Management Technology: Microneedling, Ultrasonic, Laser-Assisted, Needle-Free |
| Companies Covered | MI Medical Innovation, PERFECTLASER, Foshan Nanhai Newface Beauty Instrument Technology Co., Ltd., Leadergun, ADSS, Mesoskinline, SEA HEART, Vital Injector, Beijing DALI Beauty Technology CO., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesotherapy Guns Market Trends and Innovations
Active compound delivery precision is becoming the primary competitive battleground as clinicians demand reproducible outcomes across variable tissue densities. This shift favors programmable electromechanical systems over manual operator skill.
Electroporation-assisted transdermal delivery is electrifying the competitive landscape for facial rejuvenation applications. Seoul's Gangnam district clinics are adopting these platforms at three times the rate of European markets. The technology is compressing the addressable market for conventional needle-based devices in premium settings while expanding total procedure volumes through reduced patient downtime concerns.
EU MDR clinical evidence thresholds are restructuring the competitive field for aesthetic device manufacturers. Documentation requirements for biocompatibility and electrical safety testing have extended registration timelines by eight to fourteen months. Automatic gun categories with programmable dosage controls face the steepest compliance burdens, favoring established CE-marked incumbents over new market entrants.
Clinic procurement committees are consolidating vendor relationships around full-protocol suppliers rather than discrete device vendors. This pattern displaces standalone gun manufacturers in favor of integrated aesthetic platform providers across Germany's private clinic networks. The shift is most pronounced in dermatology chains operating across North Rhine-Westphalia and Bavaria, where standardization across branch locations overrides unit-cost optimization.
Mesotherapy Guns Market Segmentation
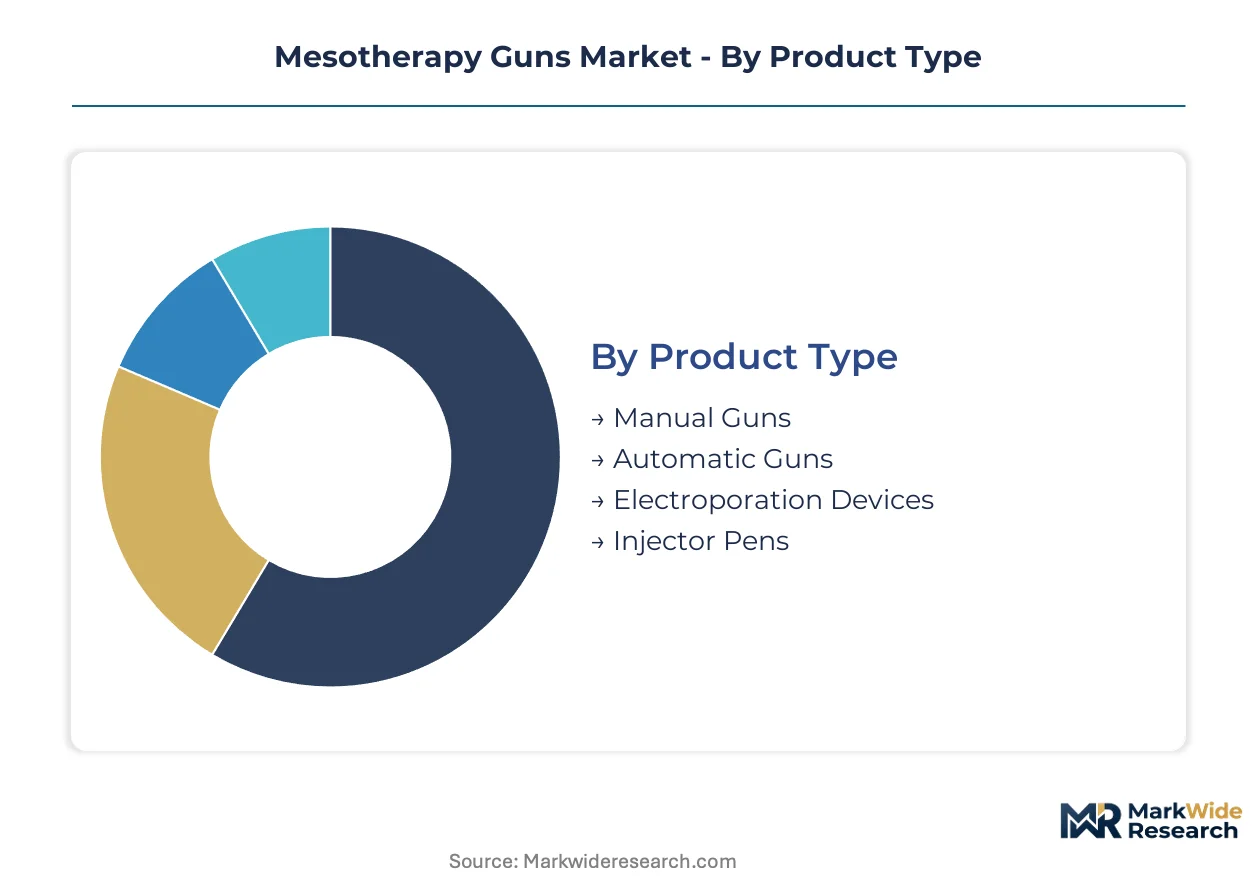
Procurement committees in aesthetic medicine prioritize precision dosing and regulatory certification over unit cost when selecting mesotherapy delivery systems. Segmentation reveals how clinical outcome requirements split demand across manual, motorized, and needle-free platforms.
Product Type:
Capital expenditure thresholds and procedure volume determine facility-level purchasing decisions across the four product categories.
- Automatic Guns:Motorized systems with programmable depth and dosage controls command premium positioning in high-throughput dermatology settings. Seoul's Gangnam medical district validates these configurations for facial rejuvenation protocols requiring reproducible tissue penetration.
- Manual Guns:Spring-loaded mechanical injectors dominate cost-sensitive channels through simplified maintenance and lower consumable overhead. Foshan's Nanhai district manufacturers supply chassis and disposable cartridges that anchor pricing in beauty salon segments.
- Electroporation Devices:Electrical pulse-based transdermal systems bypass needle safety concerns in consumer-facing applications.
- Injector Pens:Handheld precision tools target podiatric and ophthalmic subspecialties requiring micro-dosing accuracy.
Volume sits with Manual Guns; growth tilts toward Electroporation Devices.
End User:
Regulatory jurisdiction and reimbursement eligibility create distinct procurement patterns across the four customer types.
- Clinics:Private dermatology and aesthetic medicine practices drive specification requirements for programmable devices with clinical evidence packages. Germany's North Rhine-Westphalia clinic networks consolidate vendor relationships around full-protocol suppliers rather than standalone gun manufacturers.
- Beauty Salons:Non-medical aesthetic service providers prioritize needle-free ultrasonic platforms to circumvent device operator licensing requirements. São Paulo's aesthetic corridor channels expanding demand through ANVISA's accelerated Class II pathway.
- Hospitals:Institutional procurement committees impose ISO 13485 certification and biocompatibility documentation thresholds that filter out uncertified manufacturers.
- Home Users:Direct-to-patient segments concentrate in ultrasonic transdermal systems where safety concerns limit penetration device adoption.
Revenue concentrates in Clinics; expansion accelerates fastest in Home Users.
Application:
Treatment protocol complexity and session frequency determine device utilization rates and consumable attach rates.
- Hair Restoration:Multi-session regimens for androgenetic alopecia sustain premium device utilization through recurring cartridge revenue. Trichology clinics in Brazil and South Korea anchor demand for precision dosing systems that minimize scalp trauma across repeated treatments.
- Anti-Aging Treatments:Facial rejuvenation protocols favor electroporation and ultrasonic platforms that reduce patient downtime concerns. Gangnam district adoption rates for needle-free facial applications exceed European benchmarks by substantial margins.
- Cellulite Reduction:Body contouring applications require deeper penetration depths that favor motorized gun configurations with adjustable 2.0-4.0 mm settings.
- Pain Management:Musculoskeletal and neuropathic indications drive hospital-based procurement of multi-needle array systems for local anesthetic delivery.
Procedure volume clusters in Anti-Aging Treatments; value capture peaks in Hair Restoration.
Technology:
Clinical evidence requirements and technician training burdens fragment adoption across the four delivery mechanisms.
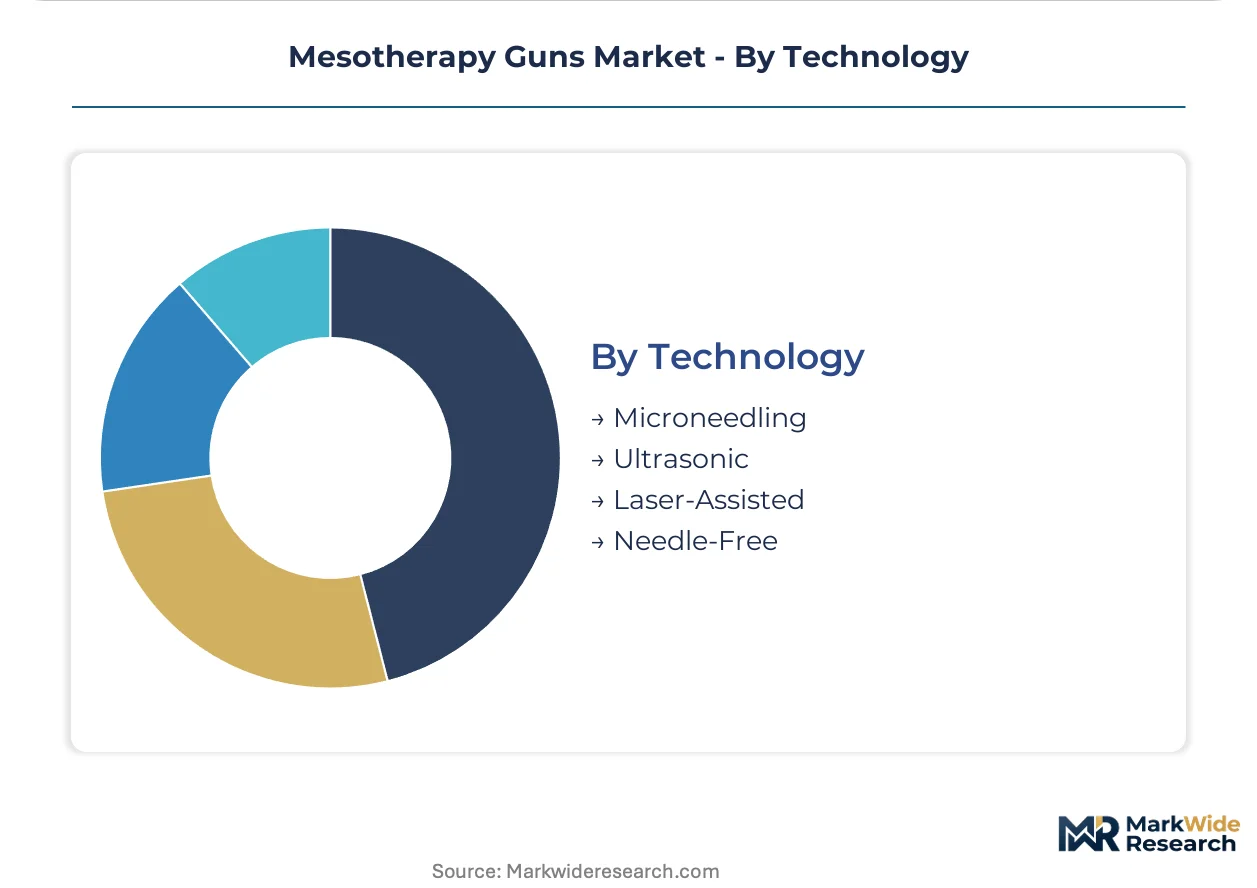
- Needle-Free:Ultrasonic and electroporation platforms bypass penetration safety concerns while expanding addressable procedure volumes. EU MDR clinical evidence thresholds for electrical safety testing extend registration timelines, favoring established CE-marked incumbents.
- Microneedling:Percutaneous collagen induction protocols sustain demand in scar revision and texture improvement applications. MFDS and NMPA regulatory divergence delays cross-border launches for Korean and Chinese manufacturers.
- Ultrasonic:Acoustic wave-based transdermal delivery captures fastest expansion in home-use segments where patient self-administration limits invasive device acceptance.
- Laser-Assisted:Photomechanical disruption technologies occupy niche positioning in pigmentation and vascular lesion adjunct therapies.
Installed base concentrates in Microneedling; adoption momentum favors Needle-Free platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam medical district concentrates the highest density of mesotherapy gun deployments worldwide, with clinics adopting programmable electroporation systems at rates exceeding European benchmarks. This Korean corridor validates automatic gun configurations that subsequently penetrate Brazilian and German markets through demonstration effects. Regulatory divergence across FDA, EU MDR, and Asian tracks fragments product launch sequencing.
United States
FDA Class II device pathways for aesthetic delivery systems impose eight-to-fourteen month documentation timelines that favor established registrants with predicate device histories. California's Los Angeles and Beverly Hills clinic clusters drive specification requirements for programmable dosage controls in facial rejuvenation applications. The agency's tightening biocompatibility testing standards filter out uncertified manufacturers from institutional procurement channels.
Germany
EU MDR framework extensions for Class IIa electromechanical devices elevate clinical evidence thresholds that consolidate vendor relationships around full-protocol suppliers. North Rhine-Westphalia dermatology chains standardize procurement across branch locations, displacing standalone gun manufacturers. Bavaria's private clinic networks anchor demand for ISO 13485-certified systems with integrated consumable supply agreements.
South Korea
MFDS maintains separate approval tracks from Chinese and European regulators that delay cross-border launches by twelve-to-twenty-four months for domestic manufacturers. Seoul's Gangnam district aesthetic corridor generates concentrated demand for high-throughput automatic configurations. Busan-Ulsan medical device fabrication clusters supply precision motorization components for programmable depth control systems.
Brazil
ANVISA's accelerated Class II pathway offers faster market access than FDA or EU MDR, creating a beachhead for Latin American expansion strategies. São Paulo's aesthetic corridor channels expanding demand for needle-free ultrasonic platforms in non-medical service settings. The regulator's streamlined documentation requirements attract manufacturers seeking to validate products before OECD market submissions.
China
NMPA maintains distinct efficacy standards from MFDS and FDA tracks that fragment product roadmaps for cross-border manufacturers. Foshan's Nanhai district concentrates domestic manual gun chassis and disposable needle cartridge production. The Pearl River Delta manufacturing cluster supplies cost-optimized electromechanical systems for beauty salon distribution channels.
Mesotherapy Guns Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and programmable precision capabilities. Automatic gun categories with CE marking and FDA registration command pricing power in regulated clinics, while manual injectors compete on manufacturing scale in unlicensed channels. Three archetypes dominate: European precision-device specialists, Asian scale manufacturers, and integrated aesthetic platform providers. Competitive moves concentrate on geographic certification arbitrage and vertical control over consumable cartridge supply.
Among Asian fabricators, Foshan Nanhai Newface Beauty Instrument Technology Co., Ltd. and Beijing DALI Beauty Technology CO., Ltd. occupy positions within cost-optimized manual production tiers. MI Medical Innovation exemplifies the European precision-device archetype through CE-marked positioning. PERFECTLASER represents scale-driven manufacturing configurations serving beauty salon distribution networks.
| Leading Market Players |
|---|
| MI Medical Innovation |
| PERFECTLASER |
| Foshan Nanhai Newface Beauty Instrument Technology Co., Ltd. |
| Leadergun |
| ADSS |
| Mesoskinline |
| SEA HEART |
| Vital Injector |
| Beijing DALI Beauty Technology CO., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Precision electromechanical assembly skills in South Korea's Busan-Ulsan corridor anchor labor-cost differentials that widen pricing spreads between premium automatic configurations and basic manual alternatives. CE-marked European manufacturers exploit this gap through value-based positioning while Foshan-based fabricators compress entry-tier economics through simplified chassis production.
Pricing Analysis
Throughput-linked value capture anchors pricing for programmable automatic guns serving high-session Gangnam clinics, with three-tier pricing structure across premium, standard, and economy levels. CE marking and FDA registration tiers separate premium European precision-device specialists from uncertified Asian commodity suppliers. Cost compression in manual injector segments intensifies because of Foshan supply concentration and beauty salon channel price sensitivity. Hospital procurement committees exhibit lowest price sensitivity, prioritizing ISO 13485 certification and clinical evidence packages over unit economics.
Supply Chain Analysis
Refurbishment flows for precision motorization components create secondary supply channels that extend equipment lifecycle and delay replacement demand in European clinic networks. Component sourcing draws from South Korea for piezoelectric actuators, China for manual gun chassis, and Germany for precision dosing mechanisms. Single-source vulnerability concentrates in Foshan's Nanhai district for disposable needle cartridges. Distribution runs through integrated aesthetic platform providers consolidating vendor relationships across Germany's North Rhine-Westphalia clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mesotherapy Guns Market is becoming a vertical-integration race as manufacturers pursue captive control over consumable cartridge supply to secure recurring revenue streams and lock in clinic procurement relationships.
For Market Incumbents: Deploy certification depth as a competitive moat by accelerating EU MDR technical documentation and MFDS-NMPA dual-track submissions ahead of regulatory divergence widening. Consolidate position through exclusive supply agreements with Gangnam and São Paulo aesthetic corridor clinics facing needle-free platform substitution threats. Backward integration into precision actuator production reduces exposure to Busan-Ulsan component price volatility. For New Entrants and Emerging Players: Launch via ANVISA's accelerated Class II pathway to establish Brazilian beachhead validation before OECD regulatory submissions. Home-use needle-free ultrasonic segments offer the most penetrable white space, bypassing clinician licensing barriers that constrain penetration device adoption. Direct-to-patient digital channels enable margin capture outside traditional clinic distribution networks. For Investors and Strategic Acquirers: Re-rating potential sits with integrated aesthetic platform providers given clinic procurement consolidation favoring full-protocol suppliers over standalone gun manufacturers. Five-to-ten year viability hinges on consumable attach rates and regulatory certification breadth rather than hardware unit economics. Monitor MFDS-NMPA harmonization negotiations as inflection signal for cross-border product roadmap consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR documentation investments filter uncertified competitors from North Rhine-Westphalia clinic networks. |
| Consumable Cartridge Supply Integration | Captive needle cartridge production locks in recurring revenue from hair restoration protocol repeat sessions. |
| ANVISA Pre-Market Validation | Brazilian regulatory clearance creates demonstrable predicate for subsequent FDA and EU MDR submissions. |
| Needle-Free Platform R&D Expansion | Ultrasonic transdermal development captures home-user segments where safety concerns limit penetration devices. |
| Hospital System Partnership Development | ISO 13485-certified system placements secure institutional procurement committee vendor consolidation benefits. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, ANVISA registration databases, and MFDS approval records, complemented by interviews with dermatology clinic procurement directors, biomedical engineers at hospital systems, GPO contracts managers, and aesthetic device distribution channel heads. Secondary validation drew from customs trade data for mesotherapy gun imports, SEC 10-K disclosures of listed medical device manufacturers, and hospital procurement database extracts. Bottom-up facility-level demand modeling triangulated against top-down market sizing across the analysis window.
Historical shipment data cross-referenced against clinician panel input on protocol adoption rates shaped the analytical framework. Segmentation dimensions modeled include product type (automatic, manual, electroporation, injector pen), end user (clinic, beauty salon, hospital, home user), application (hair restoration, anti-aging, cellulite reduction, pain management), and technology platform (needle-free, microneedling, ultrasonic, laser-assisted). CAGRs derived from curve-fitting procedure volume growth against equipment replacement cycles and consumable attach rate assumptions. Forecast inputs incorporated regulatory approval timeline divergence and needle-free technology substitution elasticity.
The model assumes a particular technology adoption path; alternative pathways for electroporation platform uptake would alter the outlook if patient downtime concerns diminish or clinician training barriers persist. Forecasts reflect underlying assumptions about ANVISA pathway efficiency and EU MDR documentation timeline extensions. Practitioners should monitor MFDS-NMPA regulatory harmonization progress and needle-free device clinical evidence publication rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
North America Regenerative Medicines Market