
 Epidermal Cell Sheets Market | 2026-2036
Epidermal Cell Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Epidermal Cell Sheets Market Analytics
The capability gap between vertically integrated tissue engineering specialists and pure-play distributors is collapsing. Japan Tissue Engineering Co., Ltd. leverages in-house stem cell culturing infrastructure to anchor domestic supply chains for autologous sheet production. Vericel Corporation sustains manufacturing scale advantages through dedicated facilities serving North American burn centers. Organogenesis Holdings Inc. competes on commercial breadth across wound healing and surgical applications.
Epidermal cell sheets comprise stratified keratinocyte layers cultured on dermal scaffolds or synthetic substrates, typically achieving 0.2–0.4 mm thickness sufficient for re-epithelialization of partial and full-thickness wounds. These constructs serve primarily as permanent skin replacements in burn reconstruction and chronic wound management. Autologous cell sheets command premium positioning due to immunological compatibility and permanent engraftment outcomes, while allogeneic alternatives address urgent cases where patient biopsy timelines are prohibitive. Stem cell culturing technology leads commercial deployment, though 3D bioprinting is gaining traction for complex anatomical graft geometries.
The FDA's regenerative medicine advanced therapy pathway and EMA's quality guidelines for cell-based medicinal products shape clinical development timelines and manufacturing standards across jurisdictions. Japan's PMDA oversees domestic sheet therapies through the Sakigake designation system, accelerating market access for innovative autologous products. Stakeholders must monitor evolving reimbursement frameworks for advanced wound care, as payer decisions on cell-based graft coverage will determine hospital procurement thresholds and manufacturer commercial viability.
Market Dynamics
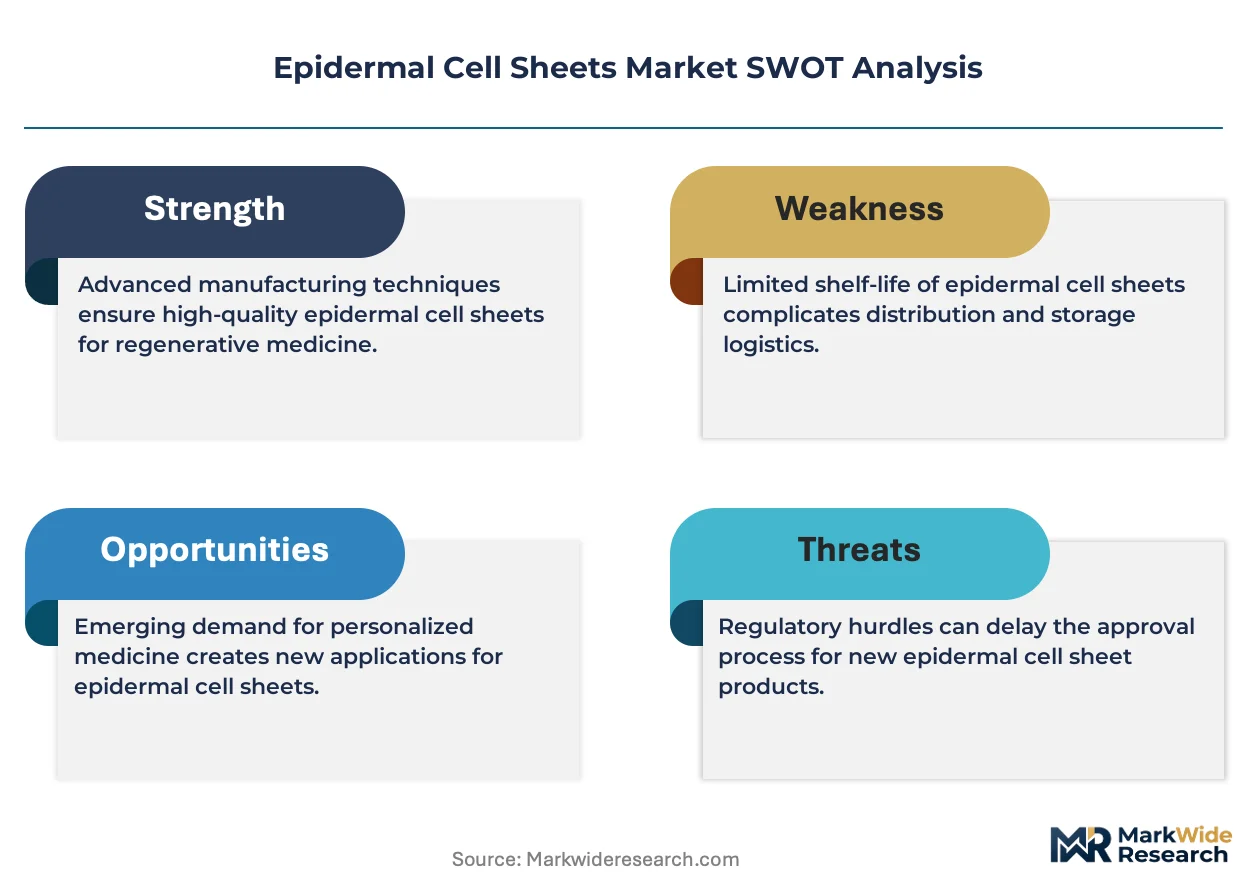
Manufacturing scale constraints in autologous cell sheet production are forcing burn centers to consolidate procurement around vertically integrated suppliers with captive culturing infrastructure.
Growth Catalysts
- FDA regenerative medicine advanced therapy designation:The pathway compresses clinical trial timelines for cell-based skin products, accelerating commercial access for severe burn indications.
- Japan's national health insurance reimbursement:Autologous epidermal sheet grafting coverage drives hospital procurement volumes and anchors domestic demand concentration.
- Stem cell culturing automation:Closed-system bioreactors reduce contamination risk and expand batch consistency for keratinocyte expansion protocols.
Market Restraints
- Donor tissue supply volatility:Allogeneic sheet production depends on neonatal foreskin procurement, creating input cost instability and ethical sourcing constraints.
- EMA quality guidelines for cell-based medicinal products:Manufacturing compliance requirements extend facility qualification timelines and elevate capital intensity for European market entry.
- Cryopreserved allograft substitution:Matriderm and Integra Dermal Regeneration Template address urgent wound coverage without patient biopsy delays, capturing price-sensitive cases.
Strategic Opportunities
- Pediatric burn applications:Limited donor sites in children create unmet need for expanded autologous sheet surface area, opening specialized clinical segments.
- 3D bioprinting convergence with microfluidic patterning:Layered deposition of keratinocytes and melanocytes enables complex anatomical geometries for facial reconstruction.
- US burn center network consolidation:American Burn Association verification programs concentrate purchasing authority at verified centers, streamlining vendor qualification.
Industry Challenges
- Good Manufacturing Practice cell therapy expertise:Shortage of qualified personnel for aseptic processing and quality control creates hiring bottlenecks at expansion facilities.
- Biopsy-to-graft logistics coordination:Two-week autologous production windows require precise scheduling between operating rooms and manufacturing sites, with temperature-controlled transport failures risking batch loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epidermal Cell Sheets Market |
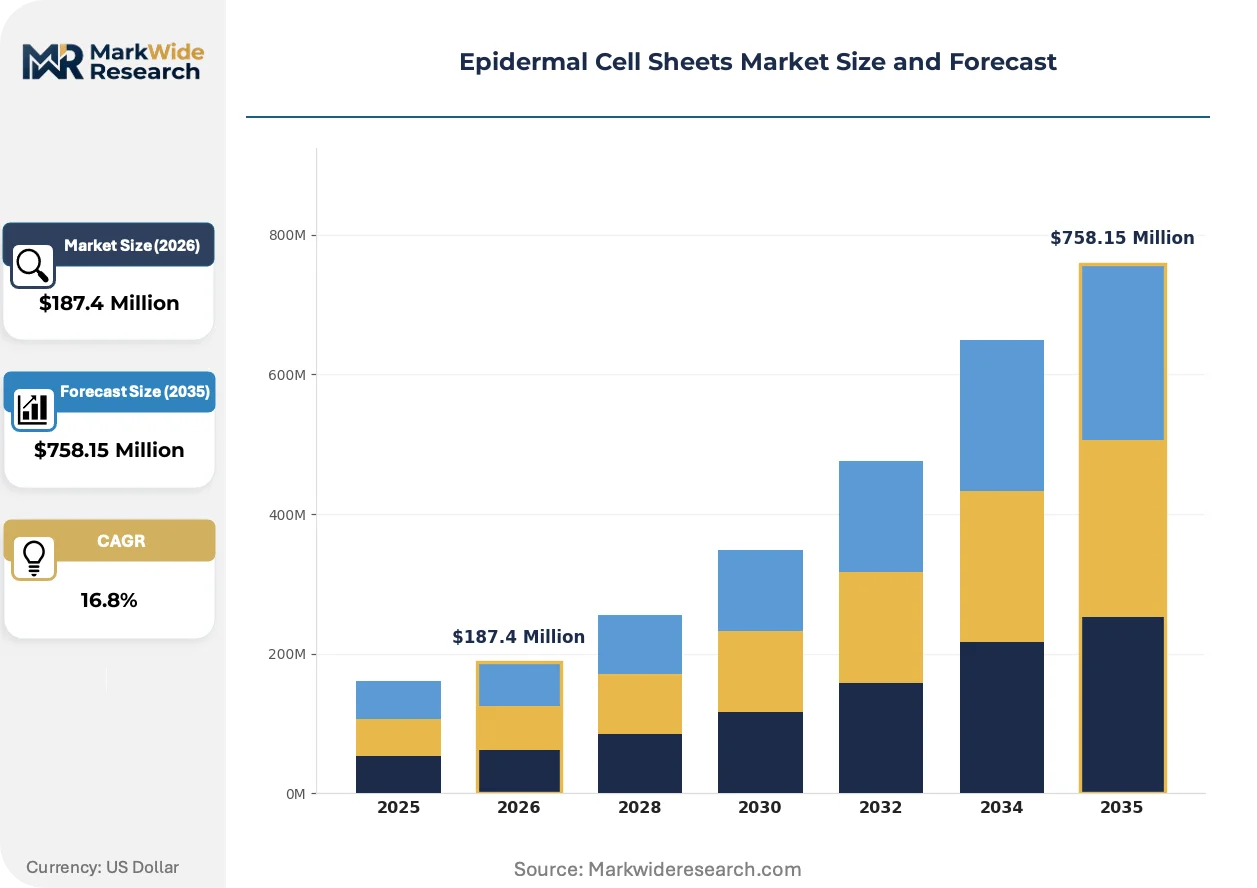
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
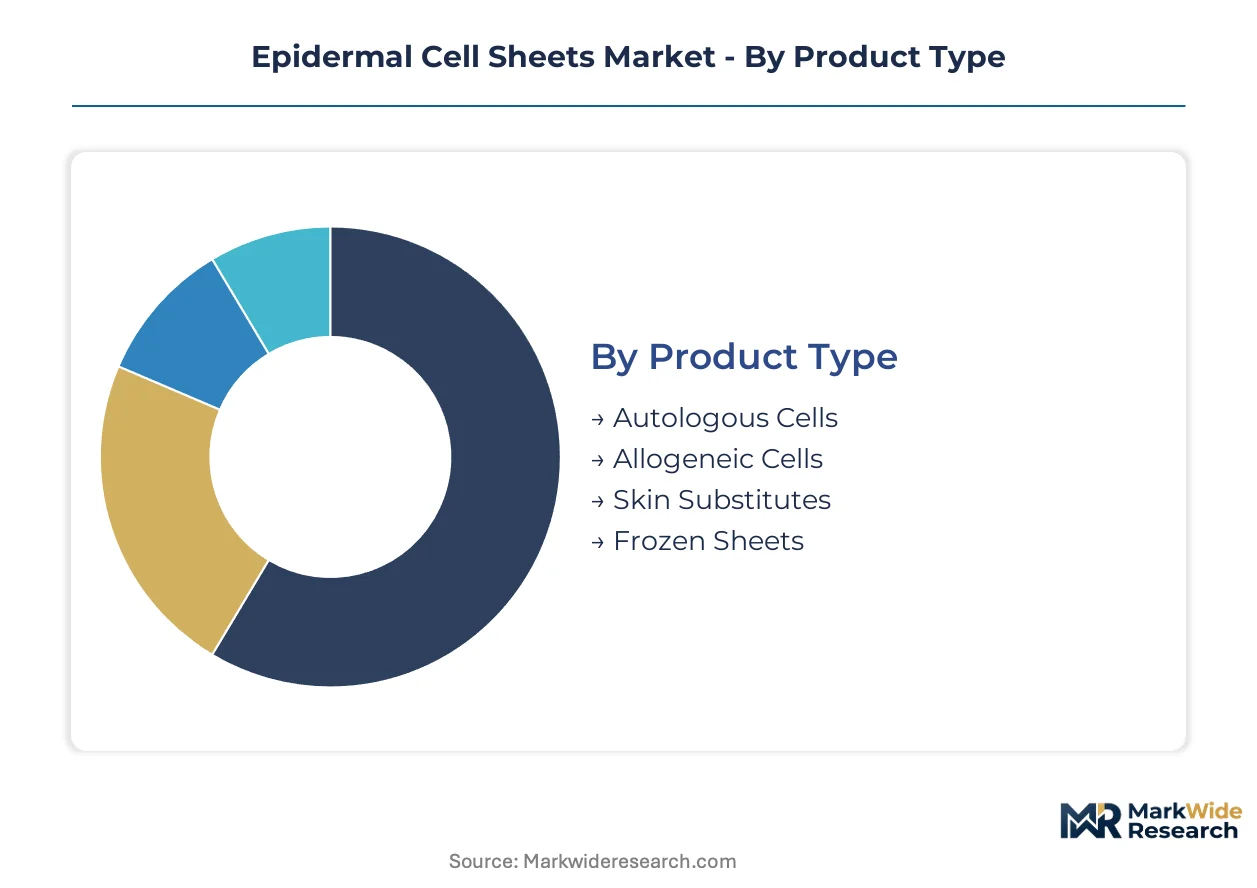
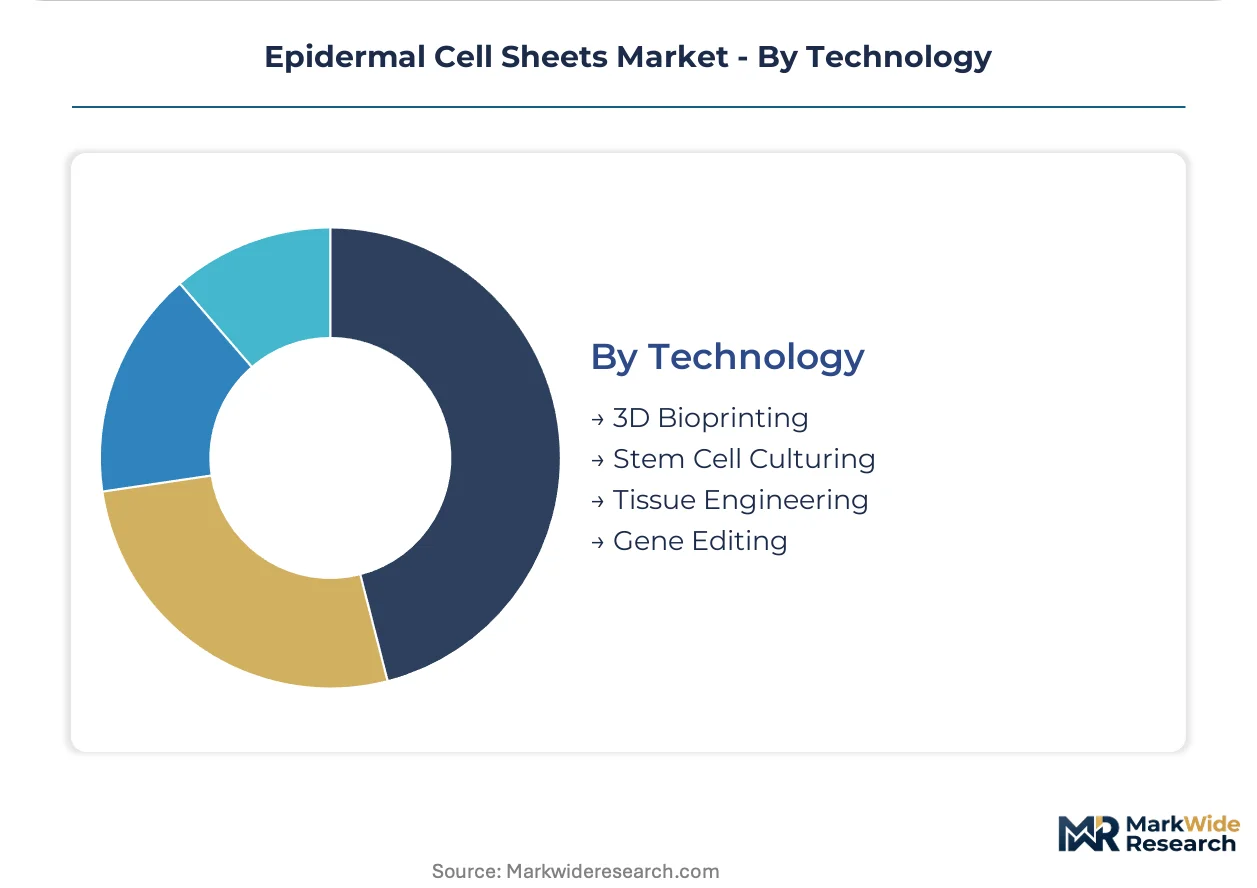
| Segmentation | Product Type: Autologous Cells, Allogeneic Cells, Skin Substitutes, Frozen Sheets Application: Wound Healing, Cosmetic Surgery, Burn Treatment, Cell Therapy End User: Hospitals, Clinics, Research Institutions, Home Care Technology: 3D Bioprinting, Stem Cell Culturing, Tissue Engineering, Gene Editing |
| Companies Covered | Japan Tissue Engineering Co., Ltd., Genzyme Corporation, Vericel Corporation, Integra LifeSciences Corp, Organogenesis Holdings Inc., Avita Medical, Smith and Nephew Inc., Genoskin, Stratatech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epidermal Cell Sheets Market Evolving Landscape
Bioprinting hardware and automated cell culture systems are compressing production timelines while expanding graft complexity beyond stratified keratinocyte sheets.
Microfluidic bioreactor technology is miniaturizing the footprint of commercial keratinocyte expansion. Burn centers in Germany and Switzerland are piloting benchtop systems for point-of-care sheet generation. This distributed production model threatens centralized manufacturing economics while enabling same-admission graft availability for partial-thickness burns.
Japan's PMDA Sakigake designation system accelerates priority review for autologous epidermal therapies with demonstrated engraftment superiority. Domestic manufacturers leverage this pathway to compress post-trial commercialization by eight to twelve months. European applicants face asymmetric timeline disadvantages without equivalent regulatory fast-track mechanisms.
Hospital purchasing committees now require health economic evidence for cell sheet adoption over acellular dermal matrices. US burn centers demand bundled payment compatibility and readmission risk documentation. This evidentiary burden favors suppliers with published long-term graft durability data and established relationships with academic medical centers.
Epidermal Cell Sheets Market Segmentation
Epidermal cell sheets serve distinct clinical workflows that reshape procurement patterns across burn centers, cosmetic practices, and research facilities. Channel configurations vary sharply by product immunology and production timeline, with autologous sheets demanding direct hospital-manufacturer coordination while allogeneic alternatives flow through tissue bank networks.
Product Type:
Autologous sheets move through dedicated hospital contracts with vertically integrated manufacturers, while allogeneic and frozen alternatives distribute via tissue procurement organizations serving multiple sites.
- Autologous Cells:Stratified keratinocyte sheets cultured from patient biopsy samples achieve permanent engraftment without immunosuppression. Japanese burn centers anchor procurement volumes through national health insurance reimbursement pathways that favor immunologically matched grafts.
- Allogeneic Cells:Neonatal foreskin-derived keratinocyte sheets provide immediate wound coverage when biopsy timelines are prohibitive. Supply volatility in donor tissue procurement constrains production scale and elevates input cost uncertainty for manufacturers.
- Skin Substitutes:Acellular dermal matrices combined with cultured epidermal layers address partial-thickness defects. These composite constructs compete on price against pure cell-based therapies in cost-sensitive wound care segments.
- Frozen Sheets:Cryopreserved allogeneic grafts enable off-the-shelf availability without the two-week culture window. Distribution concentrates through specialized tissue banks serving trauma centers and emergency departments.
By volume, allogeneic cells lead due to immediate availability. By growth pace, autologous cells are expanding most quickly as reimbursement frameworks mature.
Application:
Clinical adoption concentrates where graft durability evidence meets bundled payment compatibility, with burn reconstruction commanding premium positioning over cosmetic indications.
- Wound Healing:Chronic diabetic foot ulcers and venous leg ulcers drive recurring demand for epidermal sheet grafting. Hospital outpatient departments prioritize products with published readmission risk reduction data for value-based contracting.
- Burn Treatment:Full-thickness thermal injuries require permanent skin replacement rather than temporary biological dressings. Verified burn centers in the United States consolidate purchasing authority around suppliers with dedicated manufacturing facilities.
- Cosmetic Surgery:Facial resurfacing and scar revision applications favor thin, pliable sheet constructs. Private clinic procurement emphasizes aesthetic outcomes and minimal donor site morbidity over cost minimization.
- Cell Therapy:Investigational applications in genetic skin disorders leverage gene-corrected autologous keratinocytes. Clinical trial supply chains require GMP manufacturing partnerships with academic medical center cell processing facilities.
Burn treatment captures the highest revenue per graft. Cell therapy demonstrates the steepest expansion trajectory as regenerative medicine pipelines mature.
End User:
Facility type dictates product configuration, with hospitals requiring permanent engraftment solutions while research institutions prioritize experimental construct flexibility.
- Hospitals:American Burn Association verified centers dominate procurement for severe burn indications. These facilities demand batch traceability, long-term durability documentation, and integration with electronic health record systems.
- Clinics:Outpatient wound care centers favor allogeneic and frozen sheet options that eliminate biopsy logistics. Cost consciousness drives substitution toward acellular matrices when reimbursement rates constrain cell-based therapy access.
- Research Institutions:Academic medical centers with in-house GMP facilities pilot autologous production for investigator-initiated trials. These sites require flexible supply agreements supporting protocol customization and small-batch manufacturing.
- Home Care:Limited penetration reflects temperature-controlled transport requirements and sterile application protocols. Pilot programs in Germany and Switzerland test patient-administered sheet placement for stable chronic wounds.
Hospitals command the largest procurement volumes. Research institutions are gaining share fastest as clinical trial activity intensifies.
Technology:
Manufacturing platform selection determines capital intensity, regulatory pathway, and graft complexity ceiling, with stem cell culturing anchoring current commercial deployment.
- Stem Cell Culturing:Closed-system bioreactor expansion of keratinocyte progenitors dominates commercial production. Automation investments reduce contamination risk and improve batch consistency for high-volume hospital supply.
- 3D Bioprinting:Layered deposition enables complex anatomical geometries with integrated melanocyte populations for color-matched facial reconstruction. German and Swiss burn centers pilot benchtop systems for point-of-care production.
- Tissue Engineering:Dermal scaffold seeding with autologous cells produces composite skin substitutes. These constructs require longer manufacturing timelines but achieve superior mechanical properties for functional sites.
- Gene Editing:CRISPR-corrected patient keratinocytes address genetic blistering disorders through autologous cell therapy. Manufacturing partnerships with specialized GMP facilities constrain current commercial scalability.
Stem cell culturing leads by production volume. 3D bioprinting is climbing the fastest as hardware costs decline and regulatory frameworks adapt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan while the United States absorbs premium positioning through burn center consolidation. European manufacturers face compliance cost disadvantages without equivalent fast-track mechanisms.
United States
American Burn Association verified centers anchor procurement volumes for full-thickness wound reconstruction. The FDA regenerative medicine advanced therapy designation compresses clinical trial timelines for cell-based skin products. Boston and Philadelphia academic medical centers pilot investigator-initiated trials requiring GMP manufacturing partnerships.
Japan
National health insurance reimbursement for autologous epidermal sheet grafting drives hospital procurement volumes. The PMDA Sakigake designation system accelerates priority review for innovative autologous products. Tokyo and Osaka manufacturing clusters leverage in-house stem cell culturing infrastructure for domestic supply chain control.
Germany
Burn centers in Munich and Berlin pilot benchtop bioreactor systems for point-of-care sheet generation. EMA quality guidelines for cell-based medicinal products extend facility qualification timelines. The Baden-Württemberg medical technology corridor hosts automated cell culture system development.
Switzerland
Swissmedic oversees domestic manufacturing standards while Basel pharmaceutical clusters explore gene-corrected autologous applications. German and Swiss burn centers test distributed production models threatening centralized manufacturing economics. Zurich academic hospitals concentrate pediatric burn research requiring expanded autologous sheet surface area.
South Korea
MFDS regulates cell therapy manufacturing while Seoul capital area hospitals expand adoption for chronic wound management. Government funding for regenerative medicine infrastructure supports bioreactor automation investments. Busan-Ulsan medical device clusters develop closed-system keratinocyte expansion technologies.
Epidermal Cell Sheets Market Competitive Landscape
Concentration sits with vertically integrated tissue engineering specialists possessing captive culturing infrastructure. The capability gap between integrated manufacturers and pure-play distributors is collapsing. Three archetypes dominate: domestic supply chain anchors, North American scale operators, and commercial breadth competitors. Strategic moves center on manufacturing facility expansion and burn center network consolidation.
Within the vertically integrated tier, Japan Tissue Engineering Co., Ltd. and Vericel Corporation exemplify geographic anchoring strategies. Organogenesis Holdings Inc. occupies a position emphasizing commercial breadth across wound healing applications. These three entities represent distinct approaches to manufacturing scale and hospital procurement relationships.
| Leading Market Players |
|---|
| Japan Tissue Engineering Co., Ltd. |
| Genzyme Corporation |
| Vericel Corporation |
| Integra LifeSciences Corp |
| Organogenesis Holdings Inc. |
| Avita Medical |
| Smith and Nephew Inc. |
| Genoskin |
| Stratatech Corporation |
| Others |
Value Network & Pricing Analysis
FDA regenerative medicine advanced therapy designation gates both supply qualification timelines and price differentiation between autologous and allogeneic sheet categories. Manufacturers securing this pathway compress clinical development costs while commanding premium positioning against acellular dermal matrix substitutes.
Pricing Analysis
The customization-premium spread separates configured-to-order autologous sheets from standard allogeneic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects graft immunology, production timeline, and engraftment durability evidence. Price differentiation hinges on FDA designation tier and vertical integration depth. Cost compression in allogeneic segments is intensifying because cryopreserved allograft substitution erodes price floors. Outpatient wound care clinics exhibit highest price sensitivity; verified burn centers prioritize graft performance over procurement cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for neonatal foreskin-derived inputs sourced from Southeast Asian tissue procurement networks. Manufacturing concentration centers on Japan, the United States, and Germany, with each jurisdiction hosting captive stem cell culturing infrastructure. Raw material dependencies include neonatal donor tissue, synthetic culture substrates, and closed-system bioreactor consumables. Single-source vulnerability in donor tissue procurement constrains batch scalability. Distribution runs through vertically integrated hospital contracts for autologous products and tissue bank networks for allogeneic alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acellular dermal matrices and cryopreserved allografts threaten permanent substitution for price-sensitive wound coverage, forcing cell sheet incumbents to differentiate on engraftment durability evidence.
For Market Incumbents: Secure backward integration into stem cell culturing infrastructure to anchor supply chain control against donor tissue volatility. Lock in American Burn Association verified center contracts through dedicated manufacturing facility investments. Prioritize GMP personnel retention to defend against hiring bottlenecks at expansion sites.
For New Entrants and Emerging Players: Lead with pediatric burn applications where limited donor sites create unmet need for expanded autologous sheet surface area. Target Germany and Switzerland for benchtop bioreactor pilot deployments enabling point-of-care production models. Pursue reimbursement strategy partnerships with academic medical centers to generate health economic evidence.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated cell culture system manufacturing as closed-system bioreactor automation demands scale investments. Five-to-ten year viability favors vertically integrated tissue engineering specialists with captive culturing infrastructure over pure-play distributors. Watch for PMDA Sakigake designation announcements as inflection indicators for commercial timeline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Regenerative Medicine Advanced Therapy Designation | Compresses clinical trial timelines for cell-based skin products seeking severe burn indications. |
| Backward Integration into Stem Cell Culturing Infrastructure | Anchors domestic supply chains against neonatal foreskin procurement volatility in Japan. |
| American Burn Association Verified Center Partnership | Concentrates purchasing authority through dedicated manufacturing facility relationships. |
| 3D Bioprinting Hardware Development | Enables complex anatomical geometries with integrated melanocyte populations for facial reconstruction. |
| PMDA Sakigake Designation Pursuit | Accelerates priority review timelines for innovative autologous epidermal therapies in Japan. |
Research Methodology
Desk research of FDA filings, PMDA approval databases, hospital procurement records, and clinical trial registries preceded structured interviews with burn center procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs leads. Primary fieldwork with tissue engineering manufacturers validated secondary estimates. Bottom-up production volume modeling triangulated against top-down reimbursement expenditure analysis.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework. CAGRs derived from segment-level volume trajectories and price evolution assumptions. Forecast inputs incorporated bioreactor automation adoption curves and reimbursement framework maturation patterns.
Forecasts assume regulatory continuity in FDA regenerative medicine pathways and Japan's national health insurance reimbursement regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market