
 US Regenerative Medicine Market | 2026-2036
US Regenerative Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
US Regenerative Medicine Market Insights
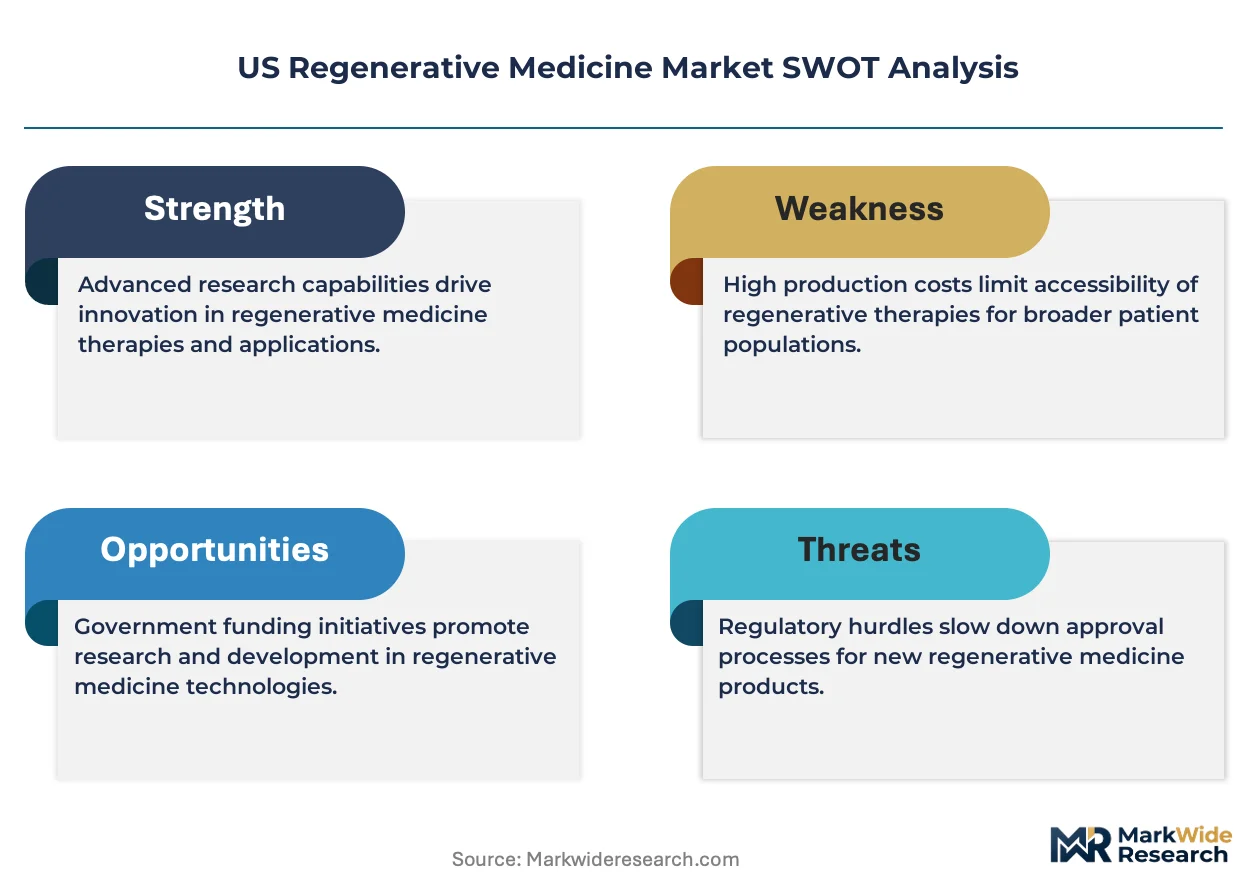
Platform licensing revenue is narrowing as therapeutic developers bring manufacturing in-house rather than outsource cell processing. Johnson & Johnson anchors its position through backward integration into autologous cell production facilities. Bristol-Myers Squibb leverages its CAR-T infrastructure to sustain leadership in oncology-directed regenerative products. Regeneron Pharmaceuticals differentiates through CRISPR-enabled gene editing platforms that occupy a distinct technical tier.
Regenerative medicine encompasses cell-based therapies, engineered tissues, gene-modification interventions, and implantable biomaterials designed to repair or replace damaged human tissue through biological mechanisms rather than mechanical intervention. These products typically require cryopreserved or fresh cellular starting material, aseptic bioprocessing, and validated potency assays to ensure functional integrity. Cell therapy commands the largest revenue pool among product types, while gene therapy represents the fastest-expanding segment driven by FDA approvals for inherited disease treatments. Orthopedics and cardiology applications concentrate the highest procedure volumes, though neurology shows accelerating clinical trial enrollment for neurodegenerative indications.
FDA's Office of Cellular, Tissue, and Gene Therapies and the Center for Biologics Evaluation and Research govern commercial approval pathways, while CMS national coverage determinations control reimbursement access for hospital-based administration. HIPAA privacy requirements and FDA good manufacturing practice standards impose data integrity and chain-of-custody obligations across clinical sites and manufacturing facilities. Stakeholders must monitor evolving FDA guidance on accelerated approval confirmatory trials and state-level stem cell clinic enforcement actions that could reshape competitive access.
Market Dynamics
Hospital procurement of autologous cell therapies is concentrating demand among vertically integrated health systems capable of managing cold-chain logistics and FDA-mandated chain-of-custody protocols.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses commercialization timelines for gene-modified cell products, pulling forward revenue recognition for developers with confirmatory trial designs.
- CMS Reimbursement Reform:New Technology Add-on Payments for CAR-T and gene therapies are expanding hospital budget capacity for high-cost regenerative procedures.
- California Biomedical Corridor:Concentrated venture deployment and CRO infrastructure in the San Francisco-San Diego axis is shortening clinical trial enrollment cycles.
Market Restraints
- Plasma-Derived Starting Material Volatility:Supply constraints on apheresis collections and cryopreserved leukapheresis units are inflating COGS for autologous platforms.
- Single-Site Manufacturing Risk:Cell therapy production concentrates in FDA-registered cleanroom facilities clustered in Massachusetts and Maryland, creating geographic vulnerability to weather or labor disruption.
- HIPAA-GxP Data Friction:The intersection of patient privacy mandates and batch record traceability requirements is extending technology transfer timelines between clinical sites and contract manufacturers.
Strategic Opportunities
- Neurology Indication Expansion:Parkinson's disease and ALS programs are advancing through Phase II with potential to unlock CMS neurodegenerative disease payment carve-outs.
- Allogeneic Off-the-Shelf Platforms:Gene-edited iPSC-derived therapies are converging with scalable bioreactor manufacturing to displace patient-matched production economics.
- Texas Medical Center Procurement:The Houston health system cluster is consolidating purchasing authority for cell therapy administration, creating channel leverage for volume-committed suppliers.
Industry Challenges
- Vector Manufacturing Bottleneck:Lentiviral and AAV production capacity scarcity is forcing developers into multi-year CDMO queue positions that delay IND filings.
- Potency Assay Standardization:Lack of harmonized surrogate endpoints between FDA and academic medical centers is fragmenting clinical validation requirements across trial networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Regenerative Medicine Market |
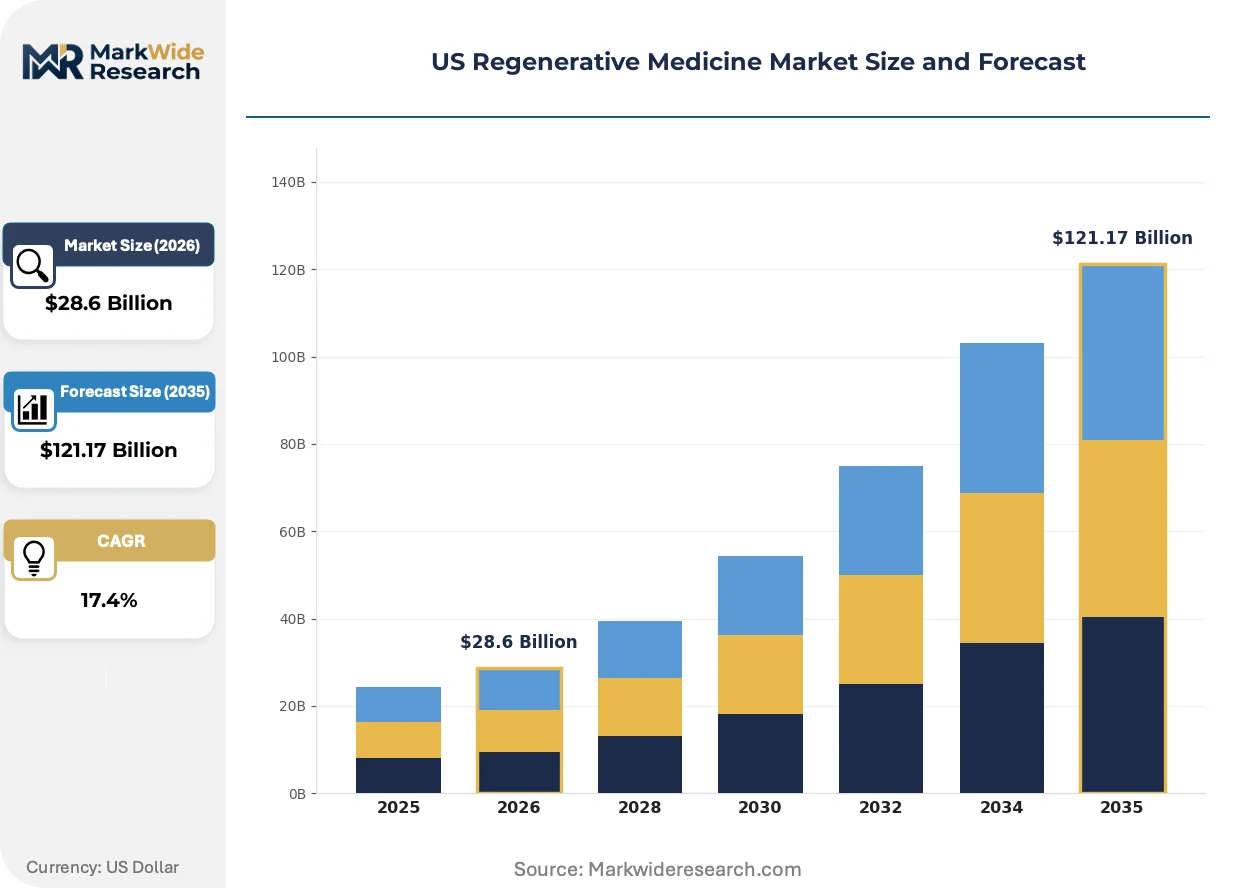
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Therapy, Tissue Engineering, Gene Therapy, Biomaterials Application: Orthopedics, Cardiology, Neurology, Dermatology End User: Hospitals, Academic Research Institutes, Specialty Clinics, Biopharmaceutical Companies Delivery Mode: Invasive, Non-invasive, Localized, Systemic |
| Companies Covered | Johnson & Johnson, Bristol-Myers Squibb, Regeneron Pharmaceuticals, CRISPR Therapeutics, Medtronic, AbbVie, Pfizer, Mesoblast, Novartis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Regenerative Medicine Market Trends and Innovations
Cell therapy manufacturing is pivoting from centralized cleanroom production toward distributed models that co-locate bioprocessing with clinical administration sites.
Gene editing is hybridizing with synthetic biology toolkits to enable multiplexed knock-ins for next-generation CAR-T constructs. Academic medical centers in the Boston-Cambridge cluster are piloting these platforms for solid tumor indications. The convergence is compressing lead optimization timelines from 18 months to under 8 months for validated targets.
FDA's draft guidance on manufacturing changes and comparability protocols is forcing developers to lock process parameters earlier in clinical development. The industrial consequence is reduced post-approval flexibility for yield improvements. Oncology-directed programs are responding by overbuilding initial capacity to avoid mid-lifecycle CMC amendments.
Hospital systems are consolidating cell therapy procurement under centralized pharmacy and therapeutics committees. Specialty distributors serving community oncology practices are losing access as academic medical centers internalize infusion logistics. The shift is most visible in the Mid-Atlantic region where Penn Medicine and Johns Hopkins have established captive supply arrangements.
US Regenerative Medicine Market Segmentation
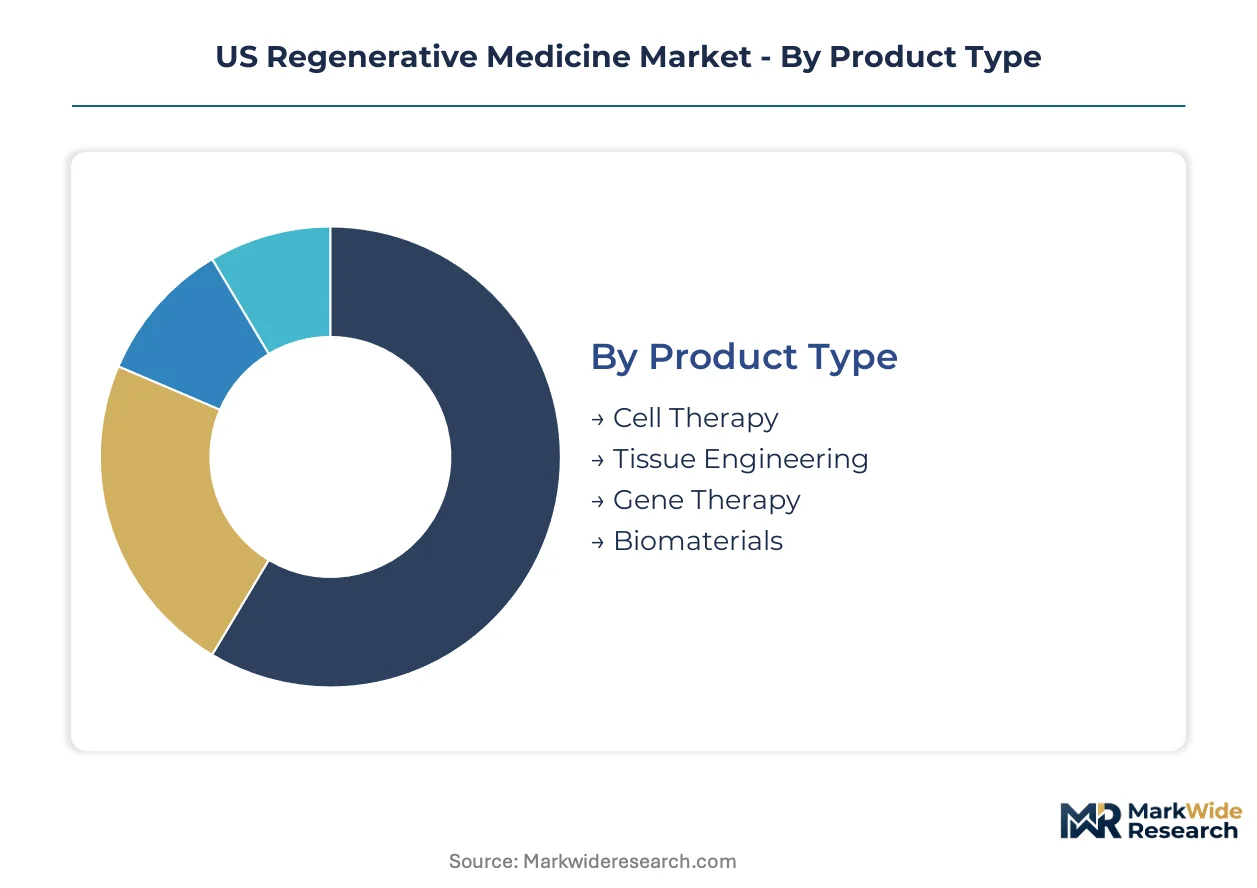
Segmentation in US regenerative medicine reveals distinct procurement rhythms across product categories. Cycle times vary from weeks for standardized biomaterials to years for personalized cell therapies, forcing portfolio managers to balance inventory velocity against margin capture.
Product Type:
Cell therapy platforms turn inventory slowest due to patient-matched manufacturing, while biomaterials move fastest through standardized distribution channels.
- Cell Therapy:Autologous and allogeneic cellular products require cryopreserved starting material, aseptic bioprocessing, and validated potency assays. Demand concentrates in California's biomedical corridor and the Boston-Cambridge cluster, driven by FDA accelerated approval pathways that compress commercialization timelines for developers with confirmatory trial designs.
- Gene Therapy:Viral vector-delivered genetic modifications occupy the fastest-expanding segment, with lentiviral and AAV platforms commanding premium pricing. Massachusetts and Maryland cleanroom facilities anchor production capacity, though vector manufacturing bottlenecks force developers into multi-year CDMO queue positions.
- Tissue Engineering:Scaffold-based constructs and 3D bioprinted grafts serve orthopedic and wound care applications with moderate turnover cycles.
- Biomaterials:Synthetic and naturally derived implantable materials move through conventional medical device distribution with the shortest procurement cycles.
Cell therapy anchors the volume base while gene therapy gains share at the steepest rate.
Application:
Procedure volumes concentrate in surgical specialties with established reimbursement codes, while emerging indications carry higher trial risk but faster enrollment acceleration.
- Orthopedics:Cartilage repair scaffolds and bone graft substitutes command the highest procedure volumes among regenerative applications. Texas Medical Center procurement clusters and Midwest hospital systems drive demand, supported by CMS coverage for autologous chondrocyte implantation.
- Cardiology:Cardiac cell therapy and engineered heart tissue programs advance through Phase II trials with potential to unlock specialized cardiovascular payment carve-outs.
- Neurology:Parkinson's disease and ALS cell therapy programs show accelerating clinical trial enrollment for neurodegenerative indications.
- Dermatology:Engineered skin substitutes and growth factor therapies serve burn centers and chronic wound clinics with established reimbursement pathways.
Orthopedics captures the highest current revenue pool while neurology demonstrates the steepest enrollment trajectory.
End User:
Purchasing authority concentrates in institutions capable of managing cold-chain logistics and FDA-mandated chain-of-custody protocols.
- Hospitals:Vertically integrated health systems with centralized pharmacy and therapeutics committees dominate procurement of infused cell therapies. Penn Medicine and Johns Hopkins have established captive supply arrangements that displace specialty distributors.
- Academic Research Institutes:Boston-Cambridge and San Francisco-San Diego clusters pilot next-generation platforms including CRISPR-enabled gene editing and multiplexed CAR-T constructs.
- Specialty Clinics:Community oncology practices are losing access as academic medical centers internalize infusion logistics.
- Biopharmaceutical Companies:Therapeutic developers are bringing manufacturing in-house rather than outsourcing cell processing, narrowing platform licensing revenue pools.
Hospitals anchor procurement volume while academic research institutes drive technology adoption velocity.
Delivery Mode:
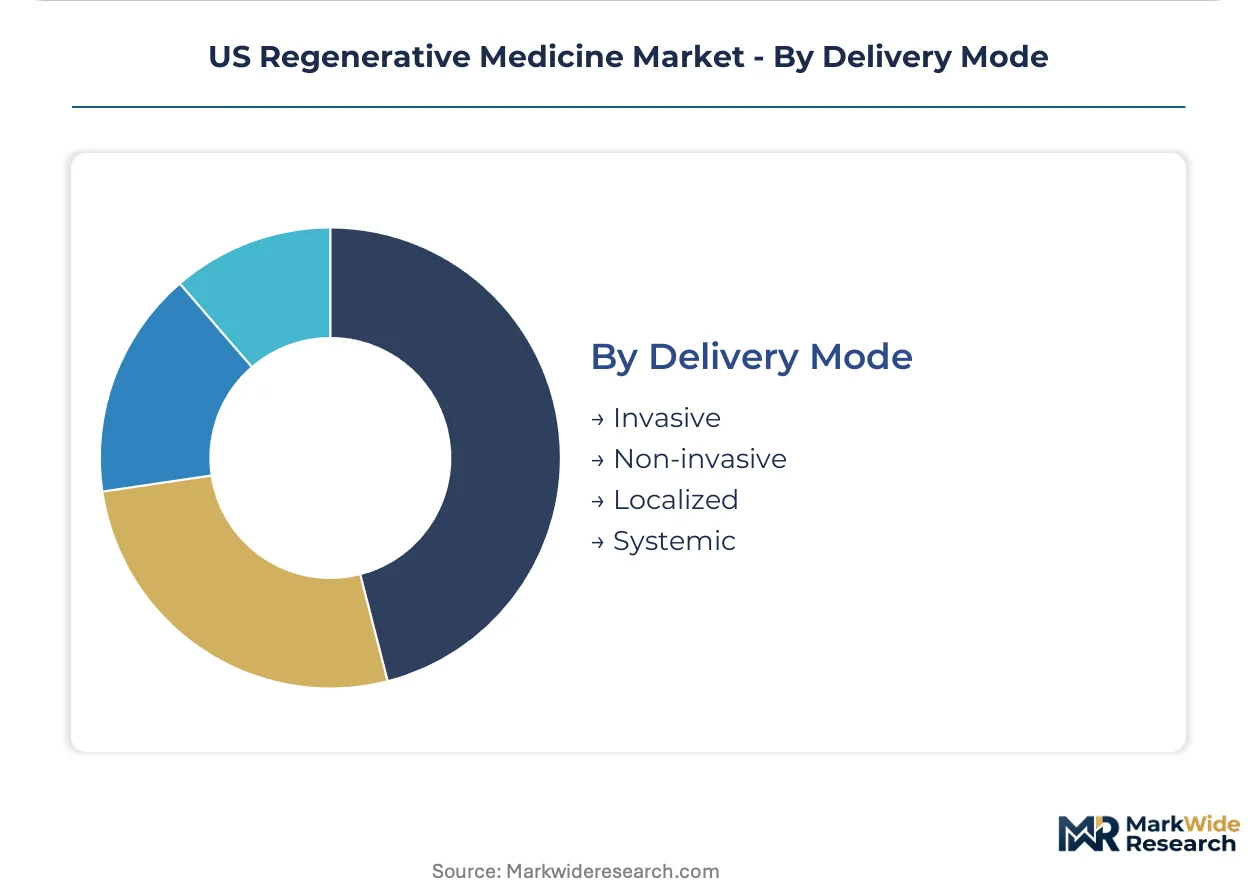
Route of administration determines site-of-care requirements and reimbursement complexity, with invasive methods carrying higher facility fees but tighter outcomes accountability.
- Invasive:Surgical implantation of engineered tissues and direct injection of cellular products requires operating room capacity and specialized surgical training.
- Non-invasive:Topical and transdermal delivery systems serve dermatology applications with lower facility overhead.
- Localized:Site-directed administration concentrates therapeutic effect while limiting systemic exposure, common in orthopedic and cardiac applications.
- Systemic:Intravenous infusion of gene-modified cells enables broad tissue targeting but requires comprehensive monitoring for immune response.
Invasive delivery captures the highest procedure reimbursement while localized administration expands fastest into outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across US sub-regions, with coastal biomedical corridors driving autologous cell therapy uptake while inland health systems prioritize standardized orthopedic grafts with faster inventory turns.
California
Venture deployment and CRO infrastructure concentrate demand for gene-modified cell platforms in the San Francisco-San Diego corridor. FDA accelerated approval pathways pull forward commercialization timelines for developers with confirmatory trial designs anchored in Stanford and UC San Diego medical centers.
Massachusetts
CAR-T infrastructure and CRISPR-enabled research programs dominate procurement in the Boston-Cambridge cluster. Mass General Brigham and Dana-Farber Cancer Institute internalize infusion logistics, displacing specialty distributors through captive supply arrangements.
Texas
The Houston health system cluster consolidates purchasing authority for cell therapy administration, creating channel leverage for volume-committed suppliers. Texas Medical Center procurement drives demand for orthopedic and cardiac applications with established reimbursement codes.
Maryland
FDA-registered cleanroom facilities cluster around the I-270 biotechnology corridor, concentrating production capacity for viral vector manufacturing. National Institutes of Health proximity accelerates academic-industry technology transfer for gene therapy platforms.
Pennsylvania
Penn Medicine anchors Mid-Atlantic demand through centralized pharmacy and therapeutics committees that control hospital-based cell therapy procurement. The Philadelphia region shows accelerating clinical trial enrollment for neurology indications targeting Parkinson's disease.
US Regenerative Medicine Market Competitive Landscape
Capability concentration sits with gene-editing specialists and CAR-T infrastructure holders; scale advantage sits with diversified pharmaceutical conglomerates with backward integration into autologous production. The market structures around three tiers: vertically integrated health systems managing captive supply, therapeutic developers bringing manufacturing in-house, and remaining platform licensors serving mid-cap entrants. Dominant competitive moves include M&A to secure vector manufacturing capacity and strategic partnerships to lock in CDMO queue positions.
Within the diversified pharmaceutical tier, Johnson & Johnson anchors its position through in-house production of autologous cell therapies. Bristol-Myers Squibb occupies a central position leveraging existing CAR-T infrastructure. Regeneron Pharmaceuticals exemplifies the gene-editing specialist archetype with CRISPR-enabled platforms.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bristol-Myers Squibb |
| Regeneron Pharmaceuticals |
| CRISPR Therapeutics |
| Medtronic |
| AbbVie |
| Pfizer |
| Mesoblast |
| Novartis |
| Others |
Pricing and Supply Chain Analysis
The I-95 freight corridor's refrigerated logistics costs directly shape pricing power for cryopreserved cell therapies, concentrating margin capture among Massachusetts and Maryland cleanroom operators while forcing price differentiation between patient-matched autologous products and scalable allogeneic platforms.
Pricing Analysis
Long-term offtake agreements dominate procurement between hospital systems and cell therapy developers, though spot purchases persist for emergency apheresis collections. Pricing stratifies across premium, standard, and economy tiers based on FDA expedited review status and cold-chain reliability guarantees. Cost compression in autologous manufacturing is intensifying because plasma-derived starting material volatility inflates COGS. Community oncology practices show highest price sensitivity as academic medical centers internalize infusion logistics and capture volume discounts.
Supply Chain Analysis
Extended payment terms from CDMOs now stretch to 180 days for viral vector production slots, straining developer working capital. Supply concentrates in Massachusetts, Maryland, and California, with apheresis collection centers, cryopreserved leukapheresis units, and lentiviral vector manufacturing anchoring dependencies. Single-site manufacturing risk creates geographic vulnerability to weather or labor disruption. Distribution runs through vertically integrated health systems with captive pharmacy and therapeutics committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for gene-modified cell products constitute a regulatory inflection compressing commercialization timelines and rewarding developers with locked manufacturing processes.
For Market Incumbents: Harden CAR-T infrastructure against allogeneic platform displacement by securing multi-year apheresis collection contracts and overbuilding viral vector capacity to avoid mid-lifecycle CMC amendments. Backward integration into autologous production facilities anchors margin defense against emerging iPSC-derived competitors.
For New Entrants and Emerging Players: Establish a beachhead in neurology indications targeting Parkinson's disease and ALS, where CMS neurodegenerative disease payment carve-outs remain underpenetrated by existing oncology-focused developers. Partner with Texas Medical Center procurement clusters to secure volume-committed supply arrangements before incumbent consolidation hardens.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core platform licensing units as therapeutic developers bring manufacturing in-house. Vector manufacturing capacity scarcity supports 5-10 year viability for specialized CDMO assets. Watch FDA draft guidance on manufacturing changes and comparability protocols as the inflection signal for locked-process competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses timelines for confirmatory trial designs. |
| Manufacturing Scale-Up | Cleanroom capacity expansion in Maryland reduces CDMO queue dependency. |
| Hospital System Partnership | Penn Medicine captive supply arrangements displace specialty distributors. |
| Backward Integration | In-house autologous production narrows platform licensing revenue pools. |
| Pipeline Diversification | Neurology indication expansion unlocks CMS payment carve-outs. |
Research Methodology
Operator-level perspectives from cell therapy manufacturing executives, FDA regulatory affairs leads, hospital formulary directors, and CMS reimbursement specialists anchored the qualitative base. Secondary validation drew from FDA Office of Cellular, Tissue, and Gene Therapeutics filings, ClinicalTrials.gov enrollment data, CMS national coverage determinations, and hospital procurement databases. Bottom-up patient population modeling and top-down venture deployment tracking were triangulated to anchor volume estimates.
Scenario-bracketing around FDA approval probability, CMS reimbursement timing, and manufacturing yield variance shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application specialty, end-user institution tier, and delivery mode complexity. CAGRs were derived from logistic diffusion curves fitted to historical approval velocity and penetration benchmarks. Forecast inputs incorporated vector manufacturing capacity constraints and state-level stem cell clinic enforcement trajectories.
Stress conditions across FDA guidance finalization timing, apheresis collection disruption, and hospital system consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway efficiency and reimbursement expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Regenerative Artificial Skin Market