
 China Longevity and Anti-Senescence Therapy Market | 2026-2036
China Longevity and Anti-Senescence Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
China Longevity and Anti-Senescence Therapy Market Insights
GB standards for cell therapy manufacturing and clinical trial qualification is collapsing the barrier between traditional pharmaceutical production and advanced biologics, forcing rapid facility upgrades across the sector. Hangzhou Tigermed leverages its CRO infrastructure to dominate clinical trial services for longevity candidates. BeiGene sustains R&D intensity through diversified oncology-to-geroscience pipelines. Tong Ren Tang anchors consumer trust by integrating classical TCM formulations with modern anti-senescence positioning.
China longevity and anti-senescence therapy encompasses interventions targeting cellular senescence, telomere maintenance, and metabolic reprogramming through biologics, synthetic compounds, and bioactive natural extracts, typically requiring cold-chain distribution and sterile administration protocols. The primary purpose is extending healthspan and compressing morbidity in aging populations. Cell therapy and gene therapy command premium positioning due to manufacturing complexity and regulatory stringency, while nutraceuticals occupy volume leadership through direct-to-consumer channels. Injectable delivery modes concentrate margin pools in hospital and clinic settings, whereas oral formats penetrate home user segments at lower per-unit economics.
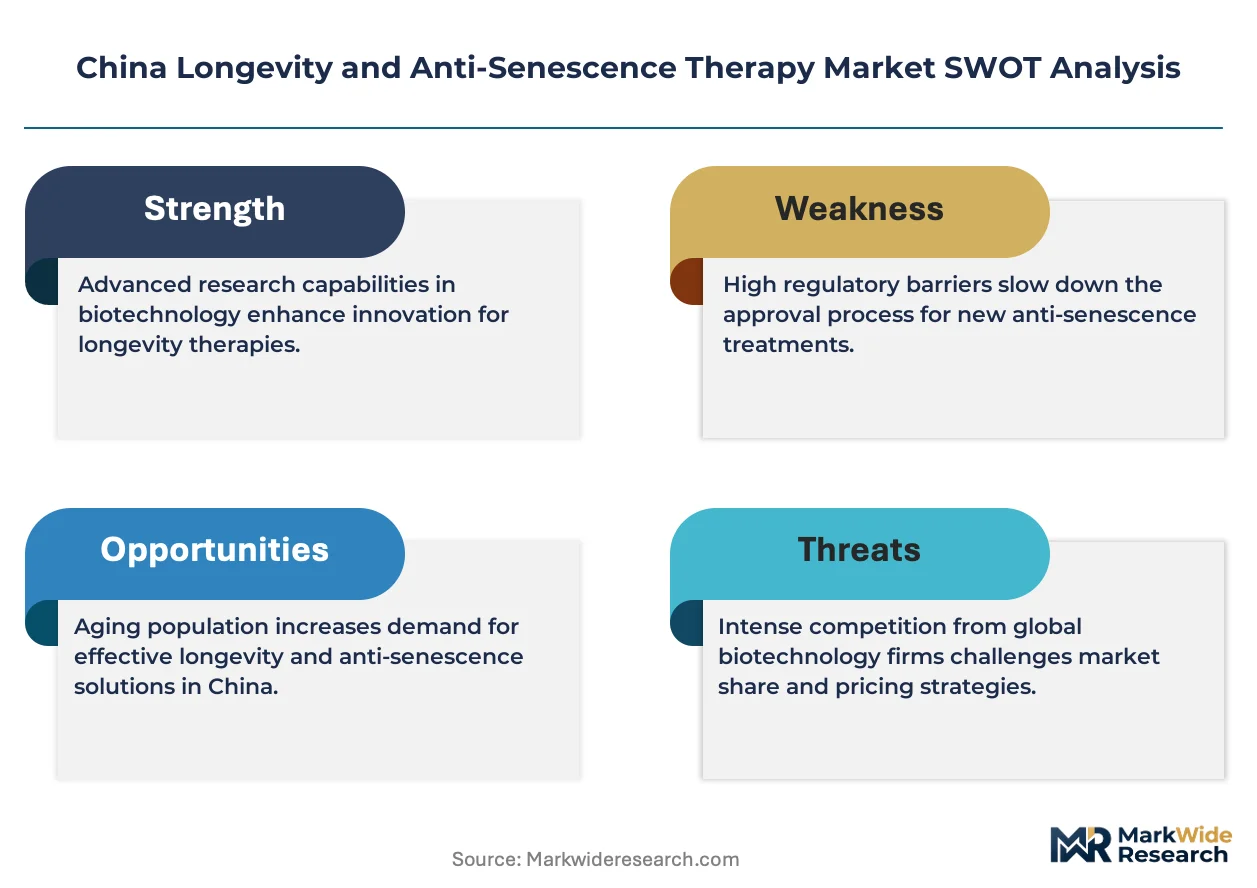
NMPA, GB standards, and the National Health Commission shape market access through phased clinical trial requirements and post-market surveillance mandates that favor sponsors with established regulatory affairs capabilities. SAMR oversight of health claims constrains nutraceutical marketing, directing investment toward substantiated efficacy data. Stakeholders must monitor evolving biosafety classifications for autologous cell products and assess whether dual carbon goals from MEE will reshape cleanroom energy costs and facility siting decisions.
Market Dynamics
NMPA's accelerated approval pathways for innovative biologics are compressing development timelines and collapsing the traditional 5-7 year gap between laboratory validation and commercial availability in geroscience applications.
Growth Catalysts
- GB Standards Harmonization:The national cell therapy manufacturing framework is eliminating redundant facility certifications, allowing Shanghai and Beijing geriatric clinics to adopt advanced interventions faster.
- Affluent Urban Demand:Hormone replacement and nutraceutical segments serving high-net-worth cohorts in tier-one cities are pulling investment toward premium positioning and cold-chain infrastructure.
- Autologous Cell Processing:Point-of-care bioprocessing technologies are reducing dependency on centralized manufacturing, expanding clinic-level service capacity.
Market Restraints
- Cleanroom Energy Costs:MEE dual carbon goals are reshaping facility siting decisions, with Guangdong and Jiangsu provinces imposing carbon intensity caps on biologics manufacturing.
- Input Material Concentration:Fetal bovine serum and recombinant growth factors concentrate supply among three international vendors, exposing margins to freight volatility and customs delays.
- SAMR Health Claim Friction:Post-market surveillance mandates for nutraceutical efficacy substantiation are extending payback periods for direct-to-consumer brands by 18-24 months.
Strategic Opportunities
- Hainan Free Trade Port:The Boao pilot zone permits accelerated import of non-NMPA-approved longevity therapies, creating a regulatory sandbox for international biotech sponsors.
- TCM-Modern Convergence:Classical formulations repositioned through anti-senescence claims are capturing pharmacy shelf space previously dominated by synthetic supplements.
- Telemedicine Integration:Remote patient monitoring platforms are compressing the consultation-to-treatment cycle for hormone therapy protocols in second-tier cities.
Industry Challenges
- Geroscience Talent Scarcity:Cell therapy process engineers with GMP manufacturing experience command 40% salary premiums, constraining scale-up timelines for domestic sponsors.
- Cold-Chain Integrity:Injectable senolytic and biologic products require uninterrupted 2-8°C distribution, with last-mile gaps in western provinces causing batch wastage.
- IP Licensing Complexity:CRISPR and telomerase extension patents held by US and European institutions force Chinese developers into revenue-sharing arrangements that compress margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Longevity and Anti-Senescence Therapy Market |
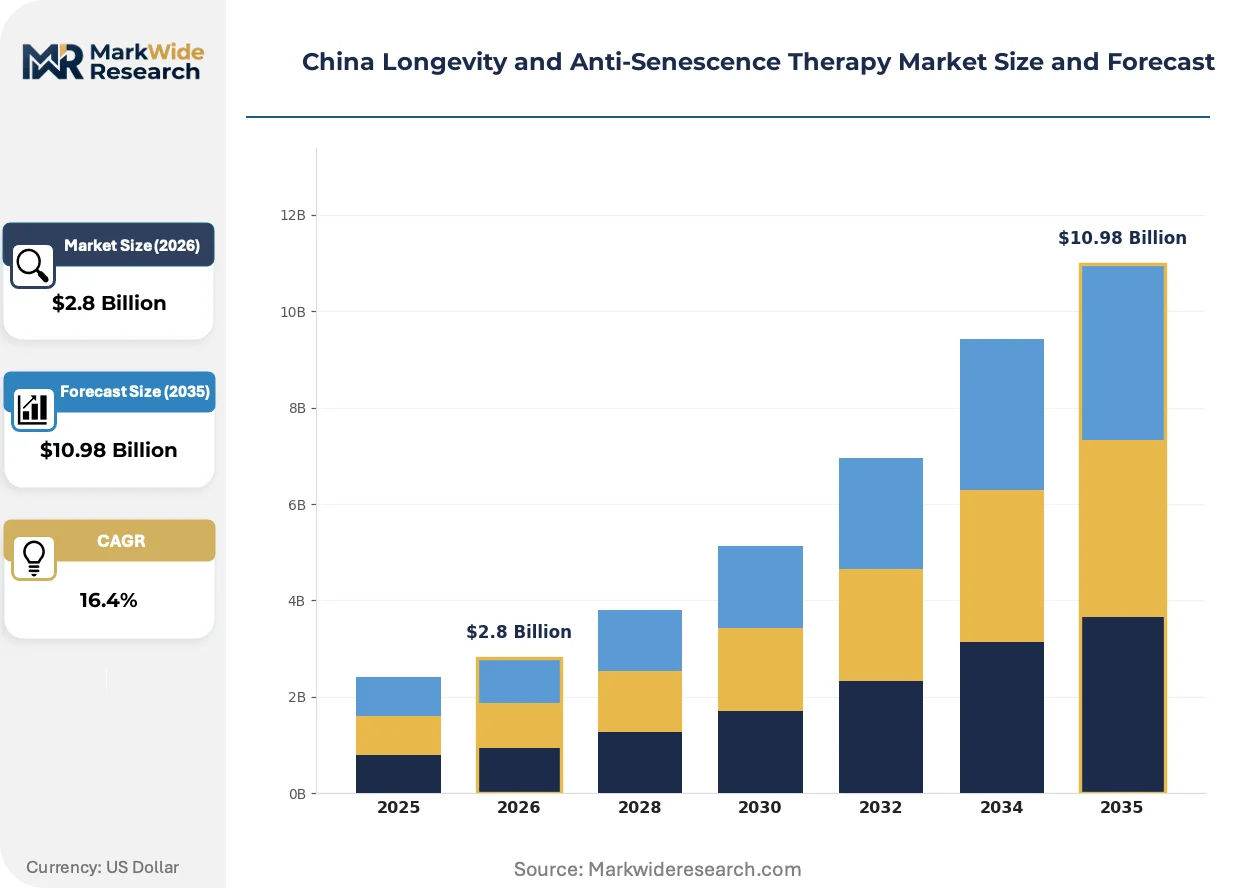
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Cell Therapy, Gene Therapy, Hormone Replacement, Nutraceuticals Application: Age-Related Disorders, Cognitive Decline, Skin Rejuvenation, Chronic Diseases Delivery Mode: Injectable, Oral, Topical, Transdermal End User: Clinics, Hospitals, Home Users, Wellness Centers |
| Companies Covered | Hangzhou Tigermed, Infinitus, AccurEdit Therapeutics, Luokang Gene, BeiGene, Yoltech Therapeutics, Tong Ren Tang, Zai Lab, Innovent Biologics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Longevity and Anti-Senescence Therapy Market Trends and Innovations
Microfluidic processing and closed-system bioreactors are displacing open-manipulation protocols, cutting contamination risk and enabling distributed manufacturing at clinic scale.
Closed-system bioreactors for autologous cell expansion are miniaturizing from 50-liter stainless steel vessels to 2-liter single-use chambers. Hangzhou and Suzhou equipment vendors are shipping these systems to geriatric clinics within six-month delivery windows. This footprint reduction is enabling point-of-care production without centralized cleanroom investment.
NMPA's 2023 technical guidelines for gene and cell therapy products are mandating real-time release testing protocols that bypass traditional batch release delays. Domestic sponsors with established quality systems are compressing commercialization timelines by 8-12 months. The hormone replacement segment is responding fastest, with several candidates advancing through conditional approval pathways.
Direct-to-consumer genetic testing for longevity biomarkers is fragmenting the traditional clinic-centric patient acquisition model. E-commerce platforms and private WeChat communities are replacing hospital referrals as the primary discovery channel for nutraceutical and peptide interventions. This shift concentrates most visibly in Shenzhen and Chengdu, where digital-native consumers self-direct supplementation protocols before seeking clinical validation.
China Longevity and Anti-Senescence Therapy Market Segmentation
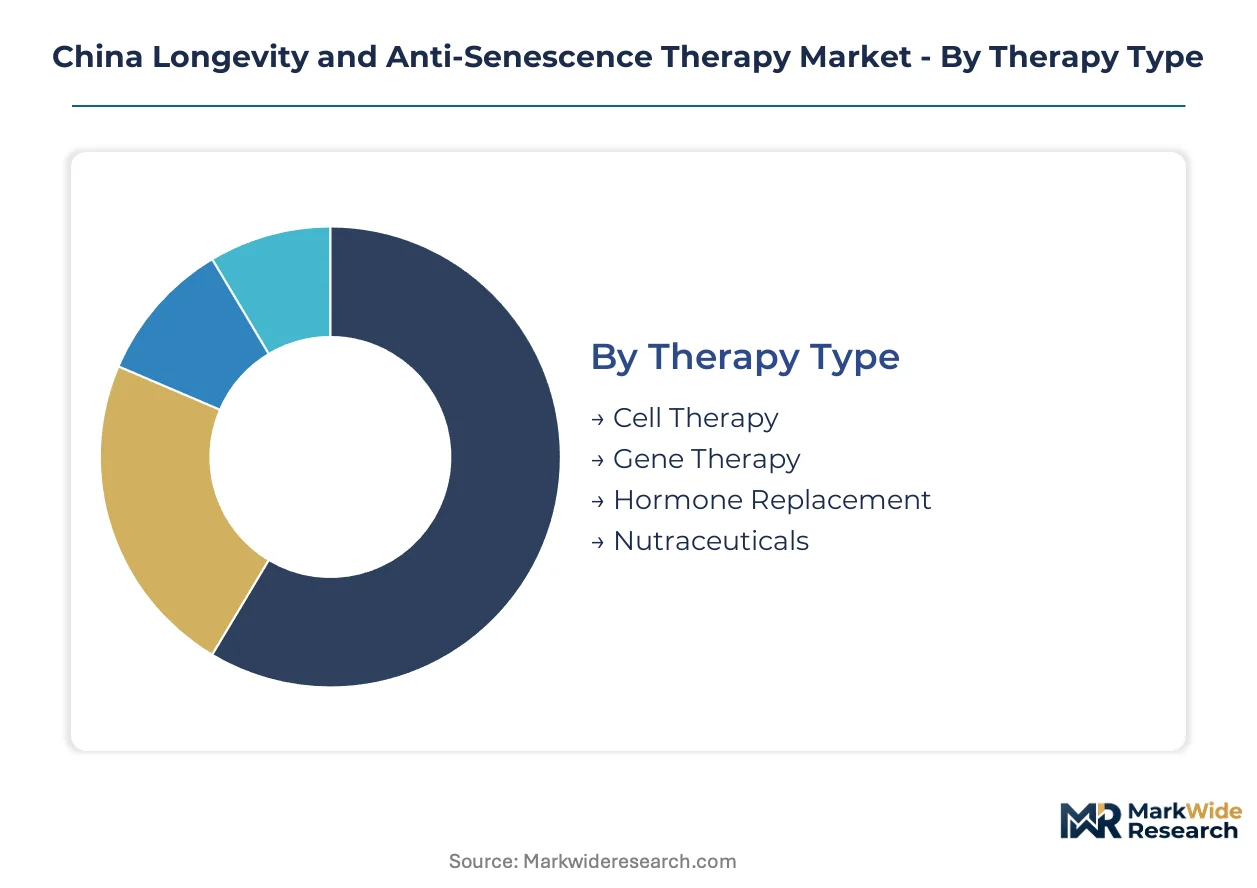
China's longevity market fragments across therapeutic modalities with divergent regulatory pathways and margin structures. Understanding substitution dynamics between cell-based interventions and traditional nutraceuticals reveals where capital is concentrating and which segments face margin compression from adjacent categories.
Therapy Type:
Cell therapy and gene therapy face intensifying substitute pressure from repositioned TCM formulations and synthetic peptide alternatives that bypass NMPA's biologics approval burden.
- Cell Therapy:Autologous stem cell expansion and allogeneic mesenchymal stem cell products dominate premium positioning in Shanghai and Beijing geriatric clinics. NMPA's accelerated approval pathways compress development timelines for candidates targeting age-related frailty, though manufacturing complexity limits clinic-level adoption outside tier-one cities.
- Gene Therapy:Telomerase activation and senolytic gene editing command the highest per-patient economics but concentrate in Hainan Boao pilot zone imports due to domestic IP licensing constraints. MEE dual carbon goals reshape cleanroom energy costs for centralized manufacturing facilities.
- Hormone Replacement:Testosterone and growth hormone protocols serve affluent urban cohorts through telemedicine-integrated delivery models in Shenzhen and Chengdu.
- Nutraceuticals:NAD+ precursors, resveratrol formulations, and TCM-derived bioactives penetrate direct-to-consumer channels with SAMR health claim friction extending substantiation timelines.
Nutraceuticals anchor the volume base while gene therapy gains share at the steepest rate.
Application:
Cost tier stratification separates hospital-administered interventions from self-directed supplementation, with cognitive decline applications commanding premium reimbursement positioning.
- Age-Related Disorders:Sarcopenia, immunosenescence, and metabolic syndrome interventions concentrate in Beijing and Shanghai hospital networks with established geroscience departments.
- Cognitive Decline:Alzheimer's prevention and mild cognitive impairment protocols attract the highest R&D intensity from domestic biotech sponsors leveraging NMPA conditional approval pathways. Hangzhou Tigermed's CRO infrastructure dominates trial services for this indication.
- Skin Rejuvenation:Collagen induction and extracellular matrix restoration procedures occupy wellness center and cosmetic clinic channels with lower regulatory barriers.
- Chronic Diseases:Diabetes, cardiovascular, and renal aging modifications integrate with existing therapeutic categories rather than standalone longevity positioning.
Chronic diseases anchor the volume base while cognitive decline gains share at the steepest rate.
Delivery Mode:
Volume concentration favors oral formats for home user penetration, though margin pools concentrate in injectable administration requiring cold-chain integrity.
- Injectable:Intravenous senolytics and subcutaneous peptide therapies require uninterrupted 2-8°C distribution with last-mile gaps in western provinces causing batch wastage. Guangdong and Jiangsu manufacturing clusters face MEE carbon intensity caps on cleanroom operations.
- Oral:Capsule and tablet nutraceuticals dominate e-commerce and pharmacy channels with Tong Ren Tang integrating classical TCM formulations into anti-senescence positioning.
- Topical:Transdermal retinoids and growth factor serums serve cosmetic longevity claims with lower SAMR substantiation requirements.
- Transdermal:Microneedle and iontophoresis hormone delivery systems expand clinic-level service capacity without injection infrastructure.
Oral formats anchor the volume base while injectable modes gain share at the steepest rate.
End User:
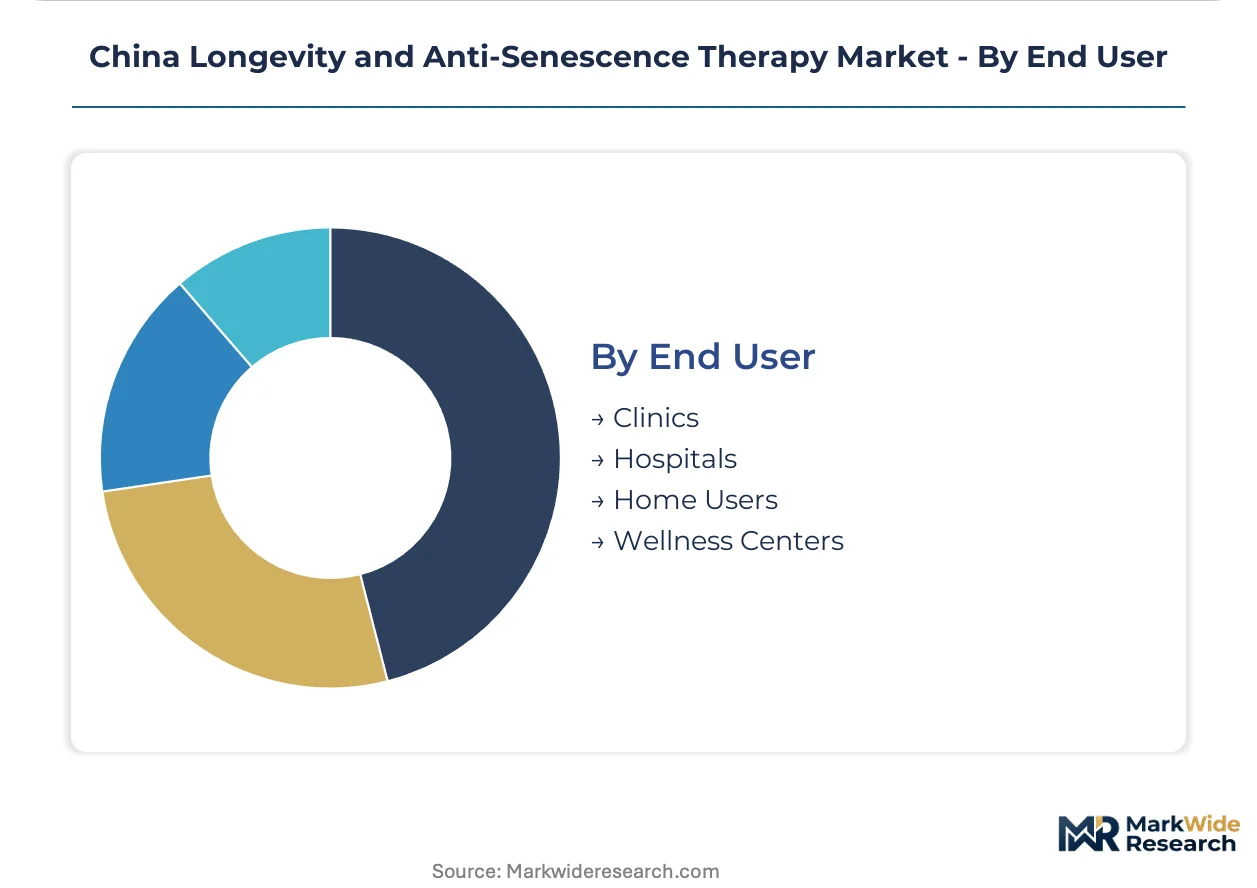
Customer type segmentation reveals divergence between institutional procurement with established GMP supply chains and direct-to-consumer discovery through digital channels.
- Clinics:Geriatric specialty clinics in Shanghai and Beijing adopt point-of-care autologous cell processing technologies, reducing dependency on centralized manufacturing. Hangzhou and Suzhou equipment vendors ship closed-system bioreactors with six-month delivery windows.
- Hospitals:Tertiary hospital geroscience departments integrate longevity protocols into existing chronic disease management with NMPA post-market surveillance mandates favoring sponsors with established regulatory affairs capabilities.
- Home Users:Digital-native consumers in Shenzhen and Chengdu self-direct supplementation protocols through direct-to-consumer genetic testing and private WeChat communities before seeking clinical validation.
- Wellness Centers:Non-medical longevity service providers occupy regulatory gray zones with cosmetic and lifestyle positioning outside NMPA biologics oversight.
Home users anchor the volume base while clinics gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent urban consumers in tier-one cities drive the majority of demand for premium longevity interventions, while provincial expansion depends on cold-chain infrastructure and telemedicine penetration.
Yangtze River Delta
Shanghai geriatric clinics command the highest adoption rates for autologous cell therapies among China's aging elite. NMPA's accelerated approval pathways for innovative biologics compress development timelines for domestic sponsors headquartered in the region. Hangzhou anchors clinical trial services through established CRO infrastructure serving oncology-to-geroscience pipelines.
Pearl River Delta
Shenzhen digital-native consumers self-direct supplementation protocols through direct-to-consumer genetic testing before seeking clinical validation. MEE dual carbon goals impose carbon intensity caps on biologics manufacturing in Guangdong province. Guangzhou wellness centers integrate TCM formulations with modern anti-senescence positioning for pharmacy channel penetration.
Beijing-Tianjin-Hebei
Beijing tertiary hospital geroscience departments attract the highest R&D intensity for cognitive decline protocols leveraging conditional approval pathways. SAMR oversight of health claims constrains nutraceutical marketing, directing investment toward substantiated efficacy data. Tianjin manufacturing clusters face cleanroom energy cost pressures under municipal emissions reduction mandates.
Sichuan-Chongqing
Chengdu private WeChat communities replace hospital referrals as primary discovery channels for peptide interventions among affluent cohorts. GB standards harmonization for cell therapy manufacturing is eliminating redundant facility certifications across western provinces. Chongqing equipment vendors ship closed-system bioreactors to regional clinics with compressed delivery windows.
Shandong Peninsula
Qingdao biologics manufacturing bases confront input material concentration risks as fetal bovine serum supply concentrates among international vendors. NMPA post-market surveillance mandates favor sponsors with established regulatory affairs capabilities in the region. Jinan geriatric specialty clinics adopt point-of-care cell processing technologies to reduce centralized manufacturing dependency.
China Longevity and Anti-Senescence Therapy Market Competitive Landscape
Player mix skews toward diversified biopharma conglomerates with oncology-to-geroscience pipelines and traditional medicine houses repositioning classical formulations. Market structure exhibits tiered consolidation with premium biologics segments concentrating around clinical-stage developers and volume nutraceuticals fragmenting across direct-to-consumer brands. Two strategic archetypes dominate: CRO-enabled clinical trial sponsors leveraging regulatory expertise, and TCM-integrated consumer health platforms exploiting pharmacy distribution. Competitive moves center on strategic partnerships for IP licensing and backward integration into autologous cell processing infrastructure.
Among Beijing and Shanghai-based biopharma developers, BeiGene, Hangzhou Tigermed, and Tong Ren Tang occupy distinct archetype positions. BeiGene exemplifies the diversified R&D-intensive model spanning oncology into geroscience applications. Hangzhou Tigermed represents the CRO infrastructure play dominating trial services for longevity candidates. Tong Ren Tang anchors consumer trust archetypes through TCM-modern convergence strategies.
| Leading Market Players |
|---|
| Hangzhou Tigermed |
| Infinitus |
| AccurEdit Therapeutics |
| Luokang Gene |
| BeiGene |
| Yoltech Therapeutics |
| Tong Ren Tang |
| Zai Lab |
| Innovent Biologics |
| Others |
Pricing and Supply Chain Analysis
GB standards for cell therapy manufacturing gate both facility qualification and price differentiation simultaneously, compressing development timelines for sponsors with established quality systems while forcing rapid upgrades that concentrate margin pools among NMPA-preferred vendors.
Pricing Analysis
Cost-plus contracts with fetal bovine serum indexation dominate biologics manufacturing agreements. Three-tier pricing structure across premium autologous cell therapies, standard hormone replacement protocols, and economy nutraceutical tiers separates hospital-administered interventions from direct-to-consumer channels. Pricing pressure stems from SAMR health claim substantiation mandates extending payback periods for nutraceutical brands. Home users in Shenzhen and Chengdu exhibit highest price sensitivity, while Beijing and Shanghai geriatric clinics absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Inventory lead times for recombinant growth factors stretch 12-16 weeks due to international vendor concentration. Supply concentrates in United States, Australia, and New Zealand for fetal bovine serum; China and South Korea for bioreactor equipment; and Germany for closed-system processing technologies. Raw material dependencies center on fetal bovine serum, recombinant growth factors, and single-use bioreactor chambers. Single-source vulnerability from three international serum suppliers exposes margins to freight volatility and customs delays. Distribution runs through cold-chain logistics networks with 2-8°C integrity requirements, concentrating last-mile investment in eastern provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's longevity market represents a platform-economics inflection where telemedicine integration and direct-to-consumer genetic testing collapse the traditional clinic-centric patient acquisition model, creating interoperability between digital discovery channels and institutional treatment protocols.
For Market Incumbents: Shield market position by backward integration into autologous cell processing infrastructure at clinic scale, reducing dependency on centralized manufacturing. Secure NMPA accelerated approval pathway expertise through dedicated regulatory affairs investment, as post-market surveillance mandates favor sponsors with established capabilities. Counter emerging CRO-enabled competitors by locking exclusive partnerships with Hangzhou and Suzhou equipment vendors for closed-system bioreactor supply.
For New Entrants and Emerging Players: Lead with TCM-modern convergence strategies in the nutraceutical segment, where SAMR health claim friction has created white space for substantiated efficacy positioning. Target Chengdu and Chongqing second-tier cities where private WeChat communities have fragmented traditional hospital referral channels. Deploy direct-to-consumer genetic testing platforms as the primary patient acquisition engine before clinical validation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene therapy manufacturing due to MEE dual carbon goals reshaping cleanroom energy costs and facility siting decisions. Five-to-ten year viability hinges on identifying sponsors with Hainan Boao pilot zone access for accelerated import pathways. Signal to monitor: NMPA biosafety reclassification of autologous cell products as the inflection indicator for regulatory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | NMPA conditional approval pathways compress commercialization timelines for cognitive decline candidates. |
| Backward Integration | Point-of-care bioprocessing reduces dependency on fetal bovine serum supply concentration. |
| Regulatory Sandbox Entry | Hainan Boao pilot zone permits accelerated import of non-NMPA-approved longevity therapies. |
| Telemedicine Integration | Remote patient monitoring compresses consultation-to-treatment cycles for hormone protocols. |
| TCM Repositioning | Tong Ren Tang's classical formulations capture pharmacy shelf space through anti-senescence claims. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with NMPA regulatory affairs leads, geriatric clinic medical directors, bioreactor equipment vendors, cold-chain logistics operators, and SAMR compliance officers combined with FDA filings, NMPA technical guideline releases, ClinicalTrials.gov records, and GB standards documentation. Bottom-up patient volume estimates from hospital procurement databases triangulate with top-down market sizing from biologics manufacturing capacity disclosures.
Sensitivity analysis around NMPA approval timeline assumptions and MEE carbon intensity cap implementation frames the forecast uncertainty. Segmentation dimensions modeled include therapy type, application indication, delivery mode, and end-user channel across the projection horizon. CAGRs derive from patient population growth, pricing trajectory assumptions, and penetration rate modeling. Industry-specific inputs incorporate autologous cell processing adoption curves and telemedicine integration rates in tier-two cities.
The analysis sits within stated boundaries; outcomes outside NMPA regulatory pathway stability or MEE dual carbon goal enforcement intensity would require recalibration. Forecasts reflect documented assumptions about GB standards harmonization timelines and Hainan pilot zone expansion scope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
US Scar Treatment Market