
 Global Tourette Syndrome Treatment Market | 2026-2036
Global Tourette Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tourette Syndrome Treatment Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is consolidating procurement standards across European hospital networks. Neurocrine Biosciences dominates the vesicular monoamine transporter 2 inhibitor segment with its specialized neurology portfolio. Teva Pharmaceutical Industries leverages its generic manufacturing scale to sustain cost-competitive dopamine antagonist supply. AstraZeneca positions its emerging neuroscience pipeline through targeted psychiatric center partnerships.
Tourette syndrome treatment encompasses multimodal interventions targeting persistent motor and vocal tics through pharmacological modulation of dopaminergic and noradrenergic pathways, behavioral conditioning protocols, and neuromodulation techniques. Pharmacological treatment anchors current revenue pools through established alpha-2 adrenergic agonist and antipsychotic prescribing patterns, while deep brain stimulation represents the fastest-growing segment for severe refractory cases. Behavioral therapy commands premium reimbursement in specialized pediatric practices where comprehensive intervention protocols integrate habit reversal training with exposure and response prevention.
The FDA's orphan drug program shapes development economics through tax credits and market exclusivity incentives for novel Tourette syndrome therapies. EMA's pediatric investigation plan requirements drive trial design standards for juvenile tic disorder indications across European member states. Japan's PMDA neurology review pathway accelerates access for devices meeting designated severity thresholds. Stakeholders must monitor regulatory divergence between centralized FDA breakthrough therapy pathways and decentralized EU national health technology assessment processes.
Market Dynamics
The FDA's orphan drug designation pathway is concentrating development capital toward severe refractory tic disorders, compressing clinical trial timelines while fragmenting commercialization strategies across pediatric and adult patient populations.
Growth Catalysts
- EMA pediatric investigation plans:Juvenile tic disorder trials now follow standardized protocols across European member states, accelerating regulatory convergence for multinational sponsors.
- Deep brain stimulation:This neuromodulation technology is capturing severe refractory cases previously managed through chronic antipsychotic exposure, expanding addressable volumes in specialized movement disorder centers.
- United States reimbursement concentration:Centers of excellence in Boston, Houston, and Los Angeles aggregate payer expertise and patient volumes, creating predictable revenue pathways for protocol developers.
Market Restraints
- Alpha-2 agonist generic saturation:Guanfacine and clonidine formulations face commoditization pressure, eroding branded pricing power in first-line pediatric prescribing.
- Behavioral therapy labor intensity:Certified habit reversal training providers concentrate in metropolitan academic medical centers, constraining scalable access outside major urban corridors.
- Deep brain stimulation device supply:Neurostimulator manufacturing concentrates among three dominant suppliers, creating vulnerability to component shortages or regulatory holds.
Strategic Opportunities
- Japan PMDA neurology pathway:Designated severity thresholds for refractory movement disorders enable accelerated device approvals, opening premium pricing windows for neuromodulation entrants.
- Telehealth behavioral protocols:Remote delivery of comprehensive behavioral intervention for tics is penetrating rural and underserved pediatric populations previously excluded from specialist access.
- EU Green Deal pharmaceutical criteria:Sustainability procurement standards are consolidating hospital network purchasing, favoring suppliers with verified carbon footprint reductions in active pharmaceutical ingredient sourcing.
Industry Challenges
- Movement disorder specialist scarcity:Fellowship-trained pediatric neurologists with tic disorder expertise remain concentrated at academic institutions, limiting protocol standardization in community practice.
- Behavioral-pharmacological integration:Electronic health record fragmentation between mental health and neurology service lines obstructs coordinated care pathway implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tourette Syndrome Treatment Market |
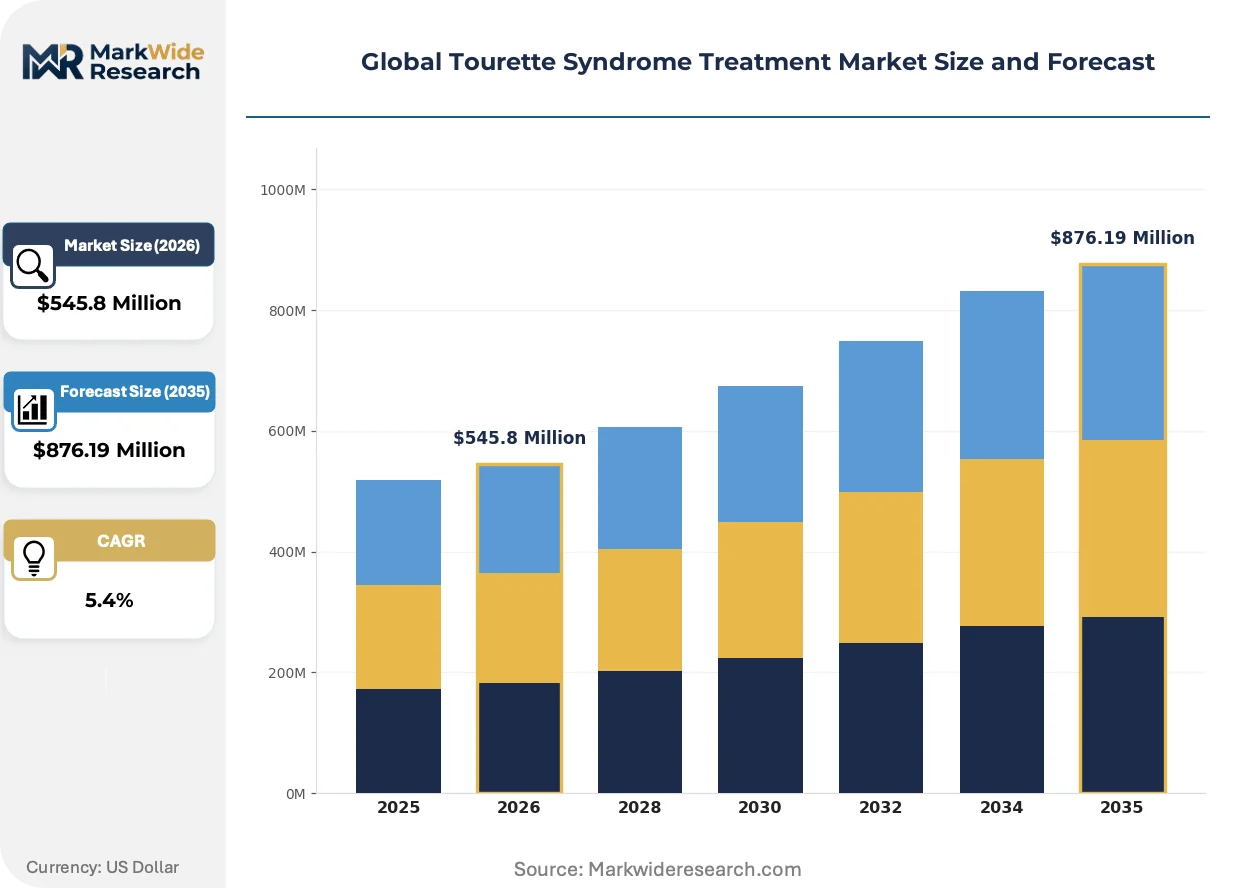
| Market Size in 2026 | $545.8 Million |
| Market Size in 2035 | $876.19 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behavioral Therapy, Pharmacological Treatment, Deep Brain Stimulation, Botulinum Toxin, Complementary Medicine Therapy Area: Motor Tics, Vocal Tics, Obsessive Compulsive Symptoms, Attention Deficit, Anxiety Disorders End User: Neurology Clinics, Psychiatric Centers, Rehabilitation Facilities, Pediatric Practices, Research Institutes Delivery Mode: Inpatient Care, Outpatient Services, Telemedicine, Home-based Care, Community Health Programs |
| Companies Covered | Neurocrine Biosciences Inc., AstraZeneca Plc, Teva Pharmaceutical Industries Ltd, Otsuka Holdings Co. Ltd, Reviva Pharmaceuticals Inc., Viatris Inc., Novartis AG, Catalyst Pharmaceuticals Inc., Emalex Biosciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tourette Syndrome Treatment Market Shifts & Advancements
Digital therapeutics and remote monitoring platforms are restructuring how tic severity is measured and intervention adherence is verified, compressing the feedback loop between clinical encounters.
Transcranial magnetic stimulation protocols for Tourette syndrome are overtaking chronic pharmacological management in treatment-resistant adolescent populations. Academic medical centers in Germany and the Netherlands are adopting these non-invasive neuromodulation approaches as first-line alternatives before antipsychotic exposure. The technology is overtaking deep brain stimulation candidacy assessments by reducing surgical referral volumes in moderate-severity cases.
REACH compliance requirements for pharmaceutical manufacturing are forcing active pharmaceutical ingredient suppliers to document full substance lifecycle environmental impact. European contract manufacturers are retrofitting production lines to meet ECHA registration thresholds for novel dopamine modulators. Pediatric formulation developers face extended qualification timelines as excipient sustainability credentials face heightened scrutiny.
Comprehensive intervention protocols now bundle habit reversal training with exposure and response prevention, displacing standalone pharmacological prescribing in affluent suburban pediatric practices. Parents are demanding documented functional outcome improvements rather than tic frequency reductions alone, reshaping provider reimbursement documentation requirements. This behavioral-first preference is most visible in United States markets with strong commercial insurance mental health parity enforcement.
Global Tourette Syndrome Treatment Market Segmentation
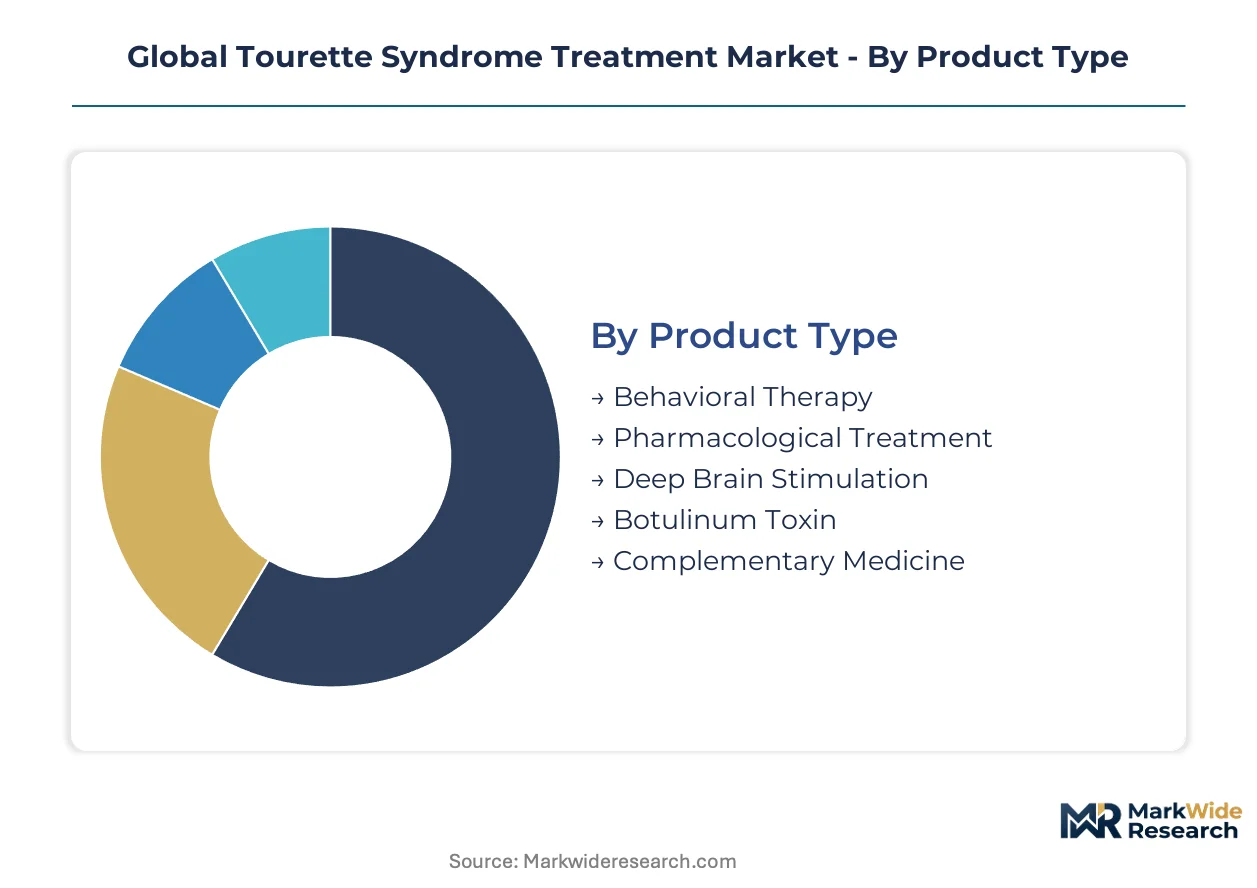
Treatment modality selection in Tourette syndrome hinges on tic severity, comorbidity burden, and patient age. Segmentation reveals where pharmacological dominance yields to behavioral and neuromodulation alternatives.
Product Type:
Standalone interventions operate independently while embedded protocols combine multiple therapeutic layers within single care pathways.
- Behavioral Therapy:Habit reversal training and exposure-response prevention protocols target tic suppression through conditioned response competing. Pediatric practices in Boston and Houston concentrate certified provider capacity, with commercial insurance parity enforcement driving reimbursement expansion.
- Pharmacological Treatment:Alpha-2 adrenergic agonists and antipsychotic dopamine antagonists modulate noradrenergic and dopaminergic pathways. Generic guanfacine and clonidine saturation in the United States erodes branded pricing power despite sustained first-line prescribing volume.
- Deep Brain Stimulation:Implantable neurostimulator systems target thalamic and pallidal nuclei for severe refractory cases. Germany's Charité and Netherlands movement disorder centers are expanding surgical candidacy assessments.
- Botulinum Toxin:Focal chemodenervation for isolated disabling motor tics. United States academic medical centers maintain injection expertise concentration.
- Complementary Medicine:Omega-3 supplementation and acupuncture protocols lacking FDA approval for tic disorder indications. Parental demand persists in California and New York wellness-oriented markets.
Pharmacological treatment leads volumes today; deep brain stimulation is gaining share fastest.
Therapy Area:
Symptom targeting determines reimbursement coding and specialist referral patterns across neurology and psychiatry service lines.
- Motor Tics:Persistent physical movements ranging from simple blinking to complex coordinated gestures. Deep brain stimulation candidacy assessments concentrate at United States centers of excellence in Los Angeles and Houston.
- Vocal Tics:Involuntary utterances including simple sounds and complex coprolalia. Transcranial magnetic stimulation protocols in Germany are displacing antipsychotic exposure for adolescent patients.
- Obsessive Compulsive Symptoms:Intrusive thoughts and ritualized behaviors complicating tic disorder management. Exposure and response prevention integration is reshaping pediatric practice protocols.
- Attention Deficit:Executive function impairment requiring stimulant or non-stimulant pharmacological coordination. Alpha-2 agonist overlap creates prescribing efficiency in combined presentations.
- Anxiety Disorders:Comorbid generalized and social anxiety amplifying tic severity perception. Behavioral therapy bundling is penetrating suburban United States practices with strong mental health parity.
Motor tics command the largest addressable population; obsessive compulsive symptoms are expanding most quickly as comorbidity recognition improves.
End User:
Care setting selection reflects symptom complexity, procedural requirements, and reimbursement infrastructure availability.
- Neurology Clinics:Fellowship-trained movement disorder specialists manage deep brain stimulation programming and pharmacological optimization. Patient volumes aggregate at Boston and Houston academic centers.
- Psychiatric Centers:Comprehensive behavioral intervention delivery and comorbidity management. Germany and Netherlands academic medical centers are adopting transcranial magnetic stimulation first-line protocols.
- Rehabilitation Facilities:Post-surgical neurostimulator programming and functional recovery support. Limited penetration outside major metropolitan corridors.
- Pediatric Practices:First-line behavioral and pharmacological intervention for juvenile tic disorders. EMA pediatric investigation plans are standardizing trial participation across European member states.
- Research Institutes:Clinical trial execution for novel neuromodulation and pharmacological candidates. FDA orphan drug designation is concentrating capital toward severe refractory indications.
Neurology clinics capture the highest procedural revenue per patient; pediatric practices are scaling fastest through telehealth behavioral protocol expansion.
Delivery Mode:
Site-of-care migration is compressing specialist access constraints while reshaping documentation and reimbursement requirements.
- Inpatient Care:Reserved for acute neurostimulator implantation and severe medication adjustment monitoring. United States centers of excellence maintain surgical volume concentration.
- Outpatient Services:Dominant setting for pharmacological management and behavioral therapy delivery. Reimbursement expertise clusters at academic medical centers in Los Angeles and Boston.
- Telemedicine:Remote behavioral intervention delivery penetrating rural United States populations previously excluded from specialist access. Parental demand is accelerating platform adoption.
- Home-based Care:Family-administered behavioral protocol reinforcement and medication adherence monitoring. Limited formal reimbursement infrastructure constrains scalable deployment.
- Community Health Programs:School-based tic disorder screening and initial intervention in underserved geographies. Sustainability depends on Medicaid reimbursement harmonization across United States states.
Outpatient services maintain volume leadership; telemedicine is climbing the fastest as regulatory flexibilities persist and platform capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tourette syndrome treatment protocols first achieved systematic standardization in the United States during the 1970s at specialized pediatric neurology centers. This foundational clinical infrastructure established reimbursement templates and specialist training curricula that subsequently diffused to European and Asian markets through academic exchange networks.
United States
Centers of excellence in Boston, Houston, and Los Angeles aggregate the majority of deep brain stimulation surgical volumes and pediatric behavioral therapy certification programs. FDA orphan drug designation accelerates development timelines for severe refractory tic disorder therapies through tax credit incentives. Massachusetts General Hospital and Baylor College of Medicine maintain the highest concentration of fellowship-trained movement disorder specialists.
Germany
Charité Universitätsmedizin Berlin and Netherlands-adjacent academic medical centers pioneer transcranial magnetic stimulation protocols as first-line alternatives to antipsychotic exposure. EMA pediatric investigation plans standardize juvenile tic disorder trial participation across member states. The country's REACH compliance requirements force active pharmaceutical ingredient suppliers to document full substance lifecycle environmental impact.
Japan
PMDA neurology review pathway accelerates device approvals for refractory movement disorders meeting designated severity thresholds. METI coordinates domestic manufacturing scale for neurostimulator components. Tokyo and Osaka metropolitan areas concentrate pediatric neurologist expertise and university hospital-based deep brain stimulation candidacy assessments.
United Kingdom
NHS England specialized commissioning frameworks concentrate Tourette syndrome treatment at designated tertiary centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory autonomy enables faster adoption of novel neuromodulation devices compared to EMA centralized procedures. Great Ormond Street Hospital maintains Europe's largest pediatric tic disorder behavioral therapy program.
Canada
Health Canada harmonizes device approval pathways with FDA breakthrough therapy designations, compressing market access timelines for neurostimulator systems. Provincial health technology assessment processes in Ontario and British Columbia determine reimbursement for deep brain stimulation in severe refractory cases. The Hospital for Sick Children in Toronto anchors pediatric neurology training for North American specialists.
Global Tourette Syndrome Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the behavioral-pharmacological integration capability spectrum. The vendor base stratifies between specialized neurology biotechs with orphan drug portfolios and generic manufacturers sustaining cost-competitive dopamine antagonist supply. Three archetypes dominate: VMAT2 inhibitor specialists, diversified neurology portfolio holders, and generic scale operators. Consolidation pressures intensify through strategic partnerships between device manufacturers and academic medical centers, while portfolio diversification into digital therapeutics represents the second dominant competitive vector.
Within the specialized neurology biotech tier, Neurocrine Biosciences Inc. exemplifies VMAT2 inhibitor market concentration through its dedicated movement disorder focus. Among diversified pharmaceutical conglomerates, AstraZeneca Plc and Novartis AG occupy positions spanning neuroscience pipeline development through targeted psychiatric center partnerships. At the generic manufacturing scale end, Teva Pharmaceutical Industries Ltd anchors cost-competitive supply for established alpha-2 agonist and antipsychotic formulations.
| Leading Market Players |
|---|
| Neurocrine Biosciences Inc. |
| AstraZeneca Plc |
| Teva Pharmaceutical Industries Ltd |
| Otsuka Holdings Co. Ltd |
| Reviva Pharmaceuticals Inc. |
| Viatris Inc. |
| Novartis AG |
| Catalyst Pharmaceuticals Inc. |
| Emalex Biosciences Inc. |
| Others |
Supply & Pricing Matrix
Academic medical center procurement departments in the United States concentrate purchasing power for deep brain stimulation systems and branded neuromodulation devices, anchoring contract-based pricing that favors multi-year service bundles over per-procedure transactional models. This buyer concentration creates divergent pricing dynamics across behavioral therapy delivery, where labor intensity sustains premium reimbursement, and generic pharmacological segments facing commoditization pressure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates implantable neurostimulator systems from transcranial magnetic stimulation protocols and generic alpha-2 agonist formulations. Price differentiation hinges on FDA breakthrough therapy designation status and after-sales programming support intensity. Cost compression in first-line pediatric pharmacology is intensifying because guanfacine and clonidine generic saturation erodes branded pricing power. Community pediatric practices exhibit highest price sensitivity, while movement disorder centers of excellence demonstrate lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and the United States maintain hub-and-spoke patterns for neurostimulator device deployment, with Tokyo and Osaka hubs serving Japanese metropolitan demand. Active pharmaceutical ingredient sourcing draws from India and China for dopamine modulator precursors, while neurostimulator component manufacturing rests on Japanese and German precision electronics suppliers. Single-source vulnerability concentrates in implantable pulse generator microelectronics, where three dominant suppliers control thalamic targeting system production. Distribution runs through academic medical center procurement consortia rather than wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tourette syndrome treatment market compounds steadily through orphan drug designation incentives that compress development timelines and sustain premium pricing for severe refractory indications. Pediatric neurology practice expansion and telehealth behavioral protocol penetration provide durable volume growth foundations.
For Market Incumbents: Anchor defensive positioning through backward integration into active pharmaceutical ingredient sourcing for VMAT2 inhibitors, securing supply continuity against REACH compliance disruptions. Deepen habit reversal training certification program control in Boston and Houston academic centers to obstruct emerging telehealth platform encroachment. Prioritize FDA breakthrough therapy pathway maintenance for pipeline assets targeting refractory vocal tic disorders. For New Entrants and Emerging Players: Telehealth behavioral protocol platforms represent the most penetrable route into rural United States pediatric populations previously excluded from specialist access. Target school-based screening and initial intervention programs in Medicaid-dependent geographies where community health program infrastructure remains underdeveloped. Pursue reimbursement strategy partnerships with commercial insurers enforcing mental health parity mandates. For Investors and Strategic Acquirers: Diversified neurology portfolio holders are the most active acquirer in this space, seeking VMAT2 inhibitor specialists and digital therapeutic platforms to fill pipeline gaps. The five-to-ten year viability window favors assets with demonstrated pediatric investigation plan execution and EMA regulatory convergence capability. Monitor FDA orphan drug designation grant velocity as inflection indicator for development capital flow intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA pediatric investigation plan compliance accelerates multinational juvenile tic disorder trial enrollment across European member states. |
| Regulatory Approval Pathway | FDA orphan drug designation unlocks tax credit incentives and market exclusivity for severe refractory tic disorder therapies. |
| Hospital System Partnership | Academic medical center alliances in Boston and Houston aggregate deep brain stimulation surgical volumes and payer expertise. |
| Software Companion Development | Digital therapeutics integration with habit reversal training protocols enables remote tic severity monitoring and adherence verification. |
| Reimbursement Strategy | Mental health parity enforcement in commercial insurance markets expands behavioral therapy premium reimbursement coverage. |
Research Methodology
Bottom-up pediatric practice and neurology clinic modeling reconciled against top-down pharmaceutical and device manufacturer supply tracking forms the analytical core of this study. Primary interviews with pediatric neurologists, movement disorder specialists, hospital procurement managers, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Triangulation between demand-side patient volume estimates and supply-side production capacity disclosures ensures cross-verified output integrity.
Historical trendline analysis of alpha-2 agonist prescribing patterns, deep brain stimulation surgical volumes, and behavioral therapy reimbursement rates established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated treatment modality, therapy area targeting, end-user setting, and delivery mode dimensions with regional regulatory cluster differentiation. CAGRs were derived from fitted trend extrapolation adjusted for orphan drug designation acceleration effects and telehealth penetration curve assumptions.
The model assumes a particular technology adoption path; alternative pathways for transcranial magnetic stimulation first-line positioning would alter the outlook for antipsychotic exposure rates and deep brain stimulation candidacy volumes. Forecasts reflect documented assumptions regarding EMA regulatory convergence timelines and FDA breakthrough therapy grant velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cubital Tunnel Syndrome Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Allergic Conjunctivitis Market