
 Cartilage Degeneration Market | 2026-2036
Cartilage Degeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Cartilage Degeneration Market Analysis
Hospital procurement of cartilage repair solutions is fragmenting as ambulatory surgical centers and specialized orthopedic clinics gain direct purchasing power. Zimmer Biomet Holdings, Inc. leverages its integrated implant portfolio to sustain relationships with integrated delivery networks. Stryker Corporation anchors its position through arthroscopy system placements that lock in consumable demand. Smith & Nephew plc differentiates via its sports medicine focus, competing for surgeon training allegiance rather than price alone.
Cartilage degeneration encompasses the progressive breakdown of articular hyaline cartilage, the avascular connective tissue comprising type II collagen and proteoglycan aggregates that cushions synovial joints and enables low-friction articulation. Its primary commercial purpose centers on restoring joint function and delaying or preventing total joint arthroplasty in osteoarthritic and traumatic chondral defect populations. Hyaluronic acid viscosupplementation occupies the largest revenue pool among product types, though stem cell therapy represents the fastest-expanding segment as regulatory clarity improves. Arthroscopy dominates technology deployment in hospital settings, while 3D bioprinting of scaffold-based constructs commands premium positioning in academic medical centers.
The FDA's regenerative medicine advanced therapy designation and the European Medicines Agency's adaptive pathway framework shape clinical trial design and commercialization timelines for cell-based cartilage products. ISO 14155 standards govern Good Clinical Practice for device trials, while the EU Medical Device Regulation imposes stricter post-market surveillance on implantable scaffolds. Stakeholders must monitor reimbursement decisions by CMS and parallel bodies, as coverage determinations for autologous chondrocyte implantation and emerging stem cell protocols will determine addressable patient volumes regardless of technical efficacy.
Market Dynamics
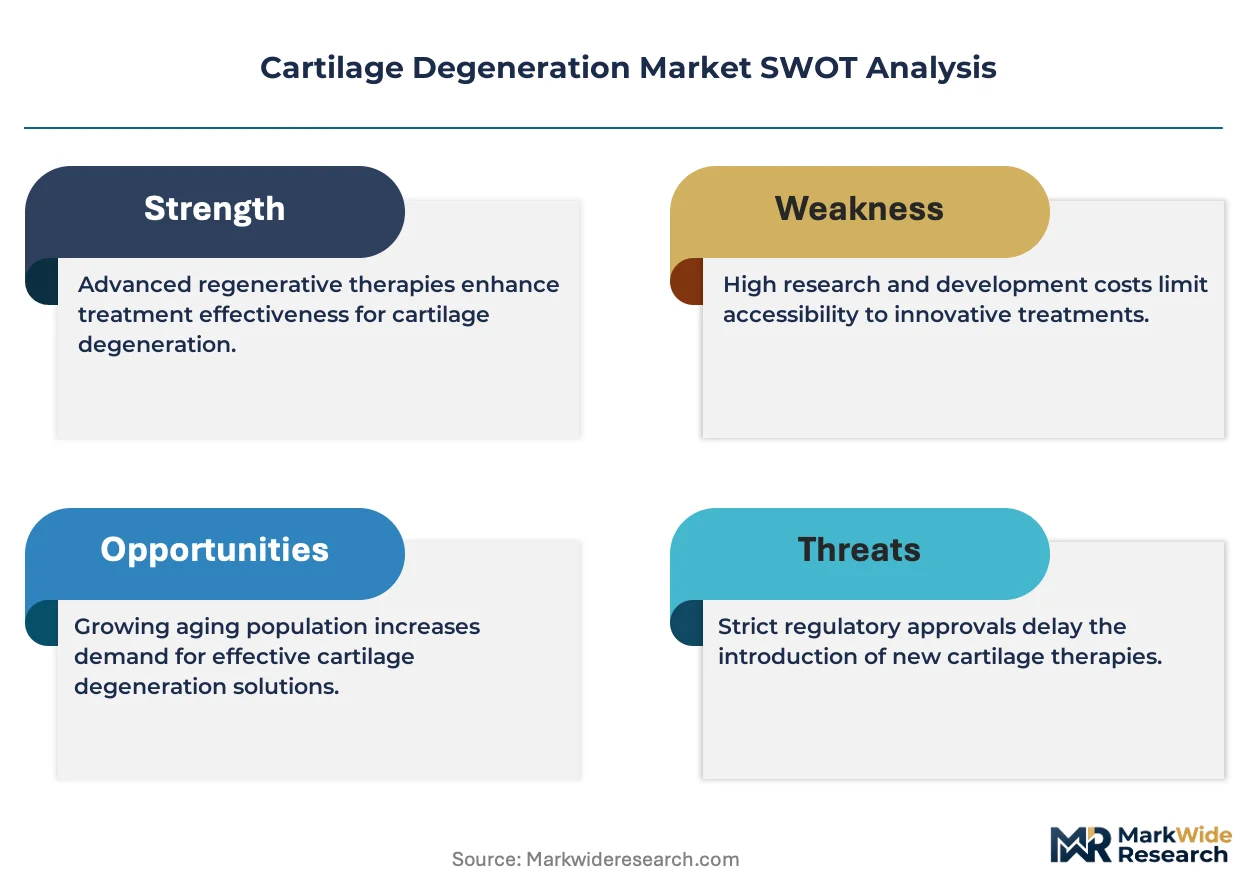
The FDA's regenerative medicine advanced therapy designation is compressing development timelines for cell-based cartilage products while simultaneously fragmenting procurement authority across ambulatory surgical centers and hospital networks.
Growth Catalysts
- EMA Adaptive Pathway Framework:The European Medicines Agency's streamlined approval mechanism accelerates conditional market authorization for autologous chondrocyte implantation products in Germany, France, and the Netherlands.
- Sports Medicine Facility Expansion:Dedicated orthopedic clinics in the United States are deploying arthroscopy suites with integrated biologics preparation stations, expanding addressable procedure volumes beyond traditional hospital settings.
- Hyaluronic Acid Viscosupplementation:This established injectable therapy maintains broad payer coverage and serves as a gateway intervention that builds physician familiarity with joint preservation protocols.
Market Restraints
- Reimbursement Uncertainty:CMS coverage determinations for autologous chondrocyte implantation remain inconsistent across Medicare Administrative Contractor jurisdictions, creating demand volatility.
- Supply Concentration in Scaffold Materials:Type I/III collagen matrices and hyaluronic acid raw materials depend on a limited supplier base concentrated in Switzerland and Italy.
- Total Knee Arthroplasty Substitution:Mature implant technologies with predictable outcomes continue to capture patients who might otherwise pursue cartilage preservation.
Strategic Opportunities
- Underpenetrated Japanese Market:Japan's aging demographic and PMDA's Sakigake designation system create favorable regulatory conditions for novel cell therapy entrants.
- 3D Bioprinting Convergence:Integration of additive manufacturing with induced pluripotent stem cell protocols enables patient-specific scaffold geometries at academic medical centers.
- Direct-to-Employer Contracting:Self-insured corporations in the United States are negotiating bundled payment arrangements for outpatient cartilage repair procedures.
Industry Challenges
- Cell Processing Technician Scarcity:Good Manufacturing Practice-compliant cleanroom operations require specialized training that outpaces current certification program output.
- ISO 14155 Compliance Burden:Device trial documentation requirements extend study initiation timelines and inflate clinical development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartilage Degeneration Market |
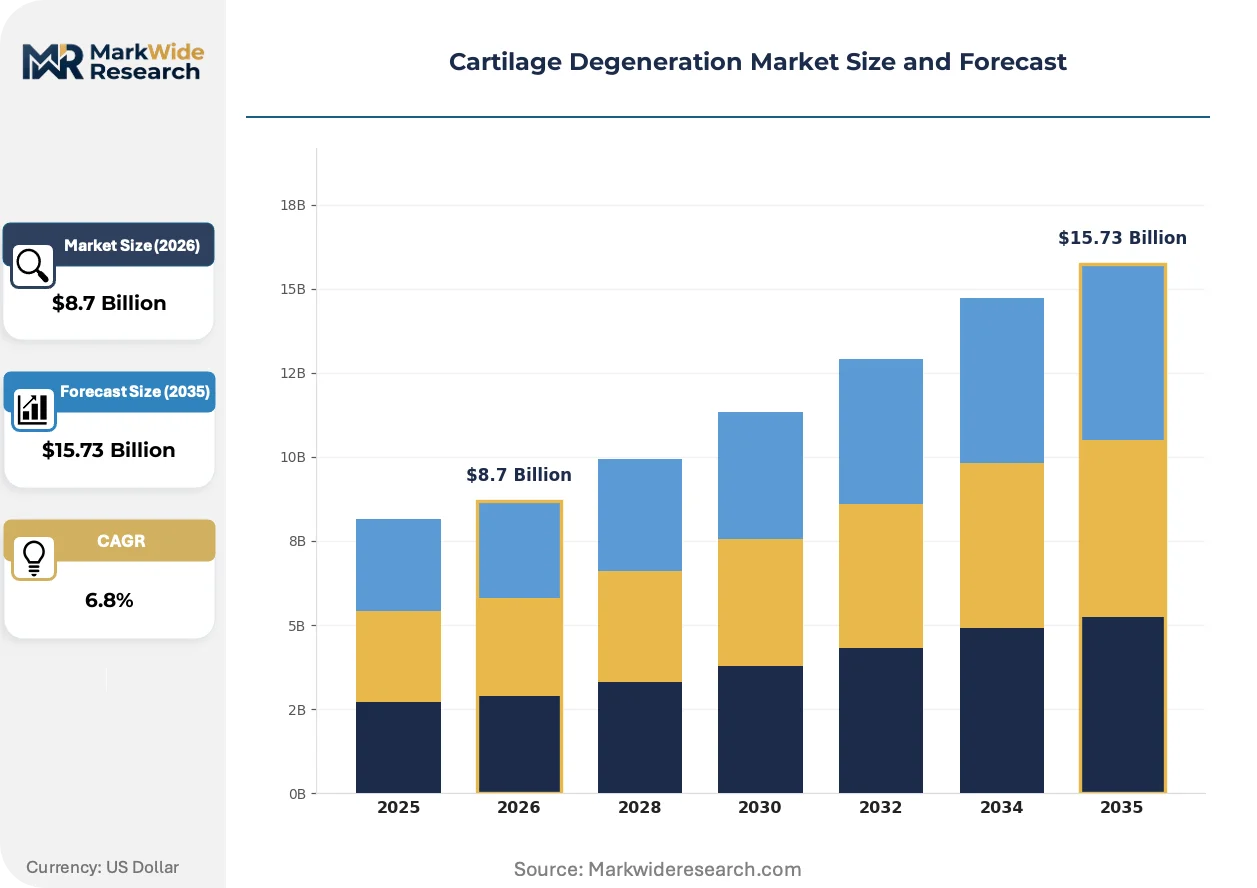
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Autologous Chondrocyte Implantation, Stem Cell Therapy, Biomaterials End User: Orthopedic Clinics, Rehabilitation Centers, Hospitals, Sports Medicine Facilities Treatment Approach: Physical Therapy, Surgical Intervention, Medication Management, Regenerative Medicine Technology: 3D Bioprinting, Arthroscopy, Nanotechnology, Tissue Engineering |
| Companies Covered | Zimmer Biomet Holdings, Inc., Stryker Corporation, Smith & Nephew plc, Johnson & Johnson (DePuy Synthes), Vericel Corporation, Anika Therapeutics, Inc., B. Braun SE, Arthrex, Inc., Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartilage Degeneration Market Emerging Trajectories
Digital integration across surgical planning, patient-specific implant fabrication, and post-procedure monitoring is compressing the traditional cartilage repair value chain from diagnosis to rehabilitation.
Artificial intelligence-powered imaging analysis is digitizing chondral defect assessment by automating lesion volume calculation from MRI sequences. Orthopedic surgeons in academic medical centers are adopting these tools for preoperative planning at accelerating rates. The technology is digitizing the transition from subjective arthroscopic grading to quantitative outcome prediction.
Europe's Medical Device Regulation imposes enhanced post-market surveillance requirements on implantable scaffolds and cell-seeded constructs. Manufacturers must maintain systematic clinical follow-up registries that extend five years beyond commercial launch. Small-to-mid-sized developers in Germany and the Netherlands are responding by partnering with contract research organizations to manage data collection infrastructure.
Hospital supply chains are disintermediating traditional distributor relationships as ambulatory surgical centers negotiate direct purchasing agreements with biologics manufacturers. Independent orthopedic clinics in Texas, Florida, and Arizona are consolidating procurement through group purchasing organizations. This channel restructuring is most visible in the United States, where certificate-of-need restrictions on outpatient surgery have relaxed in multiple states.
Cartilage Degeneration Market Segmentation
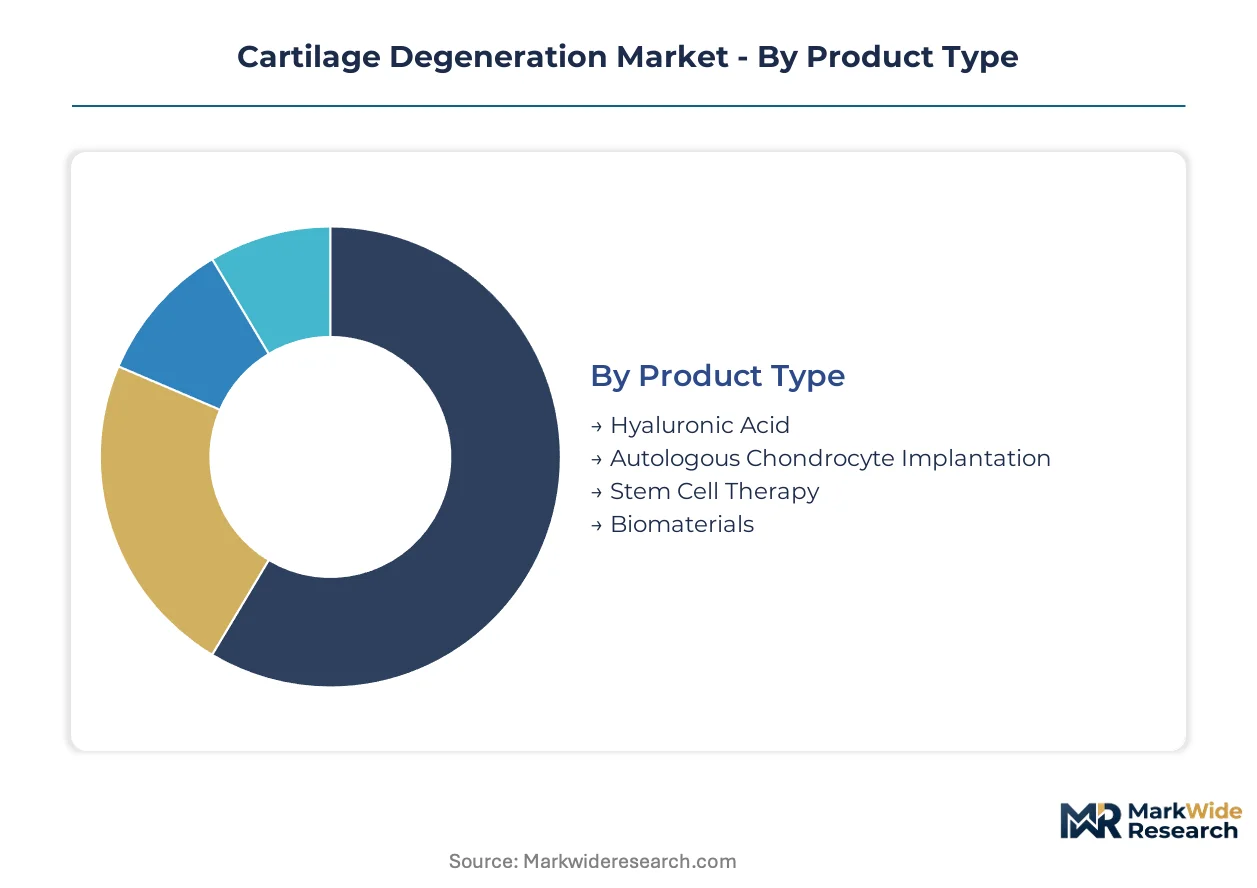
Cartilage degeneration therapies fragment across four distinct dimensions that determine pricing power, regulatory pathway, and site-of-service economics. Each segmentation axis reveals divergent margin profiles and competitive intensity that shape portfolio allocation decisions.
Product Type:
Cycle times vary dramatically — hyaluronic acid injections turn over in weeks while cell-based therapies require months from biopsy to implantation.
- Hyaluronic Acid:Viscosupplementation formulations derived from rooster comb or bacterial fermentation provide immediate symptom relief through joint lubrication. Demand concentrates in United States ambulatory surgical centers where CMS coverage creates predictable reimbursement.
- Stem Cell Therapy:Mesenchymal stromal cell and adipose-derived protocols represent the steepest expansion trajectory as FDA regenerative medicine advanced therapy designation compresses development timelines. Academic medical centers in Germany and the Netherlands are piloting commercial-scale production.
- Autologous Chondrocyte Implantation:Two-stage surgical procedure involving cartilage biopsy, cell expansion, and reimplantation.
- Biomaterials:Collagen and hyaluronic acid scaffolds for defect filling.
Hyaluronic acid dominates installed base. Stem cell therapy is where expansion concentrates.
End User:
Procurement authority is shifting toward outpatient venues that can bundle facility and physician fees.
- Sports Medicine Facilities:Dedicated orthopedic clinics with arthroscopy suites and in-house biologics preparation capture high-margin procedures. Texas, Florida, and Arizona have seen concentrated facility openings as certificate-of-need restrictions relax.
- Orthopedic Clinics:Independent practices consolidating through group purchasing organizations negotiate direct manufacturer contracts. These settings favor hyaluronic acid and emerging cell therapies over hospital-based surgical intervention.
- Hospitals:Integrated delivery networks maintain volume for complex ACI procedures requiring operating room infrastructure.
- Rehabilitation Centers:Post-surgical and non-operative care settings focusing on physical therapy protocols.
Sports medicine facilities are gaining share fastest. Hospitals retain the deepest procedure complexity.
Treatment Approach:
Margin structures diverge sharply between device-intensive surgical pathways and recurring pharmaceutical administration.
- Surgical Intervention:Arthroscopic debridement, microfracture, and autologous chondrocyte implantation generate single-episode revenue concentrated at academic medical centers. Stryker and Zimmer Biomet anchor demand through system placements.
- Regenerative Medicine:Cell therapy and tissue engineering protocols command premium pricing with multi-year outcome follow-up requirements under EU Medical Device Regulation.
- Physical Therapy:Conservative management protocols delaying surgical intervention.
- Medication Management:Oral NSAIDs and intra-articular corticosteroid injections.
Surgical intervention captures the highest per-procedure value. Regenerative medicine is climbing the fastest.
Technology:
Capital intensity separates scalable platforms from bespoke academic production.
- Arthroscopy:Minimally invasive joint visualization and instrumentation constitutes the dominant installed base. Smith & Nephew competes for surgeon training allegiance through dedicated sports medicine curricula.
- 3D Bioprinting:Additive manufacturing of patient-specific scaffolds with induced pluripotent stem cell integration remains concentrated at academic medical centers in Germany, Japan, and the United States.
- Tissue Engineering:Bioreactor-based cell expansion and scaffold seeding.
- Nanotechnology:Nanofiber and nanoparticle delivery systems.
Arthroscopy dominates procedure volume. 3D bioprinting is where R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's regenerative medicine advanced therapy designation anchors commercial momentum in the United States, while EMA adaptive pathways and Japan's PMDA Sakigake system create parallel acceleration corridors for cell-based cartilage products across three continents.
United States
Orthopedic clinic networks in Texas, Florida, and Arizona drive procedure volumes as certificate-of-need restrictions relax. CMS coverage determinations for autologous chondrocyte implantation vary across Medicare Administrative Contractor jurisdictions, creating demand volatility. Academic medical centers in Boston and Stanford anchor 3D bioprinting pilot programs for patient-specific scaffold fabrication.
Germany
Hospital procurement fragmentation favors ambulatory surgical centers negotiating direct biologics contracts. EMA's adaptive pathway framework accelerates conditional market authorization for autologous chondrocyte implantation products. The Cologne-Düsseldorf corridor concentrates contract research organizations managing post-market surveillance registries under EU Medical Device Regulation.
Japan
Aging demographics and osteoarthritis prevalence expand addressable patient populations for joint preservation protocols. PMDA's Sakigake designation system compresses review timelines for novel cell therapy entrants. Tokyo and Osaka academic medical centers pilot commercial-scale mesenchymal stromal cell production with METI funding support.
Netherlands
Sports medicine facilities integrate arthroscopy suites with in-house biologics preparation stations. EMA centralized procedures enable simultaneous market access across member states for scaffold-based constructs. The Eindhoven-Leiden corridor concentrates tissue engineering startups leveraging ISO 14155-compliant clinical trial infrastructure.
Switzerland
Type I/III collagen matrix suppliers anchor raw material concentration for scaffold manufacturing. Swissmedic maintains alignment with EU Medical Device Regulation for market access continuity. Basel and Zurich host specialized cleanroom operations producing Good Manufacturing Practice-compliant cell expansion media.
Cartilage Degeneration Market Vendor Landscape
Integrated implant conglomerates and dedicated sports medicine specialists split the market between system-driven lock-in strategies and surgeon training allegiance models. The vendor base concentrates around three strategic archetypes: diversified orthopedic conglomerates with arthroscopy platform control, pure-play biologics developers pursuing regenerative medicine advanced therapy pathways, and specialized sports medicine houses competing on procedural volume capture. Dominant competitive moves include backward integration into scaffold material supply and strategic partnerships with academic medical centers for clinical trial site designation.
Within the diversified conglomerate tier, Zimmer Biomet Holdings, Inc. and Stryker Corporation occupy positions defined by integrated implant portfolio breadth and arthroscopy system placement density. Smith & Nephew plc exemplifies the sports medicine specialist archetype, competing through dedicated surgeon training curricula rather than price-based positioning alone.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings, Inc. |
| Stryker Corporation |
| Smith & Nephew plc |
| Johnson & Johnson (DePuy Synthes) |
| Vericel Corporation |
| Anika Therapeutics, Inc. |
| B. Braun SE |
| Arthrex, Inc. |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Swiss and Italian collagen matrix suppliers determines both tiered pricing spreads and supply chain configuration across the cartilage degeneration market. FDA regenerative medicine advanced therapy designation timelines and EMA adaptive pathway conditional approvals compress procurement windows, forcing manufacturers to pre-position premium-priced scaffold inventories while standard hyaluronic acid formulations compete on volume scale.
Pricing Analysis
Customization-premium spreads separate patient-specific 3D bioprinted constructs from standard hyaluronic acid viscosupplementation. Three-tier pricing structure across premium, standard, and economy levels reflects FDA tier certification, ISO 14155 compliance grade, and surgeon training allegiance. Pricing pressure stems from CMS coverage inconsistency across Medicare Administrative Contractor jurisdictions, compressing margins on autologous chondrocyte implantation. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers absorb premium positioning for regenerative protocols.
Supply Chain Analysis
Contract manufacturing concentration rests on Lonza's cell therapy production network and Catalent's biologics fill-finish capacity. Raw material sourcing draws from Switzerland and Italy for Type I/III collagen matrices, with hyaluronic acid fermentation concentrated in bacterial production facilities across Germany and the Netherlands. Single-source vulnerability in scaffold materials exposes manufacturers to Swissmedic alignment delays with EU Medical Device Regulation. Distribution runs through hospital networks disintermediating toward direct ambulatory surgical center contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in sports medicine facility expansion as certificate-of-need relaxation across Texas, Florida, and Arizona creates procurement authority niches outside traditional hospital networks.
For Market Incumbents: Entrench system placement lock-in through arthroscopy platform density at orthopedic clinic networks. Backward integration into collagen matrix supply from Swiss raw material producers defends margin position against emerging biologics developers. Prioritize FDA regenerative medicine advanced therapy designation capture to compress competitor development timelines.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-employer bundled payment contracting for outpatient cartilage repair procedures. Target Japanese market entry under PMDA Sakigake designation, where aging demographics and METI funding support commercial-scale mesenchymal stromal cell production. Deploy surgeon training allegiance models competing on procedural curriculum rather than price-based positioning.
For Investors and Strategic Acquirers: FDA regenerative medicine advanced therapy designation reshapes the acquisition landscape by compressing time-to-revenue for cell-based cartilage products. Five-to-ten year viability favors pure-play biologics developers with cleanroom operations and ISO 14155-compliant clinical trial infrastructure. Monitor CMS national coverage determination signals for autologous chondrocyte implantation as reimbursement inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Medicine Advanced Therapy Designation | FDA pathway compression accelerates cell-based product commercialization timelines for developers. |
| Backward Integration into Scaffold Supply | Captive collagen matrix production insulates margin from Swiss-Italian raw material concentration risk. |
| Direct-to-Employer Contracting | Self-insured corporations in United States bypass traditional payer fragmentation for outpatient procedures. |
| 3D Bioprinting Platform Deployment | Patient-specific scaffold fabrication commands premium positioning at academic medical centers. |
| Surgeon Training Curriculum Investment | Sports medicine allegiance models lock in procedure volume through education-based differentiation. |
Methodological Framework
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital procurement managers, GPO contracts specialists, and cell processing technicians and refined through secondary validation across FDA 510(k) filings, EMA centralized procedure decisions, CMS Medicare coverage databases, and ISO 14155 clinical trial registries. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework across product type, end-user venue, treatment approach, and technology platform dimensions throughout the forecast period. CAGRs derived from procedure volume trajectories, pricing tier migration patterns, and reimbursement expansion assumptions. Industry-specific inputs incorporated arthroscopy system placement data and biologics preparation station deployment rates at sports medicine facilities.
Stress conditions across CMS coverage determination timing, EU Medical Device Regulation enforcement intensity, and collagen matrix supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway acceleration and reimbursement expansion. Quarterly review of FDA regenerative medicine advanced therapy designation grants and CMS national coverage determinations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market