
 Longevity and Anti-Senescence Therapy for Cancer Market | 2026-2036
Longevity and Anti-Senescence Therapy for Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Longevity and Anti-Senescence Therapy for Cancer Market Foresight
Good Manufacturing Practice certification for advanced therapy medicinal products is unwinding competitive access for smaller entrants. Unity Biotechnology leverages proprietary senolytic platforms to anchor its position in p16-positive cell clearance. Calico Life Sciences sustains deep R&D intensity through its Alphabet-backed structure. Altos Labs dominates cellular reprogramming approaches with significant laboratory investment.
Longevity and anti-senescence therapy for cancer encompasses biologic and small-molecule interventions designed to selectively eliminate or reprogram senescent cells that drive tumor microenvironment inflammation and therapeutic resistance. These therapies typically target senescence-associated secretory phenotype pathways, with formulations requiring cold-chain distribution and sterile manufacturing conditions to maintain viability. Biologics and gene therapies capture concentrated margin pools due to manufacturing complexity and patent protection, while small molecules compete on scalability and oral delivery compatibility. CRISPR and immune modulation technologies attract the fastest-growing development investment, though telomere extension approaches remain earlier in clinical translation.
The FDA's accelerated approval framework and EMA's ATMP classification system jointly shape trial design requirements and market access timelines for senescence-targeting candidates. HIPAA compliance obligations and institutional review board protocols further constrain how hospitals and research institutions adopt experimental protocols. Stakeholders must monitor how regulators reconcile longevity mechanisms with traditional oncology endpoints as the field matures beyond preclinical proof-of-concept.
Market Dynamics
The FDA's accelerated approval framework for oncology biologics is compressing development timelines and forcing developers to front-load manufacturing investments before pivotal trial readouts, reshaping capital deployment across the senescence-targeting landscape.
Growth Catalysts
- ATMP Classification:The EMA's advanced therapy medicinal product pathway streamlines market access for cellular reprogramming candidates, reducing regulatory uncertainty for European developers.
- Oncology Clinic Expansion:University hospitals in Germany are anchoring early-phase senolytic trials, creating concentrated demand for p16-targeted clearance protocols.
- Cold-Chain Infrastructure:Biologics distribution networks are maturing across the United States, enabling wider site activation for temperature-sensitive senescence therapies.
Market Restraints
- GMP Certification Barriers:Good Manufacturing Practice requirements for advanced therapy medicinal products impose capital thresholds that filter smaller entrants from commercial-scale production.
- Sterile Manufacturing Concentration:Contract development and manufacturing organizations with cell therapy expertise cluster in Massachusetts and California, creating geographic supply risk.
- Telomere Extension Limitations:Clinical translation of telomerase activation remains stalled by oncogenic transformation concerns, constraining pipeline diversification.
Strategic Opportunities
- Japan's Regenerative Medicine Framework:PMDA's conditional approval pathway offers accelerated timelines for cellular reprogramming candidates, attracting laboratory investment from foreign developers.
- CRISPR-Senolytic Convergence:Gene editing platforms targeting senescence-associated secretory phenotype regulators are opening programmable clearance mechanisms beyond small-molecule constraints.
- Academic Medical Center Partnerships:Research institutions are emerging as preferred trial sponsors, bypassing traditional pharmaceutical channel structures for patient recruitment.
Industry Challenges
- Cellular Reprogramming Expertise Gap:The intersection of developmental biology and oncology clinical development commands premium compensation, constraining talent acquisition for mid-stage companies.
- HIPAA-Compliant Data Integration:Real-world evidence collection for senescence biomarker validation requires costly infrastructure upgrades at hospital sites running experimental protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Longevity and Anti-Senescence Therapy for Cancer Market |
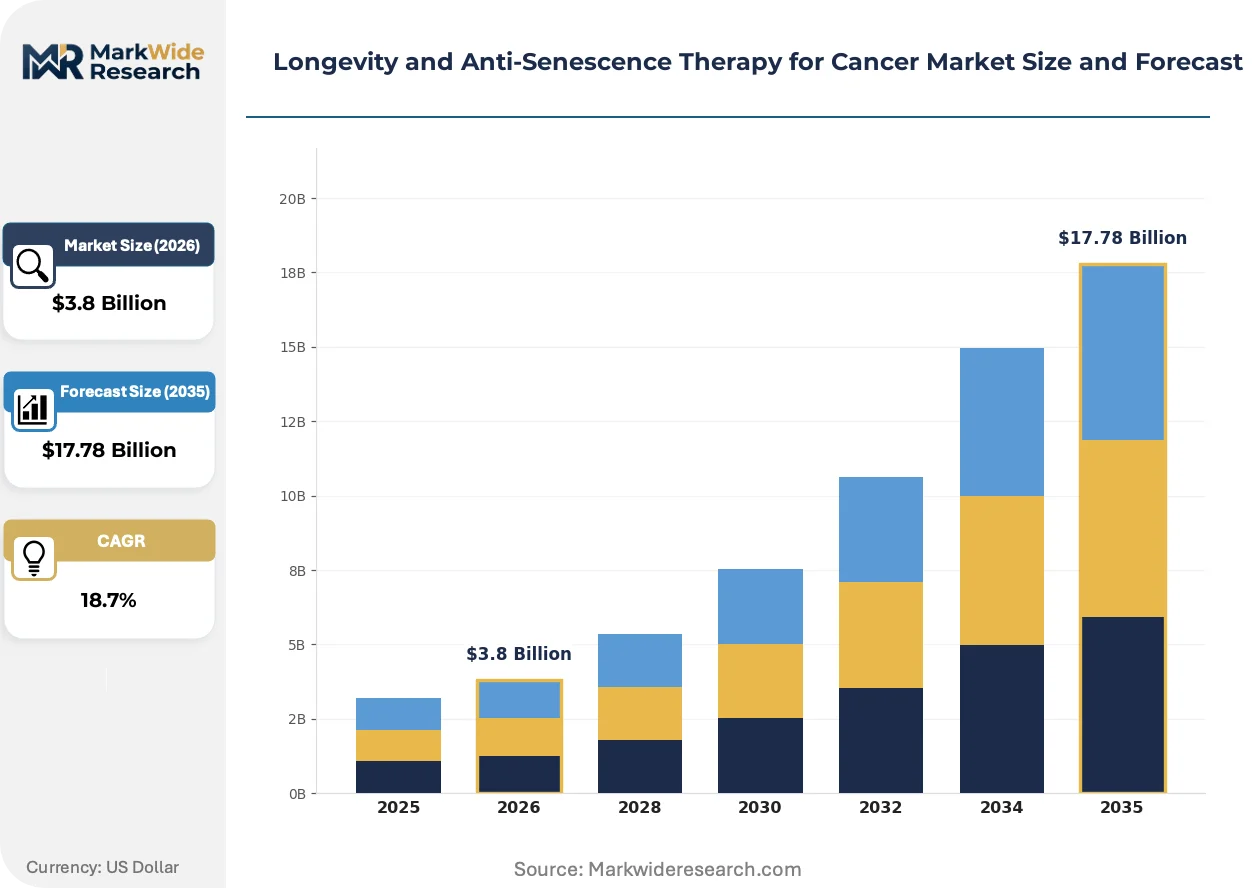
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Supplements, Gene Therapies Technology: CRISPR, RNA Interference, Immune Modulation, Telomere Extension Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal End User: Research Institutions, Hospitals, Clinics, Pharmaceutical Companies |
| Companies Covered | Unity Biotechnology, Calico Life Sciences, Altos Labs, Life Biosciences, Insilico Medicine, AgeX Therapeutics, Rubedo Life Sciences, Retro Biosciences, Oisin Biotechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Longevity and Anti-Senescence Therapy for Cancer Market Shifts & Advancements
Cellular reprogramming technologies are displacing legacy senolytic small molecules as the dominant platform architecture, while regulatory frameworks race to accommodate mechanism-based endpoints that diverge from traditional tumor response metrics.
Immune-modulating senolytics that engage natural killer cell clearance pathways are displacing apoptosis-inducing compounds in preclinical portfolios. Oncology biotechs are prioritizing these candidates for combination with checkpoint inhibitors. The shift is compressing development timelines for p53-independent clearance mechanisms while raising manufacturing complexity for multi-specific formats.
REACH authorization requirements for novel biologic intermediates are tightening supply chain documentation obligations for European manufacturers. The regulation forces developers to map substance origins through contract research organization networks. Cell therapy sponsors with captive chemistry capabilities are absorbing compliance costs that fragment smaller competitors.
Hospital procurement committees are consolidating vendor relationships for senescence-targeting trials, favoring integrated service providers over fragmented supplier networks. Academic medical centers in the United States are negotiating preferred partnerships with CDMOs offering end-to-end ATMP manufacturing. The concentration is visible in Boston and San Francisco, where institutions are locking multi-year capacity reservations ahead of pivotal studies.
Longevity and Anti-Senescence Therapy for Cancer Market Segmentation
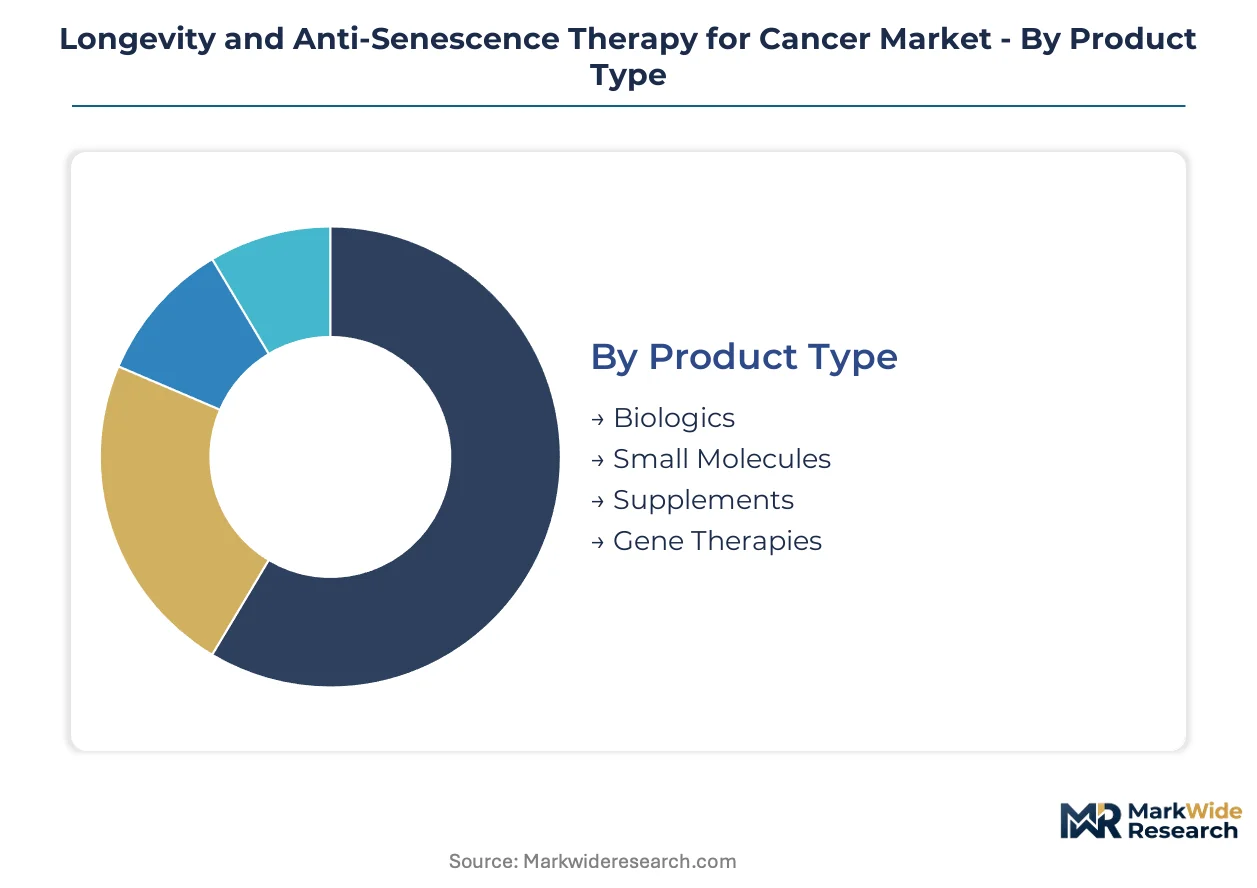
Senescence-targeting interventions fragment across manufacturing complexity tiers and clinical development maturity. Each dimension reveals distinct margin structures, regulatory pathways, and site-of-care requirements that reshape competitive positioning.
Product Type:
Biologics and gene therapies command the deepest margin pools due to sterile manufacturing requirements and patent-protected moats, while small molecules compete on scalability and oral delivery economics.
- Biologics:Protein-based therapeutics targeting p16-positive cells require cold-chain distribution and GMP-certified sterile production. Demand concentrates in oncology clinics across Germany and the United States, where university hospitals anchor early-phase senolytic protocols and absorb premium pricing for p16-targeted clearance mechanisms.
- Gene Therapies:Viral vector and non-viral delivery systems for cellular reprogramming attract the steepest R&D investment intensity. Manufacturing complexity limits production to Massachusetts and California CDMO clusters, creating geographic supply concentration that filters smaller entrants from commercial-scale participation.
- Small Molecules:Oral senolytic compounds compete on manufacturing scalability and distribution simplicity.
- Supplements:Nutraceutical formulations targeting SASP modulation occupy the lowest regulatory tier with compressed margins.
The dominant share belongs to Biologics, while Gene Therapies is closing the gap fastest.
Technology:
Clinical translation velocity varies sharply across mechanism classes, with programmable platforms outpacing legacy approaches in trial initiation rates.
- CRISPR:Gene editing platforms enable programmable targeting of senescence-associated secretory phenotype regulators beyond small-molecule constraints. Preclinical portfolios at Altos Labs and academic medical centers prioritize these candidates for combination with checkpoint inhibitors, compressing development timelines for p53-independent clearance mechanisms.
- Immune Modulation:Natural killer cell-engaging senolytics displace apoptosis-inducing compounds in oncology biotech pipelines. Multi-specific formats raise manufacturing complexity while offering differentiated clearance kinetics that complement existing immuno-oncology protocols.
- RNA Interference:siRNA and mRNA approaches target transient senescence marker suppression with reduced off-target liability.
- Telomere Extension:Telomerase activation remains stalled by oncogenic transformation concerns, constraining pipeline diversification and keeping clinical translation in preclinical phases.
CRISPR platforms attract the most aggressive laboratory investment, though Immune Modulation candidates are advancing through regulatory review most rapidly.
Delivery Mode:
Route selection directly determines site-of-care economics and patient compliance profiles across trial and commercial settings.
- Intravenous:Infusion-based delivery dominates biologic senolytic administration, requiring hospital-based administration suites and specialized nursing staff. Site activation concentrates in Boston and San Francisco academic medical centers, where institutions negotiate preferred CDMO partnerships and lock multi-year capacity reservations ahead of pivotal studies.
- Subcutaneous:Self-administered injection formats reduce site-of-care burden while maintaining bioavailability for protein therapeutics. This modality is expanding fastest among outpatient oncology clinics seeking to decentralize trial participation.
- Oral:Small-molecule senolytics enable community pharmacy distribution and home administration.
- Transdermal:Patch-based delivery remains exploratory for continuous low-dose senescence modulation.
Intravenous administration retains the largest current share, while Subcutaneous formats are gaining adoption fastest among outpatient-focused developers.
End User:
Procurement authority and trial sponsorship models diverge sharply across institutional categories, reshaping vendor relationship structures.
- Research Institutions:Academic medical centers in the United States and Germany are emerging as preferred trial sponsors, bypassing traditional pharmaceutical channel structures for patient recruitment. These institutions consolidate vendor relationships for senescence-targeting trials, favoring integrated service providers over fragmented supplier networks.
- Hospitals:University hospital procurement committees negotiate preferred partnerships with CDMOs offering end-to-end ATMP manufacturing. HIPAA-compliant data integration requirements for real-world evidence collection impose costly infrastructure upgrades at sites running experimental protocols.
- Clinics:Community oncology practices concentrate demand for outpatient-compatible delivery formats.
- Pharmaceutical Companies:Sponsors front-load manufacturing investments before pivotal trial readouts under FDA accelerated approval frameworks.
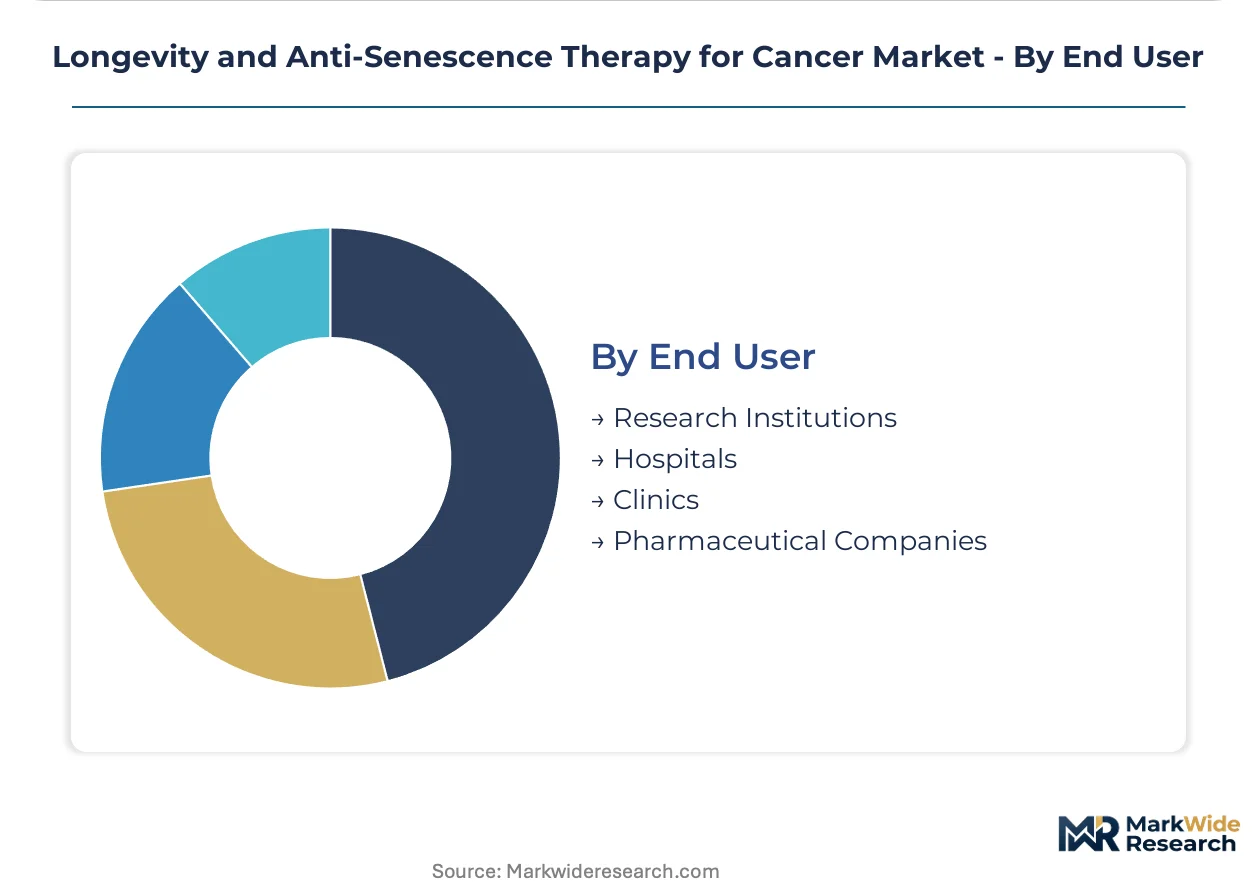
Research Institutions anchor the largest share of early-phase trial activity, while Hospitals are consolidating procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and Japan's PMDA conditional framework are compressing clinical timelines, while EMA ATMP classifications in Europe and state-level biotech incentives in the United States reshape capital deployment geography.
United States
Oncology clinics across Massachusetts and California anchor early-phase senolytic trials, with hospital procurement committees consolidating vendor relationships for ATMP manufacturing. FDA accelerated approval frameworks for oncology biologics front-load manufacturing investments before pivotal readouts. Boston and San Francisco academic medical centers negotiate preferred CDMO partnerships and lock multi-year capacity reservations ahead of pivotal studies.
Germany
University hospitals in Munich and Heidelberg concentrate demand for p16-targeted clearance protocols, creating Europe's densest early-phase trial geography. EMA ATMP classification streamlines market access for cellular reprogramming candidates, reducing regulatory uncertainty for developers. The Heidelberg-Mannheim biotech corridor houses contract development organizations with cell therapy expertise that serve pan-European sponsors.
Japan
PMDA's conditional approval pathway for regenerative medicine attracts laboratory investment from foreign developers seeking accelerated timelines. Tokyo and Osaka academic medical centers pioneer cellular reprogramming trials under this framework. METI funding programs for longevity biotechnology concentrate R&D tax incentives in the Kanto region.
Switzerland
Swissmedic's adaptive licensing approaches for advanced therapies accommodate mechanism-based endpoints that diverge from traditional tumor response metrics. Basel and Zurich host precision medicine clusters where pharmaceutical sponsors co-locate with specialized manufacturing infrastructure. The country's bilateral recognition agreements with EMA reduce duplicate regulatory filings for ATMP sponsors.
United Kingdom
The Medicines and Healthcare products Regulatory Agency's Innovative Licensing and Access Pathway compresses timelines for senescence-targeting candidates with promising early data. London and Cambridge academic medical centers bypass traditional pharmaceutical channel structures for patient recruitment. MHRA post-Brexit regulatory autonomy allows faster adoption of FDA-parallel trial designs.
Longevity and Anti-Senescence Therapy for Cancer Market Competitive Landscape
Player mix skews toward Alphabet-backed R&D platforms and venture-funded cellular reprogramming specialists, with structure consolidating around three archetypes: deep-pocketed longevity research divisions, mid-stage senolytic biotechs, and AI-driven drug discovery platforms. Competitive moves concentrate on captive manufacturing capacity acquisition and academic medical center partnership lock-ups.
Within the platform-technology tier, Unity Biotechnology and Altos Labs exemplify divergent strategic postures—Unity anchors p16-positive cell clearance approaches while Altos dominates cellular reprogramming with significant laboratory investment. Calico Life Sciences represents the corporate-venture archetype, sustaining R&D intensity through its Alphabet-backed structure without near-term revenue pressure. These three entities collectively illustrate how capital structure determines clinical development velocity in senescence-targeting therapeutics.
| Leading Market Players |
|---|
| Unity Biotechnology |
| Calico Life Sciences |
| Altos Labs |
| Life Biosciences |
| Insilico Medicine |
| AgeX Therapeutics |
| Rubedo Life Sciences |
| Retro Biosciences |
| Oisin Biotechnologies |
| Others |
Supply & Pricing Matrix
Cellular reprogramming platforms displacing legacy senolytic small molecules simultaneously concentrate manufacturing in Massachusetts and California CDMO clusters while compressing margins for oral-delivery compounds unable to command GMP-certified sterile production premiums.
Pricing Analysis
Certification level (FDA-grade GMP for ATMPs versus research-grade) creates the primary spread between commercial-scale biologics and preclinical materials. Three-tier pricing structure across GMP-certified, GLP-compliant, and research-grade tiers reflects sterile manufacturing complexity and cold-chain distribution requirements. Cost compression in small-molecule senolytics intensifies because oral formulations face commoditization from nutraceutical substitutes. Hospital procurement committees exhibit lowest price sensitivity for p16-targeted clearance protocols, while community oncology practices demand outpatient-compatible pricing.
Supply Chain Analysis
Massachusetts and California CDMO concentration with cell therapy expertise underwrites supply security for viral vector manufacturing while creating geographic vulnerability for European sponsors. Viral vector production, synthetic mRNA intermediates, and CRISPR guide RNA synthesis feed from specialized facilities with limited second-source alternatives. Single-source vulnerability runs through captive chemistry capabilities at integrated sponsors. Distribution runs through cold-chain logistics networks anchored in Boston and San Francisco academic medical center partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA accelerated approval and EMA ATMP classification erects defensive moats around incumbent sponsors with established manufacturing footprints and locked CDMO capacity.
For Market Incumbents: Compound manufacturing scale advantages by securing multi-year GMP-certified capacity reservations ahead of pivotal trial readouts, while investing in proprietary senescence biomarker platforms to differentiate from emerging CRISPR-senolytic convergence threats. Backward integration into viral vector production insulates against Massachusetts and California CDMO concentration risk. For New Entrants and Emerging Players: Service-layer gaps in HIPAA-compliant real-world evidence collection for senescence biomarker validation present white-space entry points where hospital infrastructure constraints filter established sponsors. Target Japan's PMDA conditional approval pathway for accelerated cellular reprogramming timelines. Partner with academic medical centers as preferred trial sponsors to bypass traditional pharmaceutical channel structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-funded cellular reprogramming specialists approaching clinical proof-of-concept inflection. Five-to-ten year viability hinges on successful translation from preclinical senescence clearance to registrational endpoints. Watch for FDA breakthrough therapy designation signals as acquisition timing indicators.| Strategic Initiative | Industry Significance |
|---|---|
| ATMP Manufacturing Scale-Up | GMP-certified sterile production capacity in Massachusetts and California anchors commercial viability for senescence-targeting biologics. |
| Regulatory Approval Pathway | FDA accelerated oncology framework compresses development timelines while front-loading manufacturing investment requirements. |
| Academic Medical Center Partnership | Hospital procurement committee lock-ups in Boston and San Francisco secure patient recruitment channels for early-phase senolytic trials. |
| Pipeline Diversification | CRISPR-senolytic convergence platforms expand programmable clearance mechanisms beyond small-molecule constraints. |
| Licensing Agreement | Technology access from Alphabet-backed R&D platforms accelerates cellular reprogramming candidate advancement. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration across primary interview rounds and secondary validation. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases supplied external benchmarks. Bottom-up treatment-line modeling and top-down regional regulatory cluster analysis enabled triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology platform, delivery mode, and end-user segmentation dimensions. CAGRs derived from modeled adoption curves for senescence-targeting interventions incorporated biomarker validation timelines and site activation rates as industry-specific forecast inputs throughout the projection horizon.
Underlying assumptions cover regulatory pathway stability and CDMO capacity expansion trajectories, with deviation risk concentrated in telomere extension safety signals and CRISPR off-target liability findings. Practitioners should keep alternative scenarios live as FDA and EMA guidance on longevity mechanism endpoints evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Mesotherapy Guns Market