
 Asia Pacific Platelet Rich Plasma Market | 2026-2036
Asia Pacific Platelet Rich Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Platelet Rich Plasma Market Analysis
Modular PRP kit configurations is pivoting buyer choice across the Asia Pacific market, shifting procurement from standalone centrifuge systems toward bundled preparation-concentration-application sets. Arthrex, Inc. leverages its orthopedic channel density to anchor kit placement in Japanese sports medicine clinics. Stryker competes through surgical system integration, while Zimmer Biomet sustains differentiation via orthobiologics specialization and regional distributor partnerships.
Platelet rich plasma comprises autologous blood-derived concentrate with platelet counts typically exceeding baseline whole blood levels, prepared through density-gradient centrifugation or filtration for localized growth factor delivery in tissue repair and regeneration. Autologous PRP dominates current clinical volume due to safety profile and regulatory familiarity, though PRP kits represent the fastest-expanding product category as point-of-care preparation standardizes. Orthopedics anchors application demand through sports injury protocols, while hair restoration segments capture accelerating aesthetic clinic investment across South Korea and Thailand.
Australia's TGA, Japan's PMDA, and South Korea's MFDS each enforce distinct autologous blood product processing standards that shape kit validation requirements and clinic compliance costs. REACH-aligned substance safety protocols in imported European devices add secondary certification layers for manufacturers distributing across multiple Asia Pacific jurisdictions. Stakeholders must monitor divergent national biologics classifications that determine whether PRP falls under blood product, medical device, or tissue engineering regulatory pathways.
Market Dynamics
Japan's PMDA and Australia's TGA have tightened autologous blood product processing standards, forcing kit manufacturers to accelerate validation timelines and clinic procurement teams to reassess supplier compliance portfolios across the region.
Growth Catalysts
- Aging demographics:Japan, South Korea, and Australia face expanding elderly populations with joint degeneration and tendon injuries, driving orthopedic clinic investment in PRP protocols for cartilage repair and osteoarthritis management.
- TGA kit standardization mandates:Australia's Therapeutic Goods Administration now requires documented platelet concentration thresholds and sterility validation for point-of-care preparation systems, pushing clinics toward bundled kit purchases over in-house centrifuge setups.
- Aesthetic clinic expansion:Private dermatology and hair restoration chains across Thailand and South Korea are deploying PRP for androgenetic alopecia treatments, creating secondary demand channels beyond traditional orthopedic applications.
Market Restraints
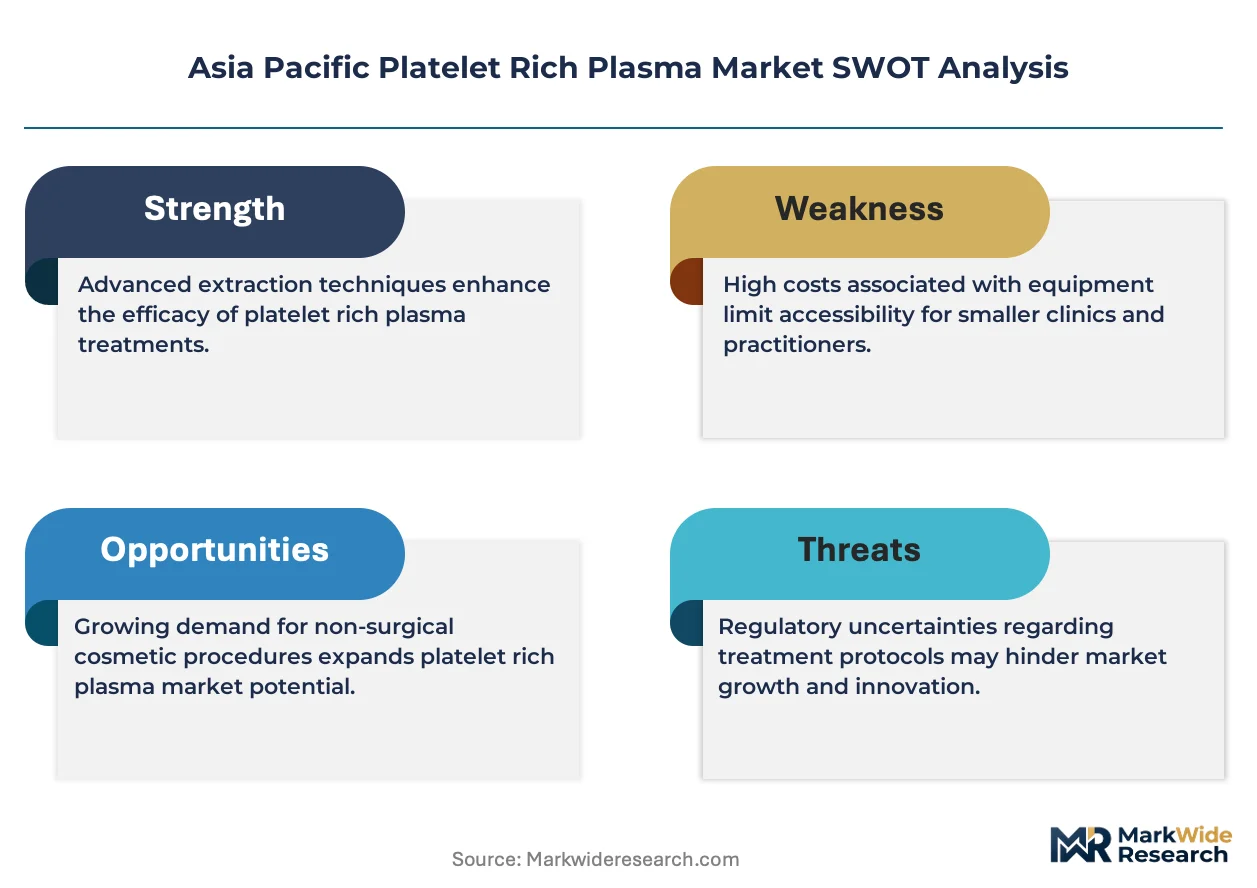
- Plasma separator membrane cost volatility:Specialized filtration membranes used in closed-system PRP kits depend on medical-grade polymer supply chains concentrated in Germany and Japan, exposing manufacturers to input price swings and extended lead times.
- MFDS biologics classification uncertainty:South Korea's Ministry of Food and Drug Safety maintains ambiguous jurisdiction between medical device and tissue engineering pathways for leukocyte-rich PRP formulations, delaying product registrations and clinic reimbursement negotiations.
- Hyaluronic acid injection substitution:Viscosupplementation therapies for knee osteoarthritis remain cheaper and more widely reimbursed across Australian public health systems, limiting PRP penetration in price-sensitive patient segments.
Strategic Opportunities
- Vietnam and Indonesia clinic networks:Underpenetrated aesthetic medicine markets in Southeast Asia present whitespace for PRP kit distributors to establish training partnerships with dermatology chains before regulatory frameworks mature.
- MFDS fast-track designation:South Korea's accelerated review pathway for regenerative medicine products offers manufacturers a 180-day timeline compression for orthobiologic indications, rewarding early dossier preparation.
- Digital centrifuge integration:Convergence of automated cell separation hardware with cloud-based platelet concentration logging is enabling remote compliance auditing and predictive maintenance contracts for high-volume clinic chains.
Industry Challenges
- Cell biology technician scarcity:Clinical preparation of consistent PRP concentrates requires trained laboratory staff familiar with density-gradient protocols, a skill set concentrated in tertiary hospital systems and scarce in outpatient clinic settings.
- PMDA QMS certification timelines:Japan's Pharmaceutical and Medical Devices Agency enforces rigorous quality management system audits for foreign manufacturers, extending market entry cycles by 14-18 months for kit suppliers without prior JIS certification experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Platelet Rich Plasma Market |
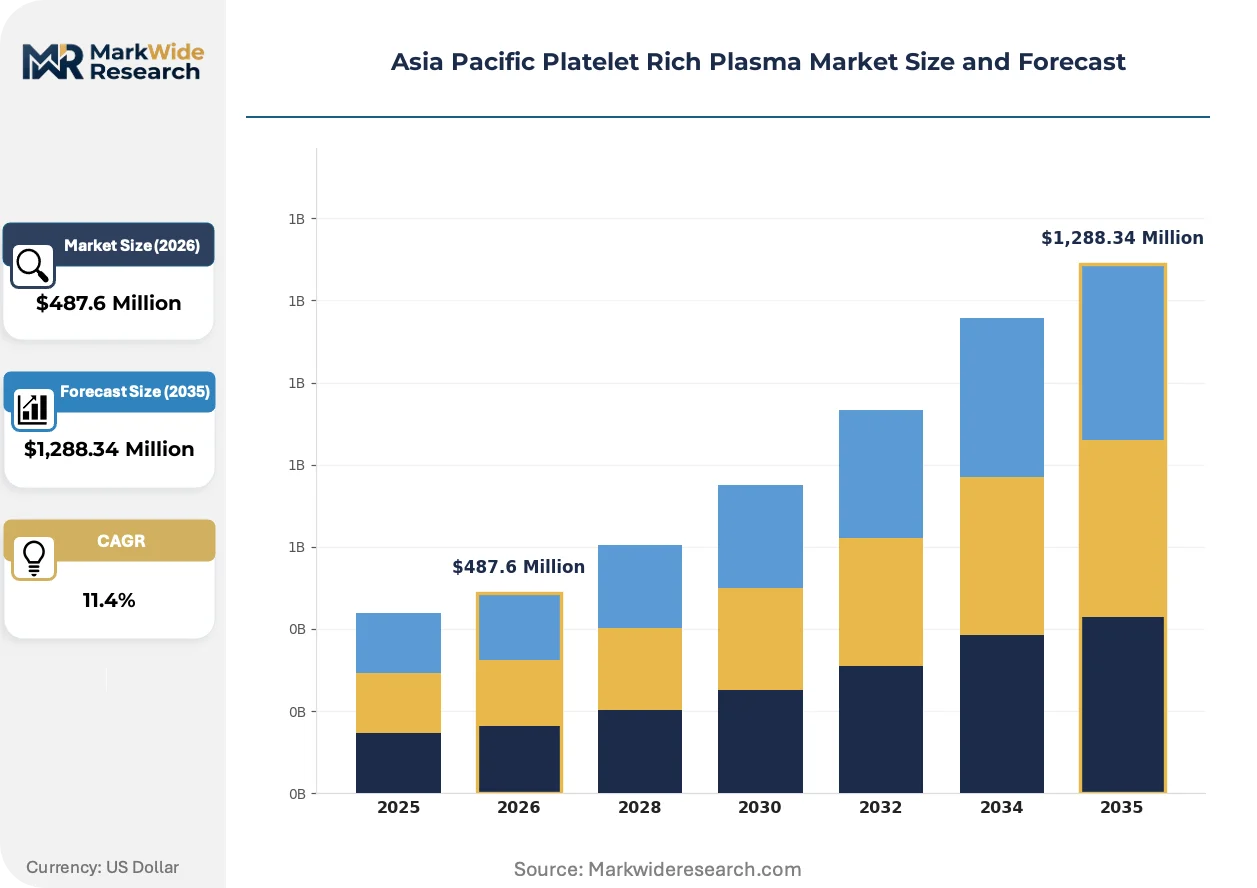
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous, Allogenic, PRP Kits, PRP Concentrate End User: Clinics, Hospitals, Research Laboratories, Aesthetic Centers Application: Orthopedics, Dermatology, Dentistry, Hair Restoration Technology: Centrifugation, Filtration, Microfluidics, Others |
| Companies Covered | Arthrex, Inc., Stryker, Zimmer Biomet, Terumo BCT, EmCyte Corporation, Dr. PRP America LLC, DePuy Synthes, Regen Lab SA, Terumo Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Platelet Rich Plasma Market Emerging Trajectories
Automated preparation systems and real-time platelet analytics are compressing the gap between blood draw and therapeutic application, reshaping clinic workflow economics and supplier value propositions across the Asia Pacific region.
Double-spin centrifugation protocols with programmable cell separation interfaces are electrifying orthopedic clinic adoption in Japan and Australia. Sports medicine centers in Tokyo and Sydney are replacing manual benchtop centrifuges with closed-system automated devices that standardize platelet concentration outputs. This technology is electrifying competitive differentiation among kit suppliers, forcing legacy equipment manufacturers to bundle software analytics or lose placement to integrated platform vendors.
Australia's TGA implemented mandatory adverse event reporting for autologous blood product processing systems in 2023, requiring clinics to document platelet yield variability and contamination incidents. The regulation has triggered wholesale procurement reviews among Australian private hospital chains, with many suspending non-validated kit suppliers until batch traceability systems are demonstrated. Orthopedic surgery units face the steepest compliance burden, as their higher patient volumes multiply documentation requirements.
Japanese aesthetic clinic chains are consolidating purchasing authority through centralized procurement consortia, displacing fragmented individual clinic buying. These consortia negotiate master service agreements with kit manufacturers that bundle training, maintenance, and consumable replenishment. The behavioral shift is most visible in Tokyo and Osaka, where dermatology network headquarters now mandate specific preparation system brands across all affiliated facilities, compressing vendor diversity from twelve suppliers to four dominant platforms.
Asia Pacific Platelet Rich Plasma Market Segmentation
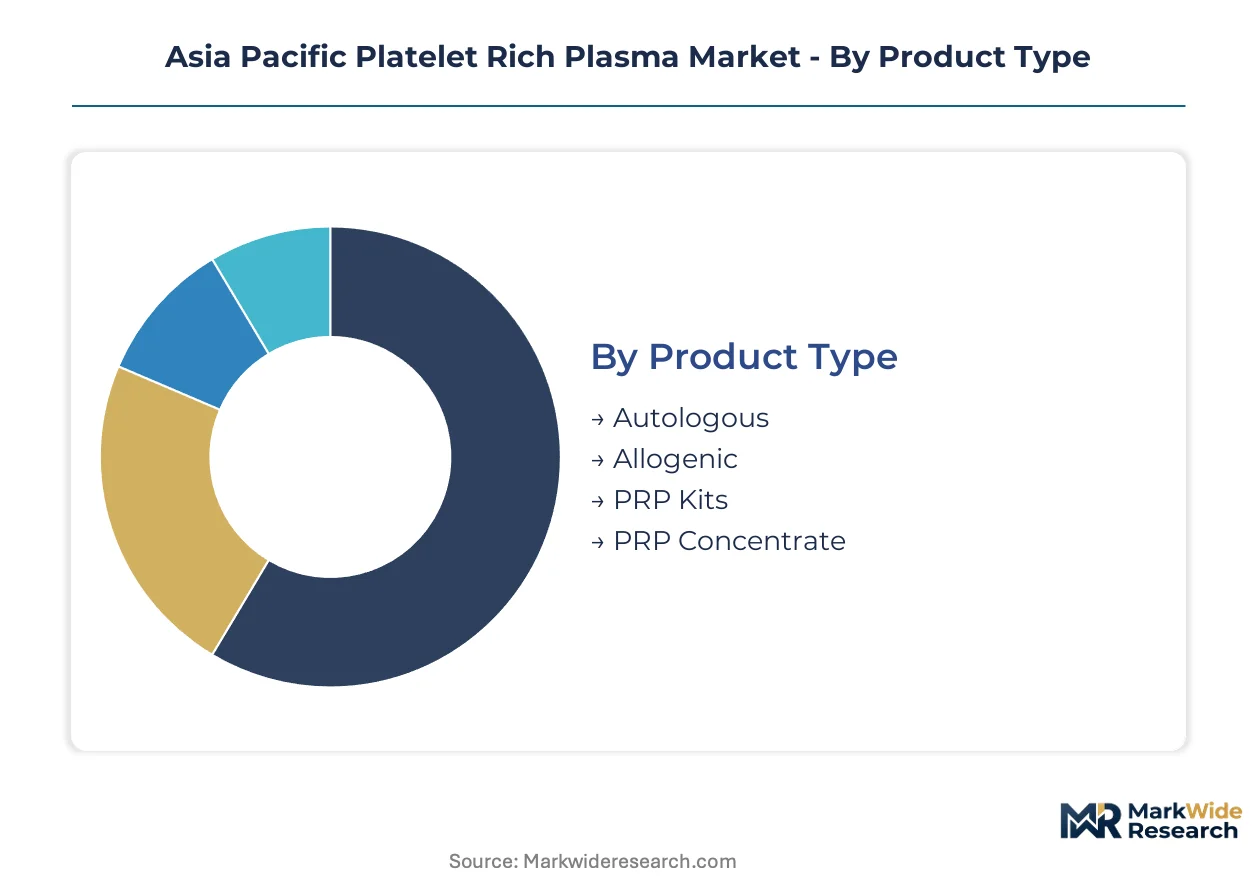
PRP market segmentation reveals how preparation technology, clinical setting, and therapeutic application intersect to determine procurement patterns. Suppliers must align kit configurations with specific workflow requirements across orthopedic, aesthetic, and research channels.
Product Type:
Supply concentration in membrane filtration polymers and centrifuge component manufacturing shapes product economics and kit standardization trajectories across the region.
- Autologous:Patient-derived concentrate prepared through density-gradient separation eliminates immunogenicity concerns. Japanese orthopedic clinics and Australian sports medicine centers anchor procurement volume, driven by PMDA and TGA familiarity with autologous blood product frameworks.
- PRP Kits:Bundled preparation-concentration-application systems standardize point-of-care workflows. South Korean aesthetic clinic chains and Thai dermatology networks are consolidating procurement around validated kit platforms, displacing in-house centrifuge setups.
- Allogenic:Donor-derived platelet concentrates from blood bank inventories. Supply depends on regional blood collection infrastructure concentration.
- PRP Concentrate:Pre-formulated therapeutic suspensions for immediate application. Demand concentrates in hospital systems with centralized pharmacy compounding capabilities.
Today's leader: Autologous. Tomorrow's challenger: PRP Kits.
End User:
Customer type determines purchasing authority structure, with centralized procurement consortia displacing fragmented individual clinic buying across mature markets.
- Clinics:Outpatient orthopedic and aesthetic facilities represent the primary volume channel. Tokyo and Osaka dermatology network headquarters now mandate specific preparation system brands across all affiliated facilities.
- Aesthetic Centers:Specialized hair restoration and facial rejuvenation clinics deploy PRP for androgenetic alopecia and skin regeneration. Bangkok and Seoul chains are expanding treatment room capacity fastest.
- Hospitals:Tertiary care systems with integrated laboratory infrastructure. Australian private hospital chains suspended non-validated kit suppliers following TGA adverse event reporting mandates.
- Research Laboratories:Academic and commercial facilities investigating platelet biology and tissue engineering applications. Activity concentrates in Japan and South Korea regenerative medicine clusters.
Procurement authority is concentrating fastest in aesthetic center chains, while hospital systems impose the steepest compliance documentation burdens.
Application:
Volume distribution across therapeutic areas reflects demographic drivers and reimbursement positioning within national health systems.
- Orthopedics:Sports injury protocols and osteoarthritis management dominate current clinical utilization. Australian orthopedic surgery units face multiplied documentation requirements under TGA batch traceability systems.
- Hair Restoration:Androgenetic alopecia treatments capture accelerating aesthetic clinic investment. South Korean and Thai private dermatology chains are deploying dedicated PRP treatment rooms.
- Dermatology:Facial rejuvenation and scar revision applications leverage platelet-derived growth factor properties. Demand clusters in urban aesthetic medicine markets.
- Dentistry:Alveolar bone regeneration and implant site preparation represent emerging applications. Adoption concentrates in specialized oral surgery practices.
Orthopedics commands current procurement volume. Hair restoration applications are climbing the fastest across Southeast Asian aesthetic markets.
Technology:
Preparation methodology determines platelet concentration consistency, processing time, and regulatory classification complexity for kit manufacturers.
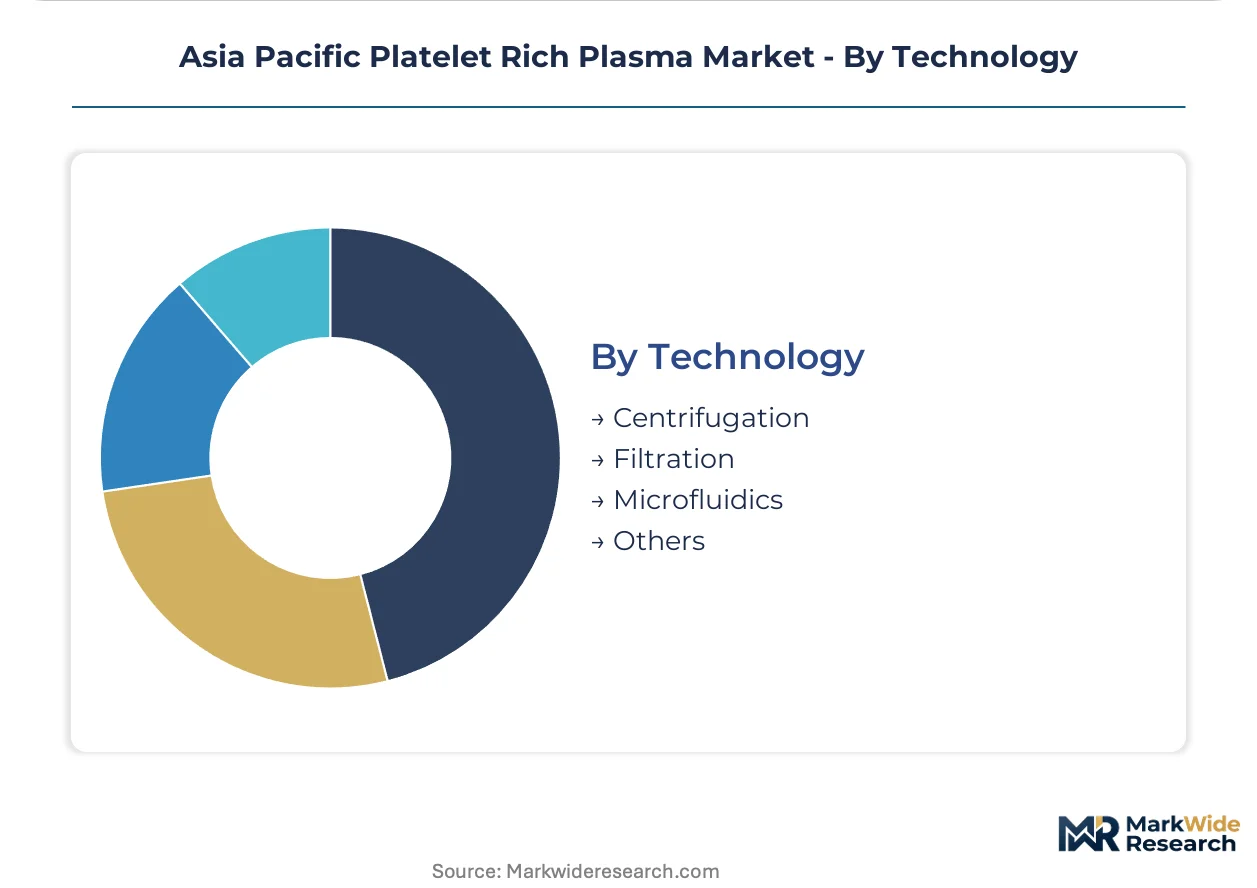
- Centrifugation:Density-gradient separation remains the dominant preparation approach. Double-spin protocols with programmable interfaces are electrifying adoption in Japanese sports medicine centers.
- Filtration:Closed-system membrane separation reduces contamination risk. Supply chain concentration in German and Japanese medical-grade polymer sources creates input cost volatility.
- Microfluidics:Emerging precision cell separation technology enabling real-time platelet analytics. Development activity concentrates in South Korea and Japan device innovation clusters.
- Others:Manual preparation methods and hybrid protocols in limited continued use. Declining share as automated systems standardize.
Centrifugation platforms anchor current installed base. Microfluidics systems are gaining share fastest among premium clinic segments seeking workflow differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PRP therapy originated in European sports medicine protocols before migrating to Asia Pacific orthopedic centers during the 2000s. Japan and South Korea pioneered aesthetic applications, establishing the region's dual-track clinical development. Today, regulatory divergence across national health systems shapes procurement patterns and kit standardization trajectories.
Japan
Sports medicine clinics in Tokyo and Osaka drive orthopedic PRP volume, while aging demographics accelerate osteoarthritis treatment demand. PMDA enforces rigorous quality management system audits for foreign kit manufacturers, extending market entry cycles by 14-18 months. The Kanto region hosts the densest concentration of validated preparation system deployments.
South Korea
Seoul's aesthetic clinic chains consolidate purchasing authority through centralized procurement consortia, compressing vendor diversity across affiliated facilities. MFDS maintains ambiguous jurisdiction between medical device and tissue engineering pathways for leukocyte-rich formulations, delaying product registrations. The Seoul Capital Area anchors hair restoration application growth.
Australia
TGA's 2023 adverse event reporting mandate for autologous blood product processing systems triggered wholesale procurement reviews among private hospital chains. Sydney and Melbourne sports medicine centers replace manual centrifuges with automated closed-system devices. TGA now requires documented platelet concentration thresholds for point-of-care preparation systems.
Thailand
Bangkok dermatology networks expand dedicated PRP treatment room capacity for androgenetic alopecia protocols. The country's national pharmaceutical regulator has yet to finalize biologics classification frameworks, creating compliance uncertainty for imported kit suppliers. Private aesthetic medicine chains in Bangkok and Phuket drive regional procurement volume.
Vietnam
Ho Chi Minh City clinic networks present whitespace for kit distributors to establish training partnerships before regulatory frameworks mature. Underpenetrated aesthetic medicine markets attract early-mover distributors bundling preparation systems with physician education. The country's medical device registration pathways remain in development for autologous blood products.
Asia Pacific Platelet Rich Plasma Market Vendor Landscape
The competitive structure tilts toward orthopedic-focused conglomerates with established surgical channel density. Three player archetypes dominate: multinational device manufacturers leveraging system integration, specialized orthobiologics firms sustaining differentiation through distributor partnerships, and regional kit specialists competing on training bundling. M&A activity concentrates on point-of-care preparation technology acquisitions, while geographic expansion through master service agreements with clinic consortia represents the second dominant competitive vector.
Within the multinational tier, Arthrex, Inc., Stryker, and Zimmer Biomet occupy positions shaped by their channel strategies. Arthrex exemplifies orthopedic channel density approaches, anchoring kit placement through sports medicine clinic relationships. Stryker represents surgical system integration archetypes, competing through compatibility with broader operating room platforms. Zimmer Biomet sits within orthobiologics specialization positioning, sustaining differentiation via regional distributor partnerships rather than direct sales infrastructure.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Stryker |
| Zimmer Biomet |
| Terumo BCT |
| EmCyte Corporation |
| Dr. PRP America LLC |
| DePuy Synthes |
| Regen Lab SA |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
Captive membrane manufacturing in Germany and Japan anchors both supply security and pricing power for premium PRP kit suppliers, while outsourced polymer sourcing leaves mid-tier vendors exposed to input cost volatility and extended qualification timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by TGA validation status and bundled training services. Cost compression in economy-tier kits is intensifying because Vietnamese and Indonesian distributors are flooding markets with unvalidated preparation systems. Hospital systems in Australia show least price sensitivity due to adverse event liability exposure, while standalone aesthetic clinics in Thailand represent the most margin-constrained buyer segment.
Supply Chain Analysis
Dual-sourcing requirements from Australian private hospital chains and Japanese orthopedic networks mandate multi-supplier qualification for membrane filtration polymers and centrifuge drive components. Manufacturing concentrates in Germany, Japan, and South Korea, with medical-grade polymer feedstocks drawing from specialized chemical producers in the Rhine-Ruhr region and Osaka Bay industrial clusters. Single-source vulnerability persists for high-precision cell separation membranes, while distribution runs through regional distributor partnerships rather than direct manufacturer-to-clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where South Korea's MFDS fast-track pathway compresses validation costs versus Japan's PMDA audit burden, rewarding manufacturers with prior JIS certification experience.
For Market Incumbents: Hedge regulatory fragmentation by maintaining parallel dossier preparation for both medical device and tissue engineering pathways in Seoul, while accelerating backward integration into membrane polymer production to offset German supply chain volatility. Channel control through master service agreements with Tokyo dermatology consortia represents the critical defensive lever against Stryker's surgical system bundling.
For New Entrants and Emerging Players: The 40-60% price-point gap between Arthrex-validated premium kits and unbranded economy alternatives in Bangkok and Ho Chi Minh City creates immediate whitespace for mid-tier positioning. Target Vietnam's underpenetrated aesthetic clinic networks through training-forward distribution partnerships before the country's national pharmaceutical regulator finalizes biologics classification frameworks.
For Investors and Strategic Acquirers: Roll-up economics work for regional kit specialists with established PMDA or TGA validation dossiers because compliance asset scarcity concentrates acquisition value in pre-qualified platforms rather than manufacturing capacity. Monitor MFDS jurisdiction clarification for leukocyte-rich formulations as the inflection signal determining whether orthobiologic registrations accelerate or stall.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Fast-Track Dossier Preparation | 180-day review compression rewards early orthobiologic indication submissions in Seoul. |
| Backward Integration into Membrane Polymers | In-house medical-grade polymer production insulates against German supply chain volatility. |
| Master Service Agreements with Clinic Consortia | Tokyo and Osaka dermatology networks now mandate specific preparation system brands across affiliates. |
| Digital Centrifuge Platform Development | Cloud-based platelet concentration logging enables remote compliance auditing for TGA mandates. |
| Training Partnerships in Vietnam and Indonesia | Early-mover distributors establish physician education relationships before regulatory frameworks mature. |
Methodological Framework
Multiple input streams — structured interviews with orthopedic surgeons and aesthetic clinic directors, procurement manager surveys at Australian private hospital chains, and regulatory affairs specialist consultations — were reconciled against TGA adverse event databases, PMDA QMS certification records, MFDS registration filings, and customs import data for PRP preparation systems. Bottom-up clinic deployment estimates and top-down manufacturer shipment analysis were triangulated to validate volume assumptions.
Historical adoption curves in Japanese sports medicine and South Korean aesthetic applications were cross-referenced against panel input from distribution channel partners across the analysis window. Segmentation modeling incorporated product type, end-user purchasing authority structure, application volume distribution, and preparation technology adoption patterns. CAGRs were derived from fitted growth curves calibrated to documented clinic procurement cycles and regulatory approval timelines, with orthobiologic indication expansion and aesthetic clinic network consolidation treated as primary demand drivers.
Caveats apply where MFDS biologics reclassification, PMDA audit timeline extensions, or membrane polymer supply disruptions could materially shift the outlook. Deviation in TGA enforcement intensity for point-of-care preparation validation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Hyper Personalized Medicine Market