
 Regenerative Artificial Skin Market | 2026-2036
Regenerative Artificial Skin Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Artificial Skin Market Outlook
Burn treatment is consolidating share within hospital procurement budgets as chronic wound prevalence rises among diabetic and aging populations. Integra LifeSciences Corporation leverages its dermal regeneration portfolio across acute and outpatient settings. Johnson & Johnson Services, Inc. anchors its position through extensive surgical channel relationships. Smith & Nephew competes with advanced wound care portfolios that integrate biologic and synthetic skin layers.
Regenerative artificial skin comprises engineered biomaterial scaffolds seeded with autologous or allogeneic cells, designed to replicate epidermal barrier function and dermal collagen architecture at thicknesses between 0.5 and 3.0 millimeters. Its primary purpose is to close full-thickness wounds where native skin graft donor sites are insufficient or contraindicated. Cell-based products command premium pricing due to manufacturing complexity and personalized processing requirements, while acellular matrices serve cost-sensitive wound care segments with off-the-shelf availability. Skin grafts derived from tissue engineering occupy the fastest-expanding niche as 3D bioprinting advances reduce production timelines.
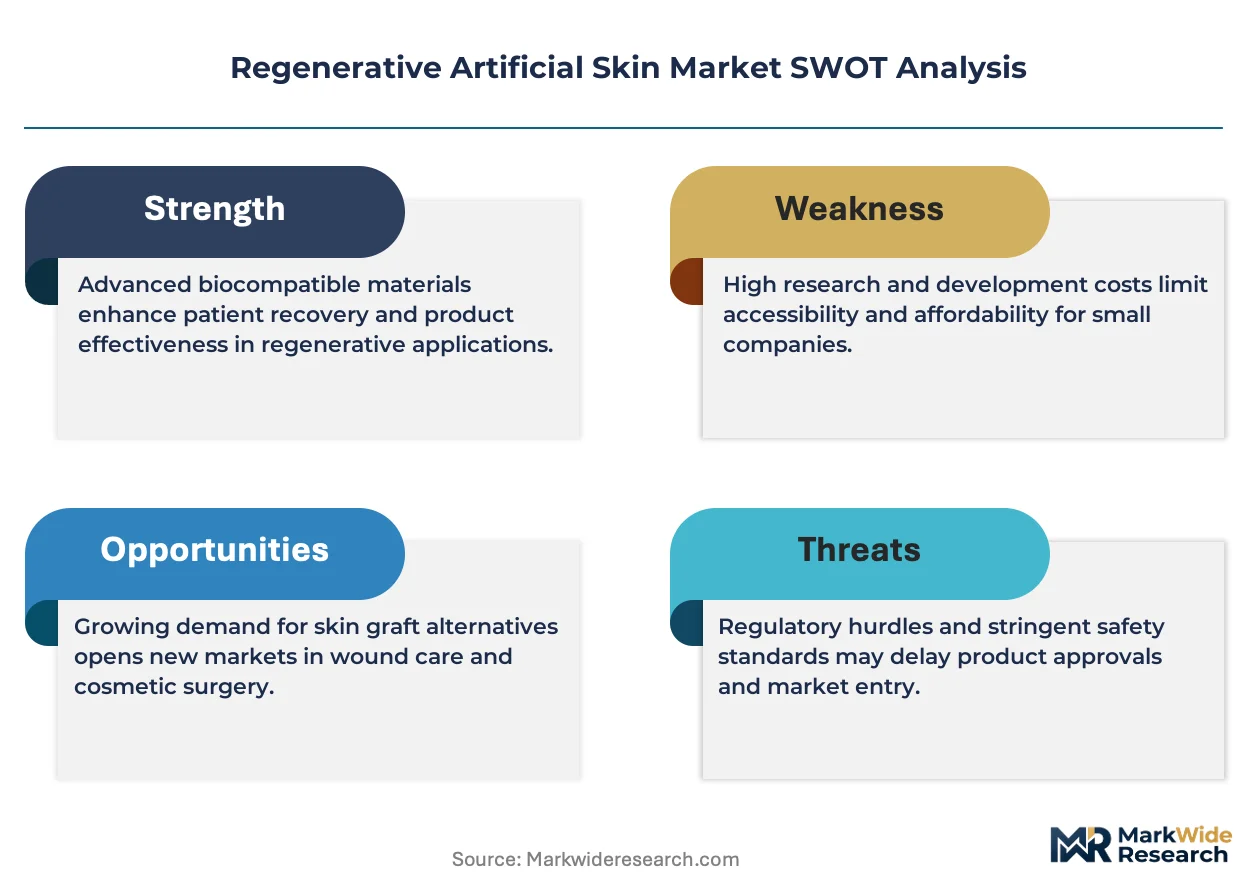
FDA premarket approval and the EU Medical Device Regulation impose stringent biocompatibility and sterility standards that filter smaller entrants from commercial distribution. Health Canada and the UK's Medicines and Healthcare products Regulatory Agency apply comparable clinical evidence thresholds for advanced therapy medicinal products. Stakeholders must monitor evolving reimbursement codes for cell-based therapies across Medicare, national health services, and private payers to anticipate accessible market volume.
Market Dynamics
FDA premarket approval pathways are tightening quality benchmarks for dermal substitute manufacturers, forcing consolidation among cell-based product developers while burn centers accelerate procurement of tissue-engineered grafts.
Growth Catalysts
- Chronic wound epidemiology:Diabetic foot ulcer prevalence among aging populations in Germany, the United States, and Japan is expanding addressable patient pools for bioengineered skin grafts.
- EMA Advanced Therapy Medicinal Products framework:Accelerated assessment pathways in the European Union are compressing time-to-market for allogeneic cell-based dermal substitutes.
- 3D bioprinting maturation:Multi-material deposition systems are reducing production timelines for personalized skin constructs from autologous biopsies.
Market Restraints
- Collagen and hyaluronic acid input volatility:Purified matrix material costs fluctuate with bovine and marine supply chain disruptions, squeezing gross margins on acellular dermal matrices.
- Manufacturing concentration risk:Cell-based product fabrication clusters in Massachusetts, North Carolina, and Bavaria create geographic vulnerability to single-site contamination events.
- Allograft substitution pressure:Cadaveric skin from tissue banks retains cost advantages for full-thickness burn coverage, limiting price elasticity for engineered alternatives.
Strategic Opportunities
- Pediatric congenital anomaly repair:Underpenetrated demand for biocompatible temporary coverage in neonatal intensive care units across France, Italy, and Spain offers first-mover positioning.
- Scar revision aesthetics:Contracting patterns with dermatology clinics for post-surgical dermal regeneration are opening direct-to-physician channels outside hospital procurement.
- Japan's regenerative medicine safety framework:Conditional approval pathways for autologous cellular products are attracting foreign manufacturers to establish local processing partnerships.
Industry Challenges
- Cell culture technician scarcity:GMP-compliant aseptic processing expertise concentrates in Boston, Basel, and Singapore, creating recruitment bottlenecks for new manufacturing facilities.
- Bioreactor capital intensity:Scalable perfusion systems for dermal-epidermal composite production require eight-figure equipment investments with extended depreciation schedules.
- ISO 10993 biological evaluation timelines:Extended cytotoxicity and sensitization testing protocols delay product iterations by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Artificial Skin Market |
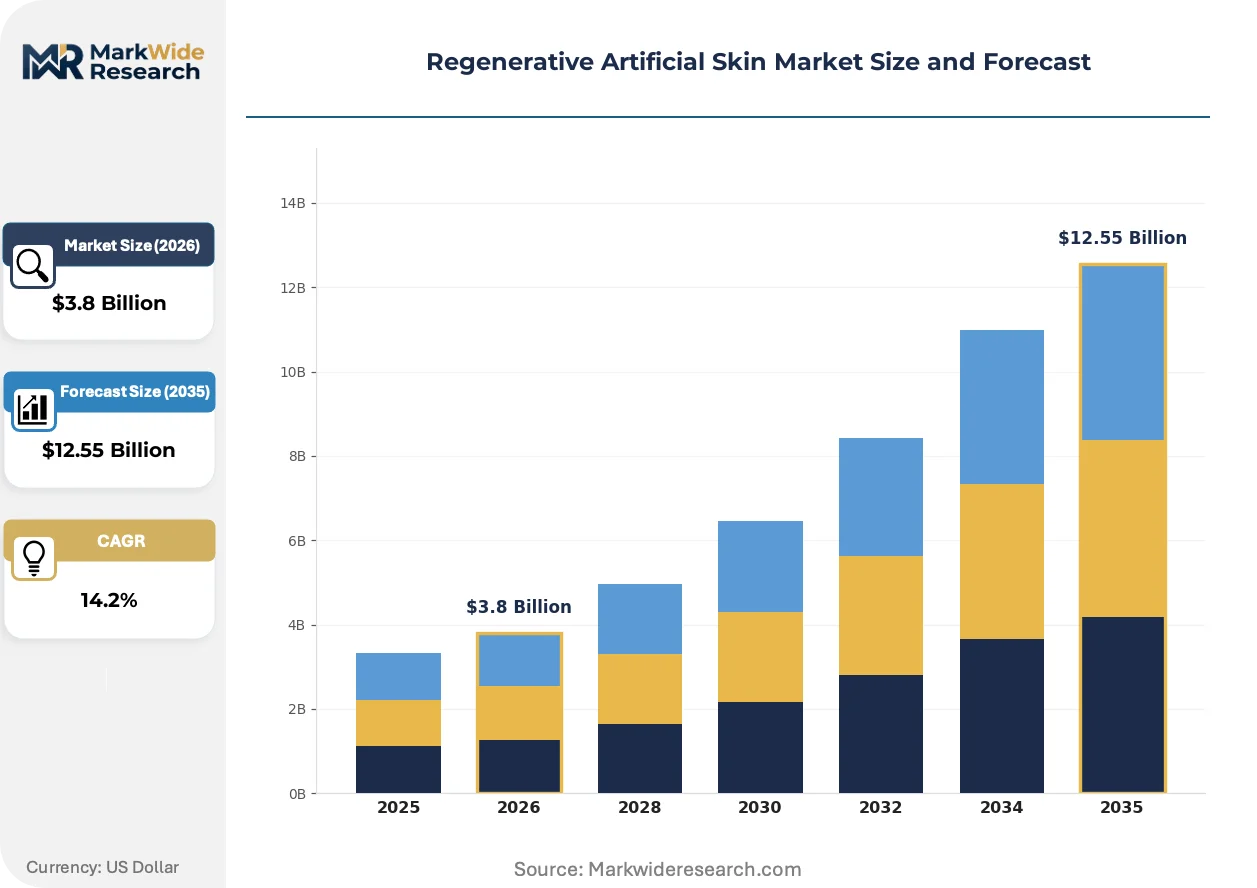
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dermal Substitutes, Skin Grafts, Cell-based Products, Acellular Matrices Application: Burn Treatment, Wound Care, Surgical Applications, Cosmetic Procedures Technology: 3D Bioprinting, Tissue Engineering, Stem Cell Technology, Biomaterials End User: Hospitals, Clinics, Research Institutes, Home Healthcare |
| Companies Covered | Integra LifeSciences Corporation, Johnson & Johnson Services, Inc., Smith & Nephew, Mylan N.V., Mallinckrodt Plc., Organogenesis Holdings Inc., Avita Medical, Medtronic plc, Vericel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Artificial Skin Market Strategic Shifts
Bioprinting platforms are compressing the gap between autologous biopsy and implantable graft, while regulatory convergence across FDA, EMA, and PMDA is standardizing evidence requirements for cell-based therapies.
Multi-material extrusion systems incorporating living keratinocytes and fibroblasts within collagen-fibrin hydrogels are expanding into academic medical center burn units and wound care clinics. Johns Hopkins Medicine and Charité Berlin are deploying these platforms for patient-specific graft production within 21-day windows. This capability is expanding into outpatient settings previously restricted to off-the-shelf acellular matrices.
EU Medical Device Regulation biocompatibility standards are elevating documentation burdens for dermal substitute manufacturers seeking CE marking. Small-to-mid-sized developers face disproportionate compliance costs, triggering partnership strategies with larger wound care portfolios. Cell-based products with novel scaffold materials bear the heaviest clinical evidence obligations.
Hospital value analysis committees are consolidating vendor contracts for advanced wound care, displacing fragmented purchasing across individual surgeons. Integrated delivery networks in Texas, Pennsylvania, and Ohio are negotiating three-year sole-source agreements for biologic skin substitutes. This concentration is most visible in Medicare-dependent regions where bundled payment models compress per-procedure spending.
Regenerative Artificial Skin Market Segmentation
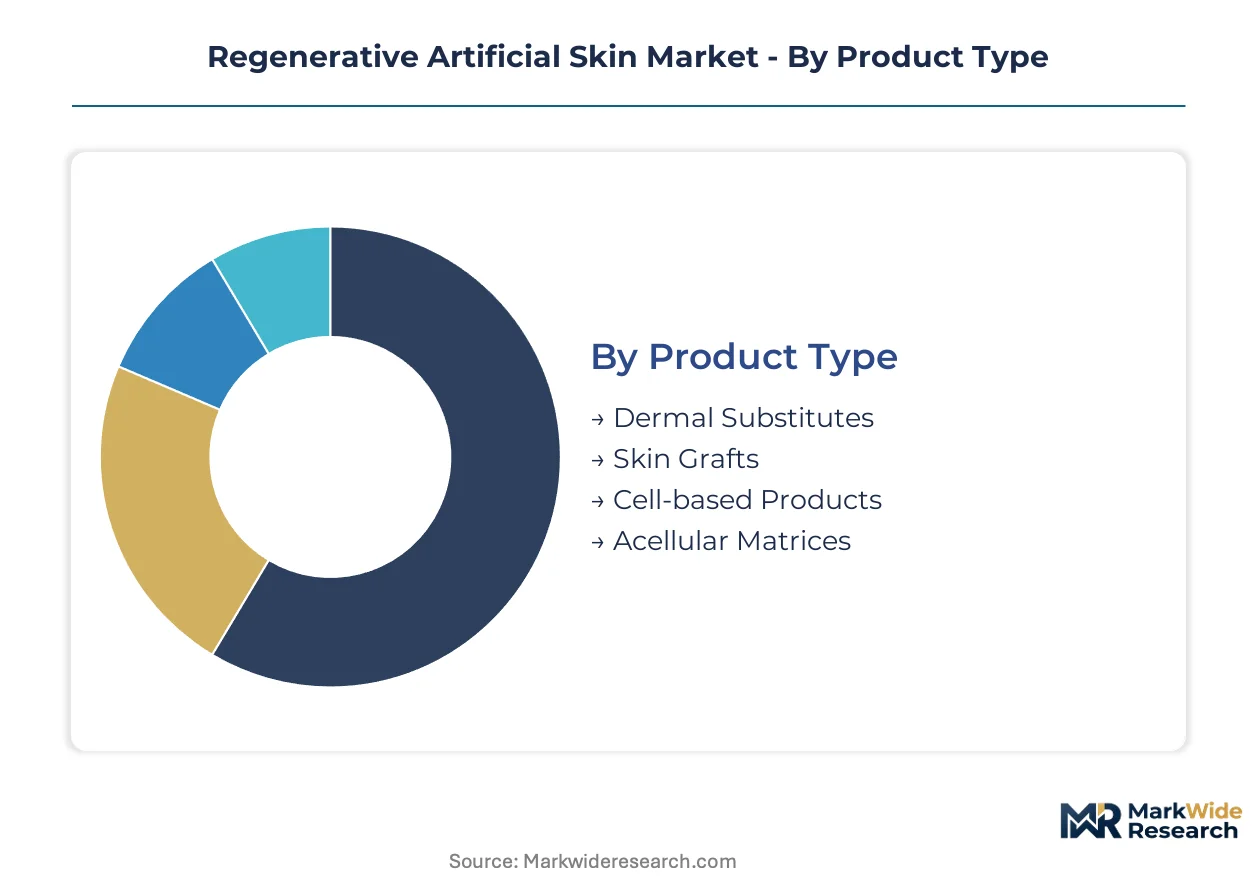
Regenerative artificial skin procurement splits sharply between acute care settings demanding cell-based personalization and outpatient channels prioritizing shelf-stable acellular options. Manufacturing capacity clusters around distinct technology platforms, creating supply-side specialization that shapes competitive positioning across each segment tier.
Product Type:
Production assets for dermal substitutes concentrate in Massachusetts, North Carolina, and Bavaria, where GMP-certified facilities handle both autologous processing and allogeneic master cell banking.
- Cell-based Products:Engineered constructs incorporate living keratinocytes and fibroblasts seeded onto collagen scaffolds, requiring 14-21 day cultivation cycles. Demand concentrates in German university hospitals and US burn centers where chronic wound complexity outstrips cadaveric allograft availability. FDA premarket approval pathways impose 18-24 month clinical evidence timelines that filter smaller developers.
- Dermal Substitutes:Bilayer matrices replicate epidermal barrier function and dermal collagen architecture at 0.5-3.0 millimeter thicknesses. Procurement is accelerating in Texas and Pennsylvania integrated delivery networks where bundled payment models compress per-procedure spending.
- Skin Grafts:Tissue-engineered constructs from autologous biopsies serve full-thickness wound closure where donor sites are insufficient.
- Acellular Matrices:Off-the-shelf collagen and hyaluronic acid scaffolds target cost-sensitive outpatient wound care segments.
Cell-based products absorb the bulk of installed capacity; skin grafts are expanding most quickly as 3D bioprinting compresses production timelines.
Application:
Revenue concentration tilts toward chronic wound management as diabetic foot ulcer prevalence rises among aging populations in Germany, the United States, and Japan.
- Burn Treatment:Full-thickness thermal and chemical injury coverage drives procurement of temporary and permanent dermal substitutes. US burn centers are consolidating vendor contracts under three-year sole-source agreements as Medicare-dependent regions adopt bundled payment models.
- Wound Care:Diabetic foot ulcers and venous leg ulcers constitute the largest addressable patient pool for bioengineered skin grafts. German university hospitals in Berlin and Heidelberg are scaling tissue-engineered programs for chronic wound patients.
- Surgical Applications:Reconstructive procedures utilize dermal substitutes for soft tissue defect repair.
- Cosmetic Procedures:Scar revision and aesthetic dermal regeneration open direct-to-physician channels outside hospital procurement.
Wound care captures the greatest revenue concentration; cosmetic procedures are climbing the fastest as dermatology clinics adopt outpatient biologic protocols.
Technology:
Patent filings and capital deployment cluster around multi-material deposition systems that reduce personalized graft production from months to weeks.
- 3D Bioprinting:Multi-material extrusion systems incorporate living cells within collagen-fibrin hydrogels for patient-specific constructs. Johns Hopkins Medicine and Charité Berlin deploy these platforms for 21-day graft production windows.
- Tissue Engineering:Scaffold-based cultivation of autologous and allogeneic cells dominates current commercial manufacturing.
- Stem Cell Technology:Pluripotent and mesenchymal stem cell sourcing enables off-the-shelf allogeneic products.
- Biomaterials:Purified collagen and hyaluronic acid matrices face input cost volatility from bovine and marine supply chain disruptions.
Tissue engineering retains the dominant installed base; 3D bioprinting is gaining share fastest as academic medical centers expand platform deployment.
End User:
Procurement authority is consolidating within hospital value analysis committees, displacing fragmented purchasing across individual surgeons and wound care nurses.
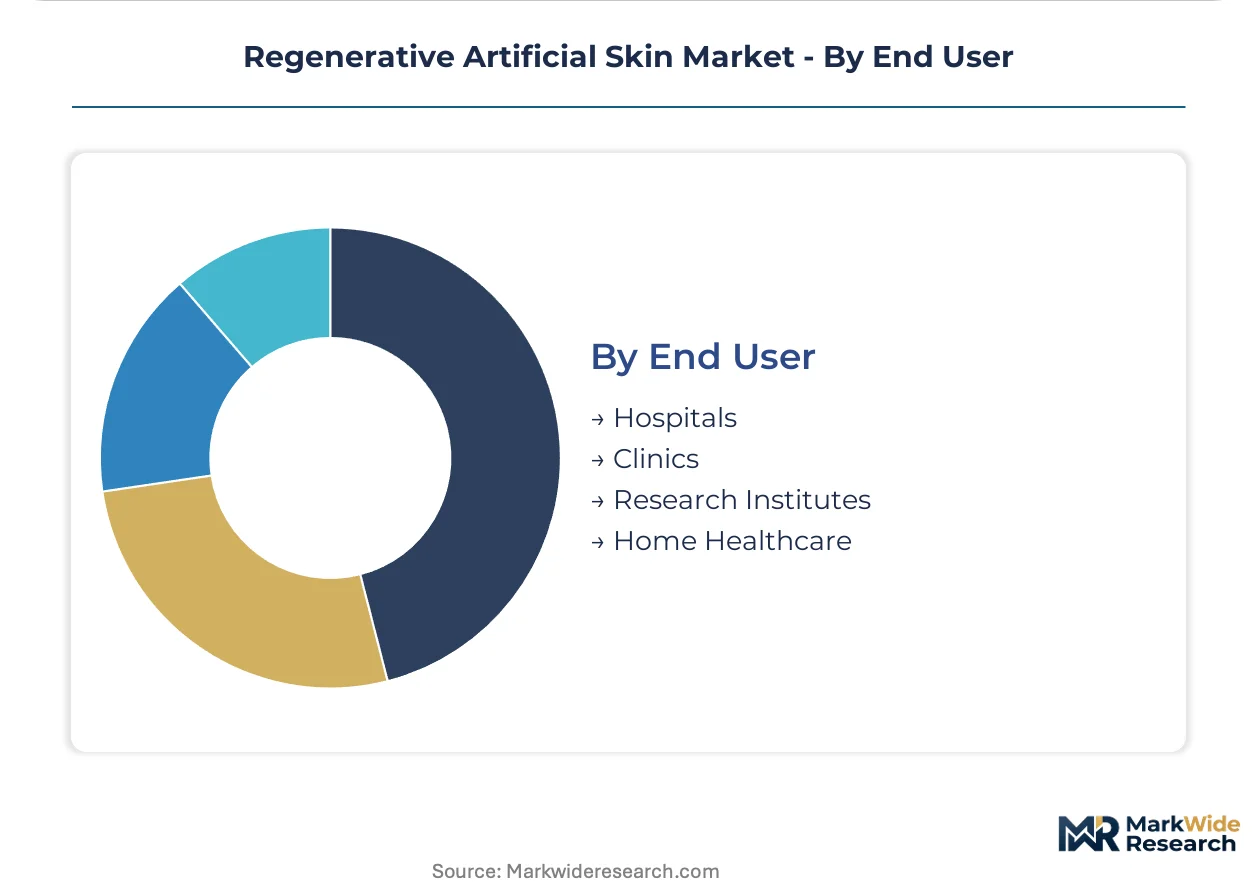
- Hospitals:Acute care settings command premium pricing for cell-based products used in burn units and surgical wards. Integrated delivery networks in Ohio and Pennsylvania negotiate multi-year contracts for biologic skin substitutes.
- Clinics:Outpatient wound care centers drive volume for acellular matrices with off-the-shelf availability.
- Research Institutes:Academic medical centers pilot next-generation bioprinting platforms and novel scaffold materials.
- Home Healthcare:Remote chronic wound management creates emerging demand for simplified dressing systems.
Hospitals absorb the bulk of cell-based product capacity; clinics are expanding most quickly as reimbursement shifts toward outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in Massachusetts, North Carolina, and Bavaria supply cell-based products to burn centers and chronic wound programs worldwide, while consumption concentrates in German university hospitals, US integrated delivery networks, and Japanese academic medical centers.
United States
Burn treatment centers in Texas, Pennsylvania, and Ohio are consolidating procurement under three-year sole-source agreements as Medicare bundled payment models compress per-procedure spending. FDA premarket approval pathways impose 18-24 month clinical evidence timelines that filter smaller developers from commercial distribution. Johns Hopkins Medicine in Baltimore deploys 3D bioprinting platforms for patient-specific graft production within 21-day windows.
Germany
University hospitals in Berlin and Heidelberg are scaling tissue-engineered skin graft programs for diabetic foot ulcer and venous leg ulcer patients among aging populations. EMA Advanced Therapy Medicinal Products framework provides accelerated assessment pathways for allogeneic cell-based dermal substitutes. Charité Berlin operates multi-material extrusion systems incorporating living keratinocytes within collagen-fibrin hydrogels for acute burn coverage.
Japan
Conditional approval pathways under the regenerative medicine safety framework are attracting foreign manufacturers to establish local processing partnerships for autologous cellular products. METI and PMDA coordinate streamlined evidence requirements that compress time-to-market for novel scaffold materials. Tokyo and Osaka academic medical centers pilot next-generation bioprinting platforms for neonatal intensive care applications.
United Kingdom
Medicines and Healthcare products Regulatory Agency applies clinical evidence thresholds for advanced therapy medicinal products comparable to FDA and EMA standards. London and Cambridge research institutes concentrate GMP-compliant aseptic processing expertise for dermal-epidermal composite production. MHRA post-Brexit regulatory autonomy is creating parallel conformity assessment routes for CE-marked dermal substitutes.
Canada
Health Canada enforces biocompatibility and sterility standards for dermal substitute manufacturers that mirror FDA quality benchmarks. Ontario and Quebec hospital value analysis committees are consolidating vendor contracts for advanced wound care, displacing fragmented purchasing across individual surgeons. Canadian burn centers accelerate procurement of cell-based artificial skin products as chronic wound prevalence rises among diabetic populations.
Regenerative Artificial Skin Market Competitive Environment
Top-tier vendors anchor hospital procurement channels and integrated delivery network contracts, while mid-tier specialists compete on bioprinting platform differentiation and regional manufacturing proximity. The competitive terrain splits between diversified medical technology conglomerates with surgical channel relationships and focused regenerative medicine developers with cell-based processing capabilities. Strategic archetypes include scaffold-technology licensors, autologous cell service providers, and acellular matrix commodity producers. Dominant competitive moves encompass multi-year sole-source agreements with IDNs and technology licensing partnerships with academic medical centers.
Within the diversified medical technology tier, Integra LifeSciences Corporation and Johnson & Johnson Services, Inc. occupy positions defined by extensive surgical channel relationships and wound care portfolio breadth. Smith & Nephew represents the advanced wound care integration archetype, competing across biologic and synthetic skin layer combinations. These three entities exemplify how scale-driven procurement consolidation favors vendors with existing hospital value analysis committee access and multi-product contract leverage.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| Johnson & Johnson Services, Inc. |
| Smith & Nephew |
| Mylan N.V. |
| Mallinckrodt Plc. |
| Organogenesis Holdings Inc. |
| Avita Medical |
| Medtronic plc |
| Vericel Corporation |
| Others |
Value Chain & Pricing Dynamics
Purified bovine collagen and marine-derived hyaluronic acid feed through acellular matrix producers in Bavaria and North Carolina before reaching hospital value analysis committees in Texas and Pennsylvania, with input cost volatility from livestock supply disruptions compressing gross margins at the standard tier while cell-based products maintain premium positioning through personalized processing complexity.
Pricing Analysis
Margin tightening in acellular dermal matrices reflects bovine collagen input volatility and marine supply chain disruptions. Three-tier pricing structure across premium cell-based constructs, standard bilayer matrices, and economy acellular scaffolds separates products by cultivation cycle length and sterility certification grade. Cost-down pressure on standard-tier manufacturers accelerates because bundled Medicare payment models compress per-procedure spending in Ohio and Pennsylvania integrated delivery networks. Outpatient wound care clinics exhibit highest price sensitivity, while German university hospitals in Berlin and Heidelberg absorb premium cell-based pricing for chronic wound complexity.
Supply Chain Analysis
Collagen and hyaluronic acid supply rests on Bavarian pharmaceutical-grade processors, Massachusetts biotechnology suppliers, and North Carolina tissue engineering facilities. Raw material dependencies center on certified bovine dermis sourcing, recombinant protein production, and GMP-grade cell culture media. Single-source vulnerability concentrates in Massachusetts and Bavaria master cell banking operations, where contamination events would disrupt autologous processing pipelines. Distribution runs through hospital value analysis committees and integrated delivery network procurement officers, displacing fragmented surgeon-level purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA premarket approval pathways and EU Medical Device Regulation biocompatibility standards erect cost-of-compliance barriers that filter smaller developers, creating defensive moats for manufacturers with established clinical evidence portfolios and GMP-certified production assets.
For Market Incumbents: Cement multi-year sole-source agreements with Texas and Pennsylvania integrated delivery networks before bundled payment models fully mature. Deepen backward integration into bovine collagen purification to buffer input cost volatility threatening standard-tier margins. Prioritize ISO 10993 biological evaluation investment to accelerate product iterations against emerging 3D bioprinting competitors.
For New Entrants and Emerging Players: Enter via Japan's conditional approval pathways for autologous cellular products, where METI and PMDA coordination compresses time-to-market for novel scaffold materials. Target neonatal intensive care units across France, Italy, and Spain for pediatric congenital anomaly repair applications. Pursue dermatology clinic direct-to-physician channels for scar revision aesthetics outside hospital procurement consolidation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier autologous cell service providers in Massachusetts and Bavaria with stranded GMP capacity but thin clinical evidence portfolios. Five-to-ten year viability hinges on successful navigation of FDA premarket approval timelines and EMA Advanced Therapy Medicinal Products framework convergence. Watch for bioreactor equipment depreciation schedule stress as a signal for acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Eighteen-to-twenty-four month clinical evidence timelines filter smaller developers from commercial distribution. |
| CE Marking Pathway | EU Medical Device Regulation biocompatibility standards elevate documentation burdens for dermal substitute manufacturers. |
| Hospital System Partnership | Three-year sole-source agreements with Texas and Pennsylvania integrated delivery networks consolidate procurement authority. |
| Bioreactor Manufacturing Scale-Up | Scalable perfusion systems for dermal-epidermal composite production require eight-figure capital deployment. |
| Reimbursement Strategy | Medicare bundled payment models in Ohio and Pennsylvania compress per-procedure spending for bioengineered skin grafts. |
Study Parameters
Document review covered FDA 510(k) and PMA filings, EMA Advanced Therapy Medicinal Products assessments, hospital procurement databases, and CMS Medicare reimbursement codes, complemented by interviews with burn center procurement directors, GPO contracts managers, biomedical engineers, and cell culture technicians. Secondary validation drew from SEC 10-K disclosures, clinical trial registries, and ISO 10993 biological evaluation protocols. Bottom-up patient volume modeling and top-down market sizing triangulated segment-level demand across the analysis window.
Segment-level value outputs trace to modeled splits across cell-based products, dermal substitutes, skin grafts, and acellular matrices, with application dimensions spanning burn treatment, wound care, surgical reconstruction, and cosmetic procedures. CAGRs derive from patient epidemiology trajectories in diabetic foot ulcer and venous leg ulcer populations, 3D bioprinting platform adoption curves at Johns Hopkins Medicine and Charité Berlin, and reimbursement code expansion timelines for autologous cellular therapies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA regulatory timeline extensions, bovine supply chain disruptions, or accelerated 3D bioprinting platform maturation. Forecasts reflect assumptions regarding EMA and PMDA pathway convergence, Medicare bundled payment geographic expansion, and cell culture technician labor pool elasticity in Boston, Basel, and Singapore. A small set of named triggers—bioreactor contamination events, novel scaffold material clinical failures, and allograft tissue bank pricing aggression—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Atrophic Scar Treatment Market